Global Markets Wrap: Wall Street Rebounds, Fed Decision Looms
2 hrs ago

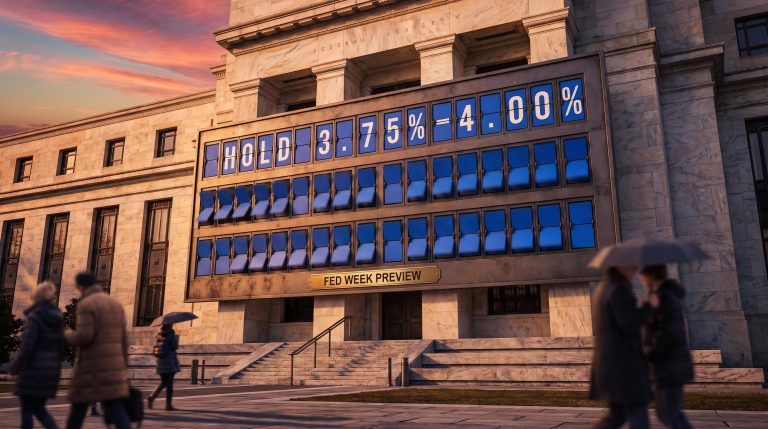





Interest rates represent the price of money and the benchmark against which all financial assets are valued. When central banks raise rates, the discount rate applied to future earnings increases, compressing equity valuations, particularly for growth stocks. Fixed income prices fall as yields rise. When rates fall, the opposite dynamics emerge. The RBA cash rate directly affects Australian mortgage markets, banking sector earnings, and consumer spending. Global rate differentials also influence the Australian dollar and cross-border capital flows. StockWire X tracks central bank meeting outcomes, interest rate market pricing, and the sector-specific investment implications of each phase of the rate cycle.
Interest rates affect housing by changing mortgage repayments and borrowing capacity. When rates rise, buyers can generally borrow less and existing borrowers face higher repayments, which can reduce demand and slow price growth. Higher financing costs can also affect property investors and developers. When rates fall, borrowing becomes more affordable and demand may strengthen. Housing outcomes still depend on other factors, including supply, population growth, employment, lending standards and consumer confidence.
When the RBA changes its cash rate, the investment implications flow through several channels. Rate hikes typically weigh on interest rate-sensitive sectors like REITs, utilities, and high-growth technology, while supporting bank earnings through wider margins. Rate cuts have opposite effects. The equity market reaction also depends on whether the rate move was anticipated by markets, as unexpected changes create larger price moves than well-telegraphed decisions.
Rate-sensitive stocks are companies whose earnings or valuations can be strongly affected by interest rate changes. They commonly include REITs, utilities, infrastructure companies, highly leveraged businesses and growth stocks valued on earnings expected well into the future. Rising rates can increase borrowing costs and reduce the present value of future earnings. Investors often respond by reviewing debt levels, refinancing risks, cash flow strength and valuation rather than simply avoiding entire sectors. Banks may benefit from wider lending margins, although funding costs and credit losses also matter.
Central banks use interest rates to influence demand and keep inflation under control. When inflation remains too high, higher rates make borrowing more expensive and encourage saving, which can reduce household spending, business investment and pricing pressure. When inflation is weak or economic activity slows, central banks may lower rates to support borrowing and demand. The effect is not immediate, and inflation can also be driven by supply disruptions, energy prices, wages and exchange rates that interest-rate changes cannot directly resolve.
Rising interest rates increase the cost of borrowing, which can reduce consumer spending. When rates rise, credit becomes more expensive, leading to higher monthly payments on loans, credit cards, and mortgages. As borrowing costs increase, consumers may cut back on discretionary spending, such as on big-ticket items like cars, appliances, or homes. Additionally, higher interest rates can lower consumer confidence, further reducing spending. However, in some cases, higher rates can signal a healthy economy, which may partially offset the negative effects on consumer behaviour.