Most options traders carry one assumption they rarely question: one contract equals 100 shares. After the iShares Ethereum Trust ETF (ETHA) completed a 1-for-3 reverse stock split on 6 October 2026, that assumption stopped holding for thousands of existing positions. The adjusted ETHA options now deliver 33 shares plus cash, not 100.
The danger is that nothing looks broken. The strike on your screen is the same number you saw last week, and the contract sits in your account looking ordinary.
The only visible warning is a small change to the symbol. ETHA options became ETHA1, 2ETHA1 and 4ETHA1, and a trader who misses that suffix can size a hedge or read a profit badly wrong.
This explainer shows you how to read an adjusted contract and confirm what it actually delivers. It also explains why the contract appears to price off a much lower stock, and gives you one practical rule for deciding which contracts to trade.
What actually changes in an option after a reverse split?
Take the ETHA case first. A contract that delivered 100 shares on Friday delivered 33 shares plus a sliver of cash by Tuesday’s open. The strike did not move.
That is not an ETHA quirk. It is how the Options Clearing Corporation (OCC), the body that guarantees and settles US exchange-listed options, usually handles reverse splits. A reverse split combines several existing shares into one, so the share count falls and the price per share rises.
Your share count shrinks and the price per share rises, but your total holding value stays the same, and the reverse split changes only the share count, price, NAV per share and option deliverable.
The general OCC pattern
When a company runs a reverse split, the OCC typically shrinks the option’s deliverable. The deliverable is the exact bundle of shares, cash or other securities you receive or hand over if the option is exercised. The strike, the number of contracts you hold and the 100 multiplier usually stay the same.
The Options Industry Council (OIC), OCC’s education arm, uses a simple example. In a 1-for-10 split, a 100-share contract becomes a 10-share deliverable with the same strike. A 1-for-20 split leaves you with 5 shares per contract.
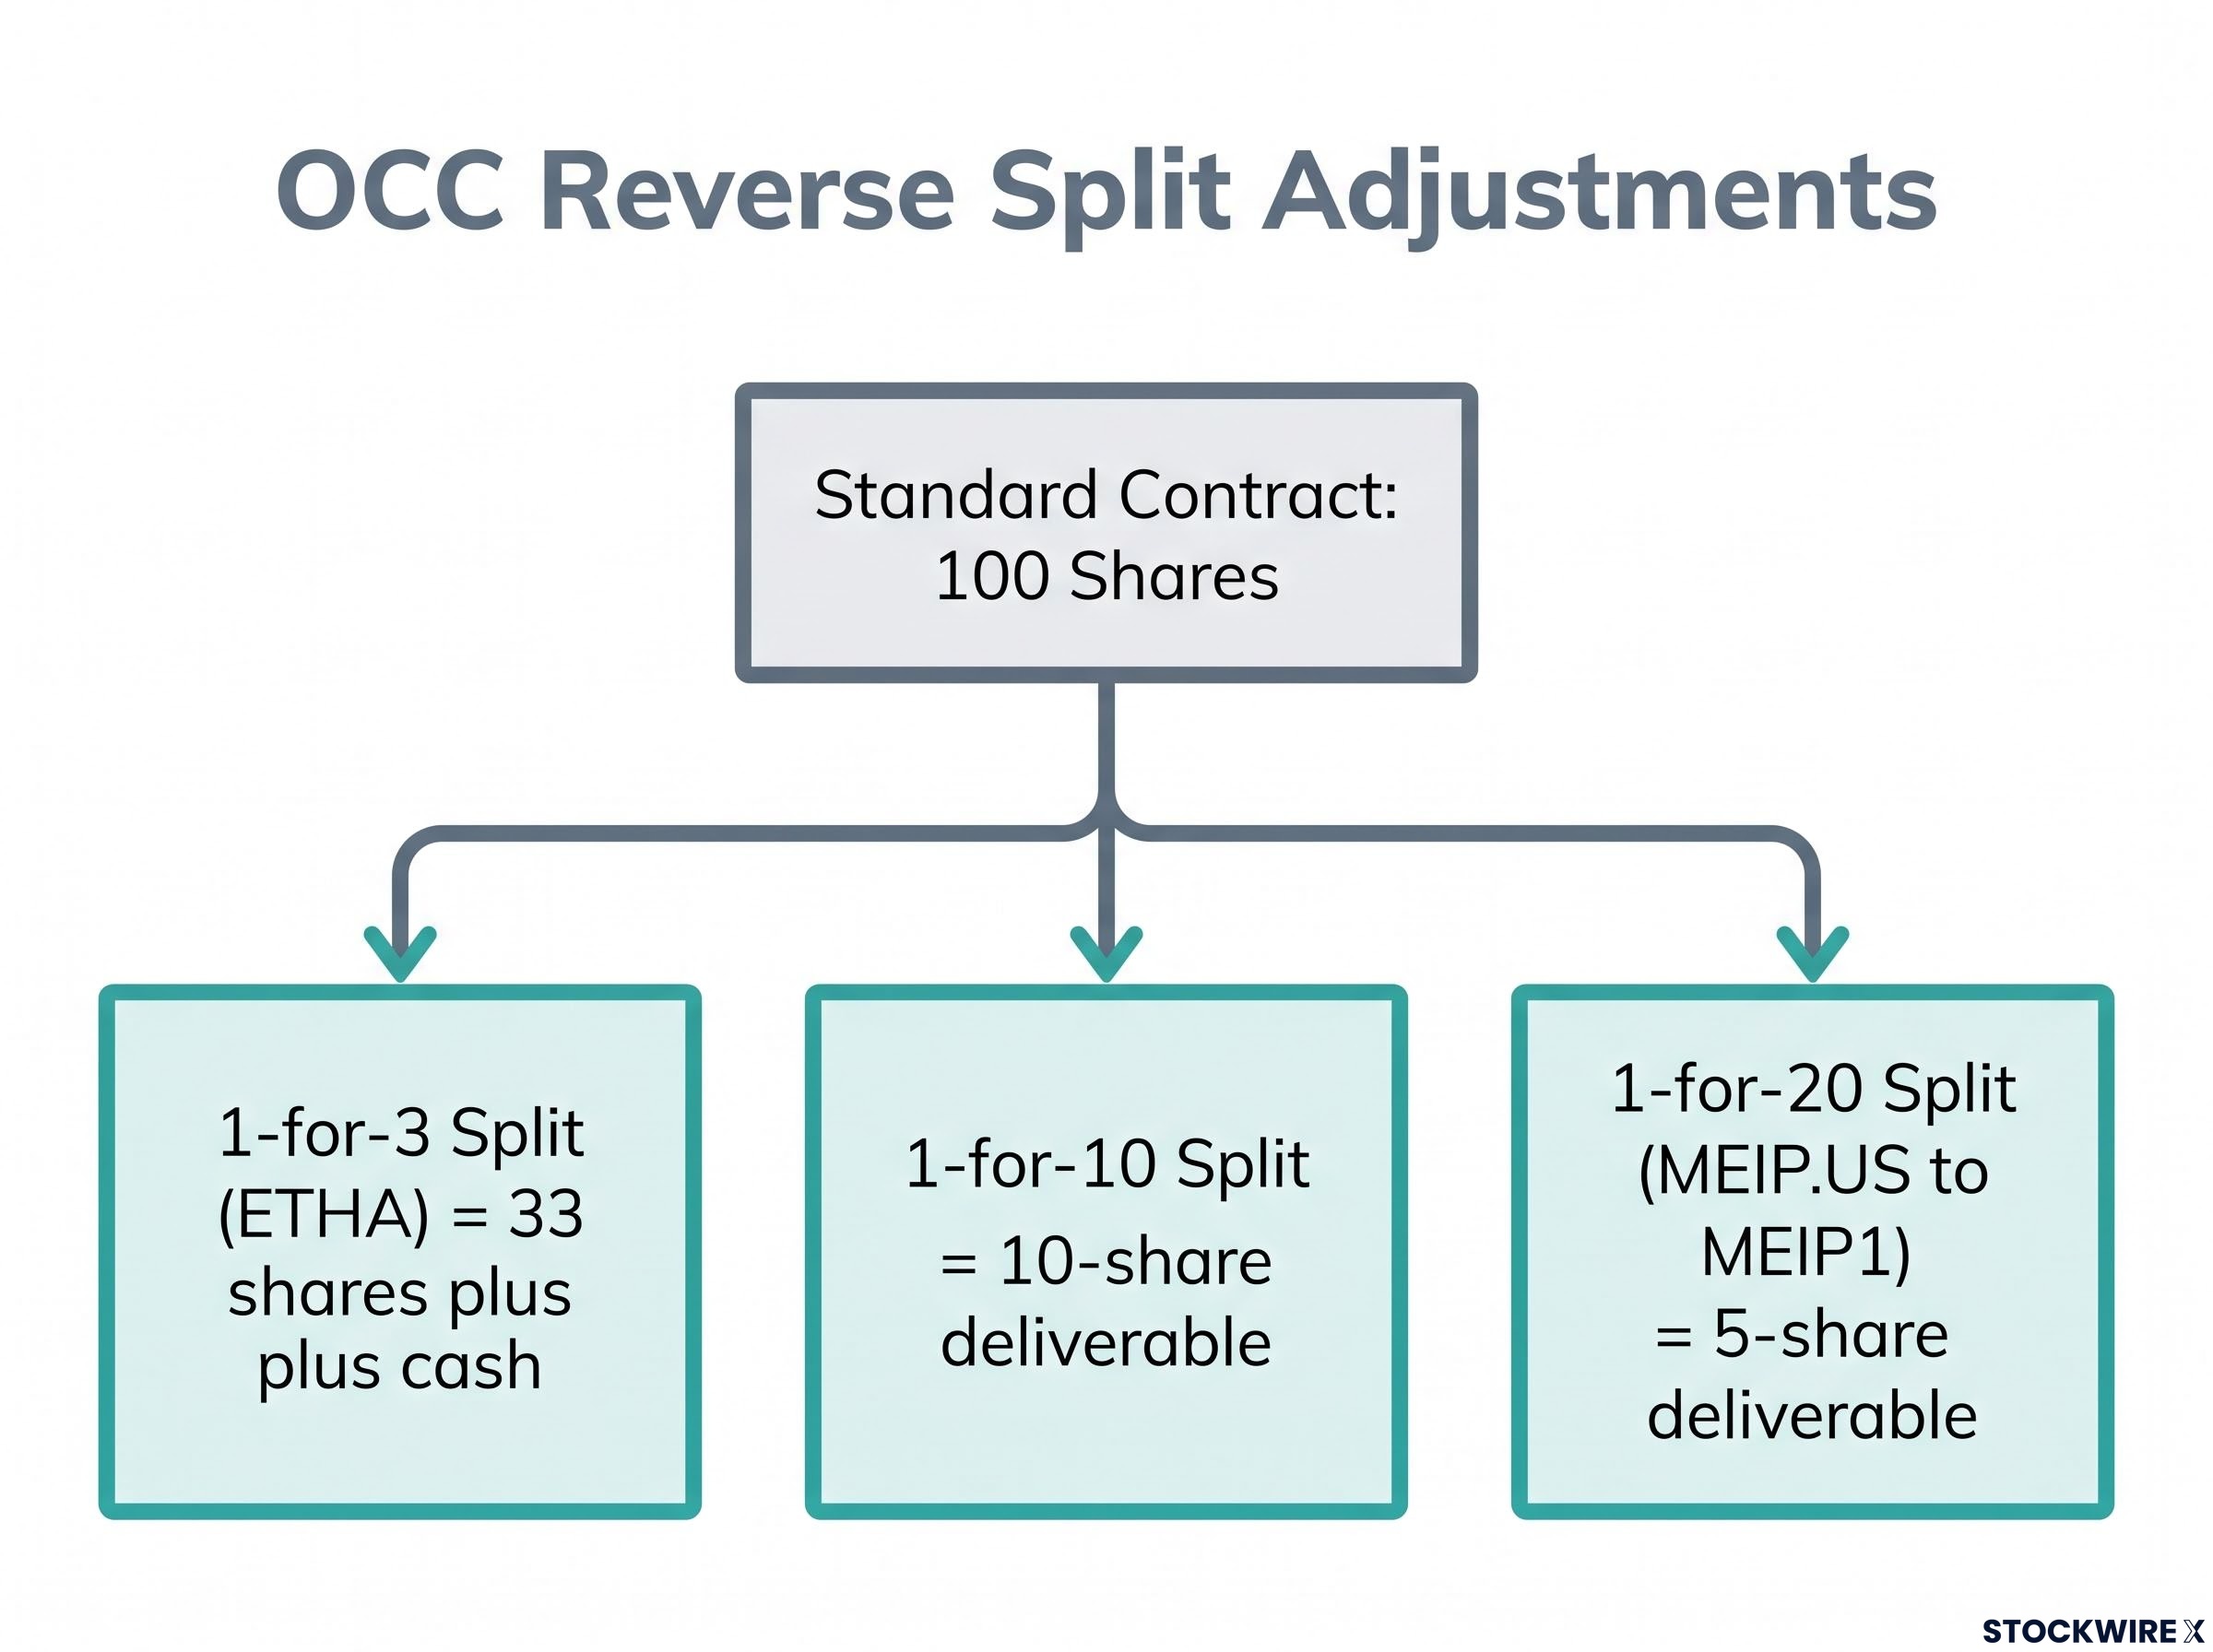
Two more conventions apply. The symbol gets a numeric suffix to flag the non-standard contract, and any fractional share is paid as cash in lieu, meaning cash instead of the fraction.
The OCC principle In a July 2026 post, the OCC summed it up plainly: your options do not vanish after a split. They are adjusted to preserve their economic value.
The OCC’s own FAQ adds a point worth holding onto: an adjusted call should not become in-the-money purely because the split pushed the share price higher.
The ETHA example in detail
ETHA’s split had a record date of 5 October 2026 and took effect at the open on 6 October 2026. According to the original source, the share price moved from roughly $20 to roughly $56 (approximate figures).
Each adjusted contract now delivers 33 post-split shares plus cash in lieu of about 0.3333 of a share. That cash is part of the adjusted deliverable itself, and the OCC delays settling it until the exact amount is determined.
ETHA1 contracts were listed on 6 October, and standard ETHA contracts resumed trading on 7 October.
| Feature | Standard ETHA contract | Adjusted ETHA1 contract |
|---|---|---|
| Symbol | ETHA | ETHA1, 2ETHA1, 4ETHA1 |
| Deliverable | 100 shares | 33 shares plus cash |
| Strike | Set at listing | Unchanged from pre-split |
| Multiplier | 100 | 100 |
| Cash component | None | Cash in lieu of about 0.3333 share, settled later |
For you, the contract in your account may no longer represent what it did last week. The symbol and the deliverable now matter more than the familiar strike.
When big ASX news breaks, our subscribers know first
How to verify an adjusted deliverable before you trade
Knowing the pattern is half the job. The other half is confirming it for the specific contract in front of you, and that takes minutes.
Work through the sources in order of authority:
- Read the OCC Information Memo. The OCC publishes one for every corporate action, setting out the new deliverable, any strike change and the effective date.
- Open your broker’s contract-detail screen. Some platforms show the deliverable right next to the contract.
- Use a non-standard deliverable filter if your platform has one. According to the original source, ETHA has such a series, while Microsoft has none.
- Check the symbol. A “1” suffix, as in ETHA1 or MEIP1, is your visible flag.
One caveat matters here. Fidelity and Firstrade describe reverse-split adjustments as raising the strike, while the ETHA adjustment kept the strike and cut the deliverable. Do not assume one method; confirm each case against its memo.
Reverse splits are also not the only source of odd contracts. Buyouts can create deliverables mixing different securities, such as 100 shares of Microsoft plus a few shares of another company.
A market-based sanity check
If you want proof straight from the market, price a combo. A combo, or synthetic future, means buying a call and selling a put at the same strike and expiry, which together behave like owning the stock.
Add the combo’s price to the strike and you get the stock level the contract is really tracking. If that level matches the live share price, the contract is tied to a full 100 shares.
The ETHA check, by the numbers An at-the-money combo priced around 15 cents, about 8 days from expiry, implied a synthetic future near $56.15. The stock was trading near $55.82. That match confirms a standard 100-share contract.
Skipping verification is the single most avoidable source of error with adjusted options. The check costs you a few minutes; getting it wrong can cost you the trade.
Why adjusted options seem to price off a much lower stock
Here is the screen that confuses people. ETHA trades near $56, yet the ETHA1 options behave as though the stock were sitting far lower.
The puzzle resolves with one multiplication. Because the strike stayed put while the deliverable shrank to roughly a third, each contract is effectively tied to a third of the share price.
Run the ETHA numbers yourself:
- Start with the stock price: about $55.82.
- Take the deliverable ratio: 33 shares ÷ 100 = 0.33.
- Multiply them: $55.82 × 0.33 ≈ $18.40.
- Compare that effective price, not $55.82, with the adjusted contract’s strike.
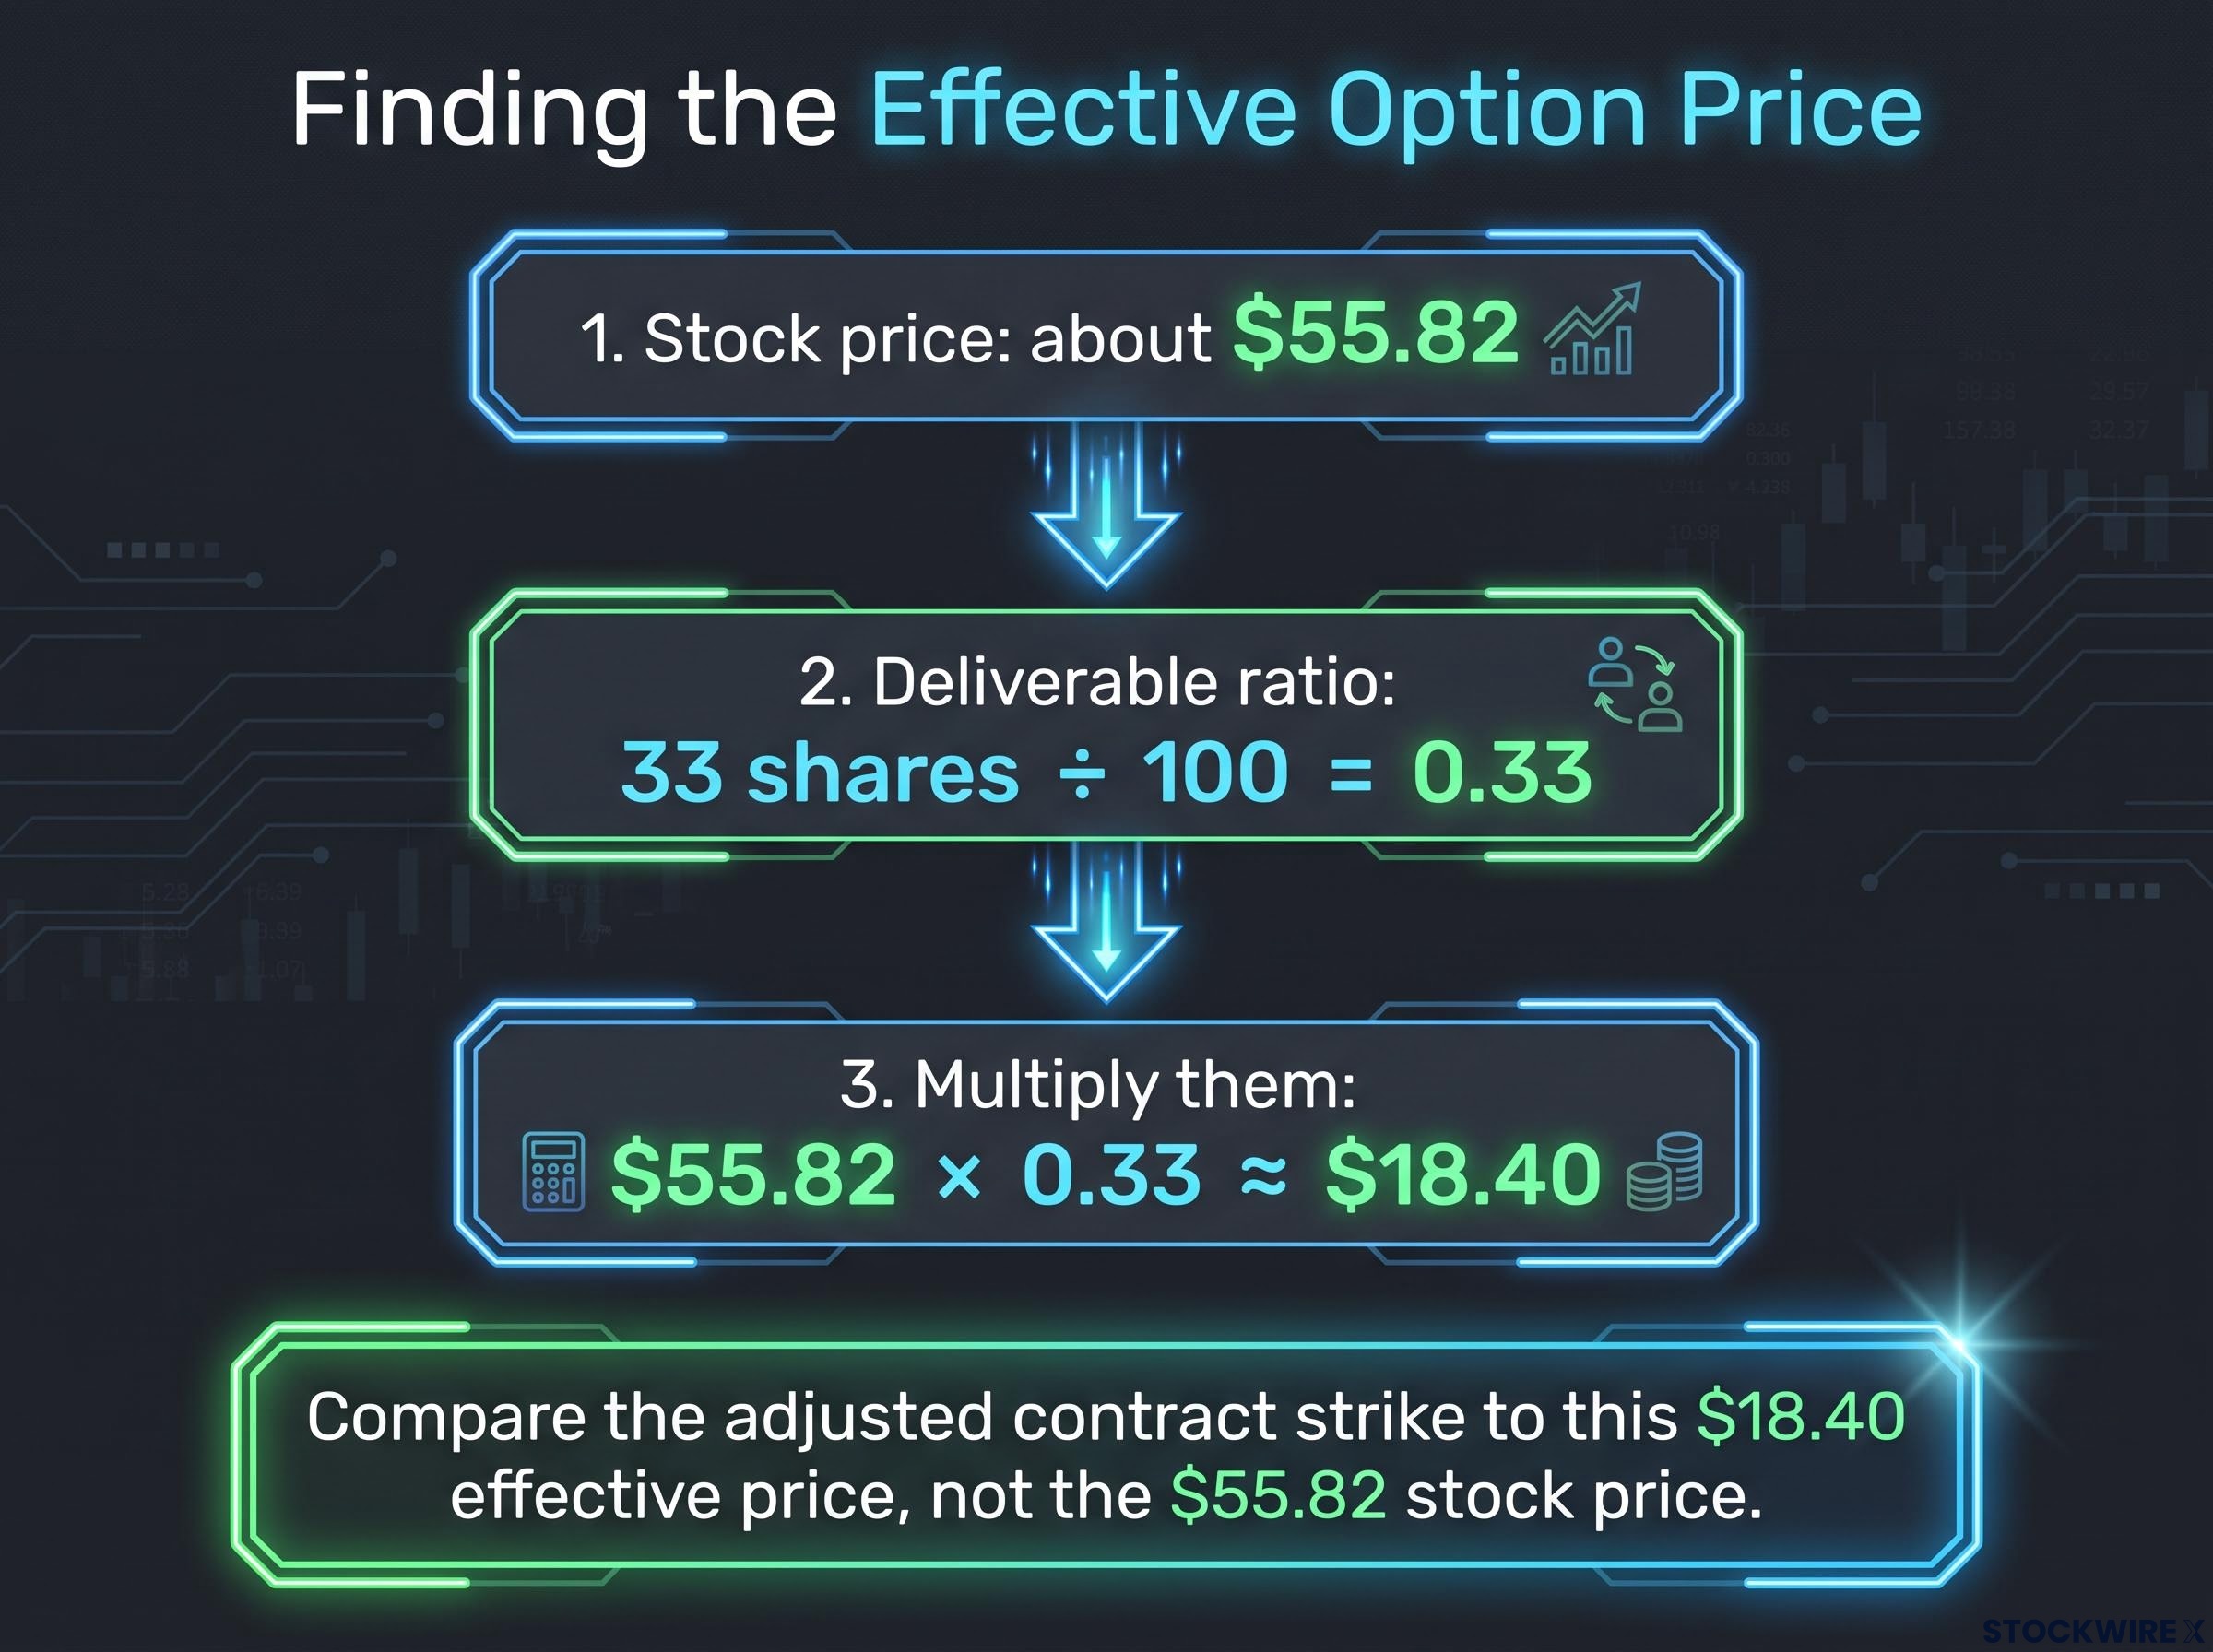
The original source quoted an effective level of roughly $22, while the direct arithmetic gives about $18.40. Treat any quoted figure as a rough guide and do the multiplication on live prices yourself.
Equicurious shows the same logic from the other direction in a 1-for-20 split. A $1 strike on 100 shares carries the same economics as a $20 strike on 5 shares.
There is one more trap. The premium multiplier usually stays at 100 even though the contract controls far fewer shares, so midpoints and profit-and-loss figures can look strange next to the stock’s moves.
| What the screen suggests | What the contract really means |
|---|---|
| Stock at about $56, so low-strike calls look deep in-the-money | The contract tracks an effective price of roughly $18-$19; compare strikes against that |
| One contract equals 100 shares | One contract equals 33 shares plus cash |
| Premium × 100 reflects full exposure | Premium × 100 reflects a much smaller share position |
| The higher share price lifted call values | The OCC FAQ says calls should not become in-the-money from the split alone |
The takeaway is direct. Comparing an adjusted contract’s strike with the quoted stock price will mislead you, so convert to the effective price first, every time.
Why liquidity moves to standard contracts, and the rule that follows
Even once you understand an adjusted contract, a second question remains: should you trade it? The answer comes from how market makers, the firms that quote prices on both sides, handle these contracts.
Why liquidity migrates
Market makers usually hedge option positions with stock in 100-share lots. A deliverable of 33 shares plus a pending cash payment does not fit that structure neatly, so their hedges are imperfect.
They also have to value two legs at once, the shares and the delayed cash. Less certainty generally means less willingness to quote tight prices.
Wider quotes push new traders towards the standard 100-share series. According to the original source, volume in non-standard contracts falls sharply, while existing open interest stays put in the adjusted series and continues to trade as holders exit.
Brokers frame it the same way. tastytrade, Fidelity, Firstrade, Longbridge and Phillip Securities (POEMS) present adjusted contracts mainly as tools for managing existing exposure. POEMS illustrates this with MEI Pharma (MEIP.US), whose 1-for-20 split left contracts delivering 5 shares under the symbol MEIP1, with strike and expiry unchanged.
No quantitative comparison of open interest, volume or spreads between adjusted and standard series surfaced in the research, for ETHA or any other ticker. The liquidity gap is consistently described, but not measured.
The risks you face in adjusted contracts include:
- Odd-lot assignment: exercise can leave you holding 33 shares, which may carry different fee or margin treatment
- Wider bid-ask spreads: the gap between buying and selling prices tends to be larger
- Slippage: your fill can land well away from the price you expected
- Unreliable mid-quotes: the midpoint may not reflect fair value
- Order-sizing errors: assuming 100 shares per contract can leave you over- or under-hedged
The practical rule and its limits
The causal chain leads to one clear conclusion.
The rule Open new positions only in standard 100-share contracts, and use adjusted contracts to close or manage positions you already hold.
The exception is built in. If you already own ETHA1 contracts, you may need to trade them to exit, so check the deliverable and use limit orders rather than trusting the midpoint.
Brokers present adjusted contracts mainly as tools for managing existing positions, and the same discipline of removing the unacceptable risk with the smallest mechanical action applies when you exit an ETHA1 holding.
The practical cost of an adjusted contract usually shows up in spreads and exit difficulty. The rule exists to keep that cost away from your new trades. Before any of it, confirm the OCC memo.
What to remember the next time a reverse split hits your options
Three habits cover almost every adjusted-contract mistake. Confirm the deliverable, convert to the effective price before judging any strike, and open new positions in standard 100-share contracts.
Reverse splits recur across ETFs and individual stocks, and the mechanics rarely change. Each time, the OCC Information Memo is your first stop, followed by your broker’s contract-detail screen.
If you hold options today, check your account for any symbol ending in a “1”. It takes a minute and tells you whether your contracts still mean what you think they mean.
Investors exploring new positions after checking their adjusted contracts can read our deep-dive into low volatility options strategies, which explains how a long vertical spread halves the maximum loss.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.