A falling euro during a bout of market turmoil looks like a verdict on Europe. The pair slid to roughly 1.1100, and the obvious reading is that the single currency deserved it. ING‘s currency team argues the opposite: the drop overshot, and its models point back above 1.1200 if markets calm down.
The pressure came from several directions at once. Stronger US rates, French fiscal stress, higher energy prices and equity volatility all hit the euro. ING’s Francesco Pesole argues the decline has gone further than short-term interest rate differentials justify. ECB succession talk has added another layer of headlines on top.
The question that matters for any EUR/USD forecast is which force is driving the selloff. Sentiment-driven moves and rate-driven moves behave differently. Here is a framework for telling them apart, and for weighing ING’s rebound case against the forecasters who expect the euro to keep sliding.
Why does ING think the EUR/USD selloff went too far?
ING’s case rests on a measurable gap. The pair traded near 1.1160 on 1 November 2026 after a 0.20% daily fall, having recently touched roughly 1.1100. ING’s short-term models, published on 9 November 2026, put the euro 2.1%-2.3% below where interest rate differentials suggest it should trade.
| Measure | Latest reported figure | Source and date |
|---|---|---|
| EUR/USD spot | About 1.1160 | ExchangeRates.org.uk, 1 November 2026 |
| Recent low | Near 1.1100 | ExchangeRates.org.uk, 1 November 2026 |
| ING short-term undervaluation | 2.1%-2.3% | FXStreet/ING, 9 November 2026 |
| ING recovery reference | Above 1.1200 | FXStreet/ING, 9 November 2026 |
ING judges that undervaluation to be larger than the French risk premium alone would explain. A risk premium is the extra return investors demand for holding an asset they see as riskier. In other words, French political trouble accounts for part of the euro’s discount, but not all of it.
The rate backdrop still favours the dollar. The ECB deposit rate sits at 2.50%, against a Federal Reserve target range of 3.75%-4.00%. Yet markets expect that gap to shrink: BNP Paribas expects a December ECB hike to 2.75%, and MUFG expects hikes taking the deposit rate to 3.00% by March 2027.
The condition attached to the call ING’s expected move above 1.1200 depends on risk sentiment not facing fresh instability. If markets turn sharply risk-off again, the model gap may simply widen.
What this tells you is that the 2.1%-2.3% figure measures mispricing against one model. It is a conditional signal, not a guaranteed bounce, and you should treat it as a reason to watch closely rather than a trigger to act.
When big ASX news breaks, our subscribers know first
How front-end spreads, risk premia and equity turmoil interact
To judge ING’s claim, you need the mechanism behind it. It starts with a simple idea about where cash earns the most.
The carry logic
A front-end spread is the difference between short-term interest rates in two economies, usually measured on bonds or swaps maturing within about two years. When US short rates sit well above euro rates, holding dollars pays more. That advantage feeds through hedging costs, money-market allocation and carry, which is the income earned from holding a higher-yielding currency.
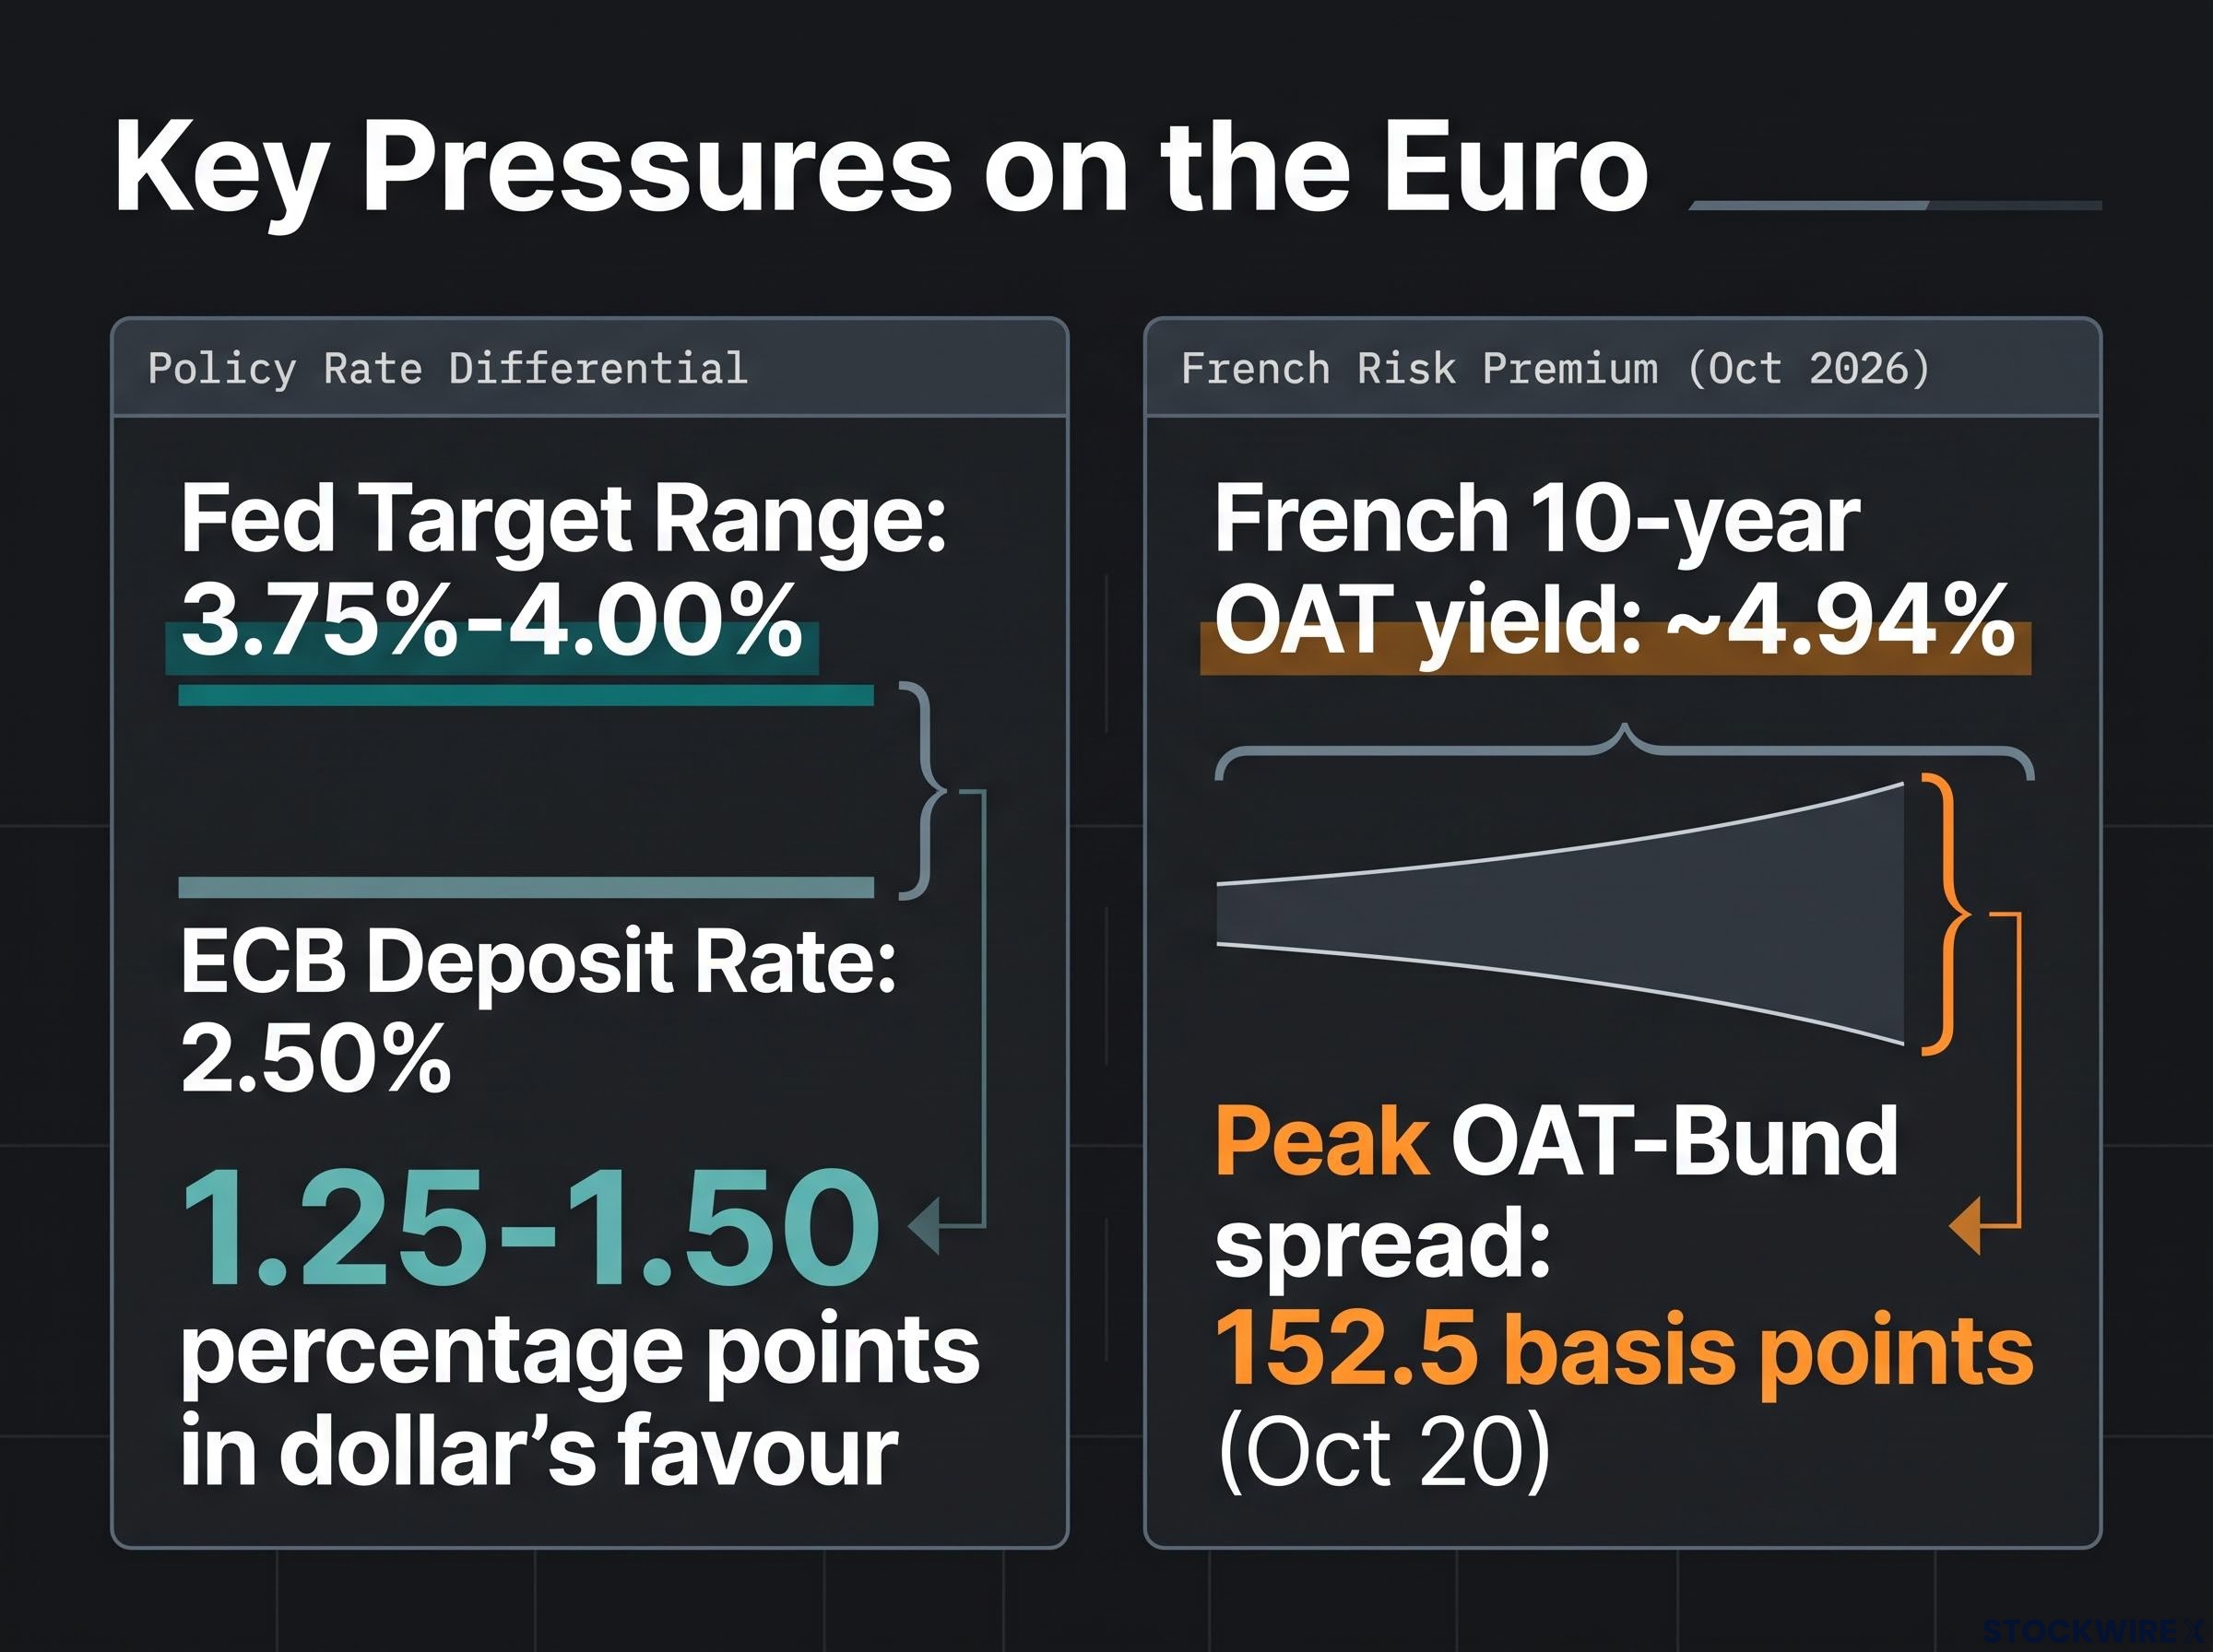
The dollar holds a 1.25-1.50 percentage point policy rate advantage, while the French risk premium peaked at a 152.5 basis point spread on Oct 20.
The policy rate differential currently runs at roughly 1.25-1.50 percentage points in the dollar’s favour. When that spread widens, the dollar becomes more attractive. When it narrows, because markets price more ECB tightening or fewer Fed hikes, the dollar’s edge shrinks.
Currencies react to the expected path of rates more than to any single decision, which is why central bank divergence can push a pair far from where today’s policy settings alone would place it.
Both forces are at work now. Markets are pricing more ECB tightening into 2027, and US midterm results reportedly reduced expectations of further Fed tightening. No precise, dated two-year US-German swap spread is available in the sources, but the direction is clear: spreads have stabilised or tightened.
When turmoil cuts both ways
Equity market stress does not push the dollar in one straight line. The sequence runs like this:
- Risk-off selling in shares normally supports the dollar as the global reserve and liquidity currency.
- Investors often buy US Treasuries, adding to dollar demand.
- That same turmoil can pull US yields lower and reduce expected Fed hikes.
- Lower US yields narrow the front-end spread, offsetting part of the dollar’s safe-haven gain.
Pesole’s argument sits in that tension. Stock market turmoil worsened sentiment but also tightened rate differentials, so the euro fell more on mood than rates justified. Scotiabank described a similar pattern: wider euro-zone and US spreads earlier contributed to euro losses, but those spreads have since steadied.
For you, the lesson is to track two drivers separately when watching the pair. A euro fall built on rate spreads tends to stick. A fall driven mainly by risk mood may be the more reversible of the two.
Does the French risk premium or rival forecasting undermine the rebound case?
If anything breaks ING’s thesis, it is likely to come from Paris.
The French premium
French 10-year government bond yields approached a roughly 24-year high in October. The spread between French government bonds (OATs) and German government bonds (Bunds) shows how much extra investors charge to lend to France. ING placed it around 135-140 basis points in its October assessment; it reached 152.5 basis points on 20 October, and JPMorgan later reported 146-150 basis points, with the 10-year OAT yield near 4.94%.
The drivers run deeper than one election. The government is trying to cut a large deficit while political instability, protests and unrest raise doubts about whether it can deliver. ING has suggested levels above 150 basis points may be becoming the new norm.
France’s fiscal crisis is rooted in debt near 117.6% of GDP and a minority government whose 2027 budget may roll over rather than pass intact, a combination that hits the euro as a specifically European event.
Where forecasters split
The disagreement among banks is genuine, and it centres on one question: will narrowing rate differentials or political, growth and safe-haven pressures dominate the next move?
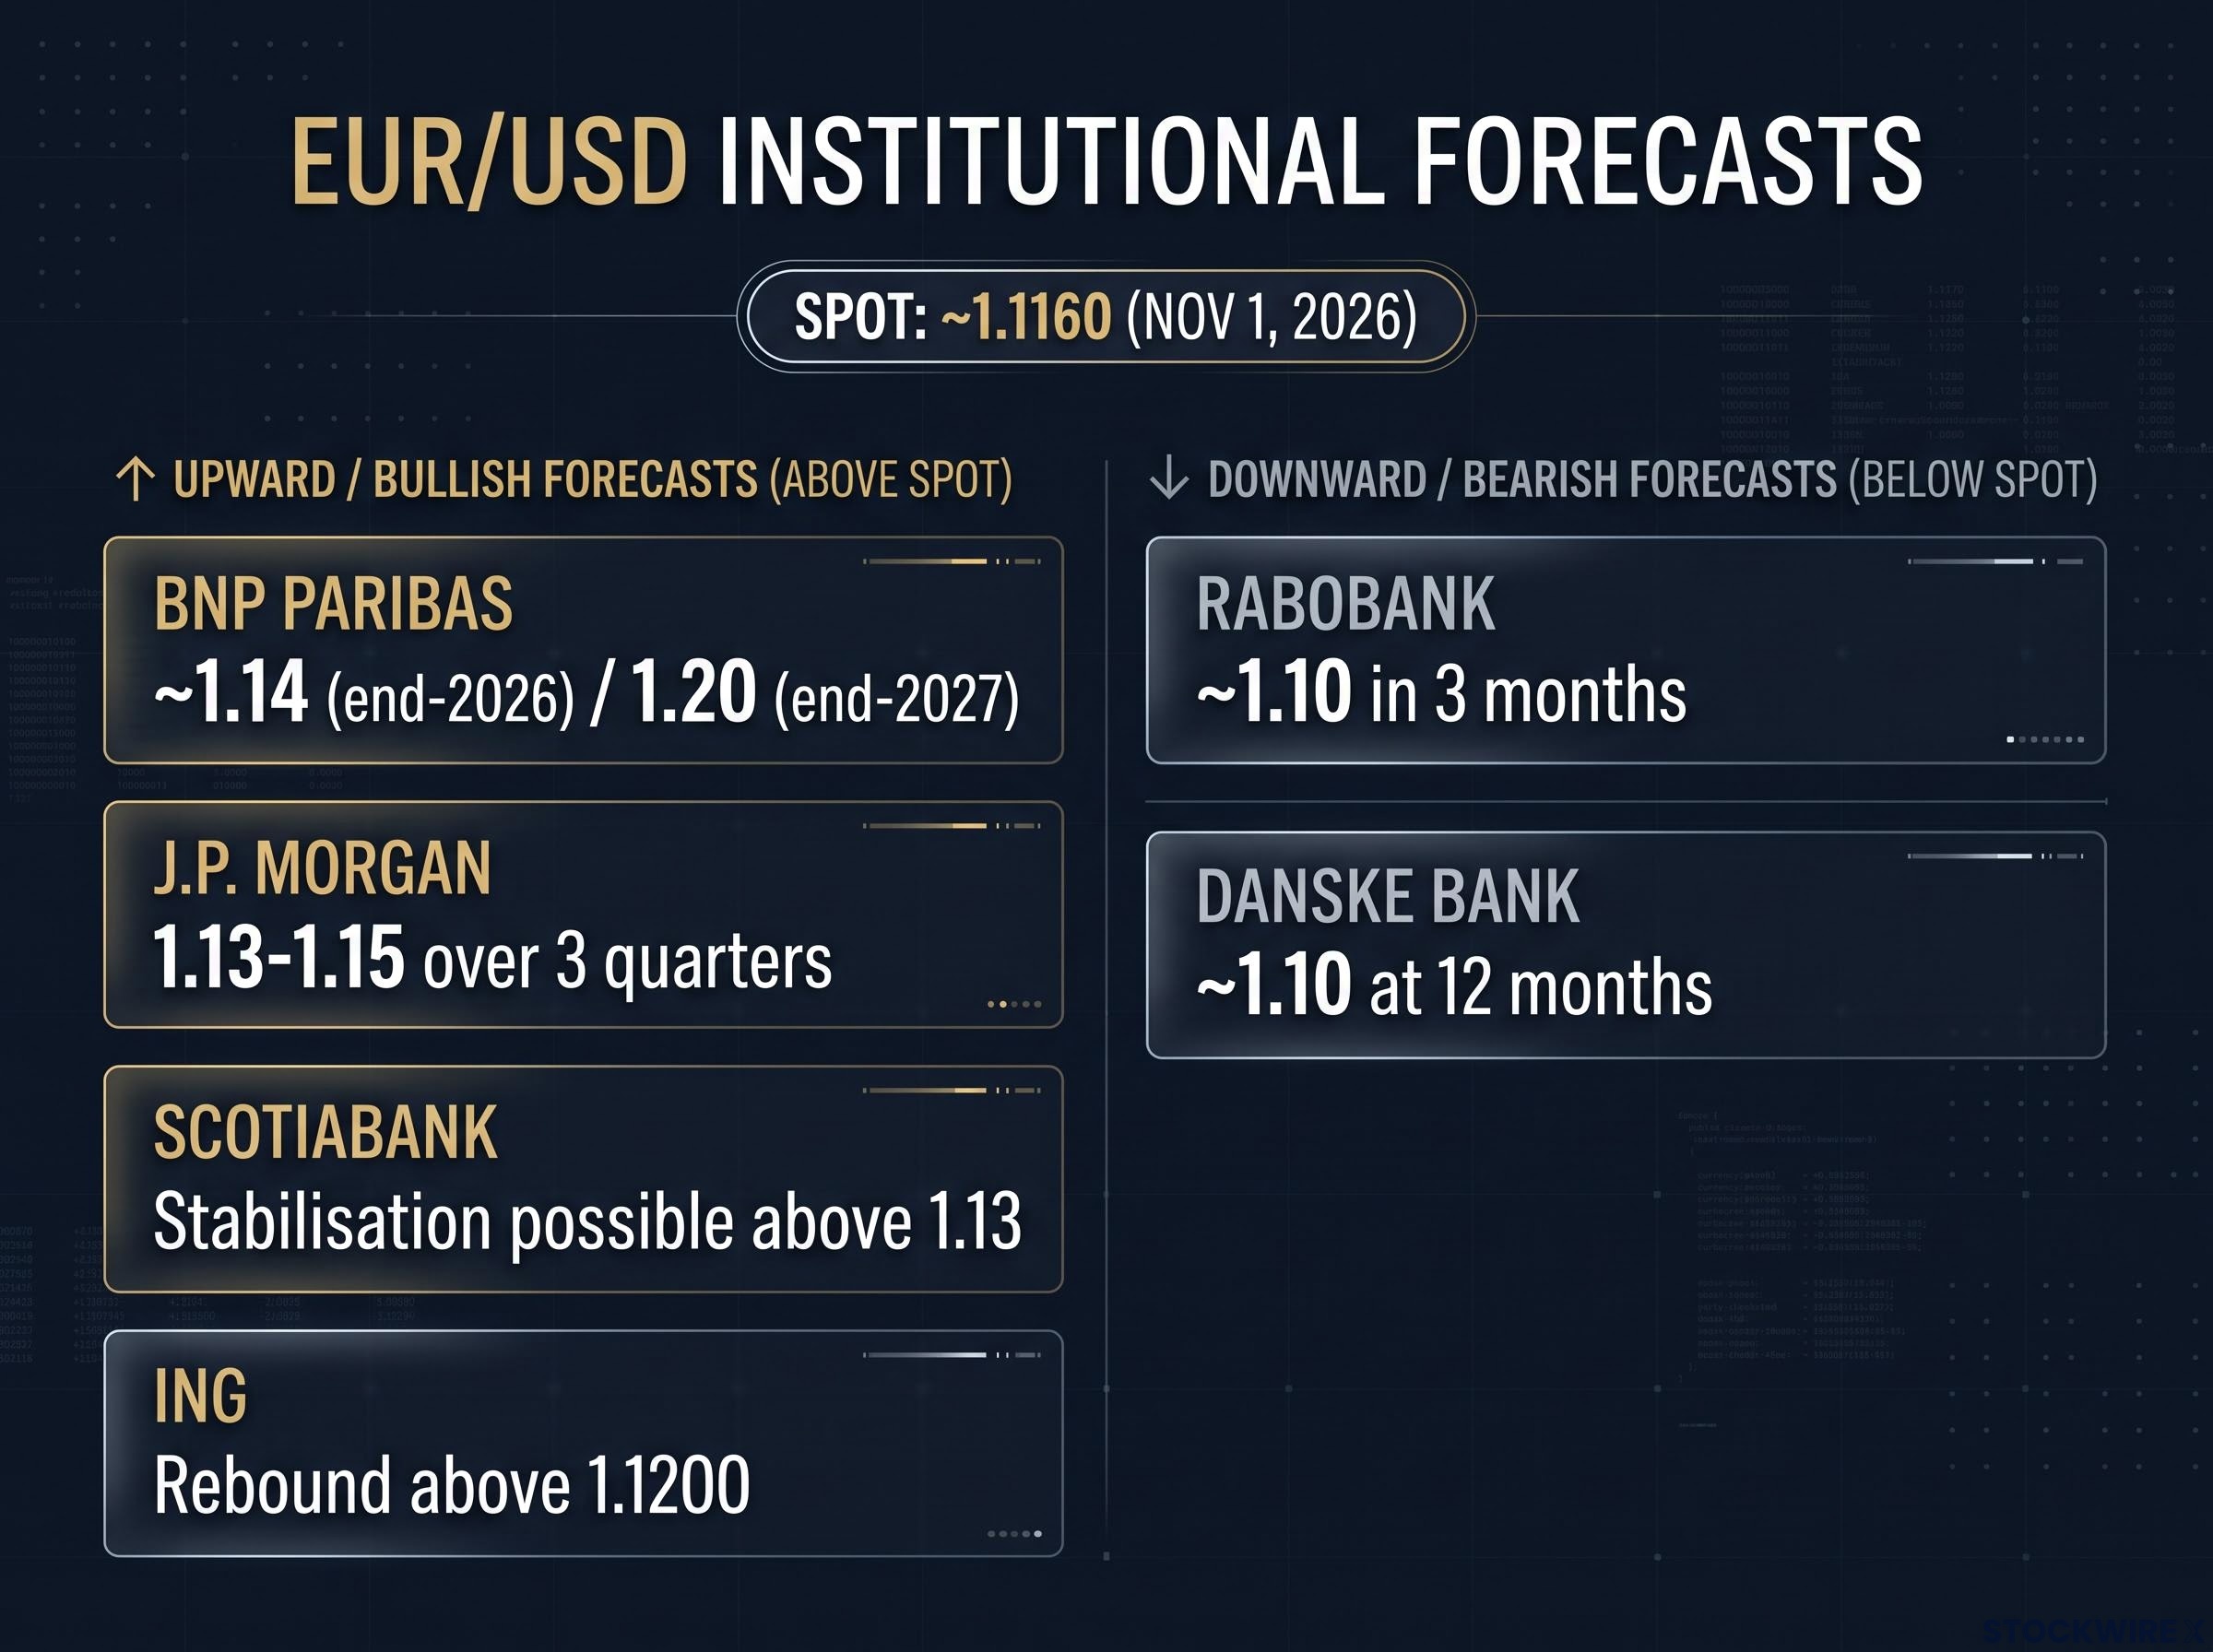
Bank forecasts for EUR/USD diverge widely, with ING looking for a rebound above 1.1200 and Danske Bank targeting ~1.10 at 12 months.
| Institution | View | Reasoning |
|---|---|---|
| ING (Pesole) | Rebound above 1.1200 | Fall too large versus short-term rate differentials |
| Scotiabank | Stabilisation possible above 1.13 | Pair down about 3% since mid-September, but spreads have steadied |
| BNP Paribas | About 1.14 by end-2026, 1.20 by end-2027 | Another ECB hike expected |
| MUFG | Near-term support, unsettled outlook | ECB hikes help; energy inflation and strained bond markets weigh |
| Rabobank | About 1.10 in three months | French bond stress could push investors out of the euro |
| J.P. Morgan | 1.13-1.15 over three quarters, cut from 1.20 | EU-US growth divergence and hawkish Fed repricing |
| Danske Bank | About 1.10 at 12 months | Bearish relative to ING |
The cautious camp points to several counter-risks:
- Renewed Fed repricing that widens the dollar’s rate advantage
- Energy-driven inflation that forces tighter ECB policy while hurting demand
- Tariff shocks that weigh on European activity and lift safe-haven dollar demand
- Weak European growth relative to the US
A fair-value gap is not a timing signal. In January 2023, ING saw EUR/USD near 1.08 as 7%-8% undervalued in real terms, with rate-spread models pointing above 1.20 later that year. Gaps can close, but sovereign stress can also hold a currency below model value for longer than the model implies. These forecasts are speculative and subject to change as market conditions develop.
What you should take from this is that the rebound case is only as strong as French spreads and risk mood stay contained. Those two indicators deserve more of your attention than the headline undervaluation figure.
What does ECB succession talk mean for the euro?
The calendar makes this story feel pressing:
- 9 November 2026: euro-area finance ministers review candidacies
- 17-18 December 2026: EU leaders target a decision at their summit
- 7 February 2027: Christine Lagarde is due to leave the ECB, earlier than her term’s normal end
The two leading candidates are Klaas Knot, former governor of De Nederlandsche Bank, nominated by the Netherlands, and Pablo Hernández de Cos, former Bank of Spain governor and current General Manager of the Bank for International Settlements, nominated by Spain. Both are experienced central bankers seen as credible and broadly continuity-oriented.
That profile is why ING expects little currency fallout.
ING’s assessment Succession discussions are expected to move the euro only modestly and briefly, with neither candidate likely to deliver a “seismic” policy change.
Reuters reported a limited market reaction, with analysts arguing the ECB’s consensus culture outweighs any single president. The structure supports that reading. The Governing Council holds 21 voting rights on monetary policy: six Executive Board members vote permanently, and the rest rotate among national central bank governors, so not all 21 governors vote at every meeting.
The residual risk is a surprise political bargain or a less orthodox candidate, which could add volatility. Short of that, you can treat succession headlines as background noise and keep the December summit as the one date worth marking.
Judging the near-term outlook: three signals to watch
ING’s case rests on a measurable gap between price and rate models, widened by sentiment more than fundamentals. French stress is the real test, and the succession story is mostly noise.
Three signals will tell you which side is winning:
- Front-end spreads: continued narrowing supports the rebound case.
- The OAT-Bund spread: sustained moves beyond the 150 basis point area strengthen the bears.
- Risk sentiment: fresh equity turmoil undoes ING’s core condition.
Add the 17-18 December summit to your calendar. ING’s call is conditional, and the 1.10 forecasts from Rabobank and Danske Bank show how wide the range of credible outcomes remains.
For the energy variable behind the December decision, our detailed coverage of the ECB rate outlook shows how TTF gas drives the call.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.