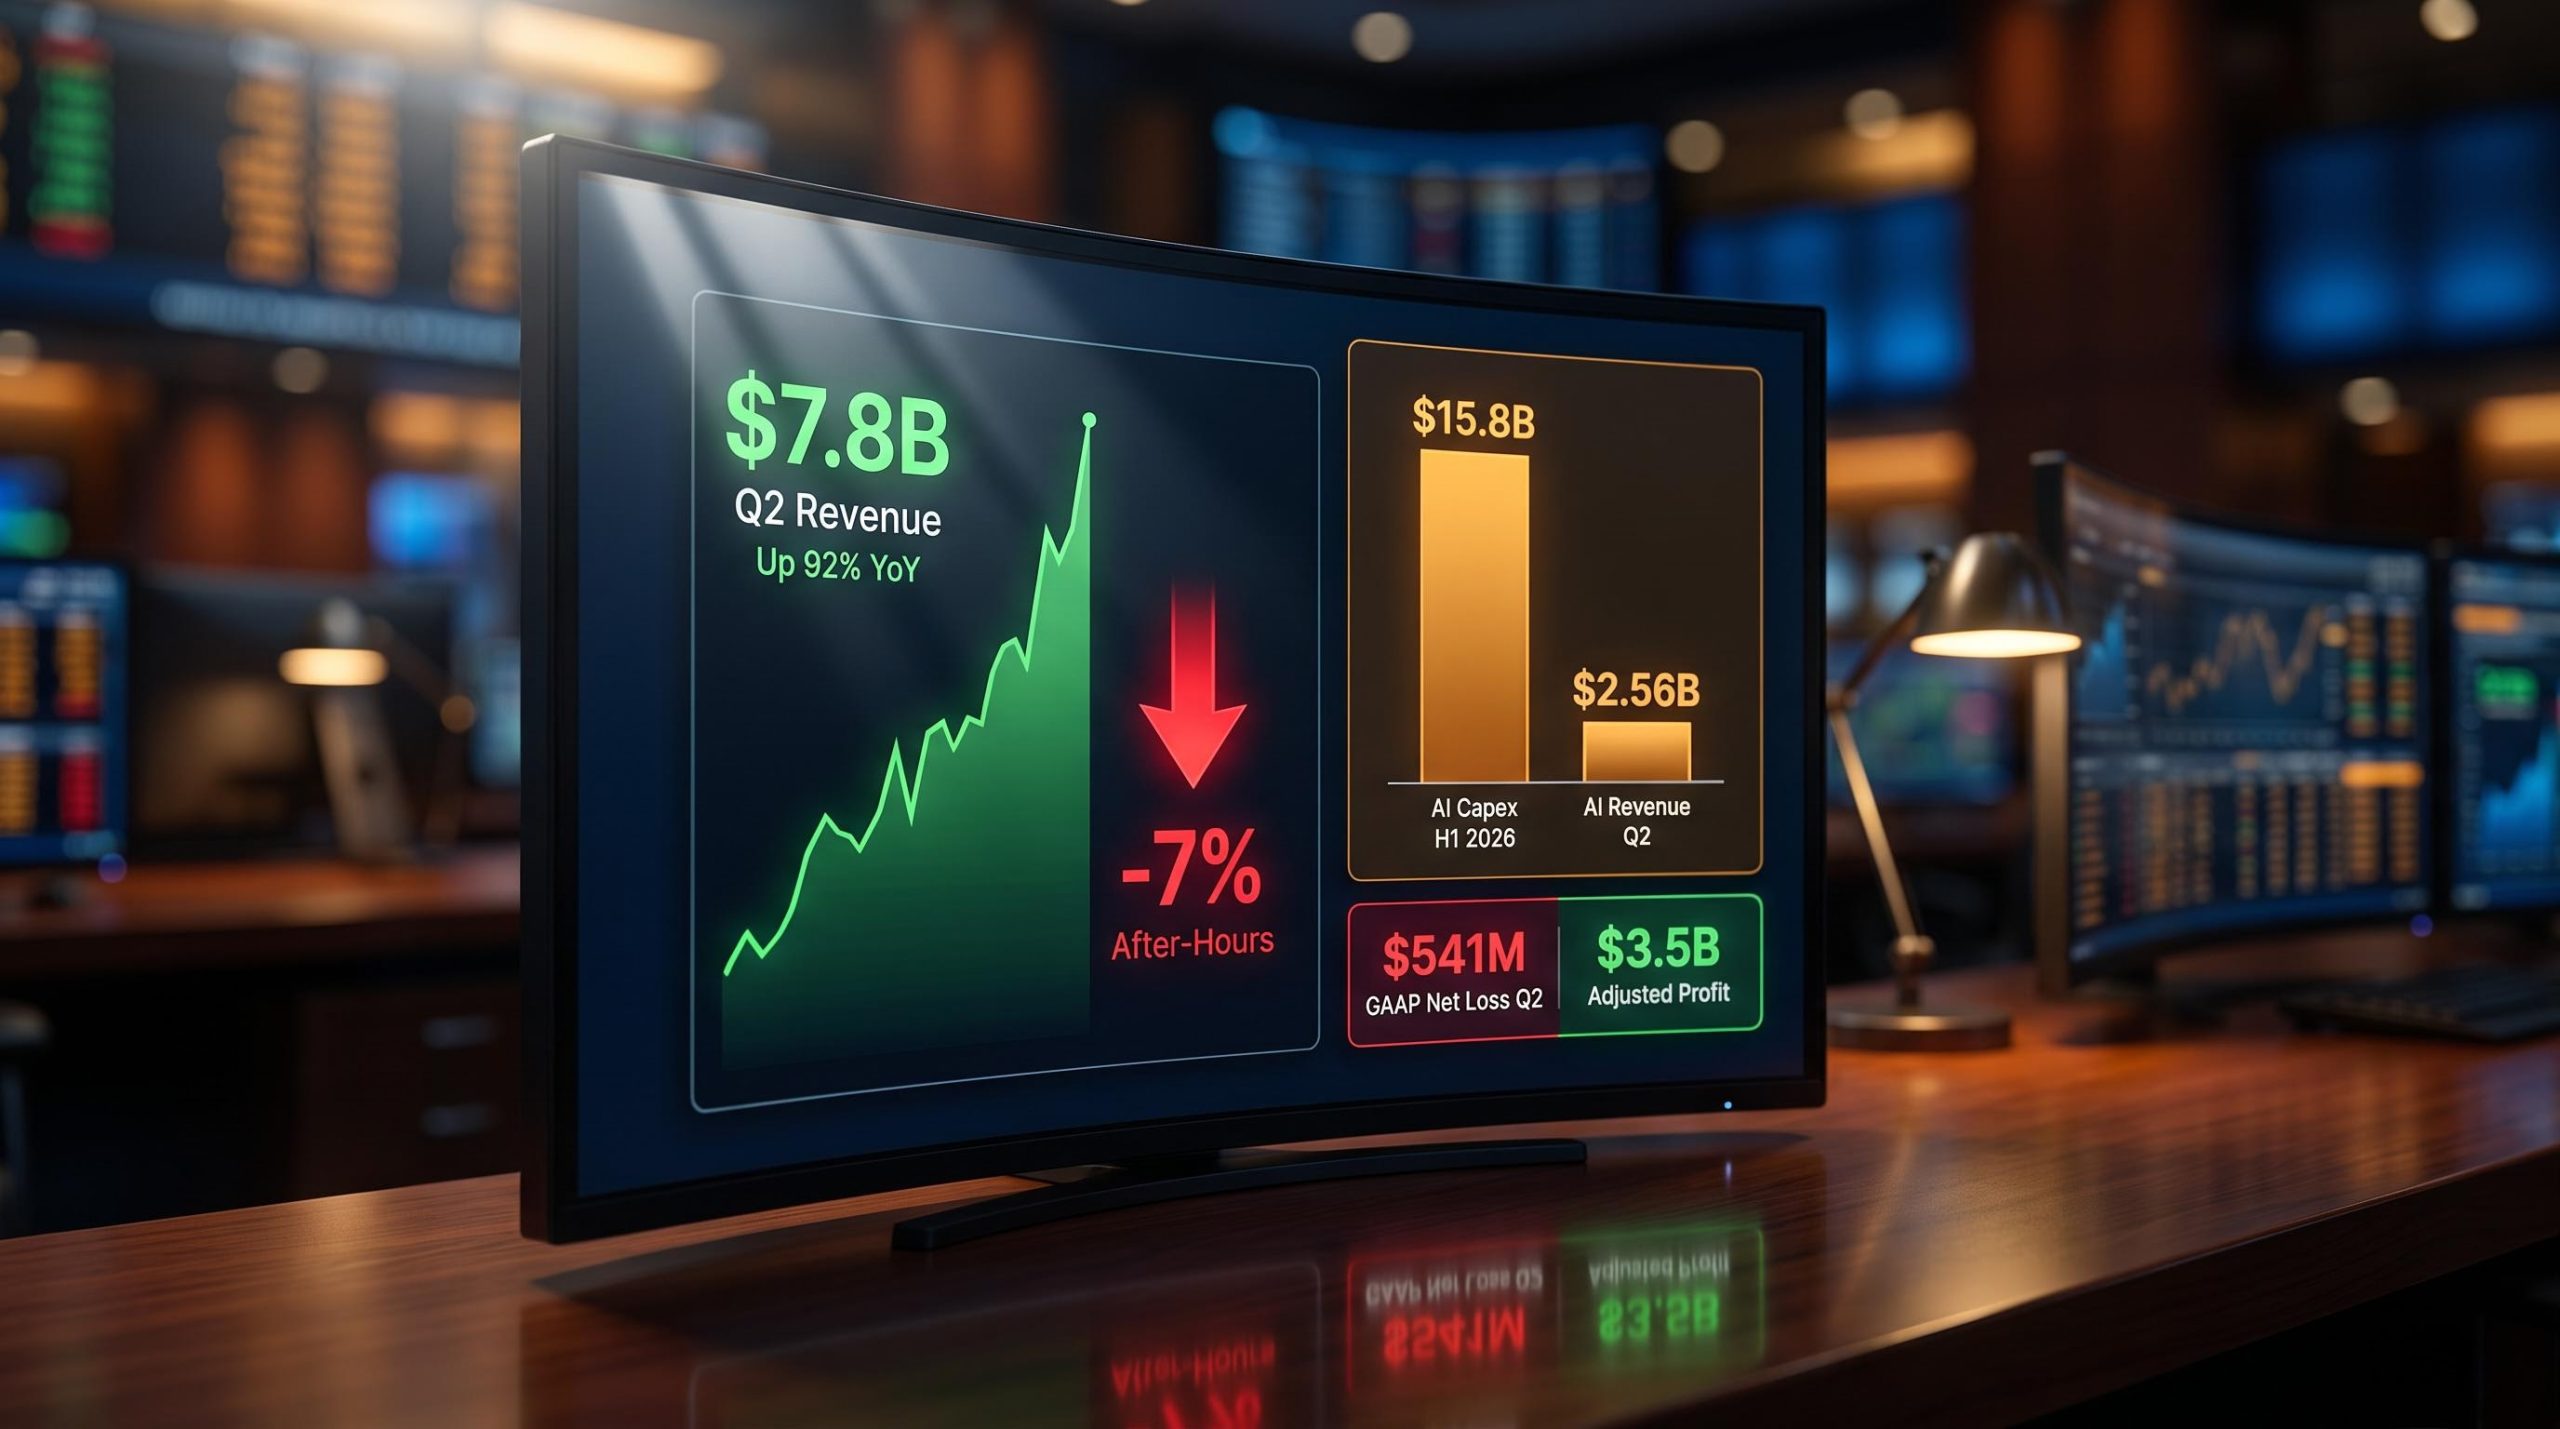
SpaceX nearly doubled its revenue year-over-year in Q2 2026, beat Wall Street’s consensus estimate by roughly $900 million, and the stock still fell more than 7% in after-hours trading.
That contradiction sits at the centre of the company’s debut earnings report as a publicly listed entity. SpaceX completed its IPO in June 2026, which means investors are forming their first real impression of the business through a set of numbers that show extraordinary top-line growth funded by extraordinary capital spending: $18.36 billion of confirmed first-half capex, with the vast majority concentrated in a single division. The disconnect between what the company earned and how the market responded is not a mystery. It is an argument about what all that spending is worth.
Here is what the data actually tells you: where the money is going, what the AI division’s burn rate implies about the return timeline, and which variables across the next two to three quarters will determine whether the selloff was a dislocation or a signal.
Revenue almost doubled, and the market still sold off
$7.8 billion in Q2 2026 revenue, up 92% year-over-year.
The beat was not marginal. SpaceX reported $7.8 billion in second-quarter revenue against analyst consensus of approximately $6.9 billion, a 92% year-over-year growth rate that few companies of any size have matched in recent quarters.
The strength was broad-based:
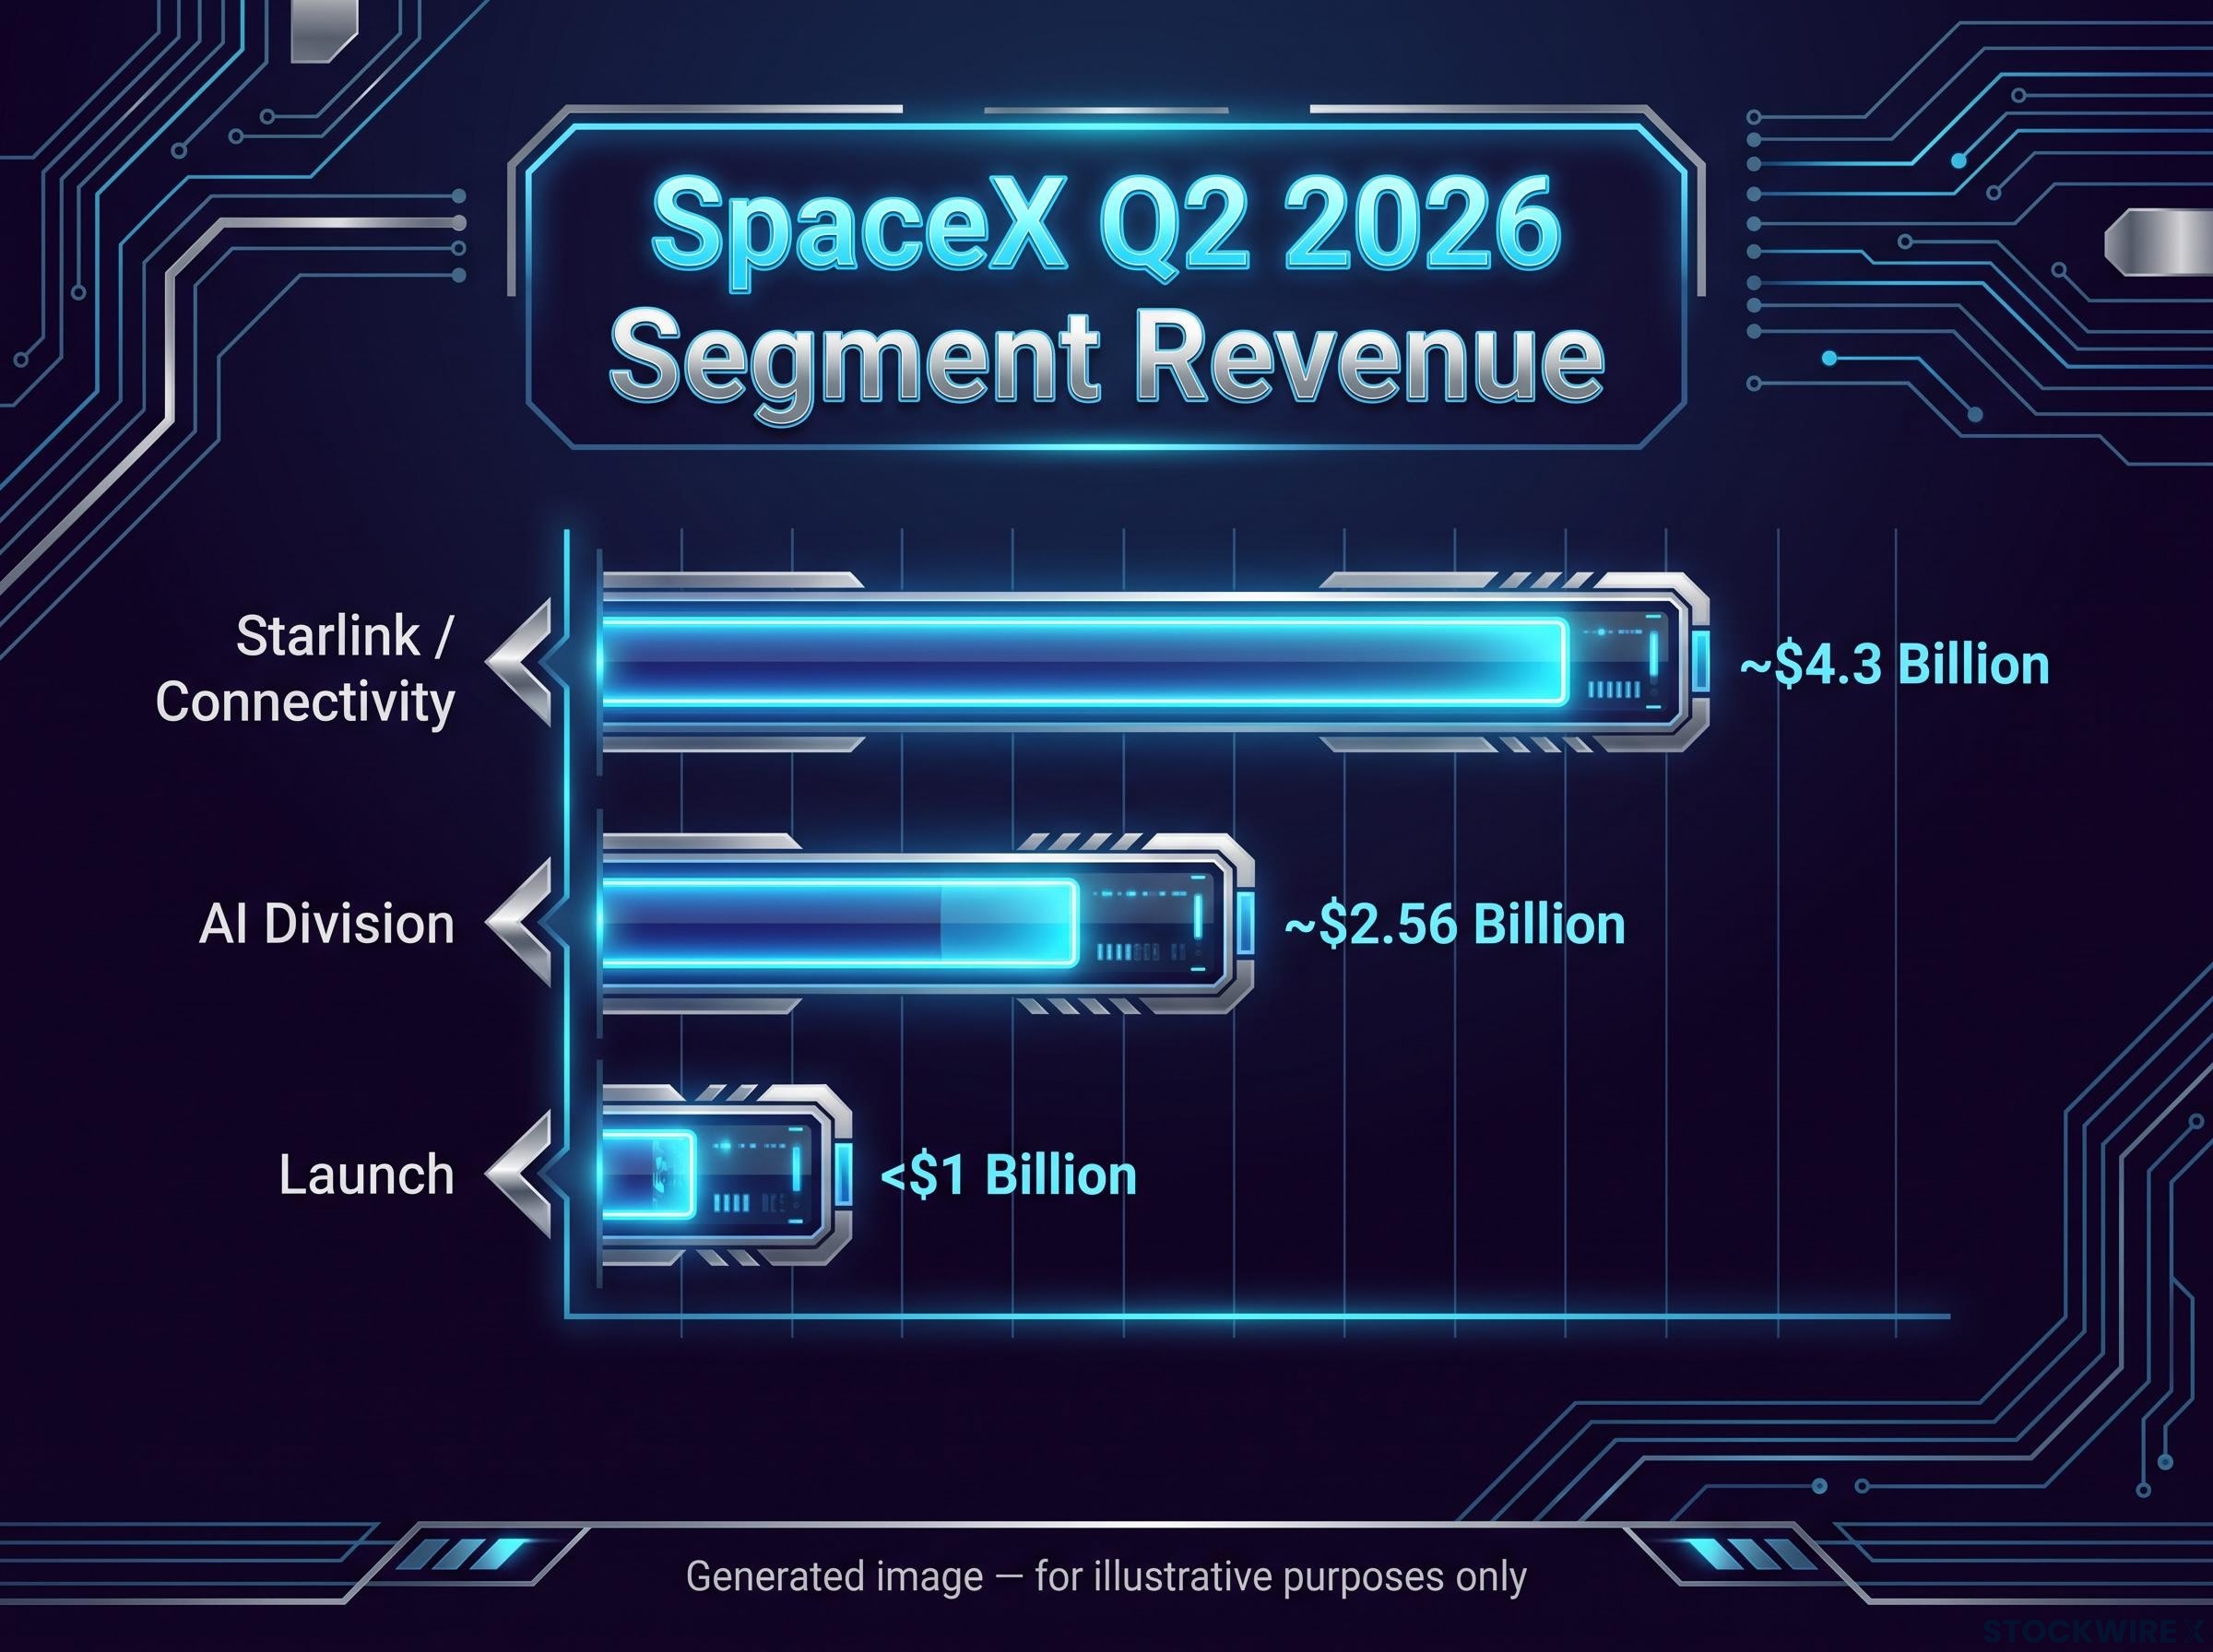
- Total revenue: $7.8 billion (up 92% year-over-year)
- Starlink/connectivity: nearly $4.3 billion (up 66% year-over-year)
- AI division: approximately $2.56 billion (up from $818 million in Q1 2026)
Every major segment exceeded expectations. And the stock dropped more than 7% in extended-hours trading.
The explanation does not sit in the revenue line. It sits further down the financial statements, in the capital expenditure figures that show a company spending at a pace its current earnings cannot yet support. The market is pricing SpaceX on what it is spending, not on what it is earning today, and that distinction shapes everything that follows.
When big ASX news breaks, our subscribers know first
Starlink is the engine, the launch business is the bet
Starlink is the financial foundation of SpaceX, and the gap between it and the launch segment is wide enough that investors should treat them as fundamentally different businesses operating under one ticker.
Starlink generated $11.4 billion in 2025 revenue, approximately 59% of the company’s total, with subscriber numbers doubling year-over-year and operating income growth of roughly 120%. In Q2 2026 alone, connectivity revenue reached nearly $4.3 billion. This is recurring, subscription-driven revenue with improving unit economics across consumer, enterprise, government, maritime, and aviation verticals.
The launch segment tells a different story. Q2 2026 launch revenue came in below $1 billion, and the segment posted an operating loss as investment in Starship and next-generation systems continues to absorb capital.
| Metric | Starlink / Connectivity | Launch |
|---|---|---|
| Q2 2026 revenue | Nearly $4.3 billion | Below $1 billion |
| Revenue trajectory | Up 66% YoY; 2025 full-year $11.4 billion | Subscale; investment phase |
| Profitability | Profitable; ~120% operating income growth in 2025 | Operating loss |
Starlink’s economics give investors something concrete to anchor a valuation on. The launch business requires a belief in future strategic payoff that the current numbers cannot yet support. Both may prove valuable over a long enough horizon, but only one is generating durable, improving-margin revenue today.
What $15.8 billion of AI spending actually buys, and what it does not yet prove
The first-half 2026 capital expenditure total of $18.36 billion breaks down in a striking way: $15.8 billion flowed into the AI division alone, making it the dominant destination for the company’s investment budget. That single figure explains both the excitement and the anxiety around SpaceX as a public company.
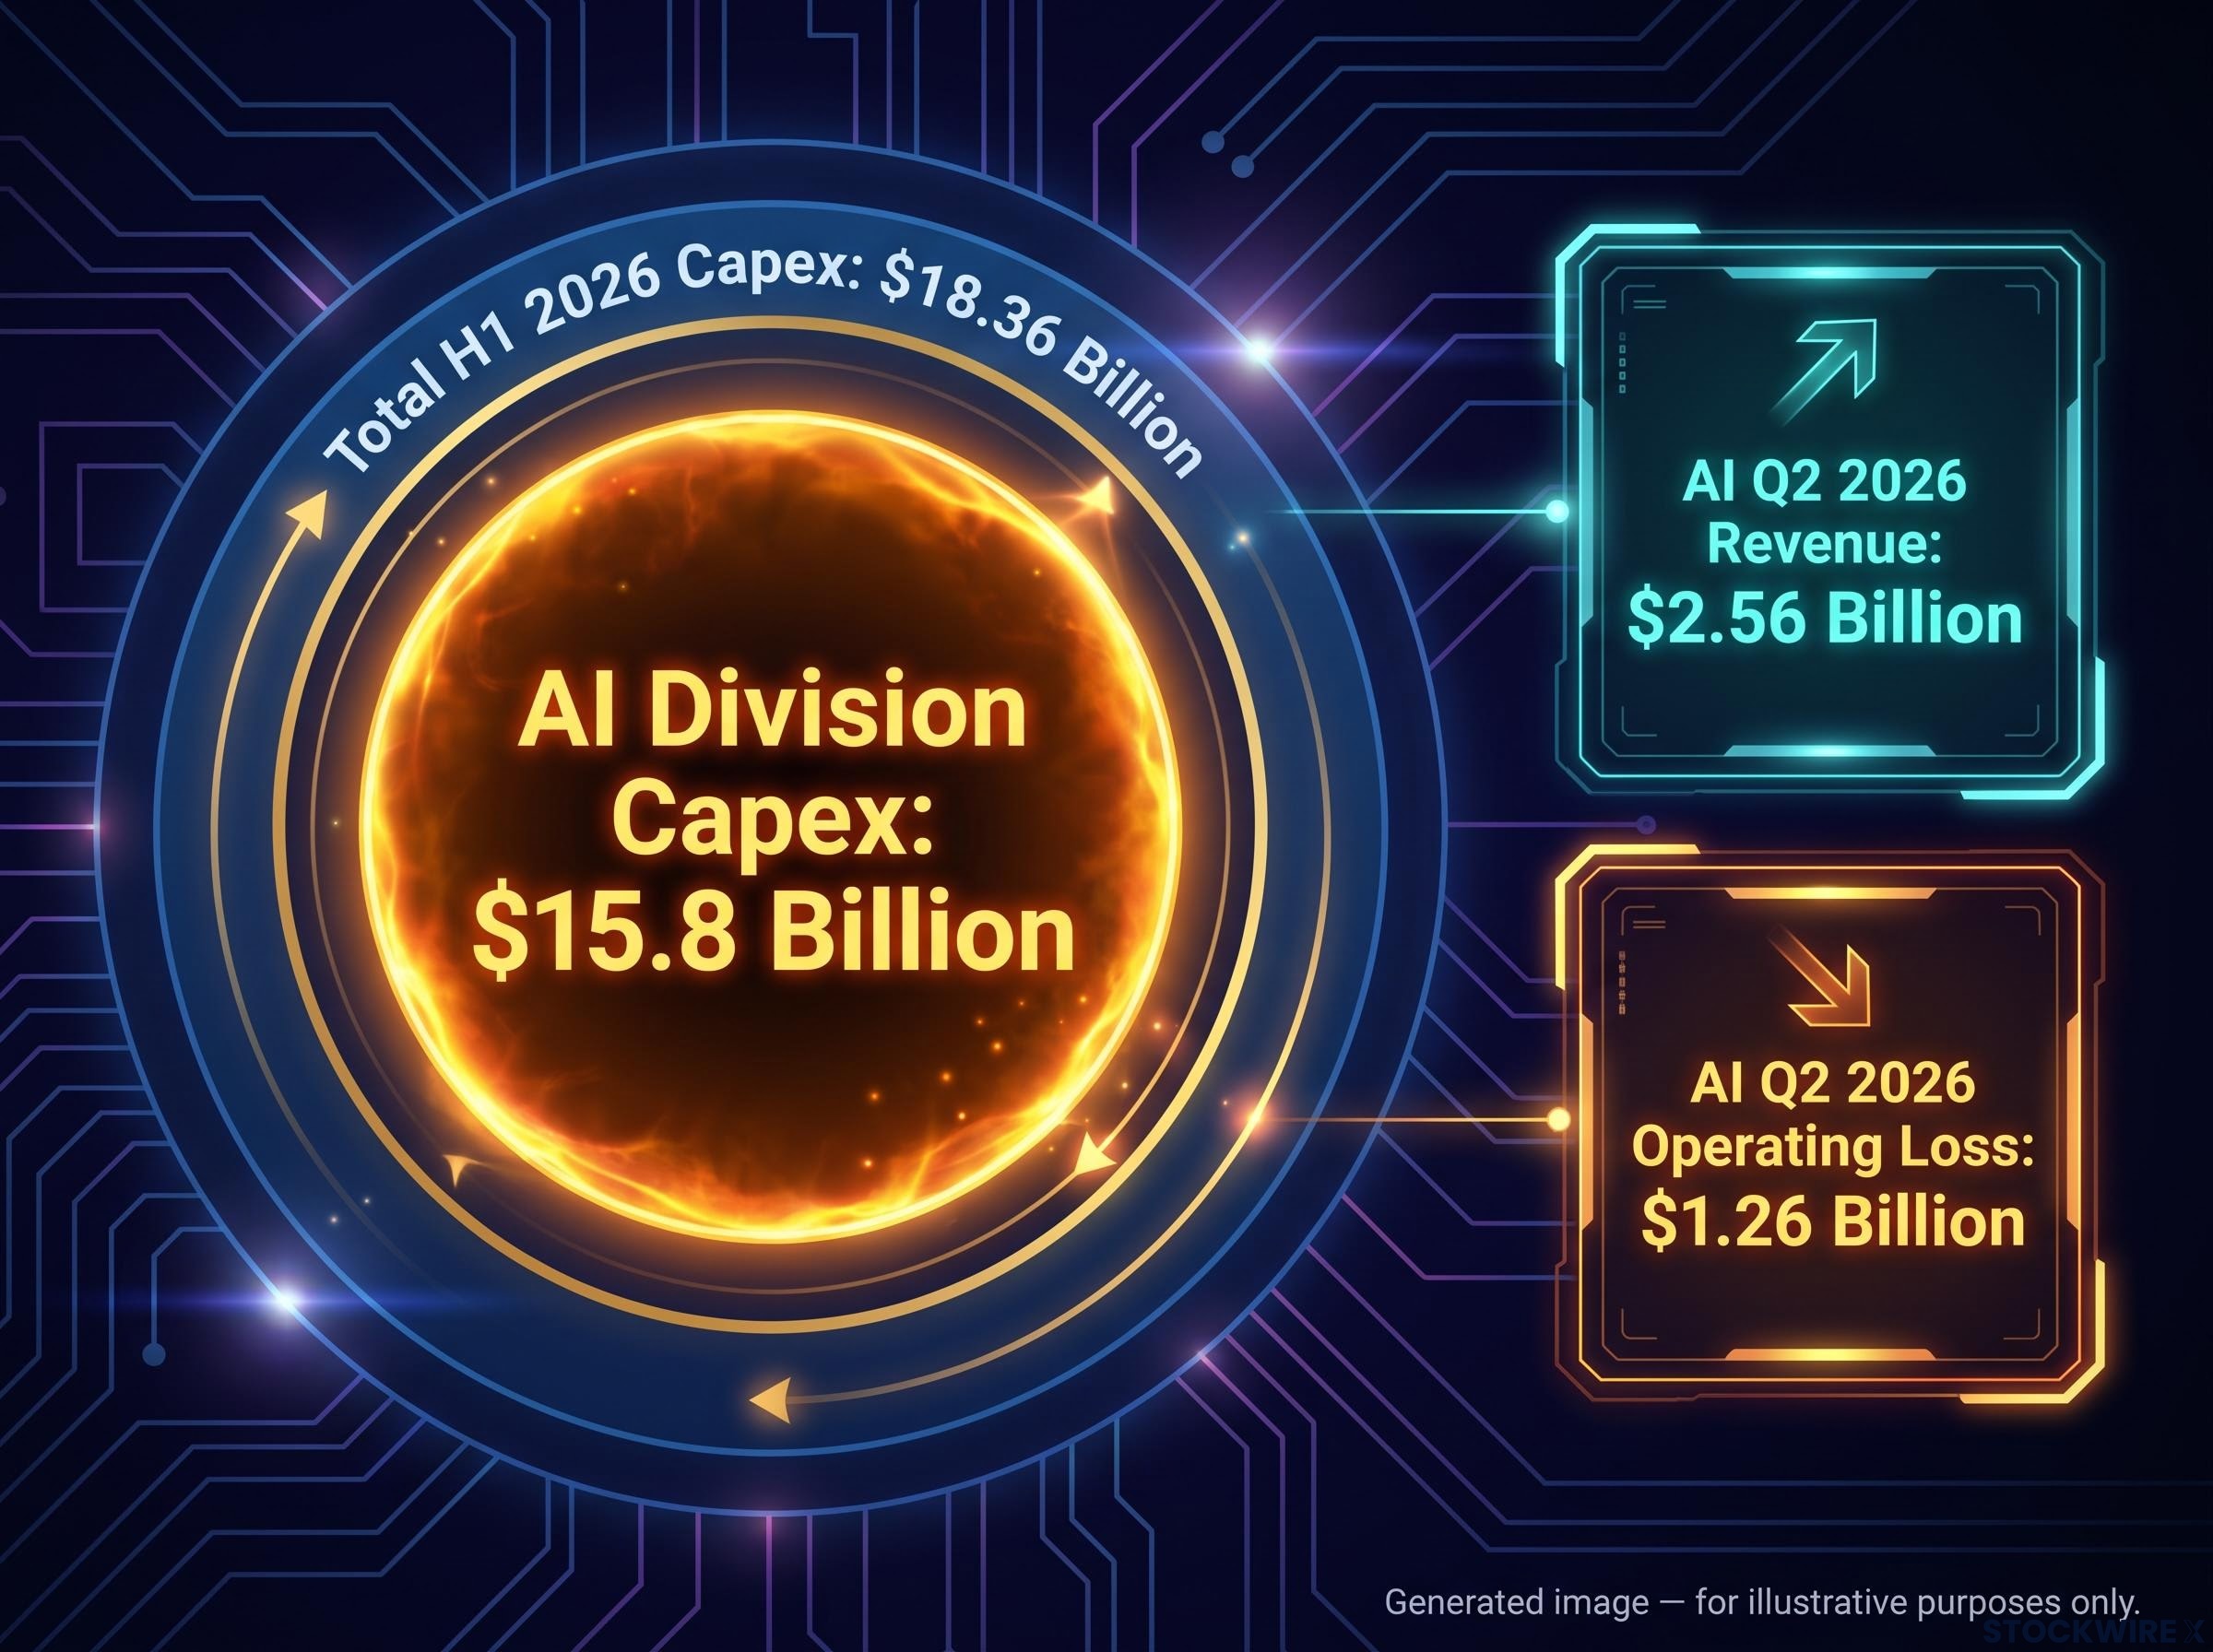
The AI division generated approximately $2.56 billion in Q2 revenue, a sharp acceleration from $818 million in Q1. But it also posted an operating loss of $1.26 billion in the quarter. The ratio of spending to revenue tells you this is not a division scaling a working model. It is a division making a structural bet on a future market, and the investor’s job is to decide whether the bet is sized appropriately.
Musk has put a concrete shape to those ambitions, pointing to orbital data centres potentially launching as early as 2027 and setting out a long-term revenue aspiration of $1 trillion. These are forward-looking aspirations, not financial commitments.
AI infrastructure investment of the scale SpaceX is committing, $15.8 billion in a single half-year, maps closely onto the binding-constraint thesis that power availability and cooling density, rather than chip performance alone, determine which operators can actually deploy at the required density and speed.
Vital Knowledge described the cash flow profile as “problematic,” even while acknowledging the strength of the underlying revenue and EBITDA figures.
Bull case, bear case, and what the data cannot yet tell you
- The bull case: Early, large-scale AI infrastructure investment builds capacity advantages that compound over time. SpaceX’s integrated connectivity-and-compute offering, linking its satellite network with AI processing, could differentiate it from traditional cloud providers in ways that justify the front-loaded spending.
- The bear case: The monetisation timeline is opaque. If AI revenue ramps more slowly than anticipated, the capital already deployed becomes sunk cost rather than competitive moat. With only a few quarters of public data, modelling a precise return-on-investment timeline is essentially guesswork.
- The unresolved question: The ratio of AI revenue growth to AI capex growth over the next two to three quarters will begin to answer whether the spending is building a platform or burning capital. That is the single most important variable in the entire earnings story.
Why SpaceX told Nvidia yes and AMD no, and what that signal means
Alongside the earnings release, Musk announced that SpaceX would commit entirely to Nvidia’s Blackwell AI server architecture, reversing an earlier position under which both Nvidia and AMD had been expected to supply processors to SpaceX and Tesla. The decision turned a strong quarter for AMD into a difficult after-hours session.
AMD’s own Q2 2026 results were, by any normal measure, excellent:
- Total revenue: $11.5 billion, marginally above consensus
- Data centre revenue: a record $6.7 billion, up from 42% to 58% of total sales year-over-year
- Fifth consecutive quarter of record chip sales
- After-hours reaction: shares fell, despite a 7% gain in the regular session
The irony is sharp. AMD delivered record results and the market punished it, not because of anything in its own financials, but because a single large buyer made an ecosystem lock-in decision that favoured a competitor.
That reaction tells you something about the current AI infrastructure cycle. Ecosystem alignment decisions made by one major buyer can matter more to a chipmaker’s sentiment than its own record-breaking revenue quarter. For anyone with exposure to the chip sector, the SpaceX–Nvidia exclusivity deal is a live case study in how competitive concentration plays out when capital commitments of this scale are being made.
AI chip competition increasingly concentrates around ecosystem lock-in rather than pure performance metrics, and SpaceX’s decision to commit exclusively to Nvidia’s Blackwell architecture illustrates precisely the dynamic that makes large buyer commitments so strategically consequential: a single capital allocation choice by one major customer can reshape competitive positioning across an entire supply chain.
Decoding the gap between adjusted profit and free cash flow
This is the section of the earnings report that matters most for understanding why the stock sold off, and it requires a clear-eyed look at what different profit metrics actually measure.
SpaceX reported $3.5 billion in adjusted Q2 profit and $6.6 billion in 2025 adjusted EBITDA (earnings before interest, taxes, depreciation, and amortisation, a measure of operating cash generation before accounting for capital investment and financing costs). These figures reflect genuine operating strength, particularly in the connectivity business.
The GAAP picture, which applies standard accounting rules to the full cost structure, looks starkly different. SpaceX posted a $541 million net loss in Q2 2026, itself a significant improvement from a $4.3 billion net loss in Q1. Free cash flow, the residual cash remaining once the company has met its operating costs and funded its capital investments, was firmly in negative territory.
| Metric | Value | What it reflects |
|---|---|---|
| Adjusted Q2 profit | $3.5 billion | Operating business strength (excludes major investment costs) |
| Q2 GAAP net loss | $541 million | Full accounting cost including depreciation and non-cash charges |
| Q1 GAAP net loss | ~$4.3 billion | Heavy AI ramp-up costs in the prior quarter |
| H1 2026 capex | $18.36 billion | Cash spent on infrastructure (primarily AI) |
| Free cash flow | Deeply negative | Capex overwhelming operating cash generation |
Why can adjusted profit and free cash flow diverge so sharply? Because capital expenditure, the cash the company spends building infrastructure, is not subtracted from adjusted profit metrics. It is, however, the primary driver of free cash flow. The adjusted figure tells you the operating businesses are working. The free cash flow figure tells you the company is spending that and vastly more on infrastructure that does not yet earn its cost of capital. That tension is exactly what sent the stock down.
Three variables that will determine whether this selloff was a buying opportunity or a warning
The after-hours decline is a question the market is asking, not a verdict it has reached. The answer depends on how three specific variables evolve over the next two to three quarters.
- AI revenue trajectory. The acceleration from $818 million in Q1 to $2.56 billion in Q2 is the single most important data point in the earnings report. Whether that pace continues, and whether the $1.26 billion quarterly operating loss begins to narrow, will determine whether investors treat the AI division as a scaling business or an open-ended cost centre. Musk’s orbital data centre timeline of 2027 provides a concrete milestone to watch.
- Capex discipline. Confirmed first-half capex of $18.36 billion is already enormous, and some analyst estimates place full-year spending above $45 billion (though this figure is unverified). If capex growth moderates as AI revenue rises, the bull case gains traction. If spending continues accelerating without commensurate revenue growth, the bear case strengthens materially.
- Balance sheet and financing. How SpaceX funds continued heavy investment, whether through debt, equity issuance, or operating cash flow, will determine dilution risk and financial flexibility. Management commentary on financing strategy in coming quarters deserves close attention, as does any secondary indicator like Starlink subscriber churn and margin trends that might signal stress in the core business.
These three variables give you a testable framework. If the next two quarters show AI revenue accelerating while capex growth moderates, the current selloff starts to look like a dislocation. If capex stays elevated without a revenue ramp, the market’s concern deepens into something more structural.
For investors wanting to place SpaceX’s capex decisions inside the broader capital cycle, our deep-dive into the AI investment cycle examines how combined hyperscaler commitments compare to every prior technology investment peak and where Goldman Sachs projects ROI will begin to emerge meaningfully.
What this earnings report actually changes about how you read SpaceX
The debut earnings report has clarified the terms of the SpaceX investment case without resolving it.
The operating business quality is real. Starlink posted nearly $4.3 billion in quarterly connectivity revenue, supported by a subscriber base that doubled year-over-year and margins that continued to improve. Adjusted profit of $3.5 billion confirms that the core business works. The 92% year-over-year revenue growth rate is not an accounting artefact.
The AI spending pace is equally real. $15.8 billion of first-half capex concentrated in a single division, against $2.56 billion of quarterly AI revenue and a $1.26 billion operating loss, shows a company that has chosen to prioritise future platform dominance over near-term cash generation. Deeply negative free cash flow is the financial consequence of that choice.
The investor’s actual question is not whether SpaceX is a good business. It is whether the current valuation already embeds enough of the optimistic AI scenario to justify holding through a period of sustained cash burn, or whether Musk’s $1 trillion revenue ambition is priced in before the infrastructure it requires has been built, let alone monetised.
The priced-in optionality embedded in SpaceX’s valuation was already a central tension before the first earnings report landed: analysts estimated approximately $1.8 trillion of the IPO price reflected future ambitions rather than current fundamental value, a gap that the Q2 data has done little to narrow.
Short-horizon investors face elevated free cash flow risk until AI spending and revenue trends converge. Long-horizon investors are making a platform bet, accepting near-term volatility and potential dilution in exchange for the possibility of outsized future earnings power. Knowing which investor you are is the first step in reading these numbers clearly.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. Forward-looking statements attributed to management are speculative and subject to change based on market developments and company performance.