The Federal Reserve held its benchmark rate at 3.75-4.00% last week, yet two policymakers voted to raise it. On 2 November, HSBC said its strongly bullish US dollar outlook remains intact, even as the dollar index slipped toward 101.4 that same day.
The timing gives the call extra weight. The Fed kept the door open to a hike in December, and inflation is running well above its 2% target. Even so, a Reuters poll of nearly 70 currency forecasters still expects the dollar to give back much of its recent rally over the next twelve months.
Here is what HSBC is betting on, where it parts ways with the broader consensus, and which events could knock its call off course.
Why does HSBC still expect a stronger dollar when the broader forecast pool does not?
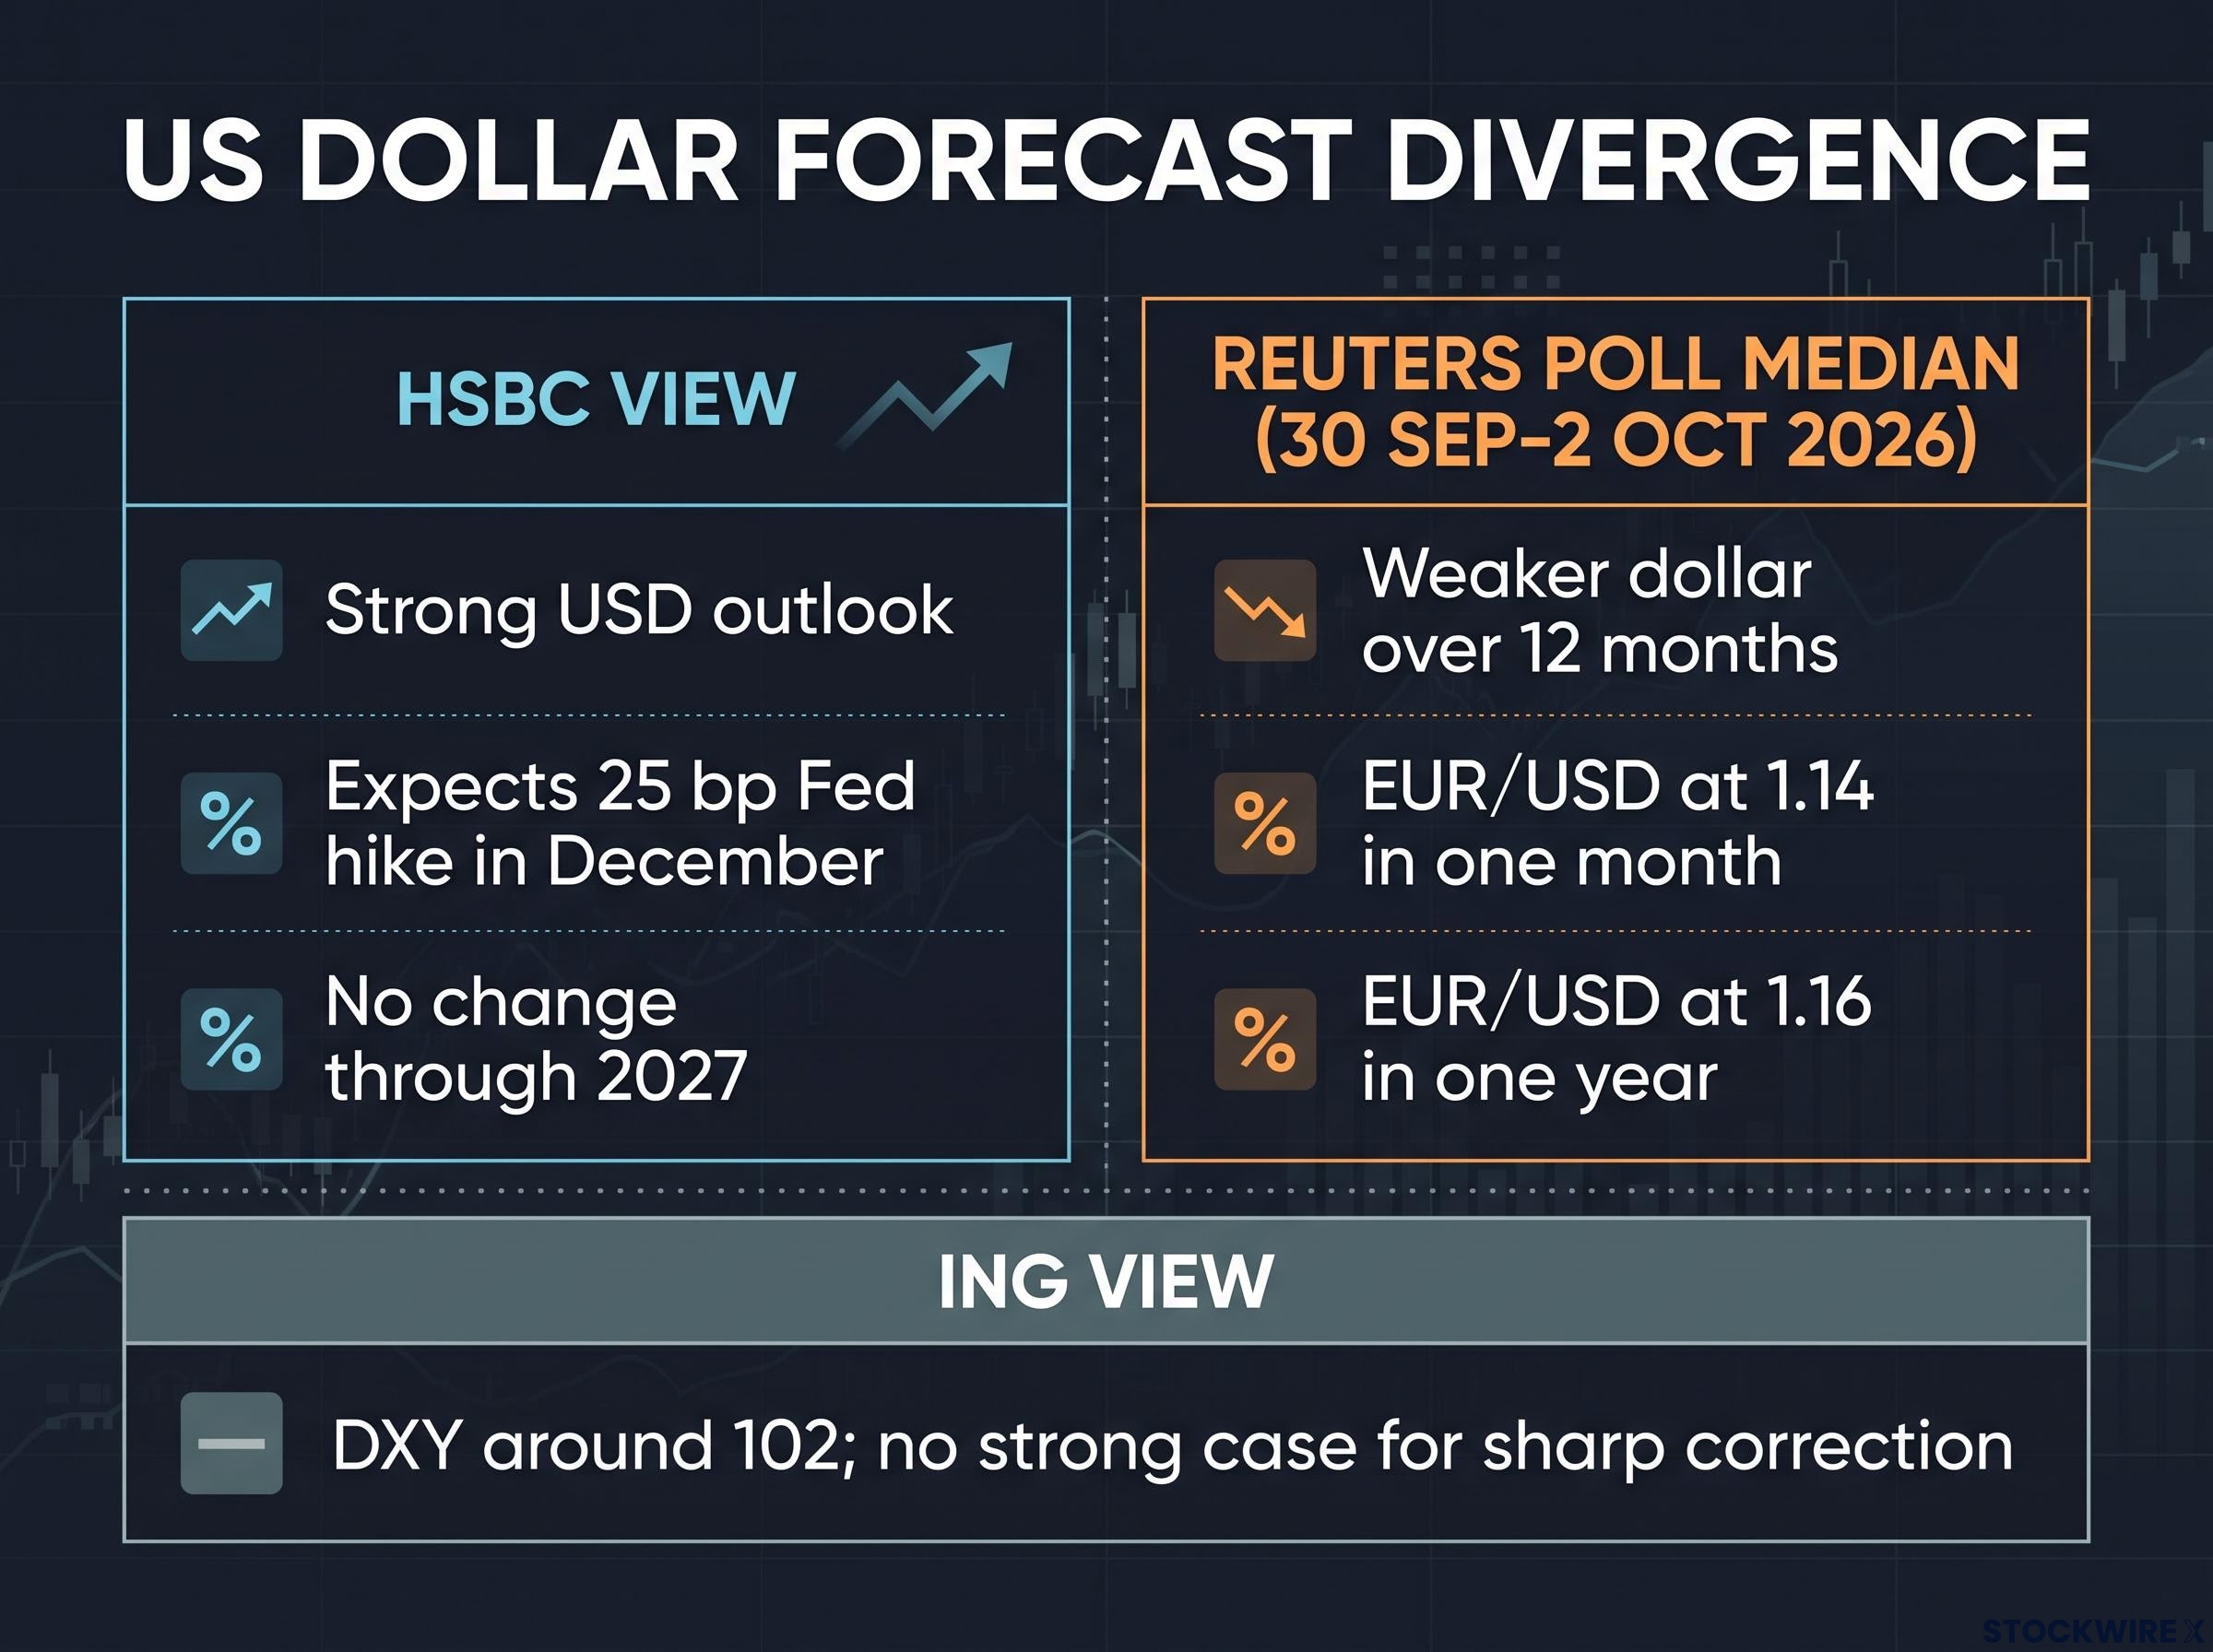
At first glance, the two views look like they contradict each other. In its 2 November FX Viewpoint, summarised by FXStreet, HSBC said it expects the dollar index (DXY) to consolidate near recent highs, with risks tilted toward further gains. The DXY measures the US dollar against a basket of major currencies.
The bank also expects a choppy run to year-end and an uneven path into 2027. It forecasts a 25 basis point Fed hike in December, then no change through 2027. A basis point is one hundredth of a percentage point.
The Reuters poll median points the other way. It expects EUR/USD at about 1.14 in one month and 1.16 in one year, which implies a weaker dollar.
The dollar’s 2026 rebound followed a roughly 9-10% slide across 2025, and valuation models now flag the index as stretched, which helps explain why many forecasters expect part of the rally to unwind over a twelve-month horizon.
The detail that changes the picture sits inside that same poll. 80% of respondents said the dollar was more likely to beat their three-month forecast than fall short of it.
| Source | Date | Position | Horizon |
|---|---|---|---|
| HSBC | 2 November 2026 | Strong USD view intact; risks tilted to further gains | Year-end into 2027 |
| ING (Chris Turner) | 2 November 2026 | DXY around 102; no strong case for a sharp correction | Near term |
| Reuters poll median | 30 Sep-2 Oct 2026 | Dollar to surrender much of its rally; EUR/USD 1.16 | 12 months |
Paul Mackel, HSBC’s global head of FX research, told Reuters last month that dollar strength should persist at least through the first half of 2027.
“Cleanest dirty shirt” Mackel’s description of the US dollar, reported by Reuters on 2 October 2026.
HSBC gave direction against the euro, sterling and yen but no new numerical forecast table. Most of the disagreement comes down to timing. A bullish call and a bearish call can both prove right, depending on whether you are looking weeks ahead or a full year out.
What are the three pillars behind the call, and what did the Fed’s hold add?
What the Fed’s October statement left open
On 28 October, the Fed held rates on a 10-2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack both wanted a 25 basis point hike. Cook’s dissent stood out because she favoured tightening while President Donald Trump has been pushing for her removal.
The Fed’s first rate hike in three years ended a long pause in September, and its effects on equity valuations, bond duration and credit exposure are still working through portfolios.
The statement described economic activity as expanding at a “strong pace” and said inflation “remains elevated”. It added that the Committee would weigh the “extent and timing” of any further moves. That stopped short of a commitment, but it left December open.
HSBC’s case rests on three pillars:
- A resilient US economy. Real GDP grew 3.4% annualised in Q3 2026, up from 2.2% in Q2, according to the Bureau of Economic Analysis.
- A Fed leaning hawkish. Headline PCE inflation, the Fed’s preferred price gauge, rose to 3.6% in September. Core PCE, which excludes food and energy, reached 3.1%. Jobless claims came in at 194,000 for the week ended 24 October, below the 200,000 forecast.
- Weakness elsewhere. France’s credit outlook was revised on 2 November. USD/JPY sat near 157.95 amid Bank of Japan uncertainty, and sterling remains exposed to fiscal and growth worries.
HSBC also argues the dollar is less exposed to high energy prices than its peers. The logic is relative: the dollar can outperform even if the Fed tightens less than expected, provided other central banks deliver even less. That means you should watch European, Japanese and UK policy signals as closely as US data.
What could make the path choppy into 2027?
The same strong backdrop did not stop the dollar from sliding on 2 November. The DXY touched a one-month low of 101.426, EUR/USD reached about 1.1237 and GBP/USD climbed to about 1.3449, according to Barron’s. Standard Chartered described the index as broadly rangebound near 102 as the US midterm elections approached.
Strong data tends to lift the dollar by raising expectations for Fed rates. Intervention talk, weak payrolls or political shocks can push it back down just as quickly.
Rising Treasury yields can also be read as a fiscal risk premium rather than a draw for investors, which inverts the usual yield-strength link and is one reason the dollar can slip even when US data stays firm.
| Risk | How it could hit the dollar | Direction |
|---|---|---|
| Hawkish pricing | Markets priced about 85 bp of hikes by October 2027; HSBC Economics expects one more 25 bp | Weaker |
| Japanese intervention | Action near 158 could trigger abrupt yen strength | Weaker |
| Fiscal and Treasury concerns | Deficits and debt costs could damage confidence in US assets | Volatile |
| Fed independence | Pressure on Cook could raise risk premiums | Volatile |
| Stronger global recovery | Firmer peer growth or tightening narrows the US yield advantage | Weaker |
Institutional currency forecasts typically draw on a common set of inputs:
- Central bank policy paths and yield differentials
- Relative growth, inflation and fiscal credibility
- Political risk and investor positioning
The 2022 rally offers a useful parallel. That move advanced in bursts around data releases and Fed meetings, then reversed quickly once expectations shifted, though today’s setup is less extreme. A durable thesis does not remove event risk, so when you act around Fed meetings, data releases and intervention signals matters as much as which direction you expect.
What to watch before the December FOMC and into 2027
HSBC’s call is a bet on relative strength with a bumpy route, not a promise of a smooth rally. The bank expects a 25 basis point hike in December and then a hold through 2027. The Reuters poll median, by contrast, expects the dollar to ease over the next year, so that gap is worth tracking in its own right.
The catalysts are already on the calendar: the US midterm elections, the next round of inflation and jobs data, any Japanese signals around 158 on USD/JPY, and the December Fed decision. Each one will test which horizon wins out.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
These statements are speculative and subject to change based on market developments and company performance.