Most attention on self-managed super went to the familiar names at the top of the table, and those names barely moved. The real signal in Class’s 2026 benchmark data sat one rung lower. Vanguard All-World ex-US Shares Index ETF (VEU), a fund that has trailed US-heavy benchmarks for a decade, climbed to fifth among the ETFs held by SMSFs.
That shift is easy to miss. VAS, IVV, QUAL and VGS stayed in their usual spots, so a quick glance suggested nothing had changed.
A self-managed super fund (SMSF) is a super fund where the members act as trustees and make their own investment decisions. SMSFs collectively hold about $1.107 trillion, and 35.5% of funds on the Class platform now hold at least one exchange-traded fund (ETF), a fund that trades on the ASX like a share.
How large-balance trustees build portfolios is worth studying, even though a big balance is not proof of skill. Here is what VEU’s climb tells you about ex-US exposure, what it does not tell you, and what to weigh before you act on it in your own fund.
What the Class 2026 data shows about SMSF ETF holdings
Start with what stayed put. Class released its 2026 Annual Benchmark Report in mid-September, drawing on funds administered on its platform, which covers about 30% of the SMSF market. The report spans FY26, the 12 months to 30 June 2026.
The sector itself kept growing. There were 680,301 SMSFs at 30 June 2026, and 52,020 new funds were set up in FY26, the highest annual figure on record. The average balance sits just under $2 million, and SMSFs account for roughly 25% of all super assets.
ETFs make up 7.2% of total assets on the platform. Among funds that hold ETFs, the most widely held were:
- VAS: Vanguard Australian Shares Index ETF, the local share market core
- IVV: iShares S&P 500 ETF, direct US large-cap exposure
- QUAL: VanEck MSCI International Quality ETF, a quality-screened global fund
- VGS: Vanguard MSCI Index International Shares ETF, developed markets including the US
- VEU: Vanguard All-World ex-US Shares Index ETF, held by about 10.3% of SMSFs with ETFs
- NDQ: Betashares Nasdaq 100 ETF, a US technology-heavy growth fund
Four of the top five are unchanged in character. VEU is the one genuine movement, and it arrived while demand for US-focused products like IVV and NDQ held firm.
That matters for how you read it. Trustees do not appear to be leaving the US; they appear to be widening their exposure around it.
ATO data on SMSF offshore exposure shows the average fund holds only about 3% overseas against 38% for large professional funds, which puts the interest in ex-US building blocks in context.
How to read a popularity ranking
The original analysis behind the data carried a clear warning worth repeating.
A caution on copying A large portfolio does not prove investing skill. The holdings of wealthy, long-term trustees show how portfolios are being built today, not where those investors expect markets to go.
So treat the ranking as a portfolio-design signal. Trustees are layering an ex-US building block over existing Australian and US holdings, and you can judge that choice on its merits for your own fund without assuming it is a forecast.
When big ASX news breaks, our subscribers know first
What is inside VEU, and what does the 0.04% fee buy?
In plain terms, VEU is a single fund that holds thousands of large and mid-sized companies from every major share market except the United States. If you already own Australian and US shares, it covers most of what is left.
How the index works
VEU tracks the FTSE All-World ex-US Index, which spans developed and emerging markets outside the US. The index uses free-float market-cap weighting, meaning each company’s weight depends on the value of its shares available for public trading, so bigger companies get bigger slices. It aims to capture roughly the top 86% of the investable market outside the US.
The fund itself is US-domiciled, meaning it is legally based in the US. Australians buy it on the ASX through CHESS Depositary Interests, which are units that represent ownership of the underlying foreign-listed fund.
The key fund facts, according to Vanguard and Morningstar data:
- Management cost of 0.04% a year, against a category median of about 0.68%
- Fund size of about $6.2 billion at 31 August 2026
- Roughly 3,856 holdings
- Annual turnover of about 5%, well below peers
- Morningstar Medalist Rating of Bronze, with quarterly distributions and no dividend reinvestment plan in the Australian wrapper
Low turnover keeps trading costs down and helps tax efficiency. Most holdings sit under 2%, with Taiwan Semiconductor Manufacturing the exception at about 4.4%.
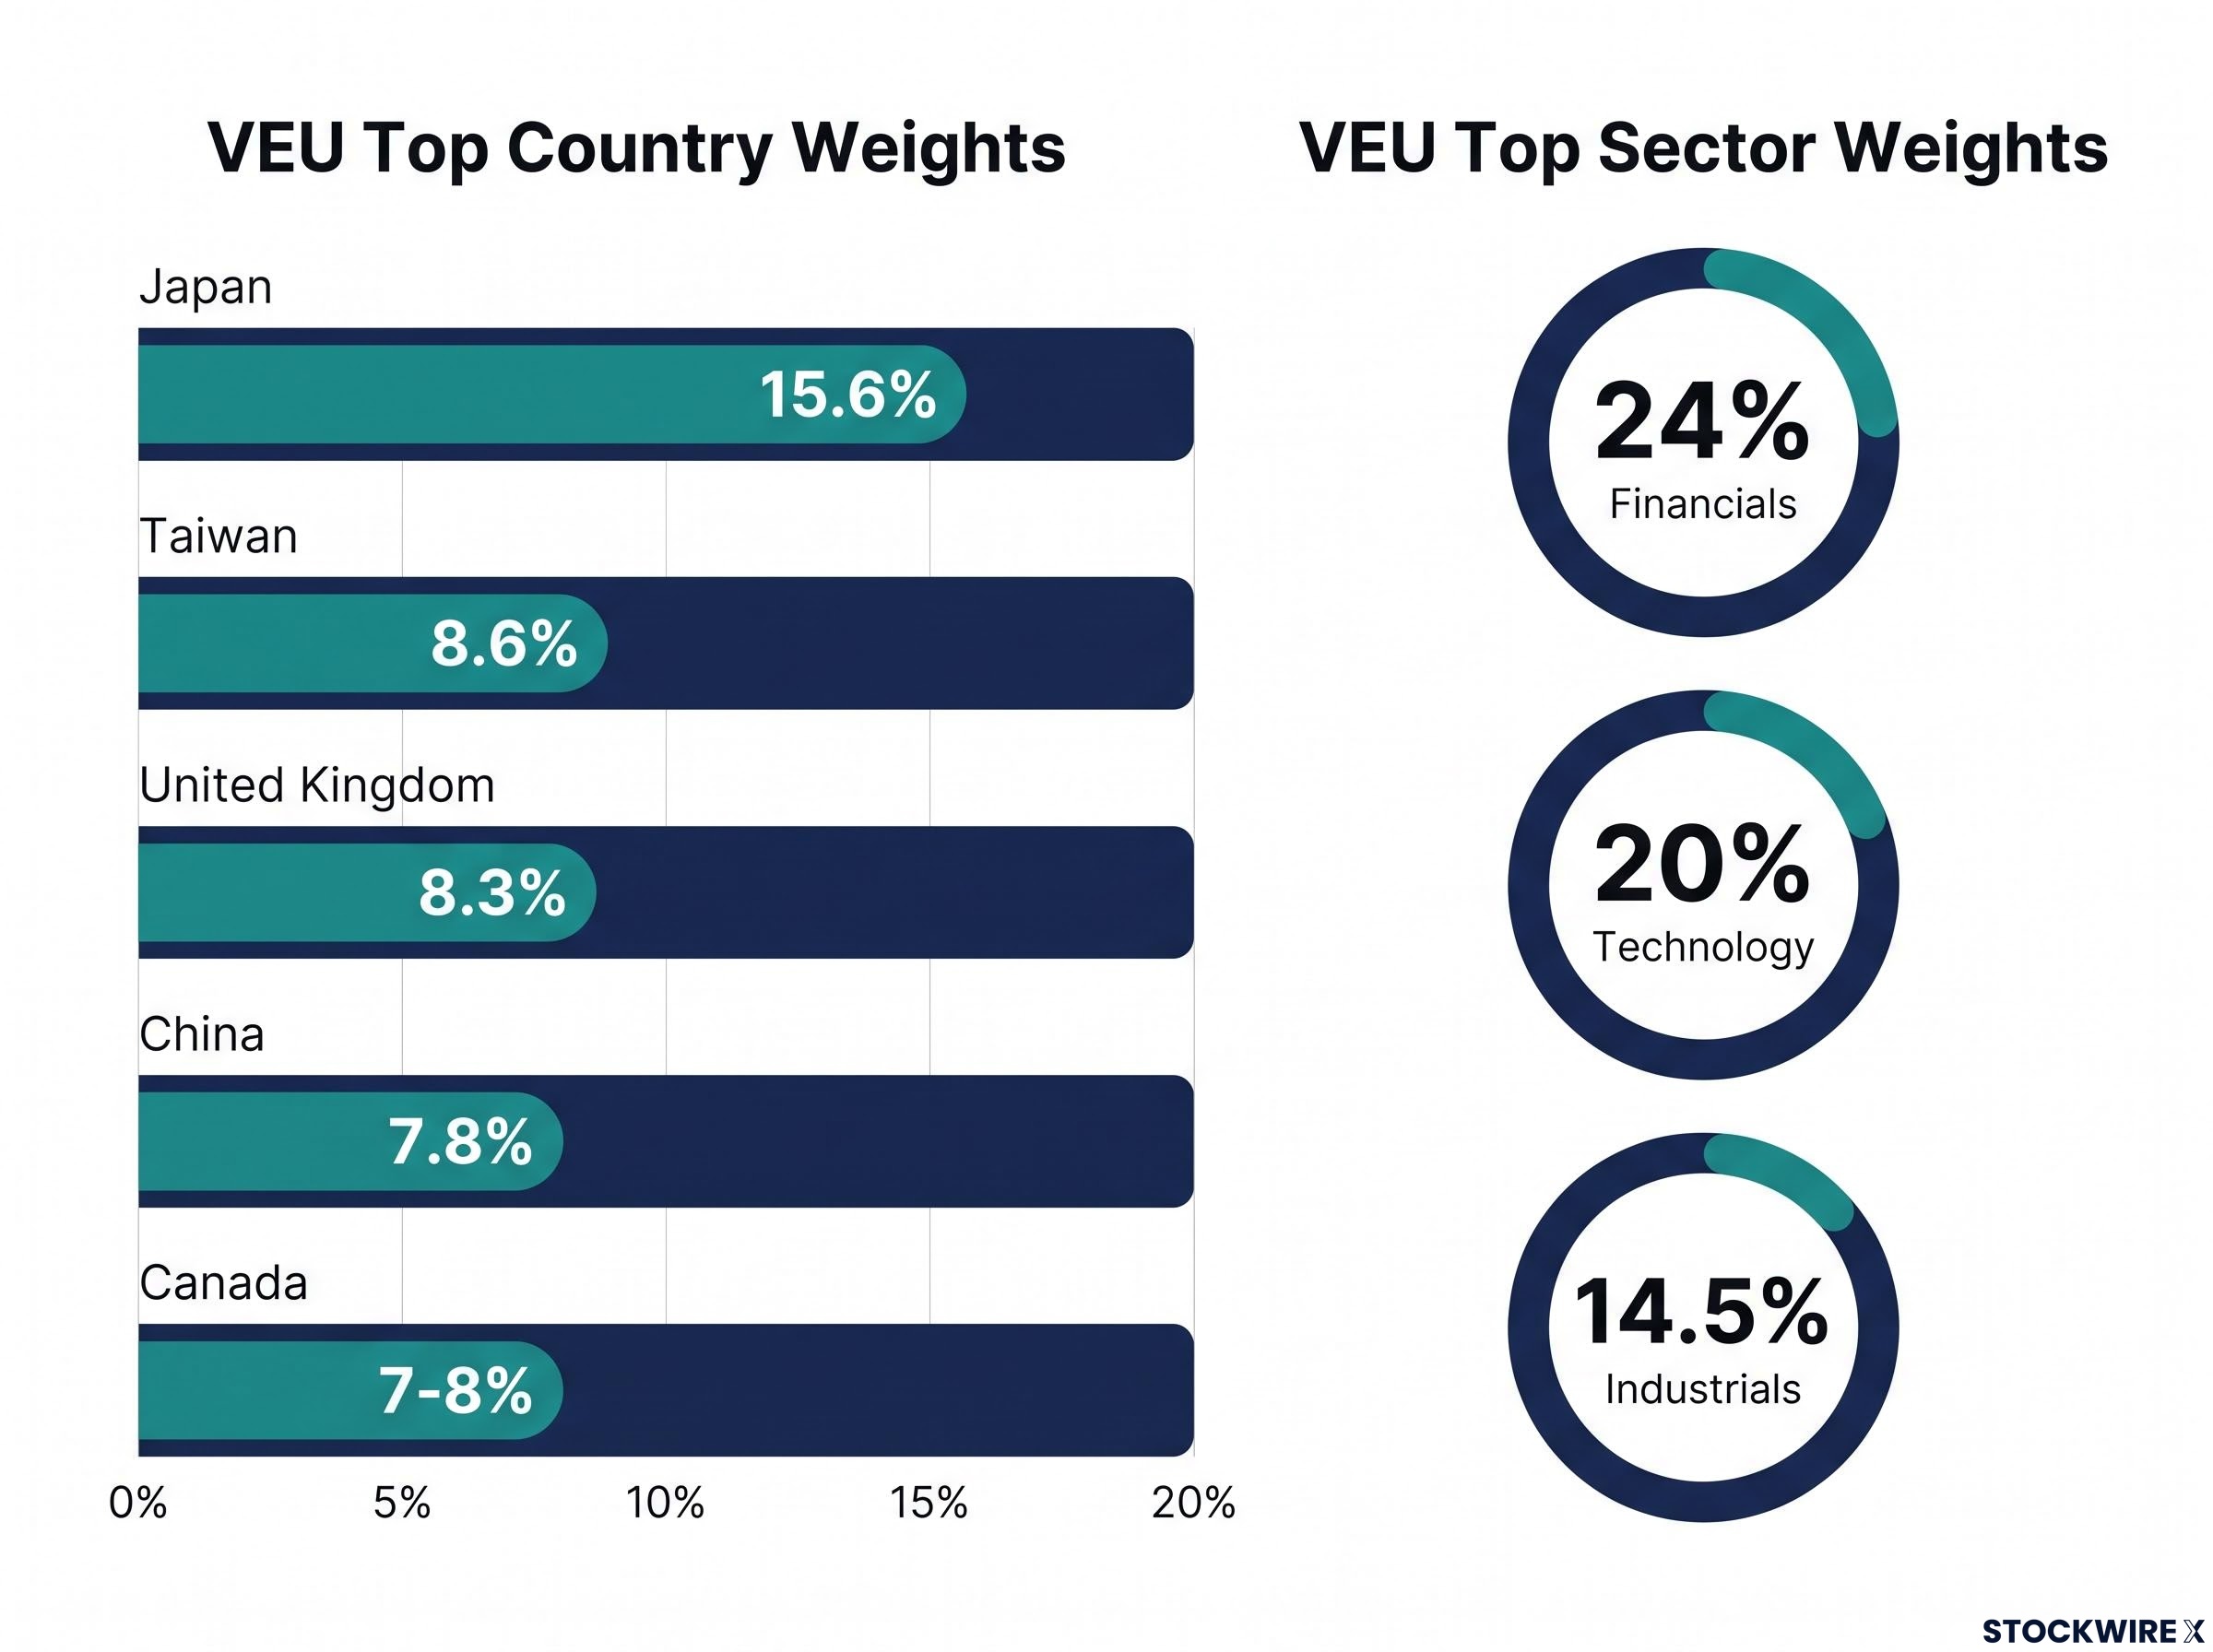
| Country | Approximate weight | Note |
|---|---|---|
| Japan | 15.6% | Largest single country |
| Taiwan | 8.6% | Driven heavily by TSMC |
| United Kingdom | 8.3% | Largest European weight |
| China | 7.8% | Emerging market exposure |
| Canada | 7-8% | Resources and banks |
By sector, financials lead at 24%, followed by technology at 20% and industrials at about 14.5%. That is a very different tilt from a US-heavy fund dominated by mega-cap technology.
How VEU differs from peers
According to Morningstar, US shares made up about 44% of the average fund in VEU’s category and about 74% of the category index as of September 2026. VEU holds none.
Australia carries only about 4.2% of the fund, so overlap with your local holdings is small. The low fee is a genuine advantage, but it is not the reason to buy. What you are really choosing is a regional and sector mix that a second global fund would not give you.
Your international share allocation matters because Australia is only about 2% of global market capitalisation, so an ASX-heavy portfolio leaves most of the world’s listed companies outside your fund.
Why add ex-US exposure when the last decade favoured the US?
Start with the number that makes most people hesitate. Over the ten years to 30 September 2026, VEU returned about 10.38% a year, while the MSCI World ex Australia Index returned about 13.99% a year.
| Measure | VEU | Benchmark | Note |
|---|---|---|---|
| 10-year return p.a. to 30 Sep 2026 | 10.38% | 13.99% | Later research puts the benchmark near 13.6% |
| US shares included | No | Yes | Explains most of the gap |
| Management cost | 0.04% | Not applicable | Category median about 0.68% |
Either way, the gap is roughly 3.3-3.6 percentage points a year. That is a long stretch of trailing.
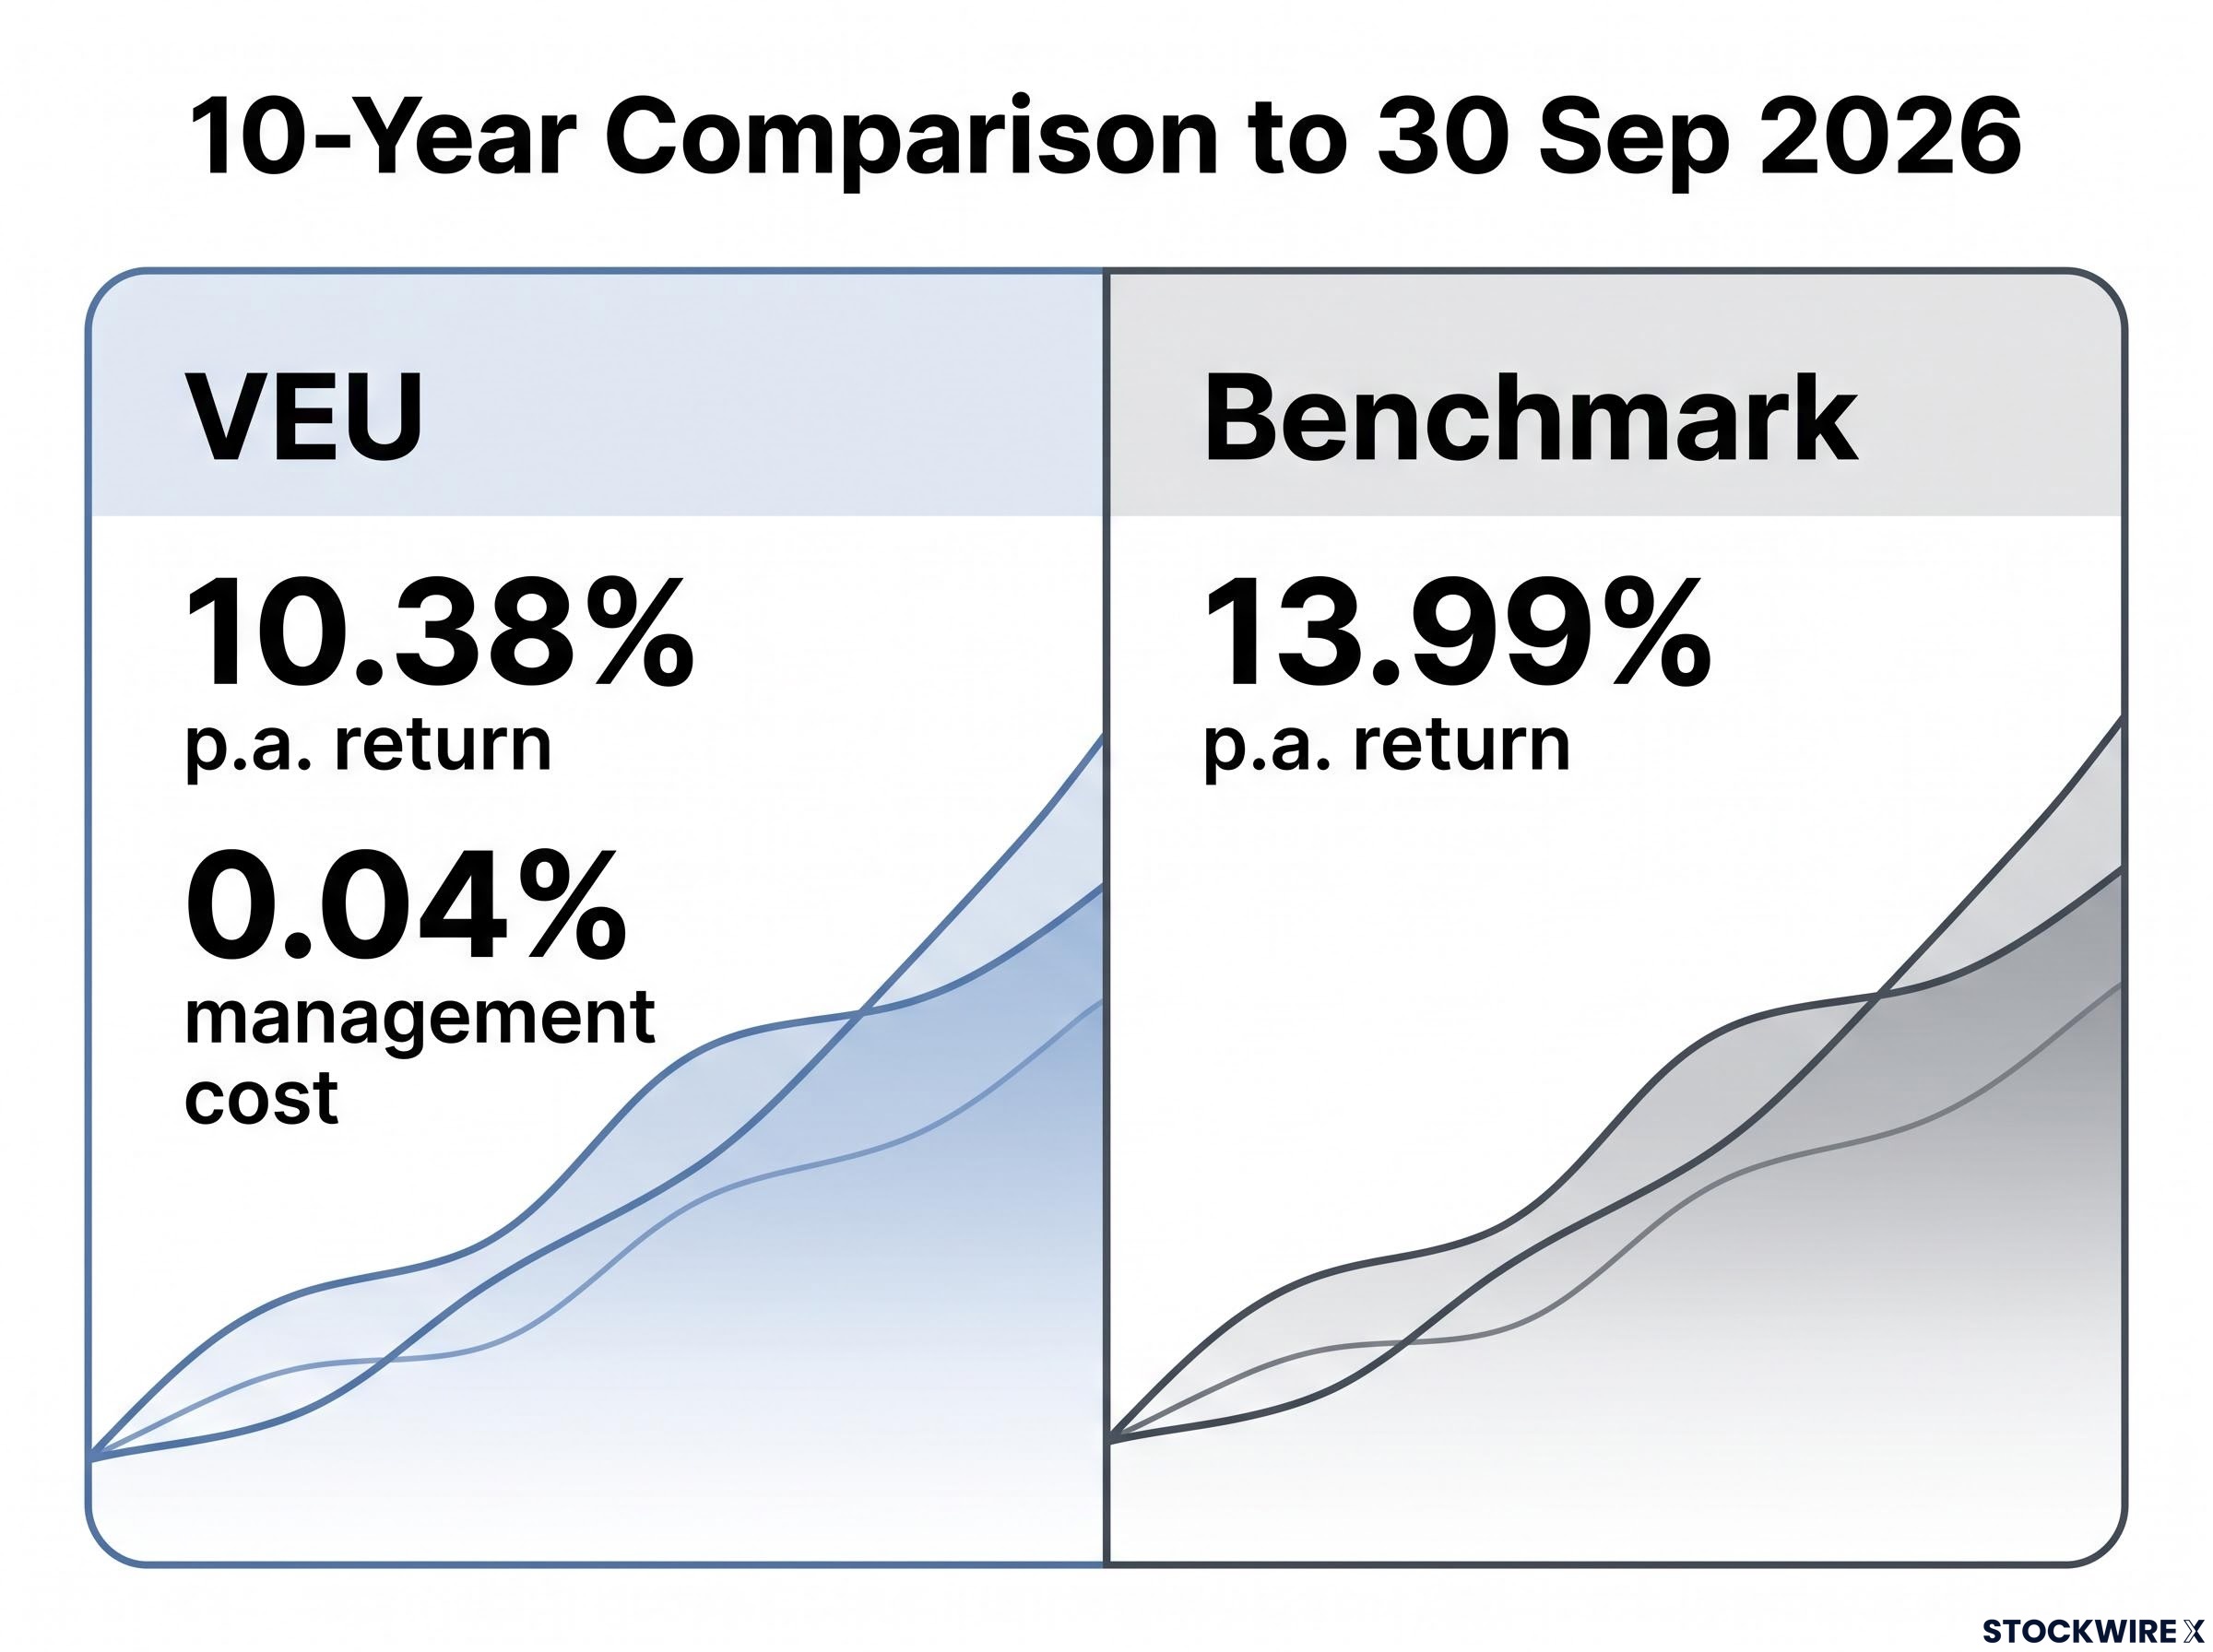
The comparison is not like-for-like, though. The benchmark includes the US and VEU does not, so the gap mostly measures what US shares delivered over the decade.
The Morningstar view A Morningstar analyst attributes VEU’s underperformance mainly to missing US market returns, describing it as a feature of the strategy rather than a flaw.
There is also a recent counterpoint. During the tariff-driven volatility of early 2025, VEU fell less than its category index.
The recent counterpoint is part of a wider pattern of international equities outperforming US markets in 2026, driven by emerging market and AI semiconductor gains in Korea and Taiwan.
Commentators genuinely disagree about what comes next:
- The case for: a handful of US mega-cap technology firms now dominate global indices, so a “global” fund can leave you heavily exposed to a few stocks, the US dollar and US regulation. Ex-US markets offer valuation discounts, more financials and industrials, and different currencies and policy cycles. Some see US leadership as cyclical and expect it to revert.
- The case against: others argue US advantages in technology, profitability and capital markets are structural, and that cheaper ex-US prices partly reflect real headwinds in Europe and some emerging markets. Weaker foreign currencies could also erode returns in Australian dollars. And because many Australians are already underweight international shares, cutting out the US alone may not improve your diversification.
The gap tells you what you are signing up for. Adding VEU is a bet on diversification, not on recent winners, so the real question is whether you can hold it through the years when it trails.
Past performance does not guarantee future results, and any view on future returns is speculative.
US domicile, tax and the limits of copying wealthy investors
The 0.04% fee is only part of the cost of owning VEU. Because the fund is based in the US, it brings paperwork and tax issues that an Australian-domiciled fund such as VGS does not.
Withholding tax and paperwork
The US withholds tax on dividends paid to foreign investors at a default rate of 30%. The Australia-US tax treaty cuts that to 15% if you lodge a valid W-8BEN form, or a W-8BEN-E for entities such as an SMSF.
You give the form to your broker, not the ATO. It stays valid until the end of the third calendar year after signing. You still need to report the foreign income and claim any foreign income tax offset through your normal ATO processes.
Estate tax for larger balances
US-domiciled ETFs are generally treated as US-situs assets, meaning US estate tax rules can apply to them. The exemption for non-residents starts at about US$60,000, although the Australia-US estate tax treaty may allow a prorated larger exemption.
That exposure matters most for large balances held through individual trustees. Many advisers suggest comparing Australian-domiciled alternatives for this reason.
Why copying popular holdings can backfire
Each popular fund plays a different role: VAS for the Australian core and franking credits, IVV for the S&P 500, VGS for developed markets including the US, and VEU as an explicit ex-US layer. Buying all of them because they top a list can leave you overweight growth and underweight defensive assets.
Emerging market and China exposure also adds volatility and governance risk that may not suit conservative trustees. Your fund must have an investment strategy that reflects your own circumstances and risk profile, and a leaderboard cannot write it for you.
Before adding VEU, work through these steps:
- Check that it fits your written investment strategy
- Map your existing international overlap from IVV, VGS or other funds
- Lodge a W-8BEN-E with your broker
- Review your potential US estate tax exposure
- Compare Australian-domiciled alternatives
Confirm your tax position with an accountant or adviser before buying, because the true cost of ownership differs between trustees.
Widening the map, not leaving it: what VEU’s climb does and does not settle
The most plausible reading of the Class data is that trustees are widening exposure around an existing Australian and US core. They are not abandoning the US, and the ranking is not a forecast of its decline.
The trade-off is plain. You get a very low fee and broader regional and sector diversification. In exchange, you accept a decade of lagging returns and extra tax and domicile complexity.
The useful question is not whether wealthy trustees own VEU. It is what gap in your own portfolio an ex-US allocation would fill, and whether you could hold it through long stretches of underperformance.
For readers deciding how to act, our deep-dive into investing overseas from Australia compares hedged and unhedged ETF outcomes and a tax-efficient framework for redirecting new savings offshore.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.