The gap between the United States and Mexico has narrowed to 250 basis points, its slimmest reading since 2015, and the peso is already telling you what that means. This is the compressed carry spread showing up in real prices, not a passing daily wobble.
The peso’s slide from its two-year high of 16.98 on 11 September 2026 to a near two-month peak of 17.50 reflects the unwinding of a position built on a far wider yield premium. The US Dollar Index clearing 101.00 for the first time since late July, alongside hawkish signals from Boston Fed President Susan Collins, Richmond Fed President Thomas Barkin, and Fed Governor Michael Barr, has repriced roughly 93 basis points of additional Fed tightening through end-2027. That repricing is the catalyst.
For traders and investors watching emerging-market currencies, this piece lays out a framework for judging whether the peso’s weakness is a tradeable dip or the early stage of a structurally repriced pair. The aim is to leave you understanding the mechanism, not just the direction.
What the market is telling you right now
The move is not a single bad session. USD/MXN was trading at 17.37905 as of 23 September 2026, according to TradingKey, up 0.53% on the day and reaching an intraday high near 17.50. Track the reference points in sequence and a coherent reversal comes into focus.
- Early September low: 16.88695182 on 5 September 2026
- Two-year peso high: 16.98 on 11 September 2026
- Current level: 17.37905 on 23 September 2026
- Intraday high: near 17.50
That is a clean, multi-day repricing rather than a spasm. The 7-day gain of 0.79% confirms the pressure has been steady, building across sessions instead of arriving in one violent lurch.
The broader dollar context anchors the direction. The US Dollar Index gained over 0.57% to clear 101.00 for the first time since late July, so the peso is not being singled out. It is being carried along by a dollar that is strengthening against most of its peers.
The peso’s sensitivity to the current repricing is not accidental; it reflects the currency’s structural position as a liquid emerging-market proxy that absorbs global sentiment shocks independently of domestic fundamentals, which is one of the core Mexican peso drivers that separates it from lower-liquidity peers in the same rate environment.
The rate environment behind that strength is stark.
The US 30-year Treasury yield reached 5.189%, its highest level since 2007, cited directly in connection with the peso pushing past 17.49.
When long-dated US yields hit levels last seen nearly two decades ago, capital has a compelling reason to sit in dollars. The read for you is that this dollar strength is broad-based, not idiosyncratic to Mexico, which means the peso cannot decouple from it without a domestic catalyst of comparable force. The character of this sell-off, steady and dollar-driven, tells you it is closer to a momentum signal than a clean mean-reversion setup.
When big ASX news breaks, our subscribers know first
How the carry trade math stopped working
The peso’s earlier strength rested on a simple piece of arithmetic. A carry trade means borrowing in a lower-yielding currency and investing in a higher-yielding one, then pocketing the interest-rate spread minus whatever the currency does against you. For years, the peso paid handsomely for that risk. Now the payment has shrunk.
The current US-Mexico differential sits at 250 basis points, its slimmest since 2015 according to TradingKey. That is a fraction of what the trade once offered, and the deterioration came from both directions at once.
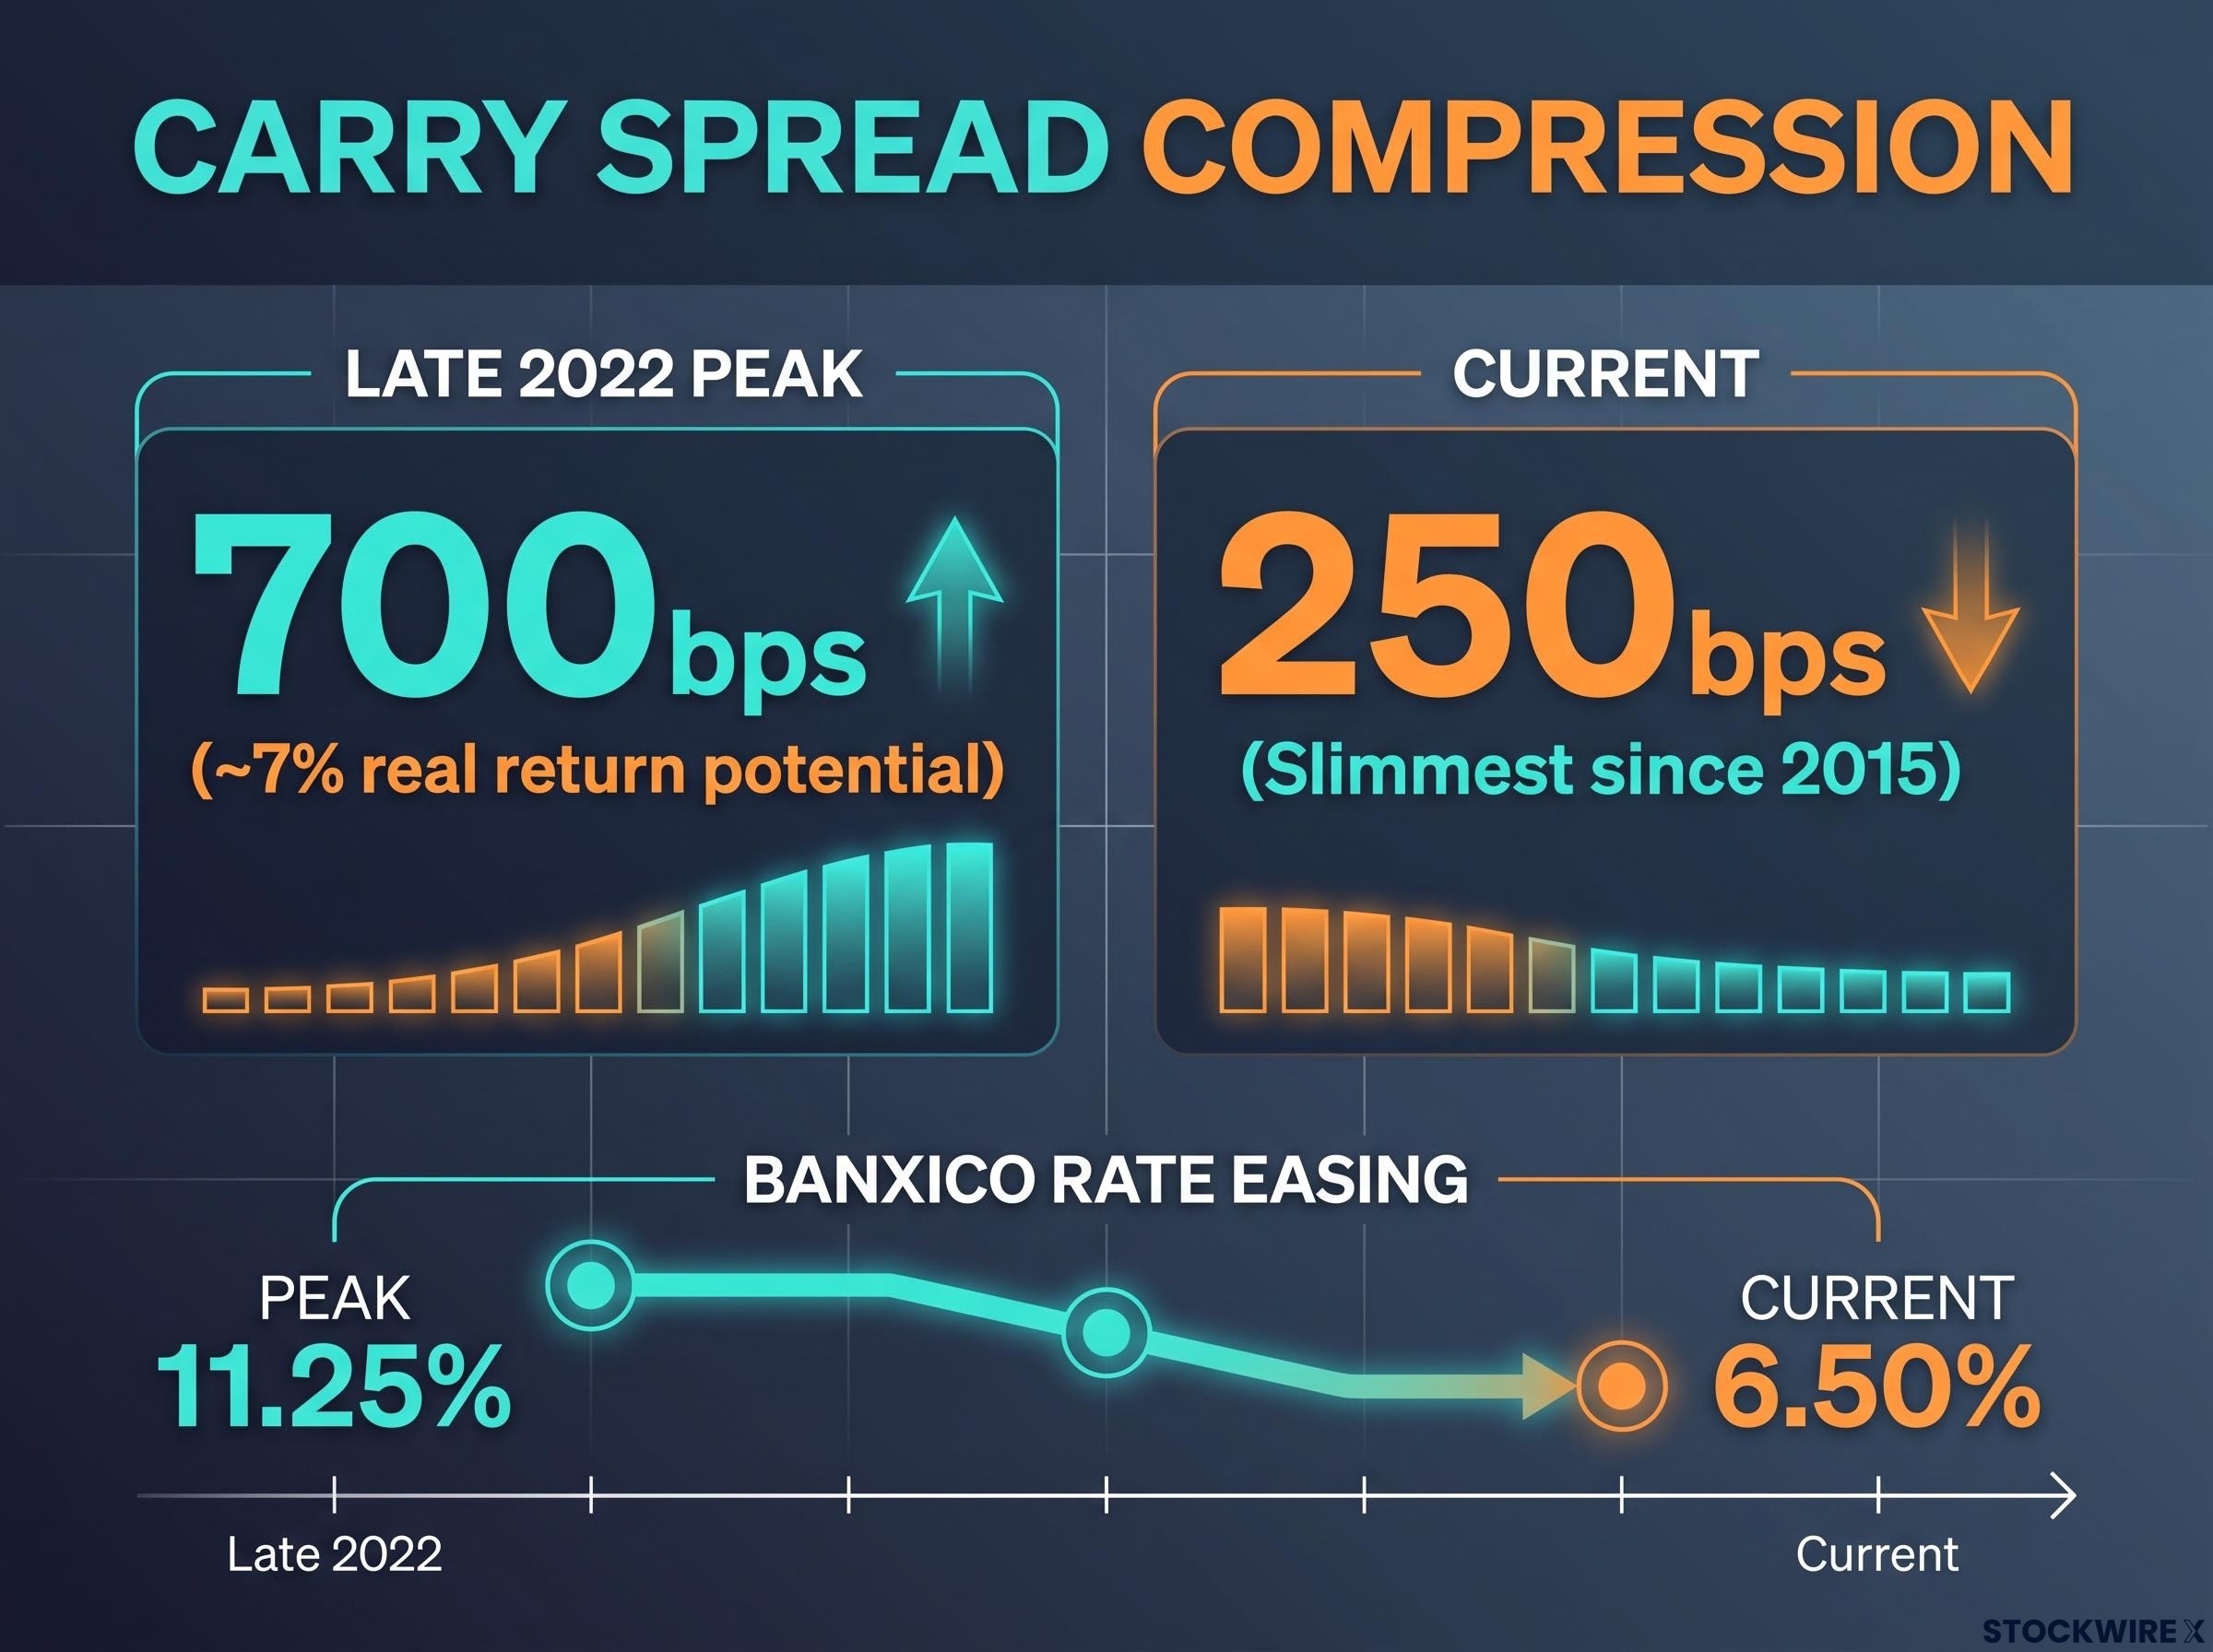
Banxico did much of the work on its side, cutting a cumulative 475 basis points from a peak of 11.25% to the current 6.50%. On the other side, markets have repriced roughly 93 basis points of additional Fed tightening through end-2027. One central bank pulled its rate down; the other is pushing expectations up. The spread got squeezed in the middle.
From 700 basis points to 250: tracing the compression
The scale of the shift becomes clear against the historical baseline. Dallas Fed research shows that in late 2022, at the peak of the differential, a carry investor could earn roughly 7 percentage points in real return by borrowing dollars and lending pesos, assuming a stable exchange rate. Banxico’s easing from 11.25% to 6.50% then steadily eroded that premium.
| Period | Approximate Spread | Peso Direction | Key Driver |
|---|---|---|---|
| Late 2022 peak | ~700 bps (real return potential) | Strengthening | Wide differential, strong carry inflows |
| 2025 “superpeso” phase | ~300 bps | Near multi-year highs | Sustained carry, solid fundamentals |
| Current reading | 250 bps (slimmest since 2015) | Weakening | Banxico easing plus Fed repricing |
Mitrade, in a note dated 22 September 2026, flagged that the carry cushion thinned as USD/MXN broke its 100-day simple moving average, a technical line traders watch as a proxy for medium-term trend. The break coincided with the fundamental deterioration, so the chart and the interest-rate maths were pointing the same way.
Rabobank made the structural point on 10 June 2026, stating the peso’s carry appeal is fading as interest-rate differentials narrow. The firm added that reduced carry returns lower the peso’s tolerance for volatility, leaving it more sensitive to electoral and political shocks than it was during the wide-spread years.
Thin liquidity concentrates carry reversal dynamics rather than suppressing them, a pattern that has repeated across three major August blowups in 2007, 2015, and 2024, each triggered inside the calendar window that carry traders historically treated as low-risk.
Here is what a 250-basis-point spread means for you: it offers roughly one-third of the cushion that made the superpeso trade compelling in 2022. Peso holders are now carrying materially more uncompensated currency risk than they were two years ago, which is why this weakness is about a multi-year shift in the yield advantage, not just today’s Fed headlines.
The Fed-Banxico policy gap and what each central bank signals next
Two central banks are now pulling on the same rope in opposite directions. The Fed is still adding tightening weight while Banxico has signalled a long pause with limited room to move either way. That tension is what governs the pair from here.
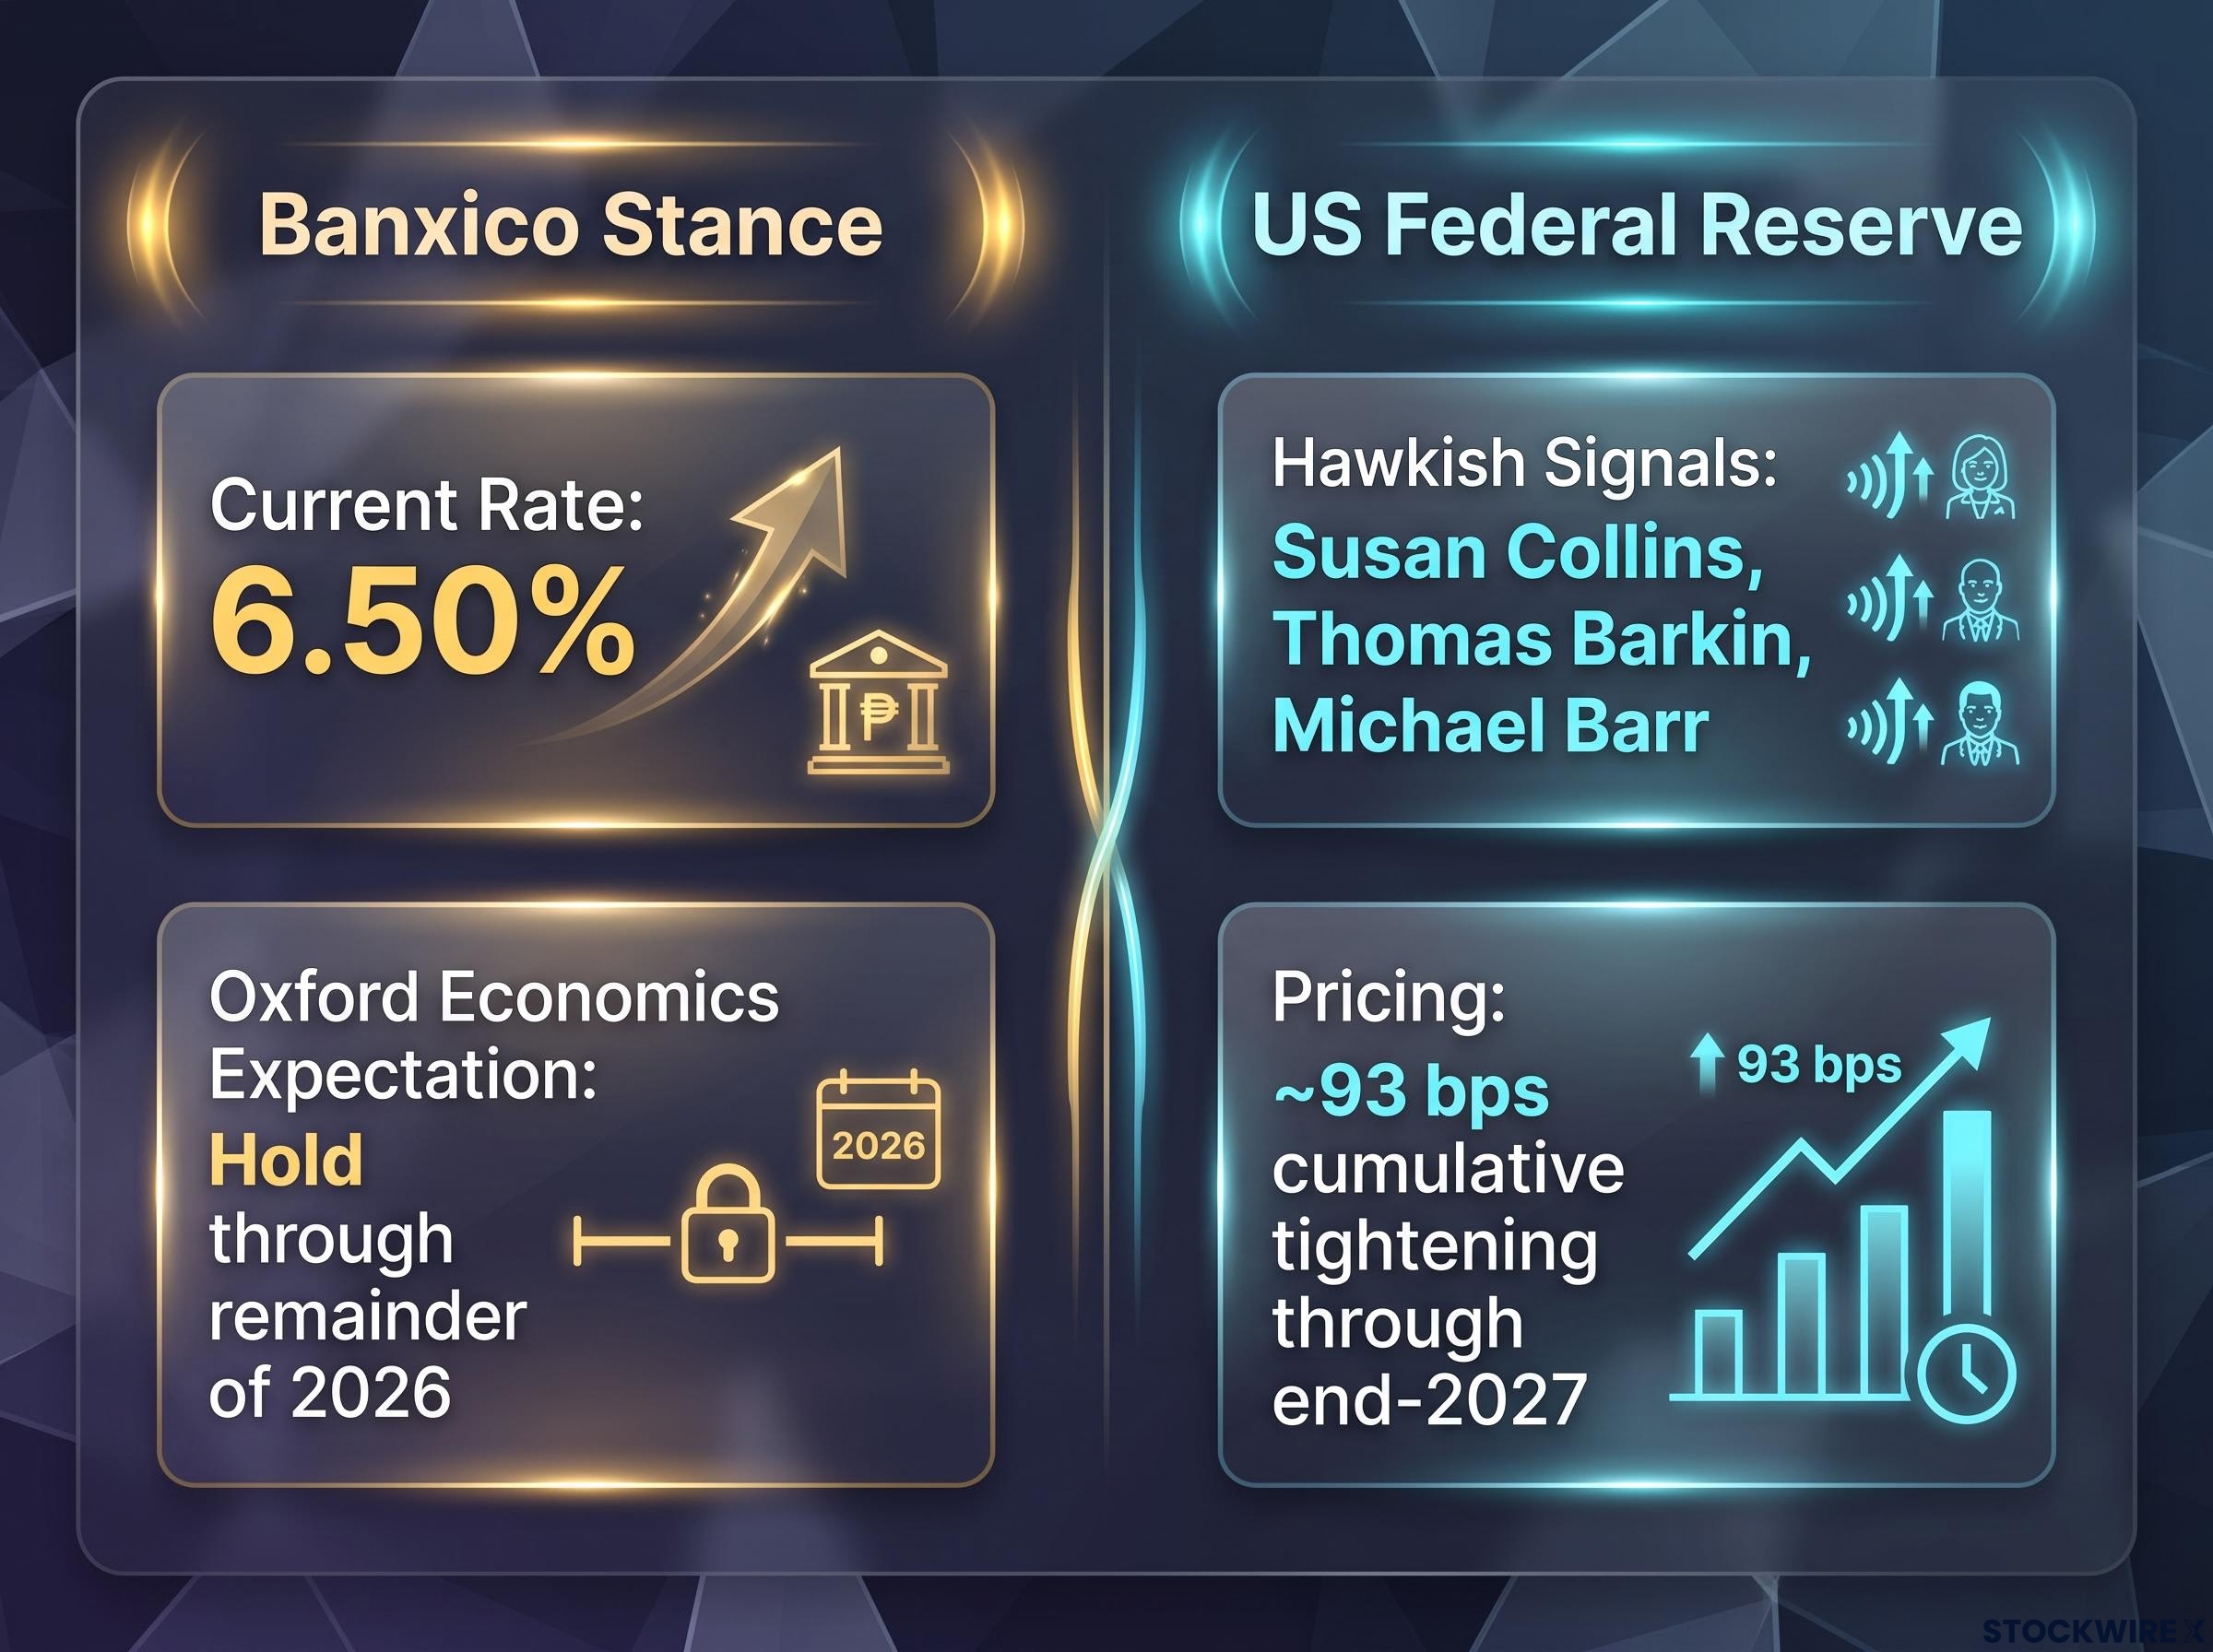
On the Fed side, the hawkish signals form a chorus rather than a set of one-off remarks. Susan Collins warned on persistently elevated inflation risks and backed further increases. Thomas Barkin flagged that inflationary disruptions could run for an extended period. Michael Barr suggested additional hikes are likely needed to return inflation to target on schedule. Together, that guidance is what drove markets to price roughly 93 basis points of cumulative tightening through end-2027.
The hawkish chorus from Collins, Barkin, and Barr carries more pricing weight than equivalent remarks would have under the prior Fed communication regime, because Warsh’s FOMC has stripped out the forward-guidance buffer that once allowed markets to smooth rate-path surprises across meetings rather than repricing them immediately.
Banxico’s position is close to the mirror image. A hold at 6.50% on 24 September 2026 is near-certain, with money markets assigning a 79% probability to no change, per Prime Terminal data. The rate has been held since 6 August 2026, and Oxford Economics expects it to stay there through the remainder of 2026, citing persistent services inflation and shock risk as reasons not to resume cutting.
| Institution | Current Rate | Expected Path Through End-2026 | Key Constraint |
|---|---|---|---|
| Banxico (own minutes) | 6.50% | Maintain at current level; “long pause” | Inflation and external risks |
| Oxford Economics | 6.50% | Hold through remainder of 2026 | Persistent services inflation, shock risk |
| Rabobank | 6.50% | Gradual easing alongside anticipated Fed cuts | Narrowing differential, political sensitivity |
The tension creates an asymmetric risk. If the Fed tightens further while Banxico holds, the differential narrows. If Banxico is forced to ease before the Fed pauses, it narrows faster. Both paths point the same way for the spread.
Convera’s FX note of 15 September 2026 argued that hawkish Fed guidance could push USD/MXN through 17.20 toward 17.50, framing the dollar’s gains as uneven but still favoured by tighter US policy.
What this means for how you weight your scenarios: the path of least resistance for USD/MXN is upward unless US data softens enough to shift the Fed’s forward guidance. Knowing Banxico describes its own stance as a long pause while the Fed still adds weight gives you a forward-looking lens, rather than a reason to chase each day’s candle.
Structural supports, political risks, and the variables that matter most
None of this makes the peso a straightforward one-way bet. Several genuine structural supports have anchored the currency for years, and they have not vanished. What has changed is that each now operates with less margin than before.
Structural supports:
- Nearshoring investment flows, with foreign direct investment tied to Mexico’s role in North American supply chains (Riotimes)
- Large, steady remittance inflows into the domestic economy
- A solid external balance that reduces reliance on carry flows alone (Rabobank, Dallas Fed)
- Deep US-Mexico economic integration, which the Dallas Fed identifies as a key reason the peso outperformed other emerging-market currencies through past stress
Rabobank’s read is that these factors keep the peso range-bound rather than setting up a repeat of its outsized 2023 appreciation. The supports are real, but they function as a floor, not a launchpad.
Dallas Fed analysis of US-Mexico economic integration identifies remittance flows and nearshoring capital as the structural anchors that allowed the peso to outperform other emerging-market currencies during past stress episodes, a distinction that still holds even as the carry cushion thins.
What could flip the outlook in either direction
The risks are just as concrete, and they matter more now that the carry buffer is thin.
Risk factors:
- The upcoming North American trade rules review, a source of investor uncertainty if negotiations turn contentious (Riotimes)
- Domestic political risk, amplified because reduced carry returns lower the peso’s tolerance for shocks
- Elevated US long-term yields combined with any geopolitical risk-off episode
- Broad shifts in global risk appetite, given weaker structural carry support
History supplies the cautionary marker. During the April 2020 stress episode, USD/MXN hit roughly 25.78, according to Mitrade, showing that even wide-differential environments could not prevent extreme moves in a genuine risk-off panic. Today’s cushion is far thinner than it was then.
Rabobank warns that diminished carry returns could amplify political or risk-off shocks, a direct consequence of the compressed spread.
Three variables are worth watching specifically: Fed forward guidance at each remaining 2026 meeting, the outcome of the North American trade rules review, and Banxico’s communication on services inflation. The structural supports are best understood as a limit on how far the peso can fall in a moderate-stress scenario, not a catalyst for renewed strength, and you should size positions with that distinction in mind.
What the current setup means for traders monitoring the pair
Two institutional camps have formed, and the useful move is to see which conditions validate each rather than split the difference. One camp expects further USD/MXN upside; the other expects stabilisation and range-bound trading. Neither is wrong in the abstract. Each depends on specific triggers.
TradingKey argues that compressed spreads and cautious positioning ahead of the central-bank decisions could sustain upside pressure if the Fed stays firm and Banxico holds. Convera puts a number on it, targeting USD/MXN through 17.20 toward 17.50 in the hawkish scenario. Against that, Rabobank sees a range-bound peso propped up by remittances and nearshoring, while Riotimes points to Banxico’s long-pause signal as a medium-term stabiliser.
- Bull case for the peso (USD/MXN lower): the Fed signals a dovish pivot at an upcoming meeting; nearshoring FDI accelerates and reinforces the external balance; the North American trade review concludes without disruption.
- Bear case for the peso (USD/MXN higher): the Fed holds its hawkish guidance and adds to the priced-in tightening; a trade shock or geopolitical risk-off episode hits; Banxico is pressured toward earlier easing.
At 250 basis points, the carry cushion is operating with roughly one-third of the buffer that underpinned the 2022-2025 appreciation phase.
The near-term bias, anchored to that policy asymmetry rather than to short-term price action, tilts toward further USD/MXN upside unless Fed guidance softens. The practical distinction to carry with you: this is a cyclical carry unwind, not a structural breakdown. A collapse toward April 2020 levels would require a separate, severe shock, because the remittance and nearshoring floor still holds.
For investors wanting to model the bull and bear cases in more depth, our dedicated guide to USD/MXN scenario analysis examines the specific trigger conditions for a hawkish Fed push through 17.50 against the USMCA and nearshoring factors that have historically capped peso weakness.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking scenarios are speculative and subject to change.
A structurally repriced pair, not a broken one
The core finding holds together cleanly: the peso’s weakness reflects a structural repricing of the carry trade, not a fundamental breakdown in Mexico’s economic position. The differential that once paid 700 basis points of real return in 2022 now offers 250, and the currency is simply reflecting that thinner compensation for risk.
Genuine uncertainty remains over the Banxico decision on 24 September 2026 and the Fed’s forward path. A hold at 6.50% is the overwhelming expectation, but the Fed’s next communication is where the balance of risk will be set. Those are the two near-term catalysts most likely to shift current positioning.
Watch the spread above all else. As long as it keeps compressing, the path of least resistance for USD/MXN stays upward, and the mechanism connecting carry mathematics to the exchange rate keeps working in the dollar’s favour. The moment that differential stabilises or widens is the moment the framework flips.