Diesel is selling at record prices, Brent crude is trading above $102 per barrel, and the G7 has just unlocked the largest coordinated emergency oil release since the Russia-Ukraine shock of 2022.
The world’s wealthiest nations are now burning through their emergency fuel reserves for the second time in four years. This time, the conflict driving the crisis shows no sign of resolution.
On 2 October 2026, the G7 announced a release of up to 100 million barrels of crude oil, diesel, and other oil products from strategic reserves, coordinated through the International Energy Agency (IEA) and phased across four months. The announcement follows months of supply pressure from the Iran war, which has pushed Brent back above the psychologically significant $100 threshold and driven U.S. diesel retail prices to all-time nominal highs.
This is not the first emergency draw of 2026. A prior 400-million-barrel IEA commitment made in March 2026 has already been largely exhausted, which makes this new package additive to an already depleted buffer.
This explainer unpacks what the release actually is, whether 100 million barrels is large enough to matter, where emergency oil releases have succeeded and failed before, and the five market signals most worth watching to understand where prices head next.
Brent above $102 and diesel at record highs: the pressure that forced the G7’s hand
If you have filled a tank, moved freight, or held an energy position in the past month, you have already felt what the data confirms. Fuel is expensive, and diesel is the acute problem.
As of the 2 October 2026 close, the price landscape looked like this:
- Brent crude: $102.72 per barrel, up $0.47 (+0.46%) on the day
- WTI crude: $91.26 per barrel, down $1.61 (-1.73%) on the day, with a broader October range of roughly $91-96
- U.S. retail diesel: around $5.85 per gallon in early September 2026, per AAA data
- European diesel wholesale: premiums over crude reportedly exceeding $100 per barrel in some assessments
The surge is attributed across G7 and IEA communications to supply pressure from the Iran war, not to demand growth or OPEC+ quota changes on their own. That matters, because a supply-driven squeeze responds to a supply-side tool in a way a demand-driven one would not.
Diesel crack spreads, the gap between what refiners pay for crude and what they receive for finished diesel, reached record territory during this crisis period, with readings four to six times the historical norm of $15-40 per barrel confirming that much of the pump-price pain sits in refining margins rather than crude costs alone.
Reported diesel peak (unverified): Some readings placed U.S. retail diesel at approximately $6.29 per gallon by mid-September 2026. This figure has not been independently confirmed against primary sources.
Look closely at those numbers and a pattern emerges. WTI actually fell on the day Brent rose, and diesel is trading far above the crude it is refined from. This is not a uniform market problem. It is a product-specific and geography-specific squeeze, with diesel and European supply far tighter than headline crude suggests.
For you as an investor, the distinction drives very different sector implications. Diesel tightness is what hits logistics, freight, agriculture, and manufacturing hardest, which is exactly why the G7’s release prioritised diesel frontloading rather than simply dumping crude into the market.
When big ASX news breaks, our subscribers know first
What the G7 actually announced, and how the 100 million barrels will flow
To judge whether this policy achieves anything, you need to picture the physical path those barrels travel: from government storage to a pipeline injection point, into a refinery or straight to wholesale, and eventually to a fuel station.
The confirmed scope is up to 100 million barrels of crude oil, diesel, and other oil-derivative products, released over four months beginning immediately. The headline feature is a frontloaded substantial diesel release within the first 20 days, confirmed in consistent G7 language reported across CNBC, CNN, and Anadolu Agency.
Seven nations are participating, with the IEA coordinating member contributions:
- United States
- United Kingdom
- Canada
- France
- Germany
- Italy
- Japan
No official statement has disclosed the per-country barrel contribution or the precise diesel-versus-crude split inside the package. That gap matters, because the product mix determines how much relief actually reaches diesel markets rather than general crude supply.
Here is where this release sits against the one that came before it.
| Feature | March 2026 IEA release | October 2026 G7 release |
|---|---|---|
| Announcement date | March 2026 | 2 October 2026 |
| Volume pledged | 400 million barrels | Up to 100 million barrels |
| Products covered | Crude and oil products | Crude, diesel, other oil products |
| Timeline | Phased drawdown | Four months, diesel frontloaded in first 20 days |
| Released to date | ~325 million barrels (over 80%) | Beginning immediately |
By early October 2026, around 325 million barrels, over 80% of the March pledge, had already been drawn. IEA Executive Director Fatih Birol had earlier cited roughly “two-thirds” released, a figure consistent with an earlier point in the drawdown.
That tells you something uncomfortable. The G7 is announcing a fresh 100-million-barrel tranche precisely because the March intervention did not resolve the underlying supply problem, and this second effort begins from a materially thinner buffer.
The inventory drawdown driving this second intervention has been running at a pace that prior emergency releases could not arrest: global stocks were drawing at 8.5 million barrels per day in Q2 2026, more than double the record rate from earlier in the year, with usable buffer estimated at only around 800 million barrels by JPMorgan.
On timing, physical delivery typically reaches storage or pipeline injection points within days to two weeks. End-user relief at the pump takes additional weeks on top of that, so the diesel frontload is the part to watch for freight and logistics exposure.
How strategic petroleum reserve releases actually work, and why they often disappoint
A government announces a number of barrels, and headlines treat it as a done deal. The reality between that announcement and a lower price at the pump is where most of the disappointment lives.
A strategic reserve release moves through four stages under IEA emergency protocols:
- Authorisation. Governments authorise releases from strategic stocks, whether national reserves or mandated commercial inventories.
- Allocation. Volumes are auctioned or allocated to refiners and traders.
- Delivery. Those buyers take physical delivery at storage sites or via pipeline injection.
- Market entry. Crude enters refinery runs, while refined products such as diesel can go directly into wholesale markets.
The IEA coordinates all of this to hit a target aggregate volume, usually expressed as a daily rate over a set number of days.
Wood Mackenzie analyst Alan Gelder estimated that a major diesel-focused release could ease wholesale prices in the near term, though the effect is likely to prove temporary given persistent supply imbalances.
Near-term diesel relief estimate (unverified): A major diesel-focused release could lower wholesale prices by $20-30 per barrel in the near term, per Wood Mackenzie, with the effect likely temporary. This figure has not been independently confirmed against primary sources.
Drawing on IEA reviews of the 2011 Libya emergency release and the 2022 Russia-Ukraine coordinated response, four structural limits consistently blunt the impact:
CFR analysis of strategic petroleum reserve policy identifies coordinated IEA action as the condition most likely to produce meaningful near-term price relief, while noting that unresolved supply disruptions consistently cause prices to revert once reserve barrels stop flowing.
- Prompt relief only. Releases lower near-term prices but do not change long-run supply expectations while war or sanctions continue.
- The bridge perception. Traders read releases as temporary supply, so prices re-converge to fundamentals once the barrels stop flowing.
- Refining and logistics constraints. Extra crude does not become extra diesel where it is needed most.
- The buffer paradox. If markets expect future tightness, a visible drawdown can reduce perceived safety and dull the calming effect.
The practical takeaway for you is this: do not assume the G7 release produces durable relief at the pump. The more useful question is whether it buys enough time for the underlying geopolitical situation to shift.
Why the barrels often do not reach where they are needed most
Crude and diesel are not interchangeable. Diesel is produced in specific refinery units, so adding crude to the system does not automatically yield more diesel on the schedule a shortage demands.
Regional fuel specifications add a second constraint. Diesel sold in one market must meet local standards, and shipping those products across regions takes time, which means additional crude cannot be converted and delivered as usable diesel wherever the squeeze is worst.
For you, that explains why a crude-heavy release can look large on paper yet leave diesel prices stubbornly high at the point of use.
Is 100 million barrels enough? The sufficiency question and the risks that cut against it
On the surface, the number looks substantial: large, coordinated across seven economies, and frontloaded toward the product under the most pressure. The arithmetic underneath is less reassuring.
Analysts view the release as providing temporary relief rather than a full structural offset to war-driven supply disruption. It is also additive to a buffer already drawn down hard across 2026.
Reserve depletion context: Across the March and October 2026 programs combined, over 500 million barrels have been committed from strategic reserves. Replenishing them will be expensive and politically difficult.
Strategic reserve capacity has been eroding throughout 2026: the US SPR held approximately 283.8 million barrels as of late September, only 39.7% of its 714-million-barrel authorised capacity, making the buffer available for any further shock roughly half the size it was during prior crisis episodes.
Three risks cut against the release achieving its stated goal:
- Reserve adequacy. With hundreds of millions of barrels already drawn, the buffer available for a second shock is now materially thinner.
- OPEC+ response. In past comparable episodes, producers signalled that reserve releases would not change their production policy, which can offset part of the intended price effect. No specific 2026 OPEC+ statement on this release has been disclosed.
- Demand absorption. Strong diesel demand from military activity, logistics, and resilient global trade can absorb extra barrels quickly, limiting relief.
There is also a genuine information gap worth naming. No explicitly attributed 2026 analyst assessment comparing the 100-million-barrel volume to estimated Iran-related supply losses is available in current reporting, so claims that the release precisely “covers” the shortfall should be treated with caution.
For you, the calibration is the point. This is a real, coordinated policy response that can move prices in the short term, but it is not a structural resolution. The cumulative draw across 2026 also means the G7 now has less room to respond if a second shock lands, which belongs in any scenario thinking around energy, freight, and agriculture exposure.
Five market signals worth watching before the diesel picture becomes clearer
Understanding what happened is one thing. Knowing what to track next is what lets you see the gap between policy intent and market outcome as it opens.
Most of these signals are observable through public data, so you do not need a professional terminal to follow them.
- Actual delivery versus headline volume. Whether the frontloaded diesel release genuinely materialises in the first 20 days is the first test of whether promised barrels become real supply.
- OPEC+ meeting guidance. Any signal that key producers will adjust quotas in response could partially or fully offset the release’s price impact.
- Crack spreads and refinery margins. The gap between diesel prices and crude costs reveals whether extra crude is actually translating into more product supply.
- Futures curve shape for Brent and diesel. The move between contango and backwardation is a real-time gauge of near-term supply and demand balance.
- Reserve replenishment signals. Government statements on how fast and at what cost they intend to rebuild stocks shape longer-term price expectations and perceived buffer adequacy.
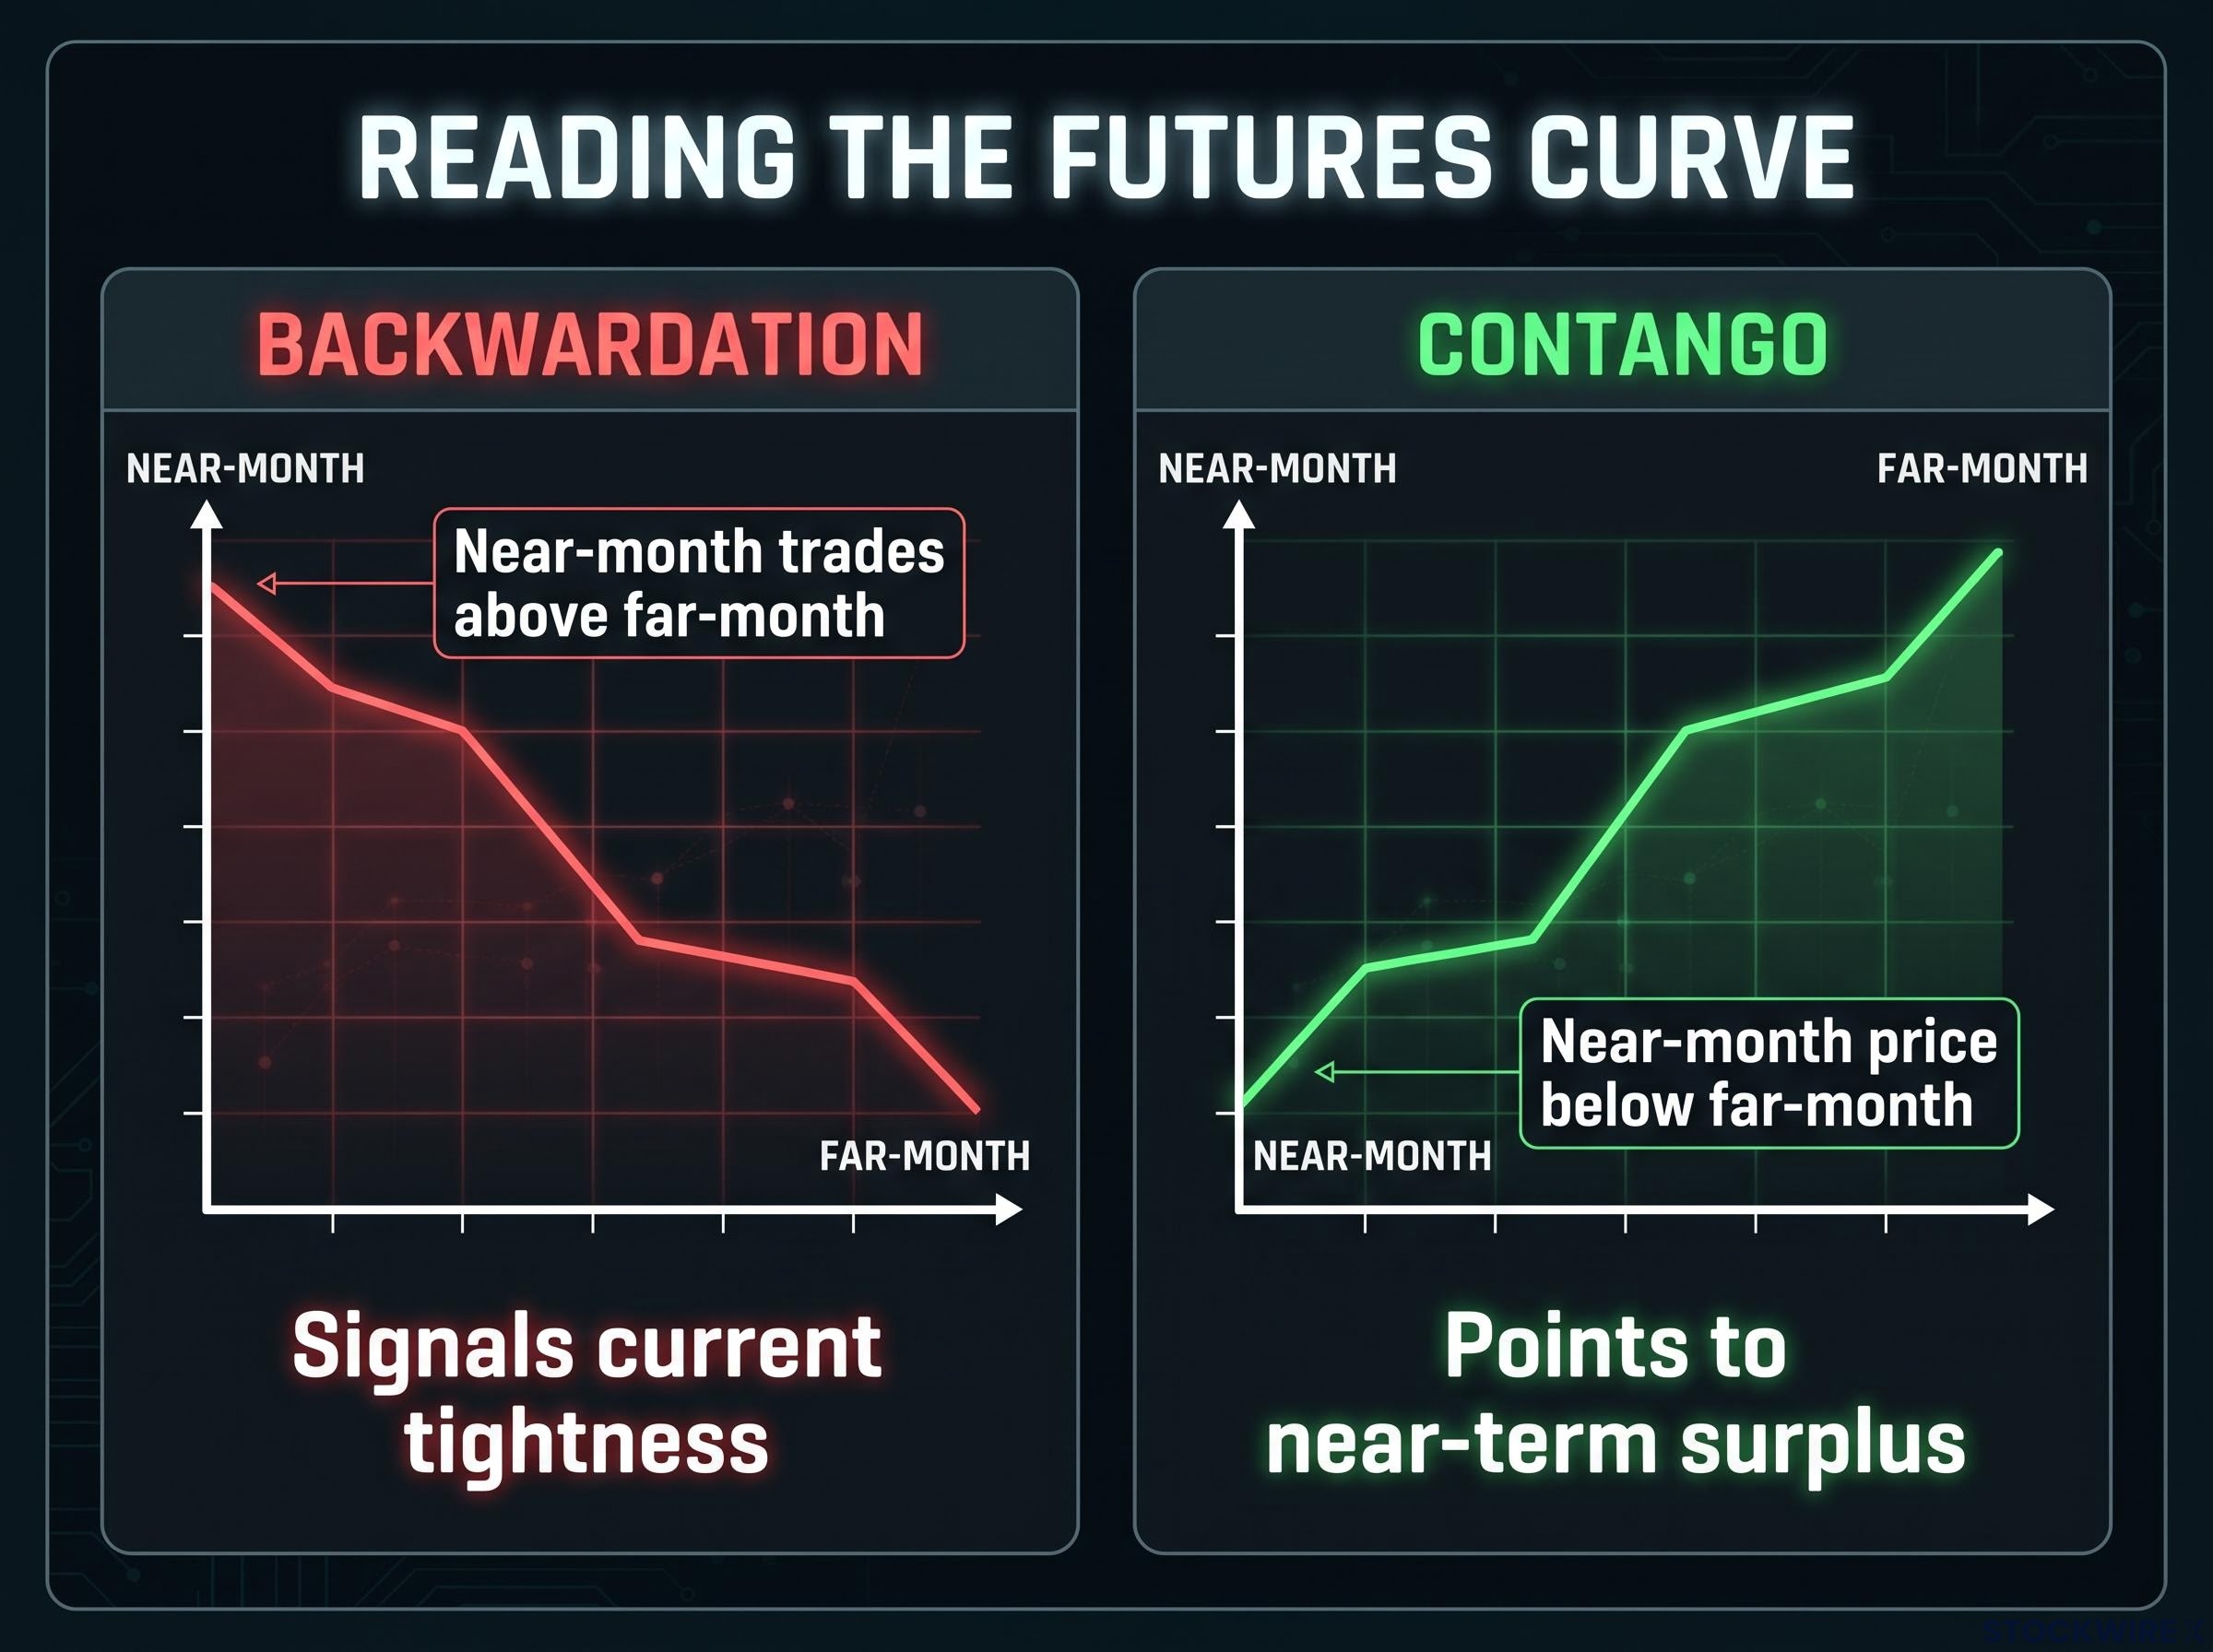
The futures curve is the single most accessible leading indicator here. A shift from backwardation toward contango would tell you traders believe supply relief is arriving faster than expected.
Reading the futures curve without a Bloomberg terminal
The futures curve plots the price of oil for delivery at different dates. Its shape carries a message about how tight the market feels right now.
Backwardation means the near-month contract trades above the far-month contract. Buyers are paying a premium for oil today, which signals current tightness.
Futures curve backwardation in crude oil can be read directly from exchange data: WTI spot was trading at $107 while the one-year forward contract sat at $73 at one recent point, a $34 gap that represents the market’s own estimate of the embedded fear premium rather than any analyst’s projection.
Contango is the reverse: the near-month price sits below the far-month price, pointing to near-term surplus and easier immediate supply.
You can watch both. Brent and ICE gasoil, the European diesel benchmark, publish their futures curves on the CME and ICE exchange websites, which makes this a practical signal for a retail investor to track week to week.
What this emergency release does and does not change for energy markets
Strip away the headline and the picture is neither relief nor alarm. The G7 release is a meaningful but temporary intervention that treats a symptom, acute diesel shortage and record prices, rather than the cause, which is Iran war supply disruption layered on sustained demand.
In the short term, the frontloaded diesel injection could ease wholesale prices, with Wood Mackenzie’s estimate of $20-30 per barrel of near-term relief offering a rough sense of scale, though that figure is unverified and explicitly described as temporary. Once the four-month program runs its course, from October 2026 through roughly February 2027, prices tend to re-converge toward underlying fundamentals.
The critical window: The next four to eight weeks are where maximum uncertainty and maximum investor risk sit. Actual delivery, OPEC+ response, and demand absorption will determine whether the policy hits its stated goal.
For you, the key implication is that this release resets the near-term price ceiling on diesel without resolving the medium-term supply equation. Positioning across energy, freight, or agriculture on the assumption that prices normalise quickly carries real residual risk, and the fact that approximately 325 million barrels have now been drawn across 2026 means the strategic safety net is thinner than it was a year ago.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments.