

Ingenia outlines the strategic case for its Peet Limited (ASX: PPC) acquisition
In its 7 October 2026 investor presentation, Ingenia Communities Group (ASX: INA) outlined the strategic rationale, valuation and expected benefits of its proposed acquisition of Peet Limited (ASX: PPC). The presentation detailed Peet’s development portfolio, potential land lease conversion opportunities and Ingenia’s capital partnering and recycling strategy.
Ingenia described the Peet acquisition as addressing one of its key strategic challenges: scale acquisition of high-quality land lease lots at an attractive price. The presentation identified the availability of attractively priced land for future development as the key constraint. It highlighted a ~15K pro forma land lease lot pipeline, 1.7x the existing pipeline, and a +70% increase in Ingenia’s land lease community (LLC) pipeline.
The proposed acquisition, first announced on 26 August 2026, remains subject to the conditions in the Scheme Implementation Deed, including establishment of the Flagstone joint venture.
John Carfi, Chief Executive Officer
“…the proposed acquisition of Peet, which offers a complementary and geographically diversified portfolio that is highly cash generative…”
Carfi also said the proposed acquisition “accelerates Ingenia’s strategy beyond the current 5-Year Plan and creates a larger, more diversified platform capable of delivering sustained growth in recurring earnings.”
When big ASX news breaks, our subscribers know first
Land lease pipeline jumps to ~15,000 lots
The presentation showed Ingenia’s stand-alone LLC pipeline of 8.8k lots, with 5k to 7k LLC Conversion Lots taking the pro forma pipeline to 13.8k to 15.8k. Ingenia said the new sites are located in deep, urban fringe markets capable of strong sales velocity.
What is a land lease community conversion?
In a land lease community, residents own their home but lease the land beneath it, which creates recurring rental income for the operator. Peet’s master planned community (MPC) lots can potentially be re-planned at higher density, from about 14 lots per hectare to about 25, and become LLC Conversion Lots.
The presentation noted a ~1.5x rule-of-thumb multiplier on MPC-to-LLC lot conversion. Conversion is subject to masterplan update, planning approval (if required), and agreement with capital partners (for managed projects).
5,000 to 7,000 LLC Conversion Lots identified
Ingenia identified ~5,000 to 7,000 potential LLC Conversion Lots across the Peet portfolio, with an indicative end value of ~$1 billion. The source totals are 2,400 to 2,710 for 100% owned projects and 2,850 to 4,280 for managed projects.
| Region | 100% owned projects | Managed projects |
|---|---|---|
| Western Australia | 900 | 1,150 to 1,700 |
| South Australia | 500 to 600 | 220 to 280 |
| Queensland | 400 to 510 | 1,000 to 1,400 |
| NSW and Victoria | 600 to 700 | 480 to 900 |
The presentation also set out FY27 LLC pipeline coverage, noting that coverage decreases below 20x rapidly as Ingenia’s annual settlements grow at 10-15% CAGR:
- INA stand-alone: 14.7x
- INA pro forma: 24.7x
- GemLife: 16.2x
- Stockland: 7.7x
- Lifestyle Communities: 10.9x
Flagstone was presented as a case study, described as the first demonstrable step in converting the identified Peet land portfolio into recurring income. Ingenia identified 600 to 900 potential LLC Conversion Lots across three separate sites (~36ha) within Flagstone City, with indicative net value creation of +$19.7m on a 100% basis.
Indicative delivery is expected to commence from FY28+. Initial site transfer is expected within 6 months of transaction settlement, subject to finalisation of the joint venture.
Valuation and financial returns
Pricing the acquisition
The offer price is $2.12 per Peet share, against a Peet Jun-26 net tangible assets (NTA) per security of $1.49. After deducting Flagstone at $615m (100% basis), the implied value paid for other projects is $0.82 per share, a ~15% discount to historical cost NTA.
Under a signed term sheet only, Brown-Neaves Investments is the JV Partner to acquire a 49.9% stake in Flagstone City. Ingenia also pointed to a ~$250m net present value (NPV) of Peet’s management fees, which is not reflected in NTA.
| Metric | Figure |
|---|---|
| Offer price per Peet share | $2.12 |
| Peet Jun-26 NTA per share | $1.49 |
| Implied value paid for other projects | $0.82 per share |
| Price per MPC lot (Flagstone) | $77k |
| Price per MPC lot (non-Flagstone) | $63k |
| NPV of management fees | ~$250m |
| FY26PF P/E | 7.3x (8.0x prior to $10m cost synergies) |
Accretion and balance sheet
On a FY26 pro forma basis, Ingenia detailed +11.0% EPS accretion, with EPS moving from $0.36 to $0.40, alongside double digit DPS accretion and nil goodwill attribution. Pro forma preliminary acquisition accounting results in no goodwill, subject to finalisation after completion.
Pro forma gearing was 29.5% against 30.9% for Ingenia standalone. The pro forma figures assume the transaction, including the Flagstone JV, had occurred on 1 July 2025, and do not represent achieved earnings.
Low-risk, cash-generative portfolio
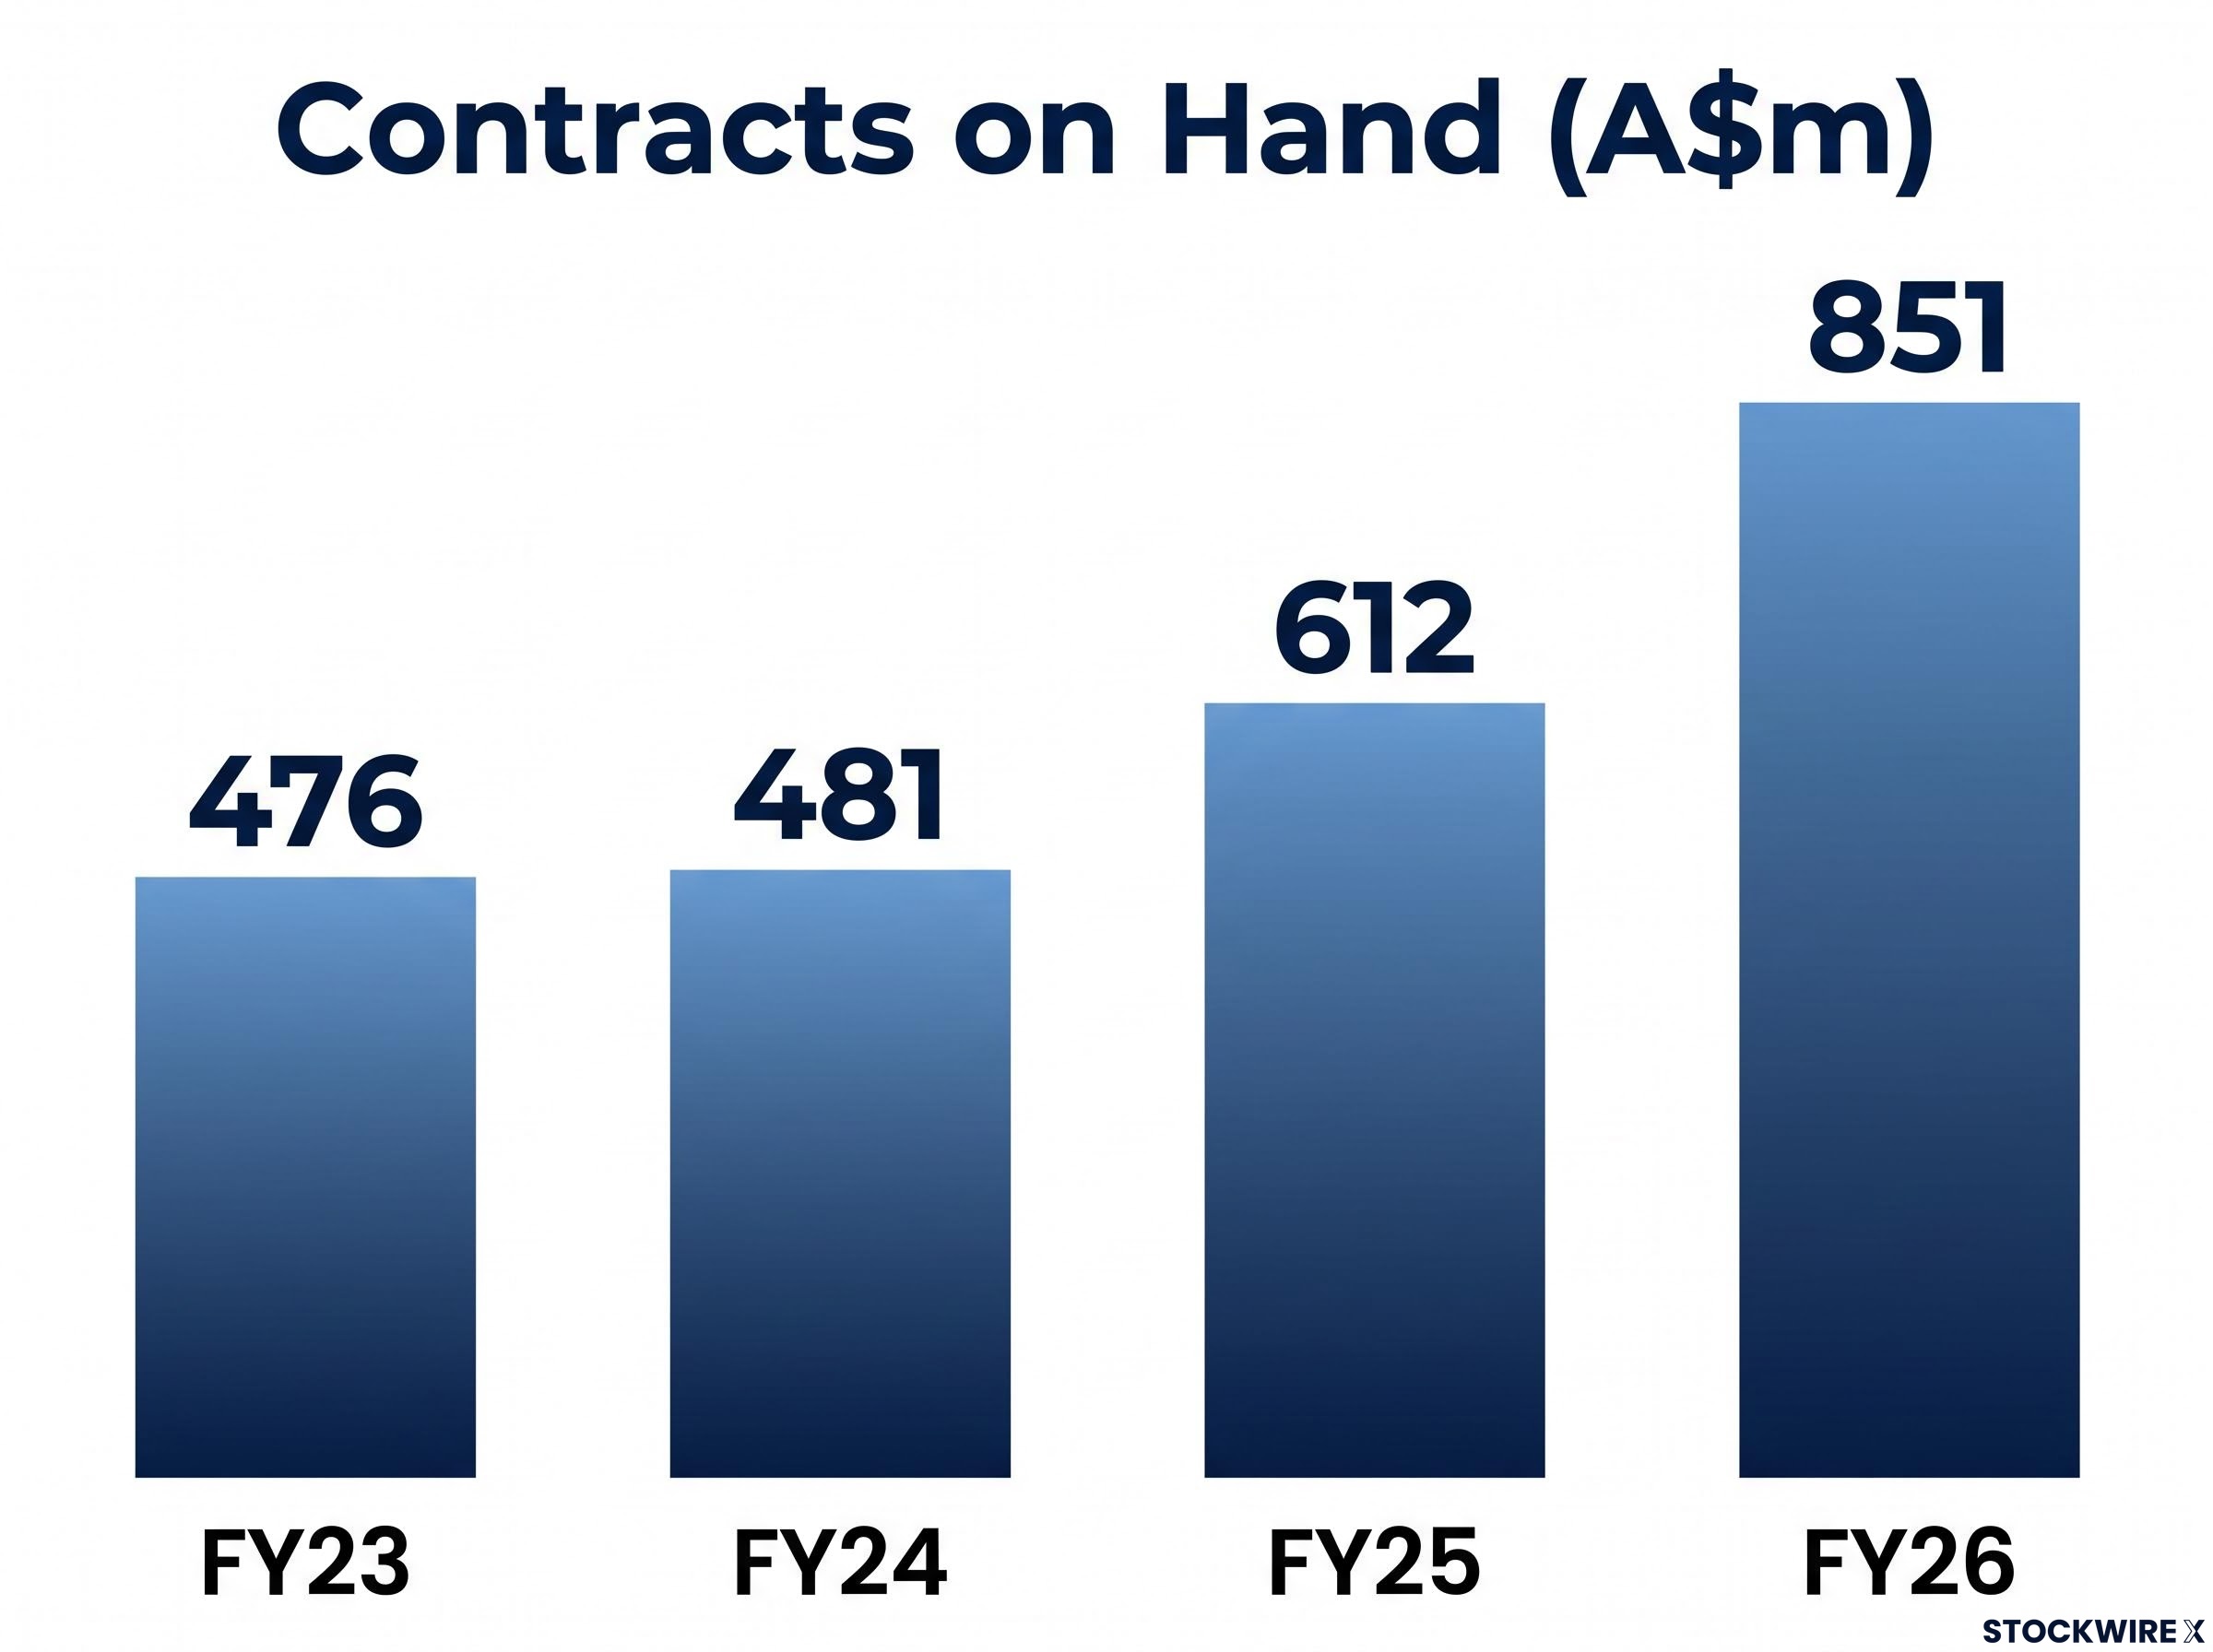
Ingenia described Peet’s MPC platform as low risk, with 87% of the portfolio activated in FY27 and $851m of contracts on hand as at 30 June 2026. Where a project is launched, all lots in that project are considered activated.
| Year end | Contracts on hand (A$m) |
|---|---|
| FY23 | 476 |
| FY24 | 481 |
| FY25 | 612 |
| FY26 | 851 |
The presentation gave an indicative payback period of ~5 years, based on forecast levered cash flows. Peet’s owned portfolio spans 18 projects, 16,613 lots and $7.4bn gross development value (GDV), while the managed portfolio covers 19 projects, 9,813 lots and $4.1bn GDV.
Capital partnering and deal status
Ingenia outlined an intention to partner with third-party capital and recycle capital across the enlarged development platform. Identified opportunities include the Flagstone JV, run-down of medium density and non-core projects, and future capital partnering on 100% owned projects.
Capital recycling is already under way, with Ingenia’s NSW asset sales releasing $124 million from six lower-growth communities at book value to fund debt reduction and higher-returning development.
The pro forma FY26 combined EBIT mix is:
- Lifestyle development: 30%
- Rental / recurring: 33%
- MPC fee income: 16%
- MPC development: 21%
The current timetable envisages completion in December 2026. The deal remains conditional on establishment of the Flagstone Joint Venture, which is being progressed.
Warburg Pincus proposals
Ingenia received unsolicited, non-binding indicative proposals from Warburg Pincus. Proposals of $4.75 per security (received 30 August) and $5.05 per security (received 14 September) were rejected by the Board, and were assessed as materially undervaluing Ingenia.
A further revised indicative proposal of $5.25 per security (less any future distributions) was received after market close on 25 September and disclosed on 28 September 2026. On 5 October, the Board agreed to provide Warburg Pincus with access to initial due diligence on a non-exclusive basis.
Ingenia has certain termination rights if it assesses a proposal to be superior to the Peet transaction. Ingenia stated that investors do not need to take any action in relation to the proposals.
Investors following the competing bid can read our detailed coverage of the Warburg Pincus proposal, which sets out the due diligence arrangements and the reverse break fee payable to Peet if the Peet deal is terminated.
Get Real Estate News Before the Market Moves
Join 20,000+ investors receiving FREE ASX alerts within minutes of release, with breaking news, in-depth analysis and the full announcement in one email. Click the “Free Alerts” button at Big News Blast to stay ahead of the next major real estate development the moment it breaks.