

Healthscope resolved, distributions back on track
HealthCo Healthcare & Wellness REIT (HCW) has resolved a prolonged period of tenant uncertainty, with binding agreements executed for the remaining 10 Healthscope hospitals owned by HCW and the Unlisted Healthcare Fund (UHF). Alongside this, the fund has declared a Q1 FY27 distribution of 1.5 cents per unit (cpu), reinstating income payments consistent with full-year FY27 guidance of 6.0 cpu.
The new leases have been agreed on a state-by-state basis with three incoming operators: Healthe Care (VIC), Acurio (NSW), and KnG Group (QLD). Transition to these operators is targeted for completion by 30 November 2026, with Healthscope continuing to operate the hospitals under its existing lease obligations until that date.
When big ASX news breaks, our subscribers know first
Q1 FY27 distribution details and key dates
The reinstated distribution covers the period 1 July 2026 to 30 September 2026 at 1.5 cpu, aligning with the fund’s stated full-year FY27 guidance of 6.0 cpu. The key dates for the September 2026 distribution are as follows.
| Event | Date |
|---|---|
| Distribution amount | 1.500 cents per unit |
| Ex-distribution date | Thursday, 8 October 2026 |
| Record date | Friday, 9 October 2026 |
| Payment date | On or about Tuesday, 24 November 2026 |
What the new lease arrangements mean for the portfolio
The new agreements are structured as 20-year leases with face rents maintained. Annual rental escalations are set at CPI (with a 4%/1.5% cap and collar) for NSW and QLD, and at +3% for VIC and WA. An overall incentive of approximately 12% over the term of the leases has been structured to support sustainable hospital operations, fully funded from existing liquidity. Rental abatements vary by state and are predominantly spread over the initial 5–10 years.
The Bethesda Health Care lease for Mount Private Hospital, secured with a WA State Government guarantee and announced in May 2026, was an earlier step in the same operator transition program that has now been extended across all remaining HCW and UHF hospitals.
The commercial arrangements deliver four material outcomes for the portfolio:
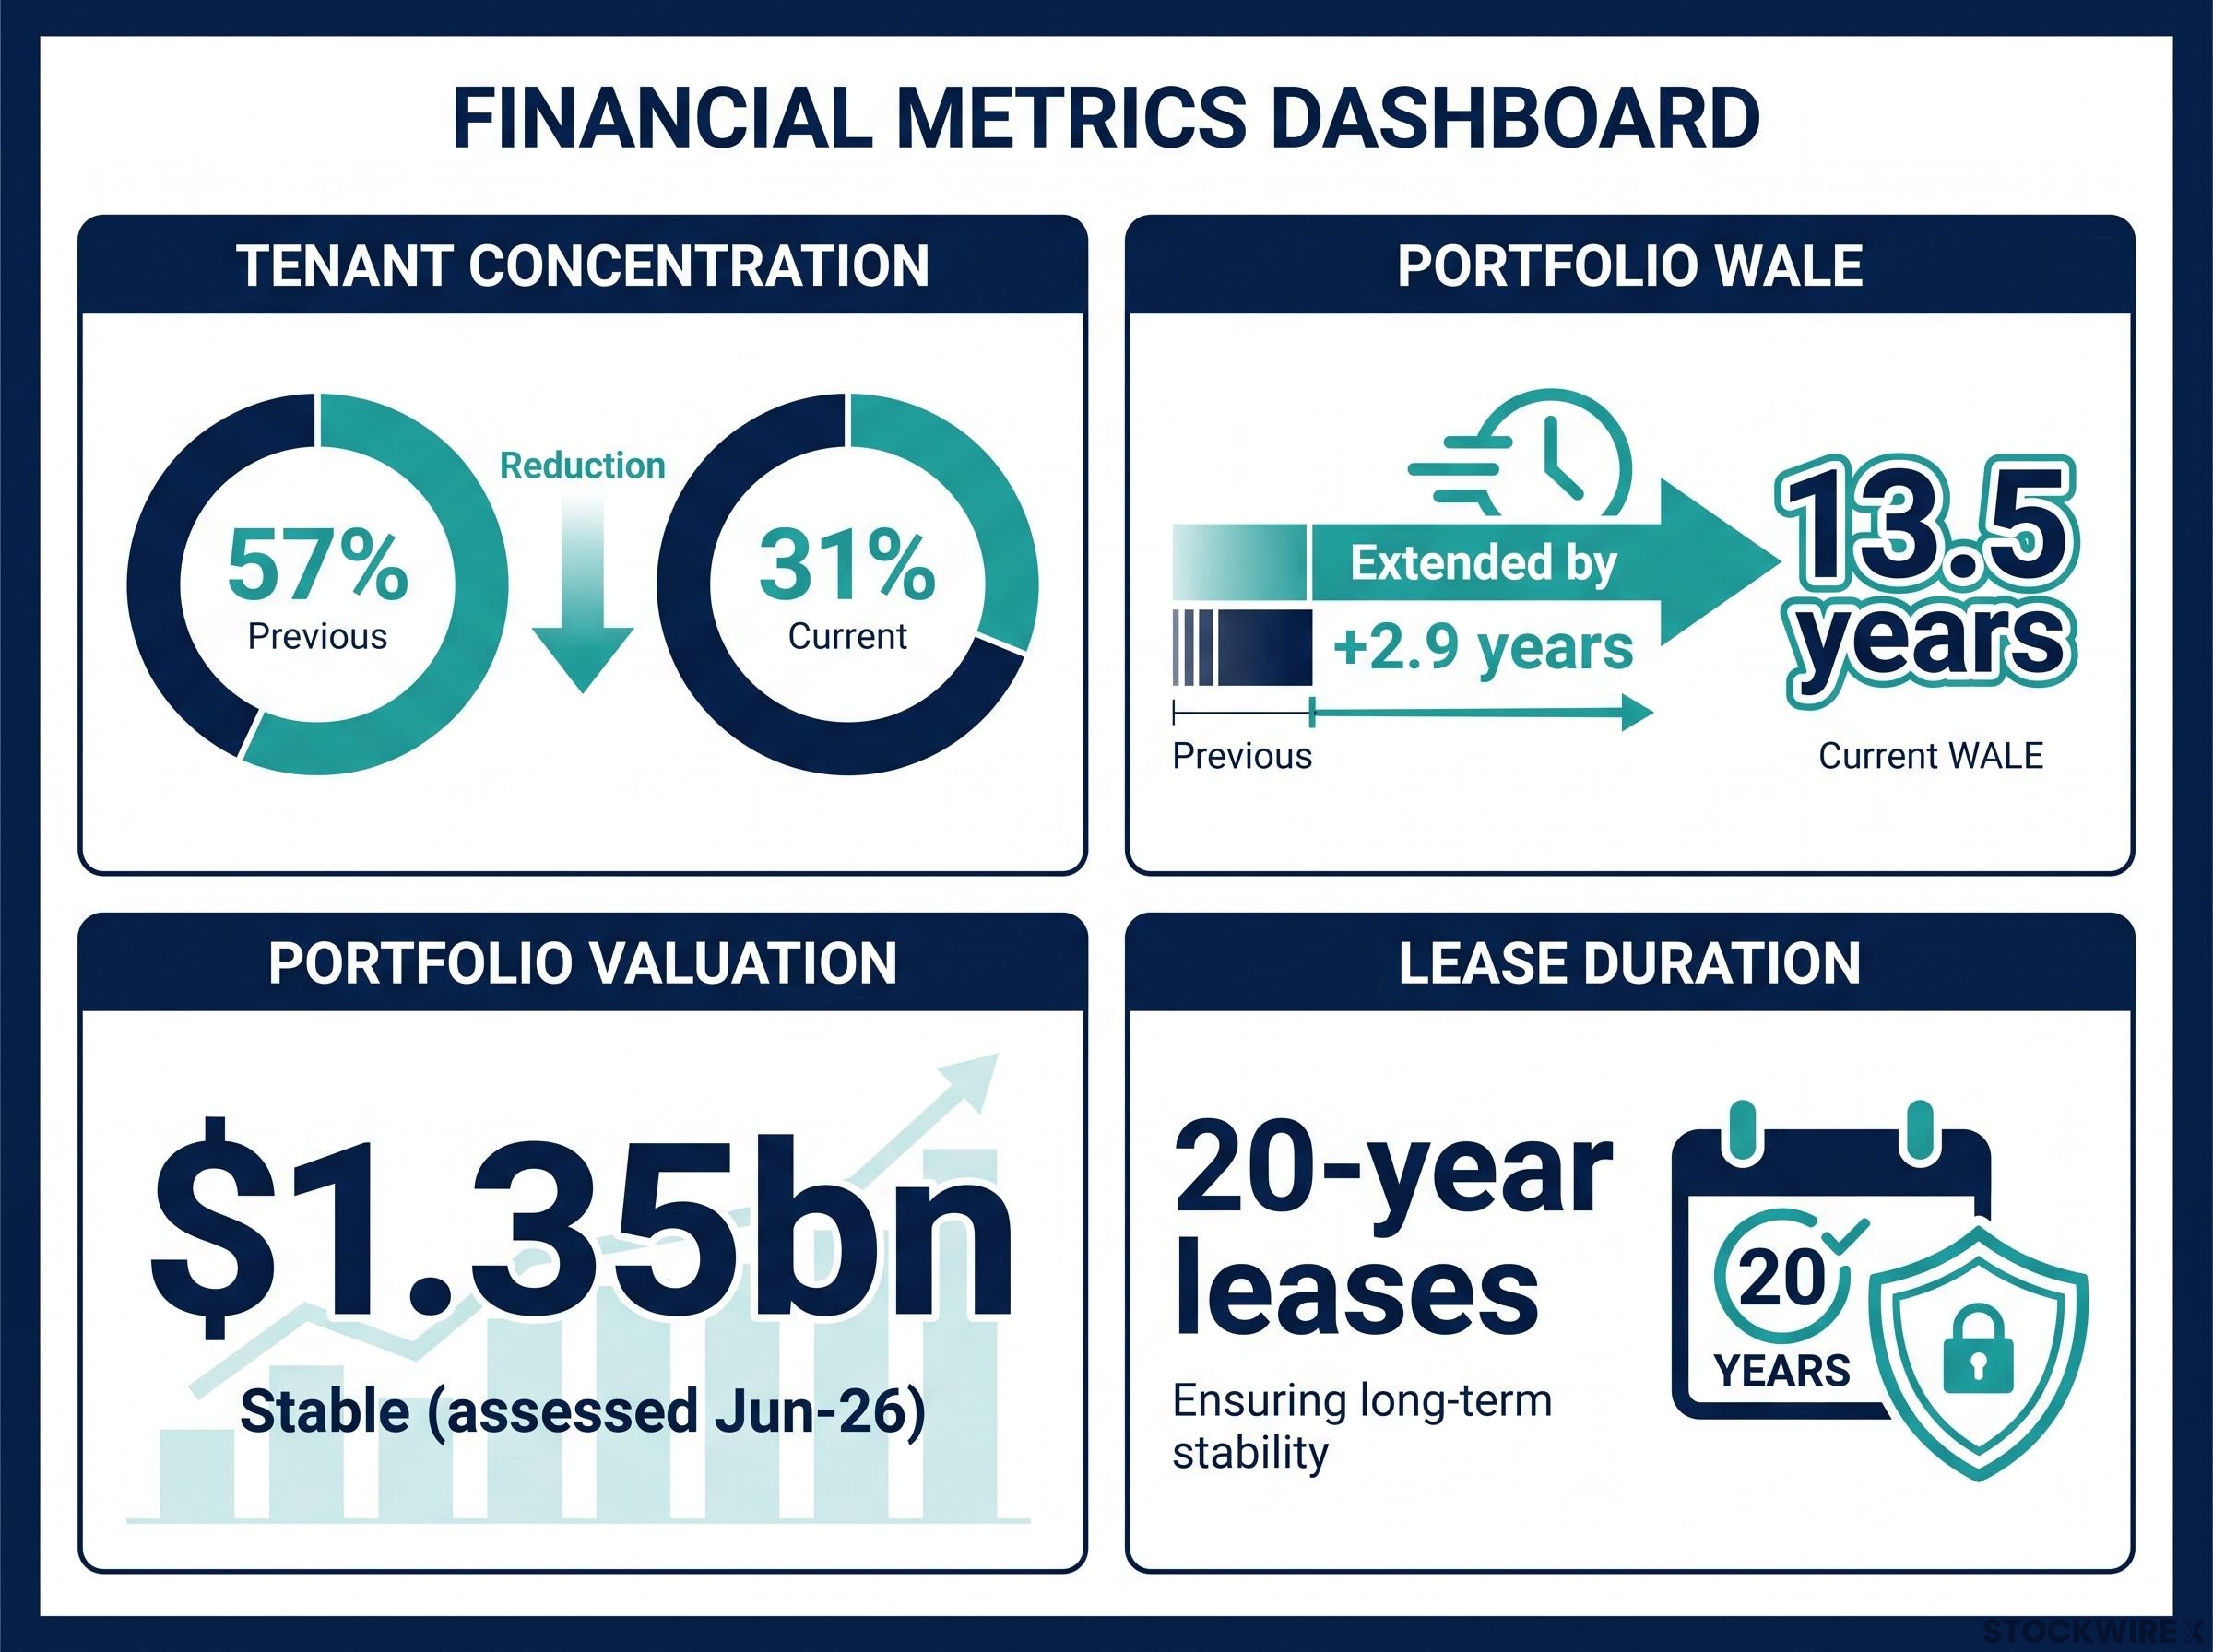
- Portfolio valuation of $1.35bn is expected to remain stable, based on independent valuations undertaken at Jun-26, with cap rate compression of 43 basis points offsetting the impact of new lease incentives
- Largest tenant concentration reduced from 57% to 31% (on a look-through income basis)
- Portfolio Weighted Average Lease Expiry (WALE) extended by 2.9 years to 13.5 years
- 20-year leases with landlord termination and cross-default rights on a state-by-state basis
The binding agreements are subject to final lender consent and other customary approvals, which are expected imminently.
Christian Soberg, HCW Fund Manager
“The resolution of the Healthscope situation is aligned with our previously stated objectives including providing continuity of service across all hospitals and maximising long term value for HCW unitholders. The new leases support distributions being reinstated, restore income certainty and provide a strong foundation for future earnings and distribution growth…”
Why tenant diversification matters in a healthcare REIT
WALE measures the average time remaining across all leases in a portfolio, weighted by income. A WALE of 13.5 years means the fund has long-dated, contractual income visibility — which directly underpins the ability to sustain distributions over time.
Equally significant is the reduction in single-tenant concentration. Prior to this resolution, Healthscope represented 57% of portfolio income on a look-through basis. That level of concentration meant the fund’s income was heavily exposed to the financial health of one operator. With concentration now reduced to 31%, the rent roll is more diversified across multiple operators, reducing the risk that any single party’s difficulties could materially impair fund income. In the context of the Healthscope situation, this diversification is a direct risk-management improvement rather than an abstract portfolio metric.
Investment case: income restored, portfolio repositioned
For investors, the key shift is that distributions have been reinstated on the foundation of long-dated leases with CPI-linked or fixed escalations — not as a one-off payment. The reinstated 1.5 cpu for Q1 FY27 sits within a full-year guidance framework of 6.0 cpu, providing a structured income outlook rather than a discretionary return.
HCW held cash and undrawn debt of $158 million as at August 2026, which is the source of funding for the approximately 12% lease incentive. No additional capital raise is required to meet this commitment.
The fund’s Board has also stated its intent to continue evaluating “a range of strategic and capital management initiatives aimed at maximising value for HCW or HCW unitholders,” though no specifics beyond this statement have been provided. HCW also holds a 49.6% interest in UHF, which forms part of the broader portfolio context.
With a stabilised $1.35bn portfolio valuation (as assessed at Jun-26), an extended WALE of 13.5 years, and income certainty restored across the hospital portfolio, the fund’s investment profile has materially improved relative to the period of Healthscope-related uncertainty.
Don’t Miss the Next Healthcare REIT Move
Big News Blast delivers FREE breaking ASX healthcare and REIT news straight to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ investors who stay ahead of the market the moment announcements drop. Click the “Free Alerts” button to start receiving real-time alerts today.