

Q1 FY27 highlights: Aspen Group delivers a strong start to the year
Aspen Group‘s Q1 FY27 quarterly update, covering the three months to 30 September 2026, came in above management expectations. Pre Tax EPS reached 7.1 cents, up 34% from 5.3 cents in Q1 FY26, while EBITDA grew 38% to $17.8m.
FY27 guidance has been reiterated, with management targeting at least 20% growth in Underlying EPS to 26.1 cents for the full year. The result reflects a business positioned to benefit from the structural undersupply of quality, value-for-money housing across Australia.
Q1 FY27 earnings at a glance
| Metric | Q1 FY26 | Q1 FY27 | Change |
|---|---|---|---|
| Net Rental Income | $10.9m | $12.7m | +16% |
| Realised Development Profit | $4.0m | $7.9m | +96% |
| EBITDA | $12.9m | $17.8m | +38% |
| Pre Tax EPS (cents) | 5.3 | 7.1 | +34% |
Figures represent unaudited management accounts.
When big ASX news breaks, our subscribers know first
What drives Aspen’s business model — and why it’s built for this market
Aspen operates across four integrated business pillars, each designed to capture value from its wholly owned property portfolio:
- Owner: Aspen maintains a 100% proprietary ownership structure across all properties and projects, with no joint venture, profit-sharing, or fund interests involved.
- Operator: The business actively manages properties to maximise profitability, offering various lease durations and services rather than acting as a passive rent collector.
- Developer: Aspen creates accommodation through brownfield and greenfield development, targeting its core customer base with cost-effective, market-appropriate product.
- Capital Manager: Disciplined acquisitions, flexible customer funding options, and capital recycling are used to optimise the portfolio and maximise equity value.
The fully integrated structure means there are no third-party conflicts diluting returns. According to the announcement, Aspen has generated 2.3x the listed peer return on a Pre Tax Return on Equity (ROE) basis, averaging 23% across FY21–FY26 compared to a simple average of 10% for listed peers (Ingenia Communities, Lifestyle Communities, and GemLife Communities).
Underlying EPS is a non-IFRS measure that management uses as the primary profitability metric. In the directors’ view, it more accurately reflects Aspen’s underlying operating performance than statutory earnings, by capturing the economic reality of the rental and development businesses.
Rental and development performance in Q1 FY27
Rental portfolio: occupancy full, margins expanding
Rental Revenue grew 10% in the quarter, while Net Rental Income increased 16%, with the NRI margin expanding 3 percentage points to 58%. Management attributed this improvement to operational management, property refurbishments, better marketing, and portfolio mix.
Long-stay accommodation is described as essentially full, with rents generally increasing 3–5% per annum and estimated to be approximately 10% below market. This is consistent with the broader rental market backdrop; Cotality estimated average rental growth of 5.5% for the 12 months to September 2026.
At CoVE Upper Mount Gravatt, a major upgrade of common facilities was completed during the quarter. A 20% rent rebate granted during the construction period ended on 1 September, and occupancy subsequently rebounded to above 90%.
The Residential Build-to-Rent (BTR) component of the Australind project is on track for completion this half. Demand has been strong, with some 2-bedroom houses leasing to corporate customers at $1,000 per week (double-occupancy, furnished and serviced), materially above the $400–$450 per week assumed in the initial feasibility assessment.
On the portfolio management side, the ECH portfolio acquisition settled in early September, the sale of Trigg apartments settled on 1 October, and the sale of Barlings Beach and Black Dolphin parks is expected to settle mid-October.
The ECH portfolio acquisition added 198 inner-metropolitan Adelaide villas at an implied entry price of $205,000 per dwelling, well below Adelaide median values, with a 6% expected net rental income yield and further upside as subsidised-rent and vacant stock is progressively normalised to market rates.
Development: profit margins and settlements accelerate
The development business recorded a strong uplift across all key metrics in Q1 FY27:
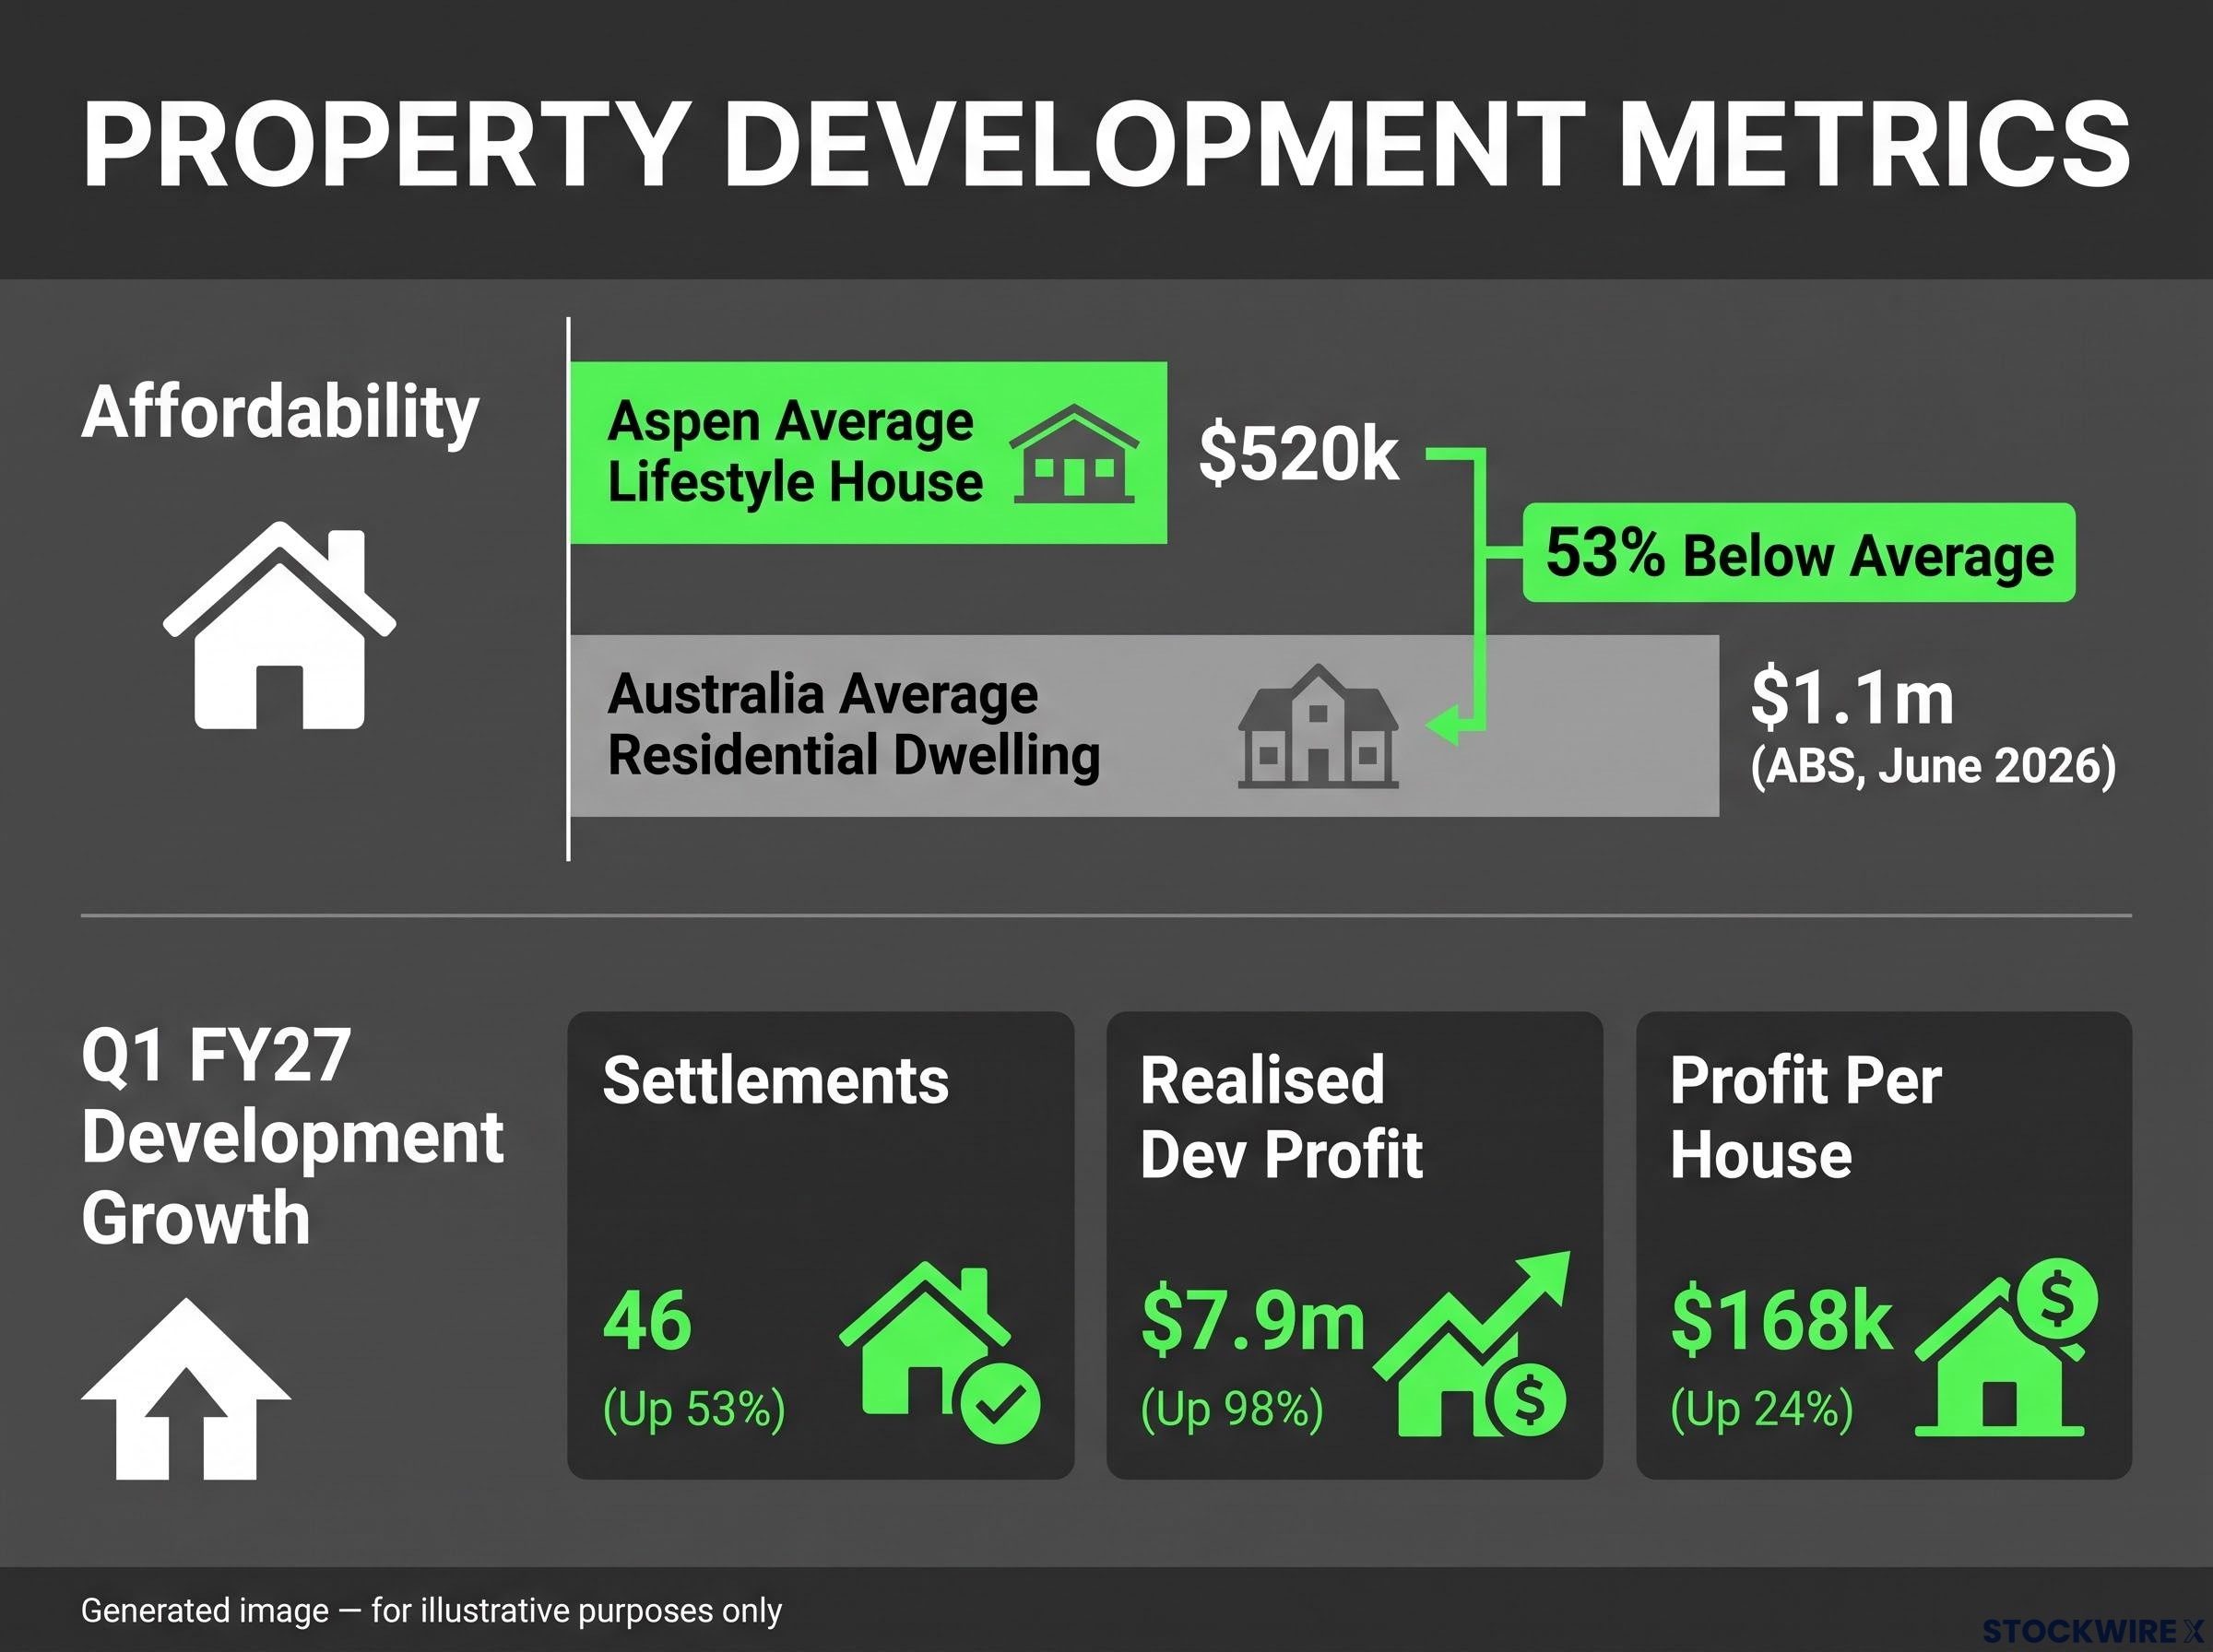
- Settlements: 46 in Q1 FY27 versus 30 in Q1 FY26 (up 53%), comprising 45 Lifestyle houses and 1 Residential land lot.
- Average Lifestyle house sale price: $520k, which is 53% below Australia’s average residential dwelling price of $1.1m (ABS, June 2026).
- Realised Development Profit: $7.9m, up 98%; margin expanded 5 percentage points to 36%; profit per house increased 24% to $168k.
- Contracts on hand: 123 at quarter end; combined with the 46 settlements, the total of 169 represents approximately 78% of FY27 Development Profit guidance.
Contract cancellations at Lifestyle projects remained very low, with no settlement delays recorded to date. At Residential land projects, 7 cancellations (9%) were recorded, however 6 of those lots have already been re-contracted, with 5 re-contracted at an average price 5% higher and 1 at the same price.
Titles have recently been issued for land lots at Mount Barker, with settlements under way. Titles for land lots at Ravenswood are expected to be issued in November, which management noted as an important milestone for mitigating development risk in FY27.
FY27 guidance reiterated — what investors should watch
Management has maintained full-year guidance despite the Q1 result coming in ahead of expectations, citing caution around weakening economic conditions and the timing risk associated with development settlements.
| Metric | FY26 Actual | FY27 Guidance | Change |
|---|---|---|---|
| Net Rental Income | $42m | $44m | +4% |
| Realised Development Profit | $22m | $33m | +52% |
| EBITDA | $54m | $66m | +22% |
| Pre Tax EPS | 21.8 cents | 26.1 cents | +20% |
| DPS | 11.0 cents | 12.0 cents | +9% |
Guidance is subject to no material change in Aspen’s operating environment.
One tax-related change is worth noting for investors. Aspen expects an effective tax rate of 10–15% of the group’s total Pre Tax Underlying Earnings in FY27, following the exhaustion of historic tax losses in FY26. A higher proportion of distributions is also expected to be franked in future periods.
Looking ahead, the announcement states that acquisition opportunities are increasing, with management indicating the company will remain selective in growing its portfolio. The structural shortage of quality, affordable accommodation for Australian households is positioned as the core demand driver underpinning the FY27 outlook and beyond.
Don’t Miss the Next ASX Real Estate Winner
Big News Blast delivers FREE breaking ASX announcements straight to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers staying ahead of the market across real estate and beyond. Click the “Free Alerts” button at StockWire X to start receiving alerts the moment news breaks.