

Warburg Pincus tables $5.25 per security bid for Ingenia
Ingenia Communities Group (ASX: INA) has received a further revised non-binding indicative proposal from Warburg Pincus LLC and/or its affiliates to acquire 100% of its issued capital via a scheme of arrangement at $5.25 cash per stapled security, less any future distributions paid prior to implementation. The proposal is dated 25 September 2026 and represents the latest development in an ongoing, evolving competitive situation around the group.
The $5.25 figure represents the third Warburg Pincus approach on record, following the rejected $5.05 offer in late September 2026, which the Board concluded substantially undervalued Ingenia and required the group to abandon its Peet acquisition strategy.
In response, the Board has agreed to provide Warburg Pincus with access to initial due diligence on a non-exclusive basis, subject to a mutually acceptable confidentiality arrangement being agreed. The purpose of this access is to allow Warburg Pincus to develop the Further Revised Indicative Proposal into something sufficiently compelling and certain for the Ingenia Board to assess whether it constitutes a “Bidder Superior Proposal” under the scheme implementation deed between Ingenia and Peet Limited dated 26 August 2026 (Peet SID).
Importantly, the Board has not determined that the Further Revised Indicative Proposal constitutes a Bidder Superior Proposal under the Peet SID, nor has it indicated any intention to recommend the proposal to securityholders. Two distinct and competing positions now exist simultaneously:
- Existing deal: Ingenia is progressing its acquisition of Peet Limited in accordance with the provisions of the Peet SID
- Competing proposal: Warburg Pincus is seeking to acquire 100% of Ingenia at $5.25 cash per stapled security via a scheme of arrangement, with initial due diligence access granted on a non-exclusive basis
The announcement also carries an explicit caution: there is no certainty that the Further Revised Indicative Proposal will result in a formal binding offer for Ingenia, or that any transaction will eventuate.
When big ASX news breaks, our subscribers know first
Understanding scheme of arrangement takeovers — what investors need to know
A scheme of arrangement is a court-approved process through which a company can be acquired. Unlike an on-market takeover bid (where an acquirer purchases shares directly from shareholders on the open market), a scheme requires shareholder approval at a meeting and subsequent court sanction before it can proceed. Both structures achieve full acquisition, but the scheme process generally requires higher thresholds of securityholder support.
The term “non-binding indicative proposal” means precisely what it states: the offer carries no legal obligation on either party and provides no certainty of completion. Warburg Pincus has expressed an intention, not made a commitment.
The concept of a “Bidder Superior Proposal” is a contractual threshold defined within the Peet SID. In plain terms, before the Ingenia Board can recommend or meaningfully engage with a competing offer, it must first assess whether that offer is sufficiently superior to the existing Peet deal. The Board has not yet reached that determination.
“Non-exclusive due diligence” means Ingenia can continue progressing the Peet acquisition in parallel while allowing Warburg Pincus to review its books. Granting access does not signal endorsement and does not pause the existing arrangement.
What the $10 million break fee means for the Peet deal
The governance stakes attached to the existing Peet SID are material. If the Ingenia Board ultimately determines that a Bidder Competing Proposal constitutes a Bidder Superior Proposal, and the Board has determined in good faith (after consulting its financial and legal advisers) that failing to recommend it would constitute a breach of fiduciary or statutory duties, Ingenia is entitled to terminate the Peet SID. However, this termination can only occur prior to 8:00am on the Second Court Date, and in that event, Ingenia would be liable to pay Peet a $10.0 million reverse break fee.
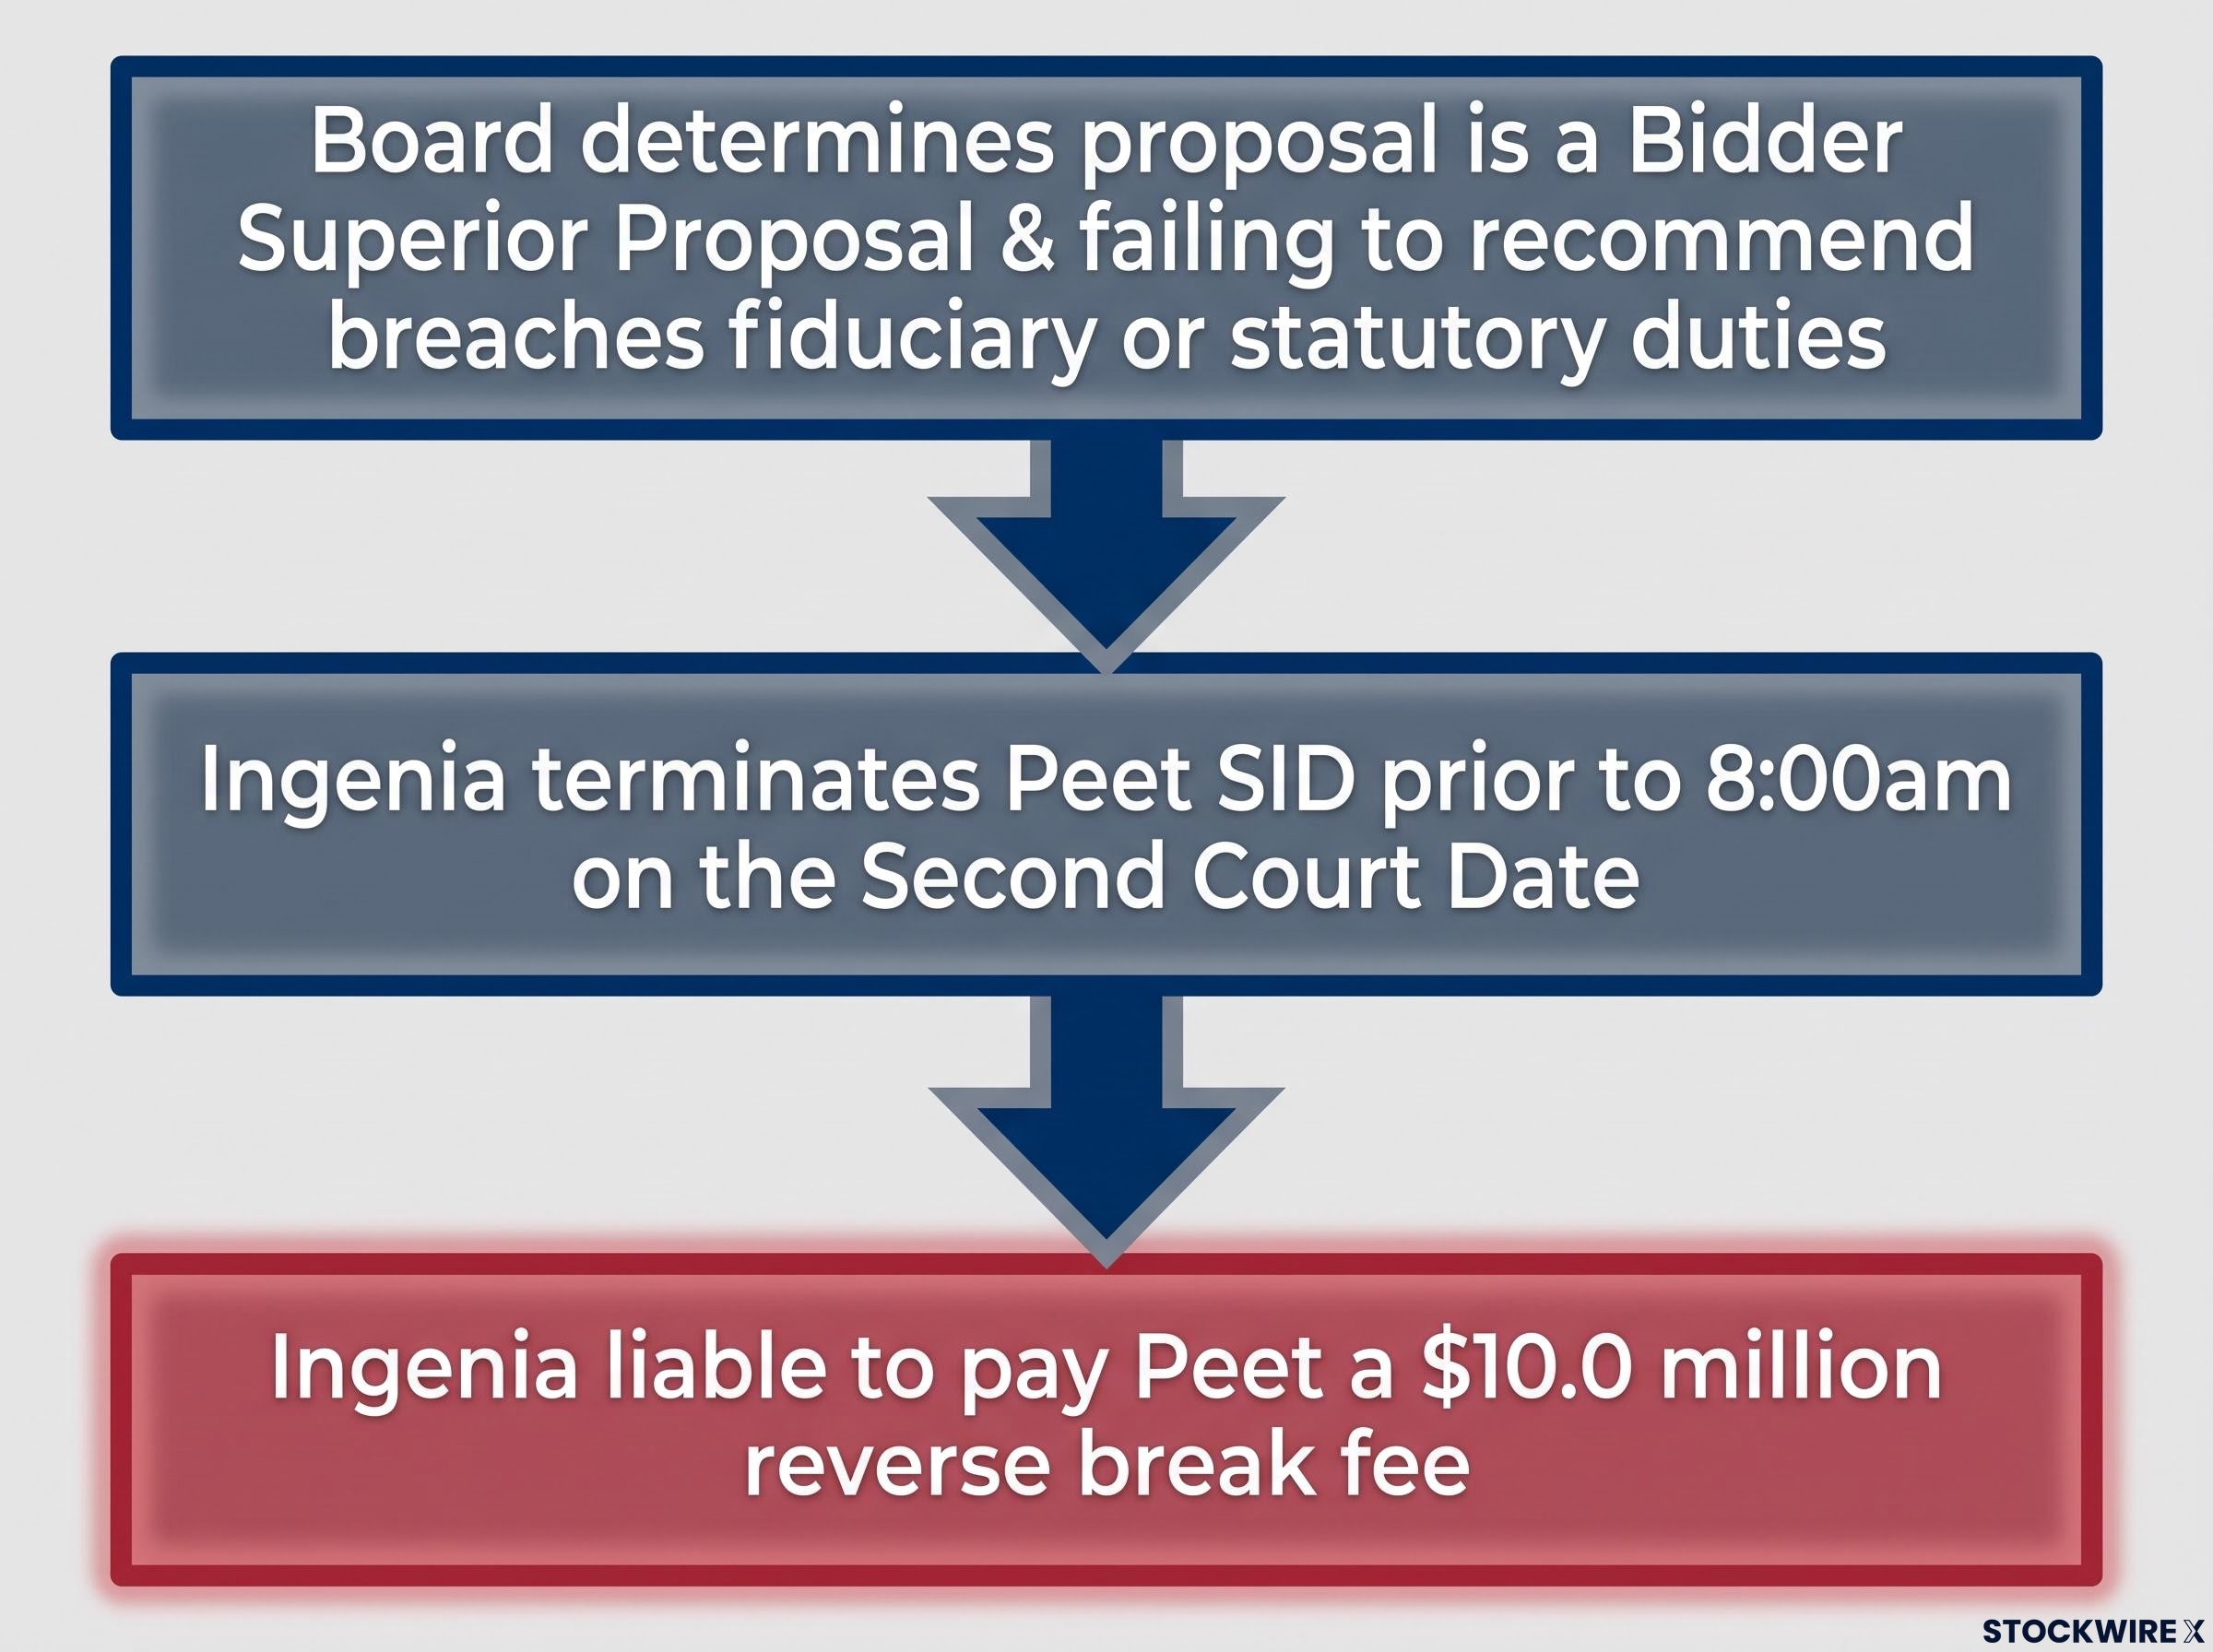
This break fee reflects the contractual weight of the existing Peet arrangement. It signals that the Board’s obligation to act in securityholders’ best interests is governed by a structured framework, not an open-ended discretion.
The Ingenia-Peet merger scheme, announced in late August 2026, structured Peet shareholders receiving 0.3367 Ingenia securities plus $0.68 cash per share, with the combined group projected to reach a $2.4 billion market capitalisation and qualify for S&P/ASX 200 inclusion.
The Board has confirmed it has implemented a robust governance and evaluation framework to assess and respond to proposals with regard to the best interests of Ingenia securityholders. As it stands, no action is required from securityholders.
Securityholder action
“Ingenia securityholders do not need to take any action in relation to the Further Revised Indicative Proposal.”
Key facts at a glance
| Element | Detail |
|---|---|
| Warburg Pincus proposal price | $5.25 cash per stapled security (less any future distributions paid prior to implementation) |
| Proposal type | Non-binding, indicative; non-exclusive due diligence granted subject to confidentiality arrangement |
| Proposal date | 25 September 2026 |
| Existing deal | Ingenia acquisition of Peet Limited (Peet SID dated 26 August 2026) |
| Reverse break fee (Peet SID) | $10.0 million payable by Ingenia to Peet if Peet SID terminated for Bidder Superior Proposal |
| Board recommendation status | Not determined; no recommendation made to securityholders |
| Securityholder action required | None at this time |
This announcement confirms three things for investors:
- Warburg Pincus has been granted limited, conditional due diligence access on a non-exclusive basis
- The Board has not endorsed the Further Revised Indicative Proposal and has made no recommendation
- The Peet acquisition continues in parallel under the existing Peet SID
Don’t Miss the Next ASX Real Estate Takeover Move
Get FREE breaking ASX real estate news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ subscribers already staying ahead of market-moving developments. Click the “Free Alerts” button at StockWire X to receive the latest updates the moment announcements hit the ASX.