

Heathwood industrial property sold at premium to valuation
Garda Property Group (ASX: GDF) has entered a conditional contract to sell its industrial property at 67 Noosa Street, Heathwood, for $17.5 million, representing a $1.1 million premium above the independent valuation of $16.4 million. The premium equates to 6.7% above independent valuation.
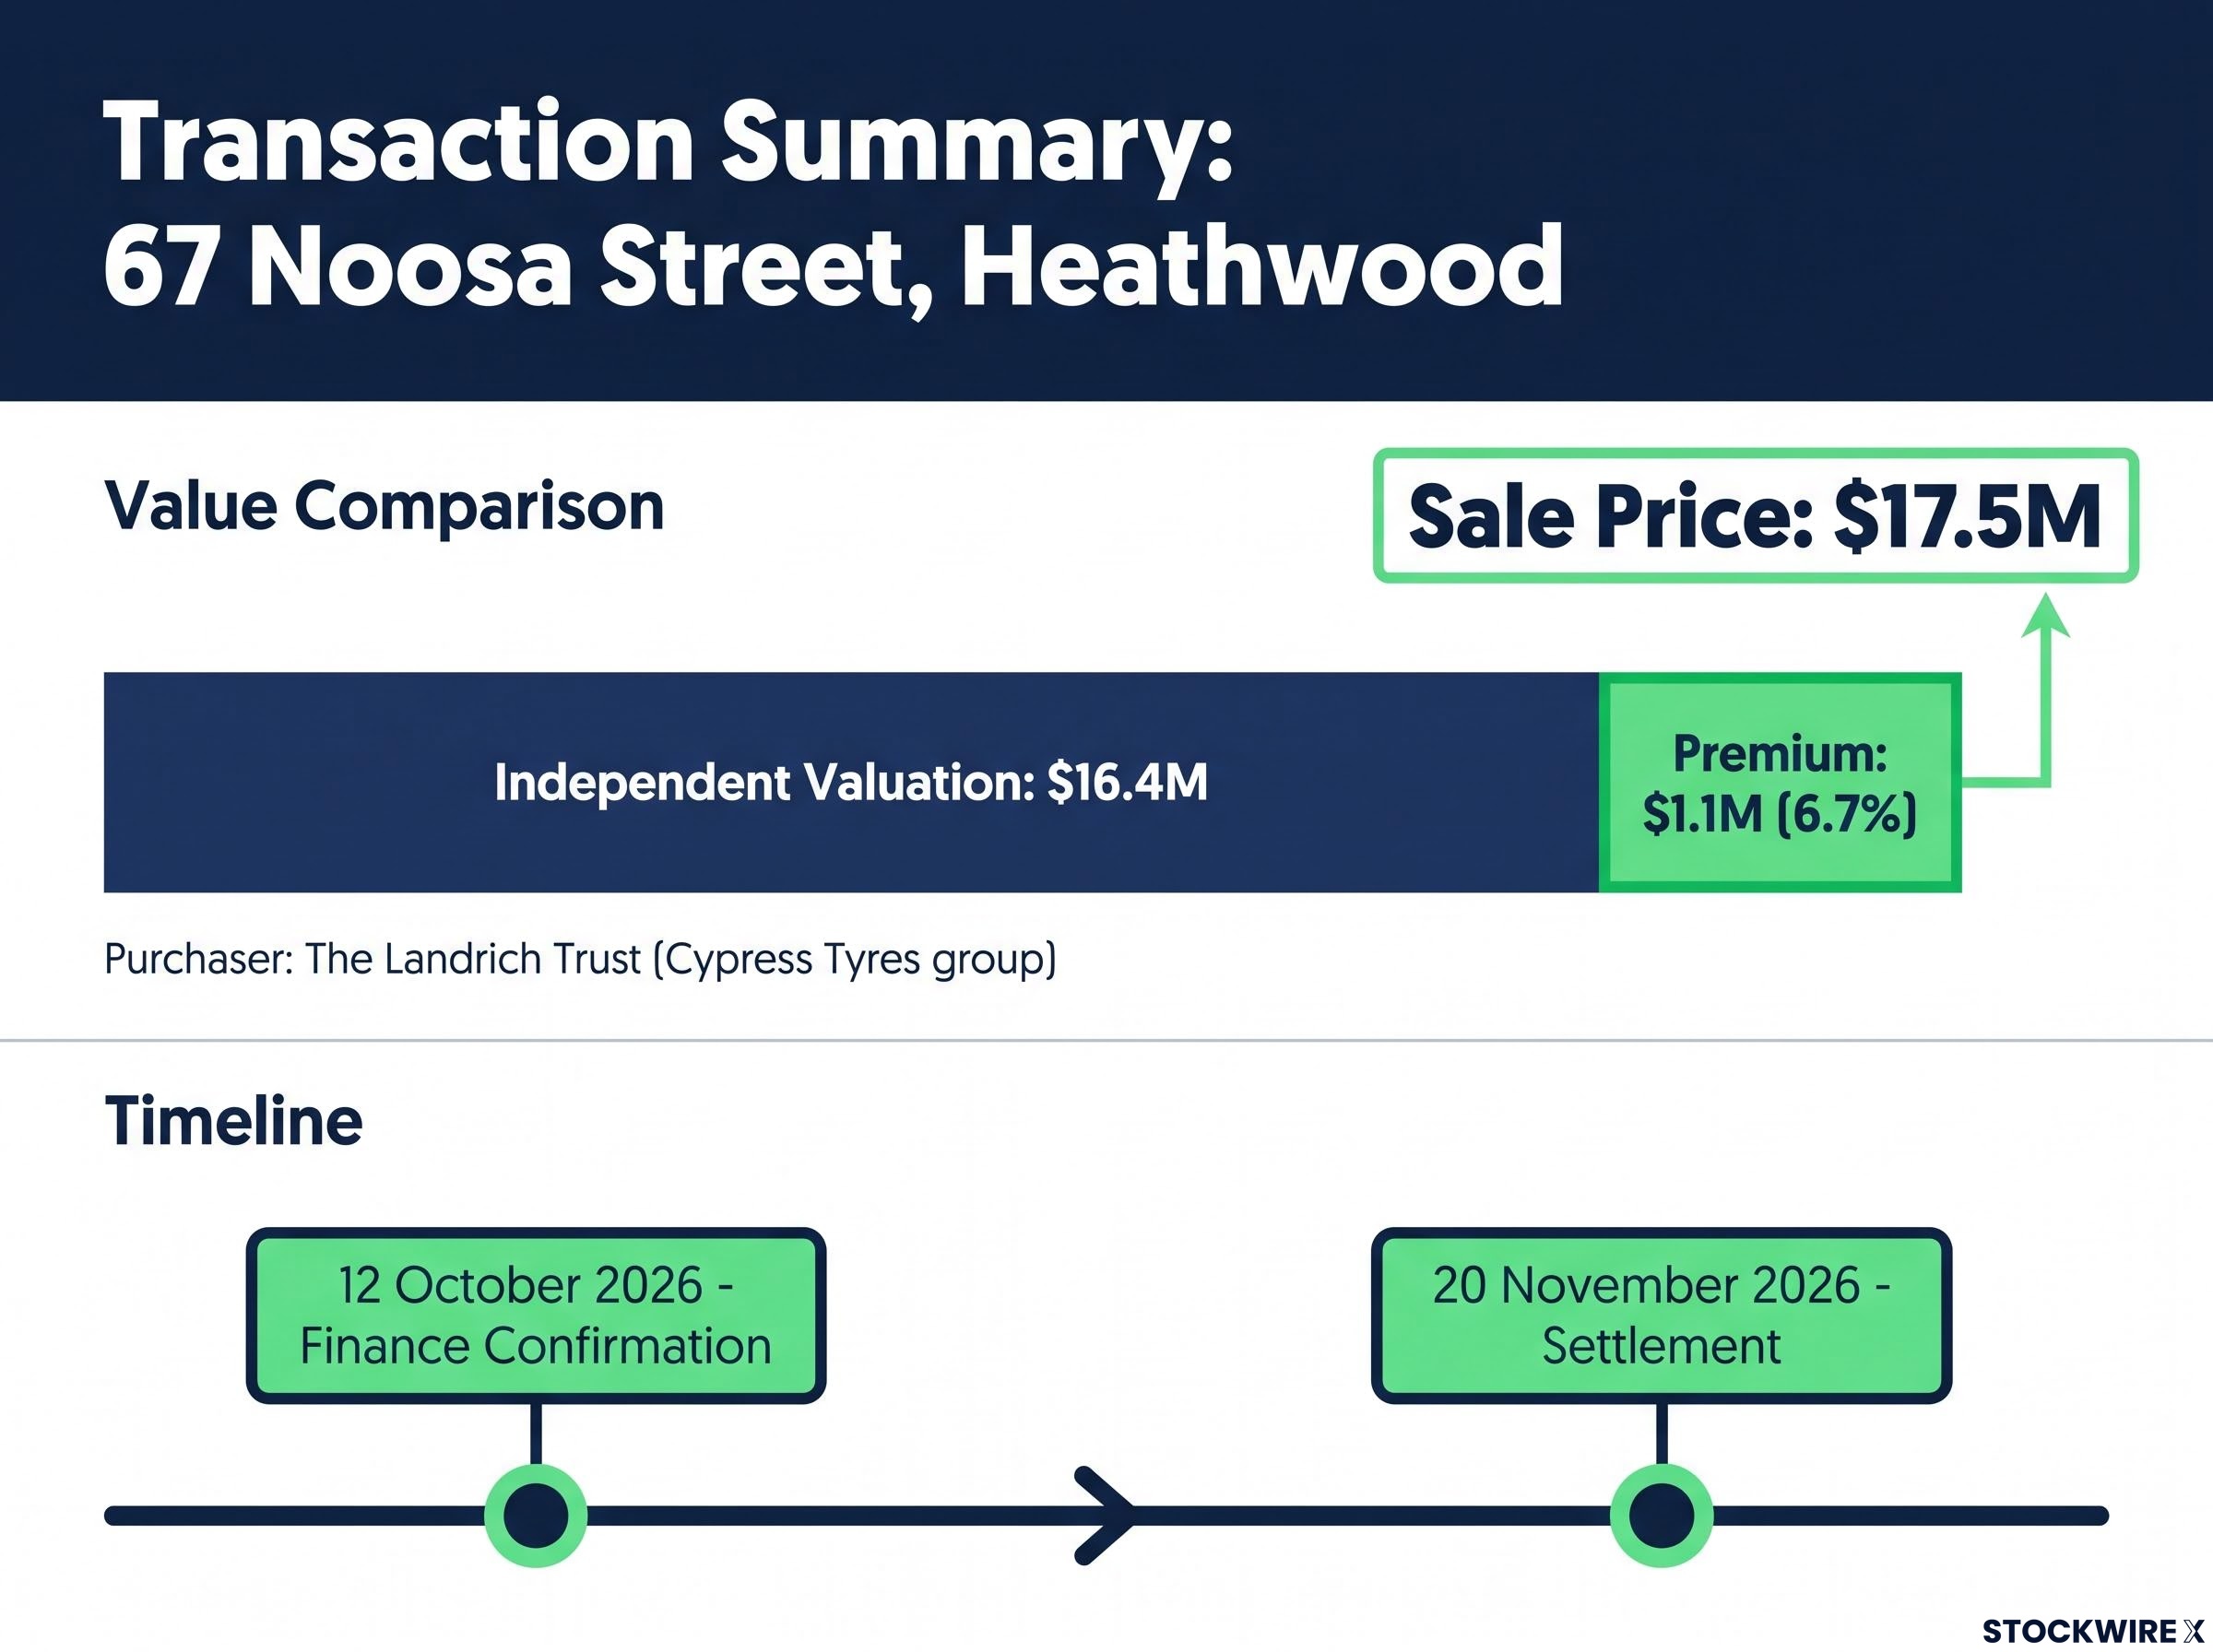
The purchaser is The Landrich Trust, an entity associated with the Cypress Tyres group. The contract is conditional on finance only, with the purchaser required to confirm finance by 12 October 2026 and settlement to occur on or before 20 November 2026.
When big ASX news breaks, our subscribers know first
Balance sheet impact and gearing reduction
Net sale proceeds will be applied directly to reduce Garda’s drawn debt. The Heathwood sale alone is expected to reduce drawn debt by approximately $17.2 million.
Garda FY26 results showed gearing fall sharply from 42.9% to 29.8% over the full year, providing the balance sheet context against which these consecutive asset sales represent a further deliberate step toward a more conservative leverage position.
Post-Heathwood sale metrics are as follows:
- Debt reduction: approximately $17.2 million
- Drawn debt: $158.8 million
- Gearing: 29.0%
- NTA per security: $1.65
Garda also announced the sale of its Pinkenba property on 28 September 2026. On a pro-forma basis, assuming both the Heathwood and Pinkenba sales complete, the combined impact on Garda’s balance sheet would be:
- Total debt reduction: approximately $50.1 million
- Drawn debt: $125.9 million
- Gearing: 23.8%
- NTA per security: $1.64
The table below compares both scenarios, noting the combined figures are pro-forma and contingent on both settlements completing.
| Scenario | Debt Reduction | Drawn Debt | Gearing | NTA per Security |
|---|---|---|---|---|
| Heathwood sale only | ~$17.2M | $158.8M | 29.0% | $1.65 |
| Heathwood + Pinkenba (combined pro-forma) | ~$50.1M | $125.9M | 23.8% | $1.64 |
What this means for Garda investors: understanding gearing and NTA
Gearing measures drawn debt as a proportion of asset value. For a listed property trust, lower gearing generally signals a stronger balance sheet and reduced financial risk, providing more capacity to manage interest costs and navigate market cycles without being forced into distressed asset sales.
NTA, or net tangible assets, per security represents the underlying value of the trust’s assets minus its liabilities, divided by the number of securities on issue. When a property is sold above its independent valuation, as is the case here, the excess proceeds can support or grow NTA rather than erode it. With two asset sales announced across two consecutive days, Garda is materially reducing its leverage and moving to a more conservative gearing position.
Brisbane industrial portfolio valuations across Garda’s eight properties delivered a 2.5% uplift to $340.56 million at June 2026, with the weighted average capitalisation rate of 5.88% reflecting the same sustained investor demand that supported the Heathwood sale above independent valuation.
What comes next for Garda
The immediate milestones are finance confirmation by 12 October 2026 and settlement on or before 20 November 2026, at which point proceeds will be applied to reduce drawn debt. No other use of proceeds has been disclosed. The outcome of the Heathwood sales campaign, achieved at a 6.7% premium to independent valuation, demonstrates Garda’s capacity to transact above independent valuation in the current market.
Don’t Miss the Next Property Sector Move on ASX
Get FREE breaking ASX real estate news delivered to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ investors who never miss a market-moving announcement. Click the “Free Alerts” button at Big News Blast to stay ahead of the market the moment news drops.