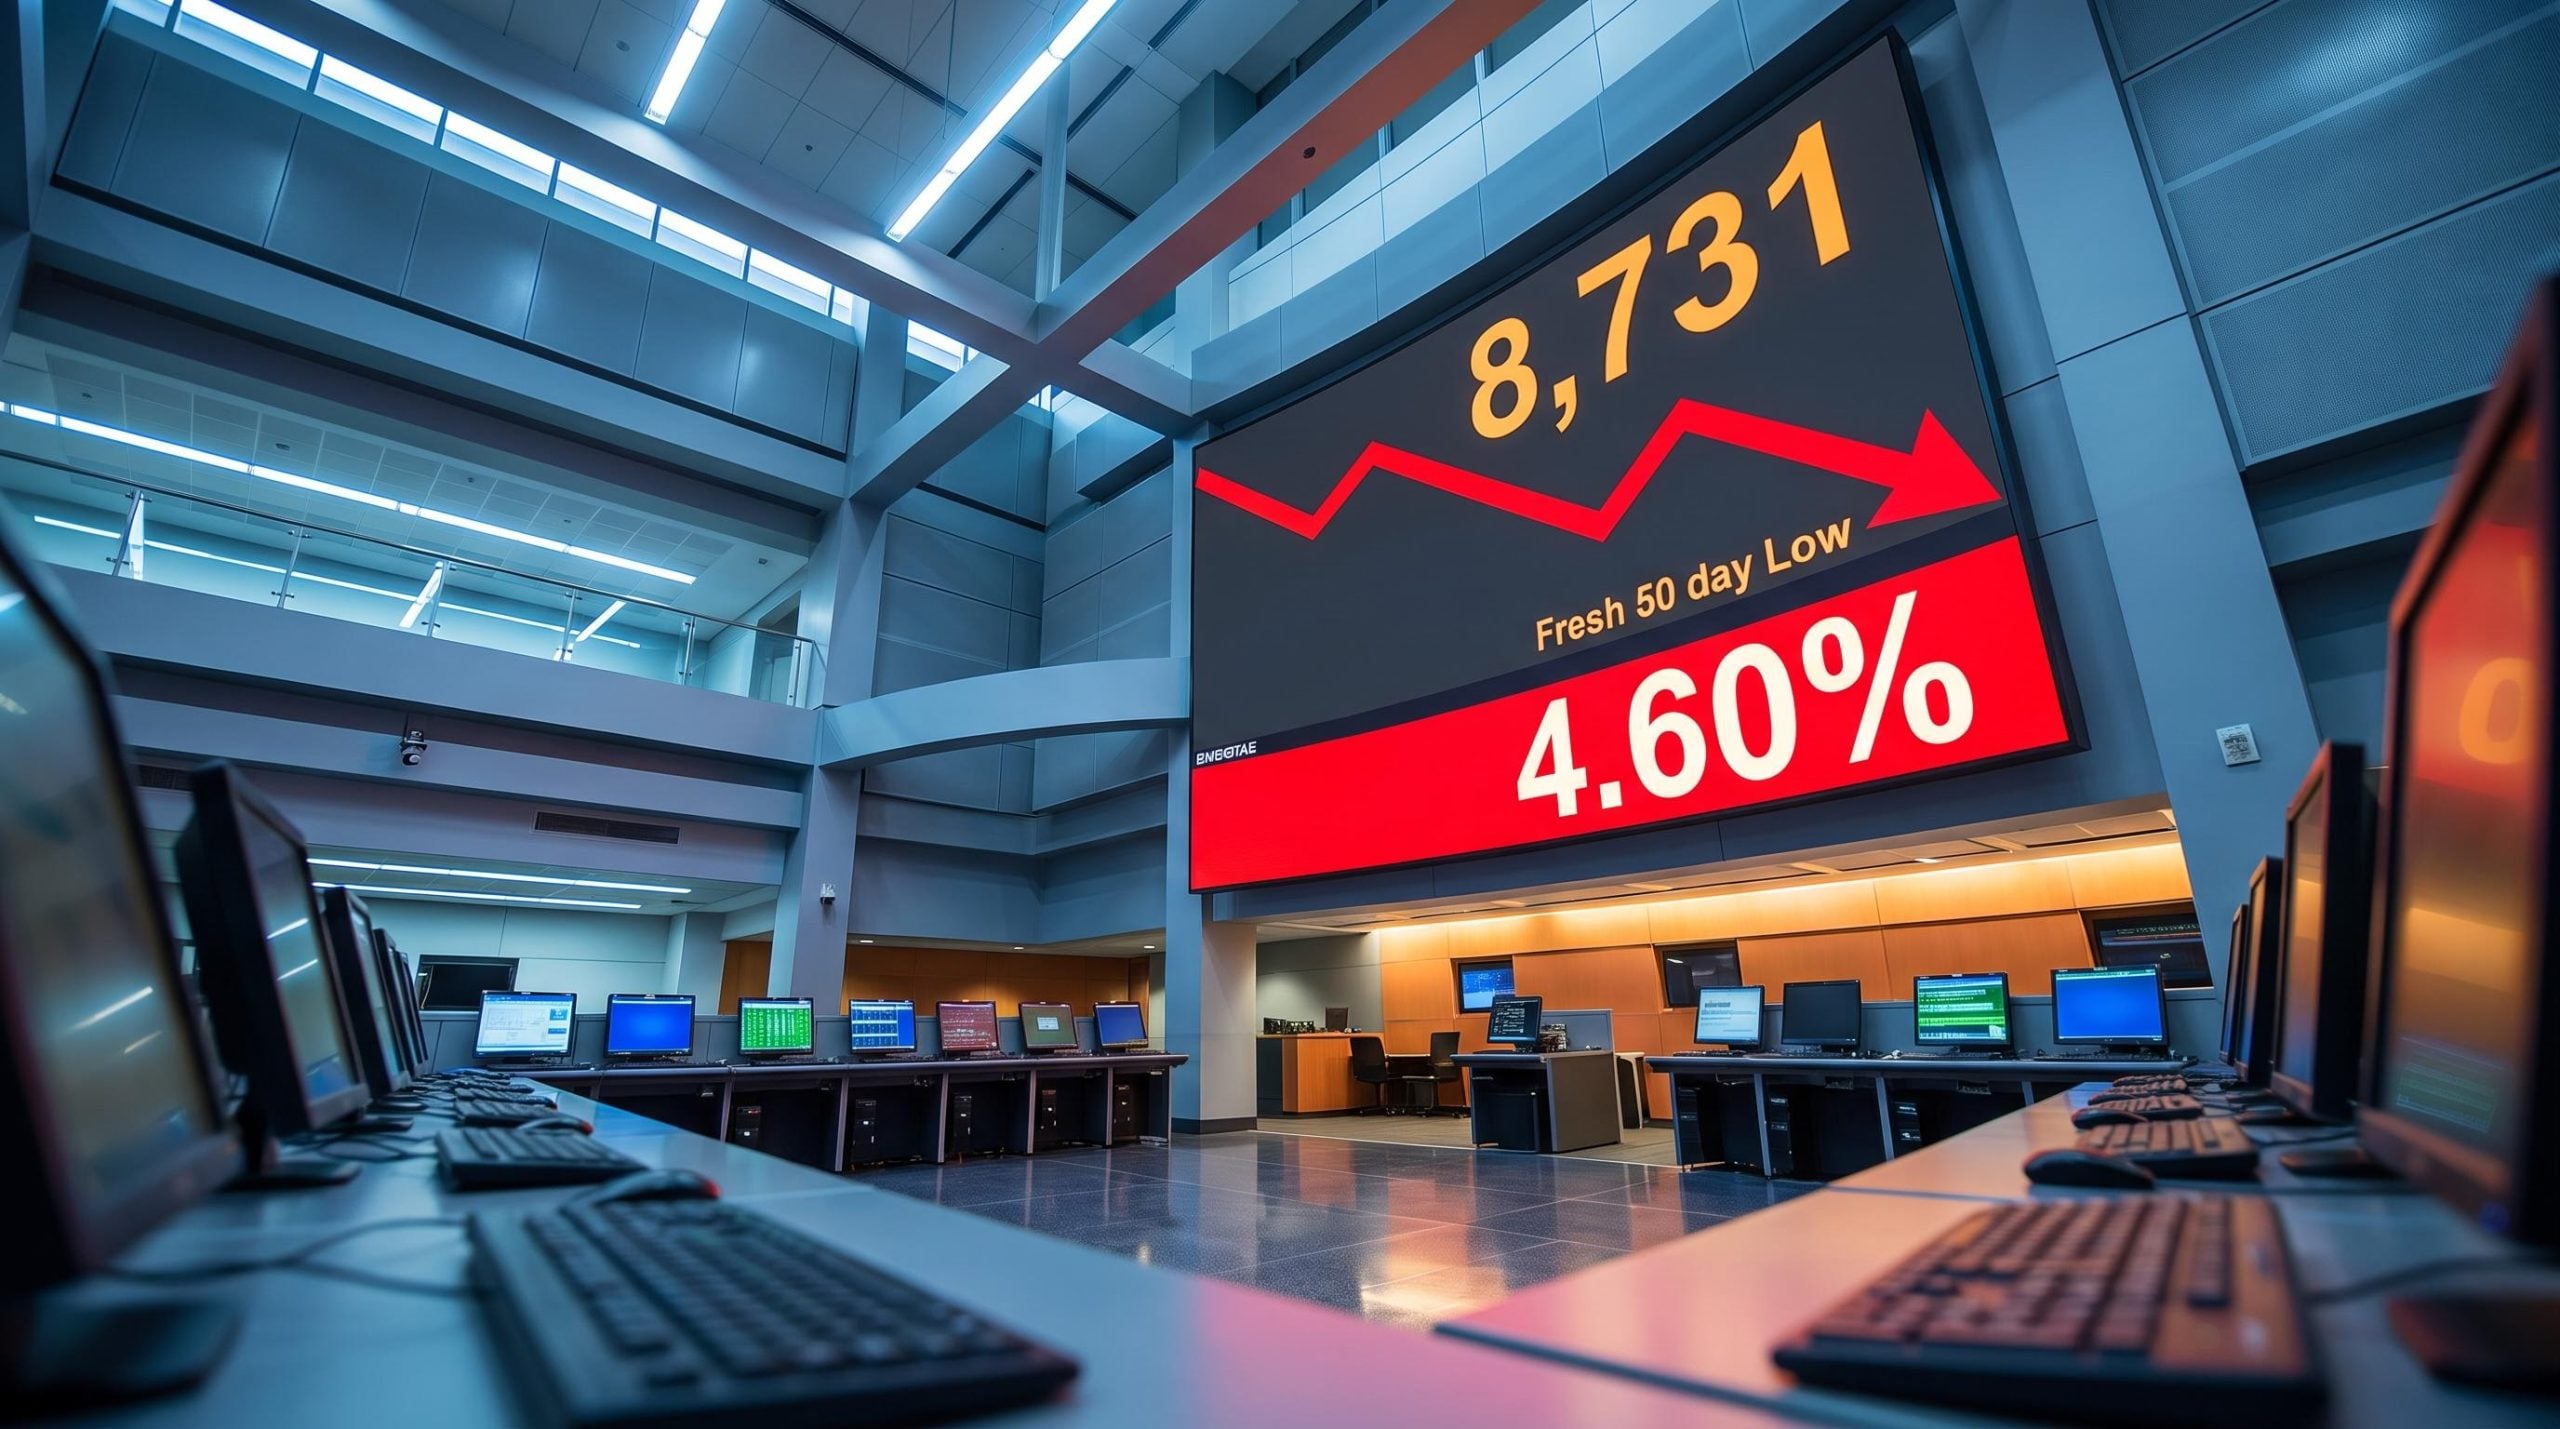
Markets are pricing a greater than 90% probability that the Reserve Bank of Australia (RBA) will lift the cash rate to 4.60% tomorrow afternoon, and the ASX 200 has just recorded a new 50-day low heading into the decision.
But the RBA rate decision on 29 September 2026 is not really about a single 25 basis point move. It is about what Governor Michele Bullock signals next.
The tone of her press conference and the language in the written statement will shape how investors position across the 3 November and 8 December meetings. ANZ is already forecasting the cash rate reaching 4.85% before year-end, a level not seen since late 2008.
After reading this, you will know what to watch beyond the headline number today, and why the press conference matters more than the announcement itself.
You will also know which parts of your portfolio face the sharpest adjustment in a rate environment that is at 4.60% and climbing.
What the market is pricing in, and what a 4.60% rate actually means
By the morning of 28 September 2026, financial markets had assigned a greater than 90% probability to a 25 basis point increase. This is not a forecast anyone is waiting to confirm. It is the established base case.
A move to 4.60% would be the fourth RBA hike of 2026, coming after two consecutive holds at 4.35%, on 16 June and 11 August. The current rate has been effective since 12 August 2026.
Here is the shape of the decision at a glance:
- Current cash rate: 4.35%, unchanged since 12 August 2026
- Expected rate after today: 4.60% (a 25 basis point rise)
- Next two RBA meetings: 3 November and 8 December 2026
The near-certainty extends beyond market pricing. The ANU Crawford School Shadow Board, a panel of economists that publishes its view on where rates should sit, assigns a 70% probability that lifting the rate above 4.35% is the optimal call.
ANU Crawford School Shadow Board, September 2026 A 70% probability that raising the overnight rate above 4.35% is optimal, versus 26% for a hold and just 4% for a cut. The rationale: persistent inflation and resilient economic activity that risk keeping prices above target without further tightening.
So if the outcome is close to settled, where is the information? Not in the rate itself.
The July inflation overshoot, where trimmed mean CPI held at 3.6% against a 3.5% forecast, collapsed rate-cut probability from above 80% to just over 60% within hours of the release, providing the clearest recent evidence that underlying price pressures have not yet responded to the existing tightening cycle.
The real content this afternoon sits in the language Bullock uses about November and December. When the decision is already priced, the market reaction depends on the forward tone, not the number. That is why the smarter move today is to watch the press conference, not the announcement.
When big ASX news breaks, our subscribers know first
Why the RBA paused twice before pulling the trigger in September
The two holds earlier this year were not signs of hesitation. They were a deliberate sequence.
The 11 August hold at 4.35% was the second consecutive pause, and ABC News coverage at the time framed it as a decision to assess the cumulative impact of prior tightening. Monetary policy works with a lag: rate rises take months to feed through to household spending and employment. The Board wanted time to see that flow-through before moving again.
The August hold decision was framed by the Board as maintaining restrictive settings rather than signalling an end to the cycle, a distinction that proved consequential when ANZ revised its terminal rate forecast higher just weeks later.
Crucially, the August hold was framed as maintaining restrictive settings, not ending the cycle. Reuters reported on 18 September 2026 that Bullock warned inflation risks were still materialising even after the pause.
What ‘back to normal’ means for the path ahead
The clearest signal came from a parliamentary hearing. On 18 September 2026, Bullock, Deputy Governor Andrew Hauser, and Assistant Governors Sarah Hunter and Brad Jones described the current rate setting in plain terms.
Governor Michele Bullock, parliamentary hearing (ABC News, 18 September 2026) RBA leadership characterised rates as “just back to normal.”
That single framing carries weight, and not only because four senior officials stood behind it. Economists read “back to normal” as the RBA describing 4.35% as roughly neutral, not restrictive.
Here is why that matters to you. If 4.35% is merely neutral, then 4.60% becomes the first genuinely restrictive setting of this cycle. That changes the calculus for how far the Board is willing to push.
ANZ’s economics team responded directly to Bullock’s guidance. On 22 September 2026, ABC reported ANZ had added both a September and a November hike to its forecasts, taking the cash rate to 4.85%, the highest since late 2008.
The takeaway for your positioning is straightforward: the RBA does not yet believe it has done enough. Rate risk is not priced out of the market. There is more distance in this cycle than the two holds suggested.
How the ASX 200 has behaved around RBA decisions, and what four weeks of losses signal
The recent pattern is clear. When the RBA held, the market edged up. When it hiked, the market pulled back, even when the move was expected.
| Decision date | Outcome | ASX 200 move | Closing level |
|---|---|---|---|
| Earlier 2026 | Hike to 4.35% | -0.2% (rattled sentiment) | 8,680 |
| 16 June 2026 | Hold at 4.35% | +0.04% | 8,917 |
| 11 August 2026 | Hold at 4.35% | +0.2% | Higher on the day |
The detail that stands out from the earlier hike is that a widely anticipated move still knocked the index down 0.2%. Even priced-in tightening can produce a short-term drawdown.
That history frames what is happening right now. The conditions heading into this decision are notably weaker:
- The ASX 200 fell 0.4% on Friday 26 September 2026
- The index recorded a new 50-day low that same session
- The market has now declined for four consecutive weeks
- Futures were trading sideways ahead of the decision, a wait-and-see posture
- September has historically been a seasonally weak month, and this year has followed that pattern
There is nuance underneath the weakness. ABC’s 21 September 2026 markets blog reported the ASX 200 flat at 8,731 points, with banks rising as miners fell, after major banks brought forward their September hike forecasts.
A new 50-day low ahead of a near-certain hike tells you something important. Equity markets are not treating this as a non-event, and they are not waiting for confirmation before repositioning. Some of the rate-hike pain is already being absorbed.
The ASX 200 record high of 9,202.9 set on 26 February 2026 now sits roughly 470 points above the current index level, with three RBA hikes in four months identified as the primary mechanism that converted a broad-based breakout into a sustained Q2 trading range.
That matters for what happens next. Today’s market reaction will reveal how much tightening beyond September is already priced, not simply whether the hike surprises anyone.
Which parts of your portfolio face the most pressure as rates climb toward 4.85%
The one-day divergence on recent decision days is worth reading as a structural pattern, not noise. Banks and insurers have gained. Miners and cyclicals have lagged. That split tells you where rate risk is concentrated.
The logic is sector-specific. Banks and insurers draw net interest margin support in a rising rate environment, which cushions them. Property-linked names, discretionary retailers, and leveraged businesses sit at the sharp end, because both asset values and consumer spending are sensitive to higher borrowing costs.
AUD rate differentials with the US, Europe, and Japan have reached as much as 235 basis points at points in the 2026 cycle, meaning the September hike and any November follow-through carry direct implications for the currency, not only for domestic equities and borrowing costs.
| Sector | Rate sensitivity | Key risk or tailwind | Consideration |
|---|---|---|---|
| Banks | Low | Net interest margin support | Relatively better positioned |
| Insurers | Low | Higher yields on investment income | Defensive income appeal |
| Property | High | Asset values pressured by higher rates | Most exposed to further hikes |
| Discretionary retail | High | Consumer spending under strain | Watch cash-flow resilience |
| Resource stocks | Medium | Global growth and commodity demand | Cyclical, lagged on decision days |
When you review holdings, the quality signals that matter most in a higher-rate setting are balance-sheet strength, cash-flow resilience, and pricing power. A higher discount rate punishes weak balance sheets hardest.
The term deposit competition: when cash yields change the income calculus
Higher rates do more than pressure valuations. They change what your cash is worth sitting still.
ANZ terminal rate forecast ANZ expects the cash rate to reach 4.85% following a November hike, the highest level since late 2008 and a return to pre-GFC tightening territory.
With the cash rate at 4.60% today and potentially heading to 4.85%, term deposits now offer meaningfully higher nominal yields. That competes directly with low-growth, high-yield dividend stocks whose entire appeal rests on their yield advantage over cash.
Here is what that ANZ forecast is really asking of you. It is an invitation to audit whether your income-generating holdings can still justify their place against a term deposit paying a competitive, risk-free rate.
The next material data point arrives fast. August 2026 CPI figures are due Wednesday 30 September 2026, the day after the decision, and they will shape the November outlook immediately.
What to watch this afternoon, and before the November meeting
The decision lands this afternoon. Treat the rate itself as confirmation, and put your attention on the signals around it.
Three things to watch today:
- The rate decision language, read as confirmation of the 4.60% move rather than a surprise
- The written statement’s signals regarding the 3 November meeting and the pace of further tightening
- The tone of Bullock’s press conference on how high rates might ultimately go
Then comes the sequence that defines the next five weeks:
- August CPI on Wednesday 30 September 2026, the first read on whether inflation is easing
- The 3 November 2026 meeting, ANZ’s expected hike to 4.85%, the scenario to stress-test against
- The 8 December 2026 meeting, still a live event, not a foregone conclusion
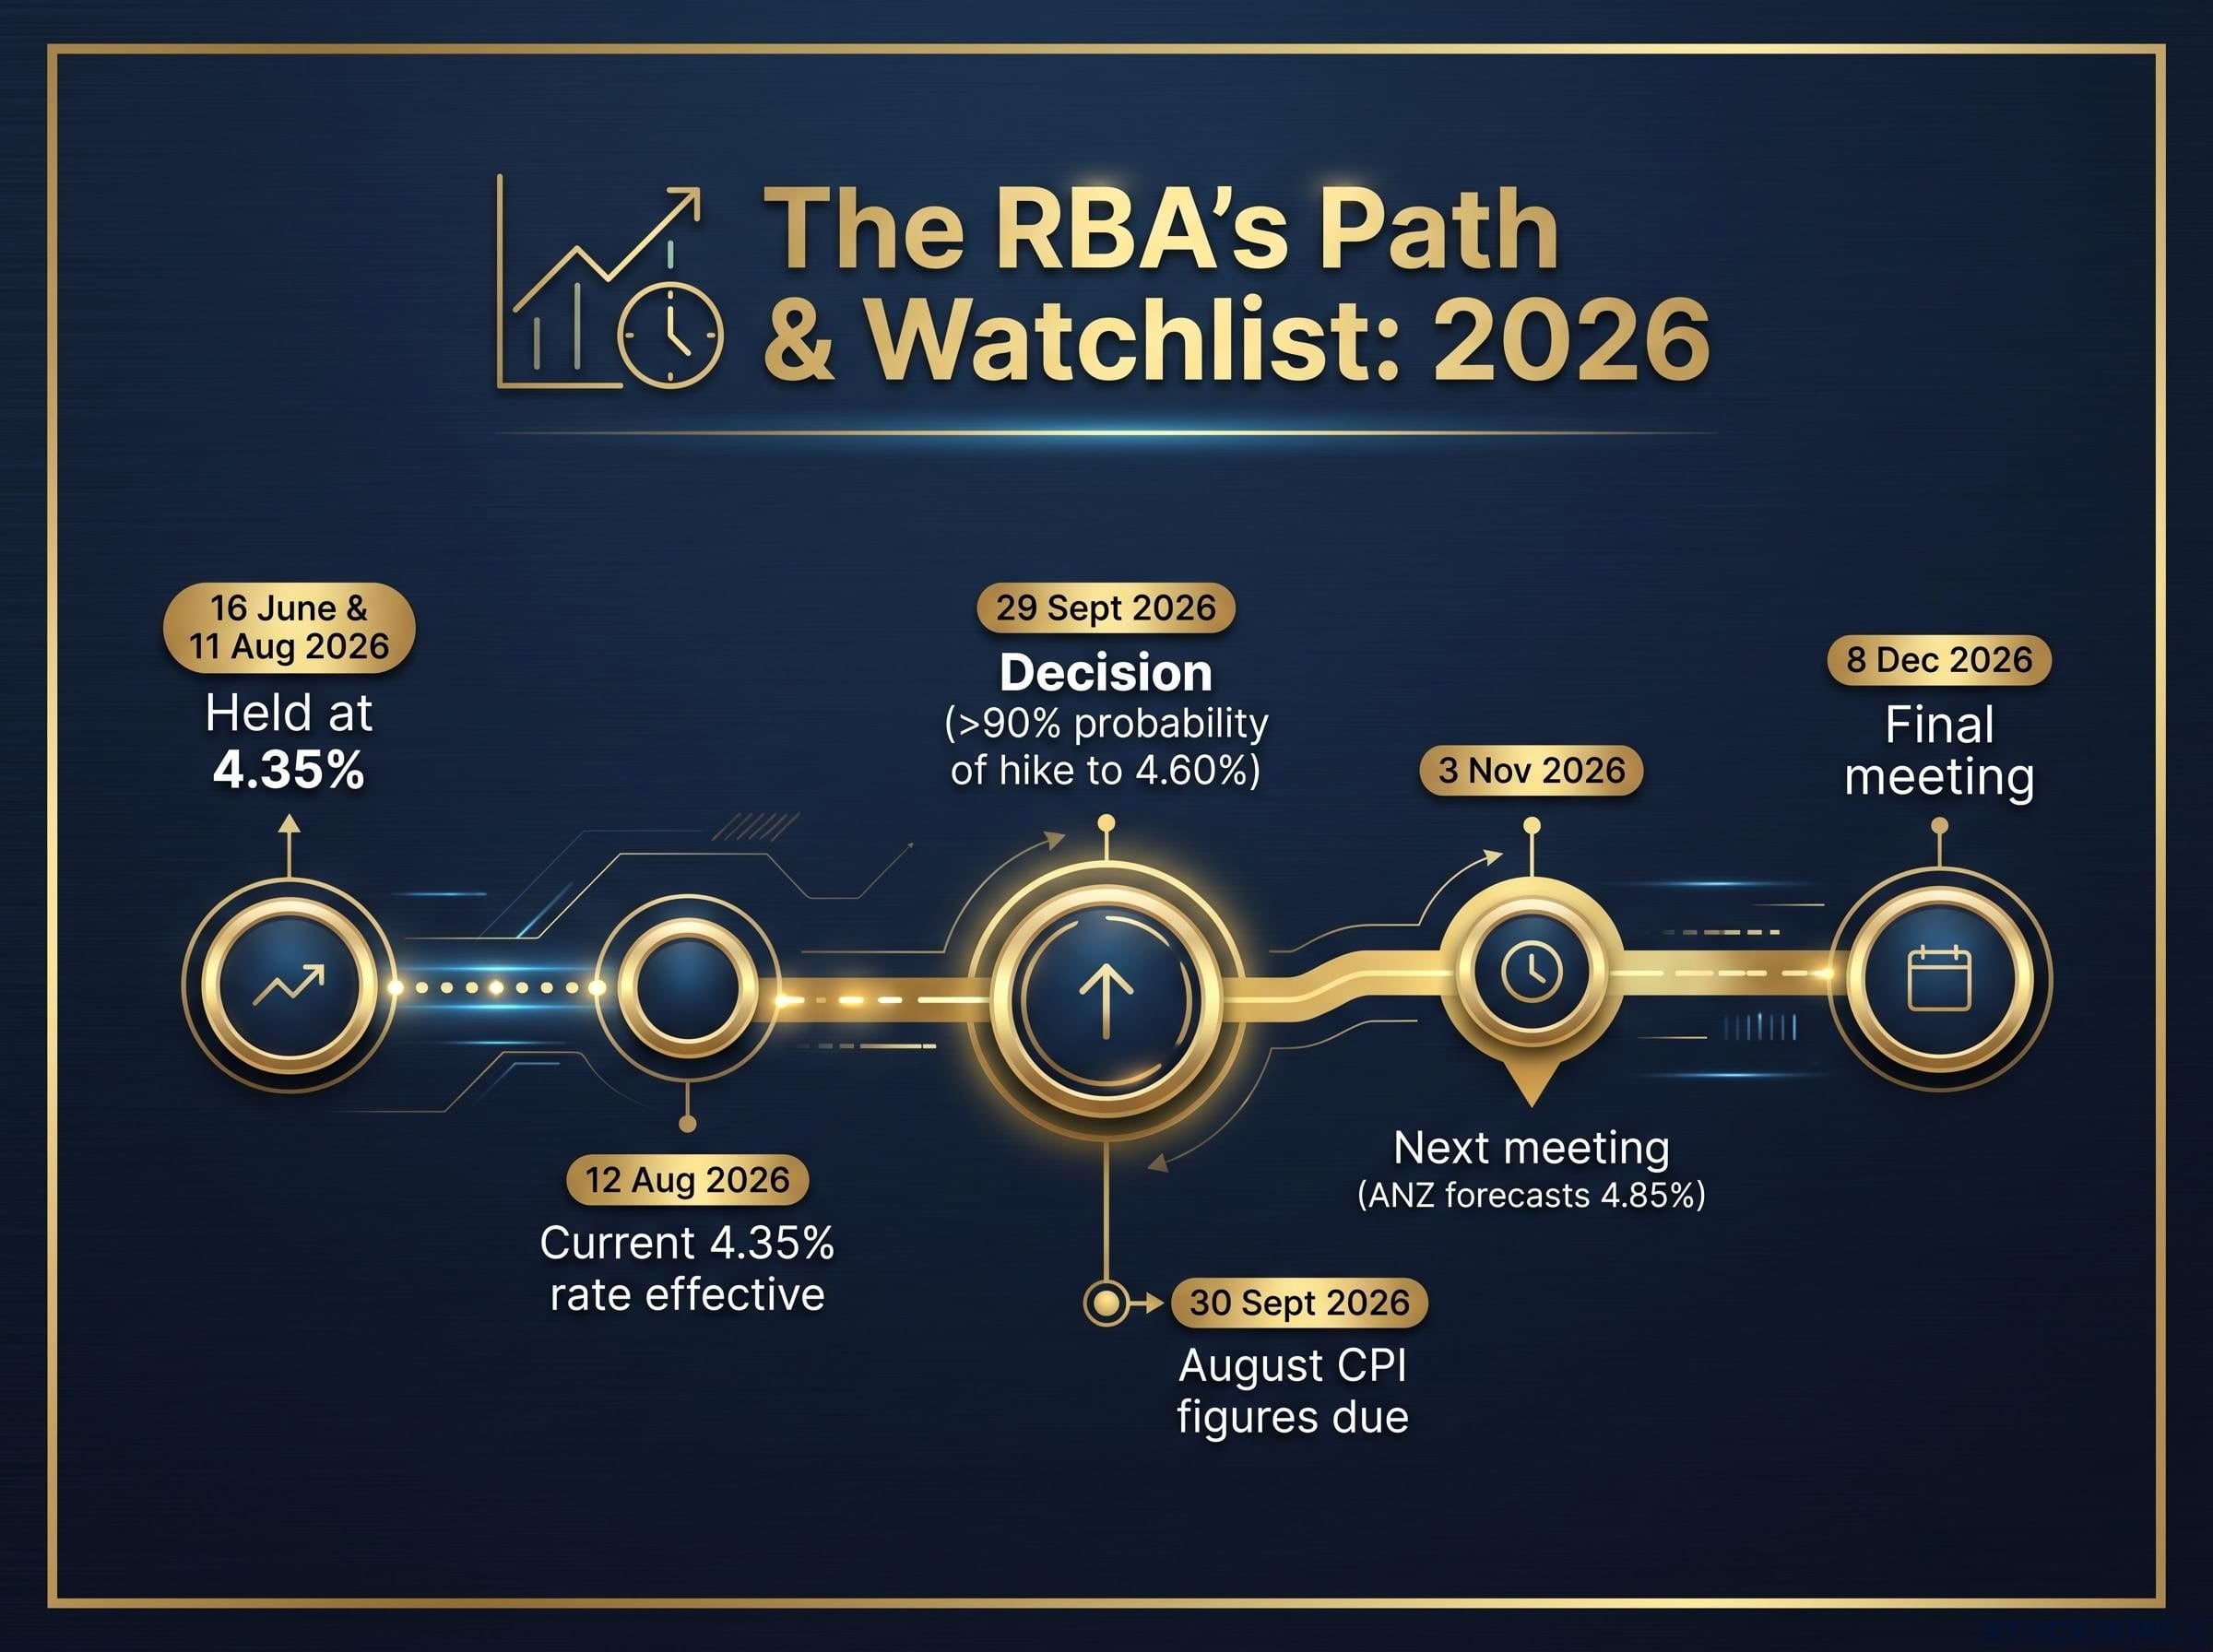
Think of these as a three-step information ladder. Today’s statement, tomorrow’s CPI, then the November decision. Each rung tells you more precisely where the cash rate is heading, and each positioning call you make after a rung is better informed than one made before it.
With the ANU Shadow Board putting only a 4% probability on a cut, the floor on rates is firm. The realistic question is not whether rates fall, but how much further they rise.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments.