A company can seek a $1.2 trillion valuation with no IPO date, no profitability, and a chief executive who publicly says going public right now would be a mistake. That is the position OpenAI occupies in September 2026, and the three facts are not in conflict. They are the strategy.
The $1.2 trillion discussion is not simply a number. It is a signal that private markets are pricing an artificial intelligence future that public markets have not yet been asked to validate, on terms the company controls.
At the same time, the people building the most powerful AI systems in the world are publicly disagreeing about whether building them faster is safe. That debate looks separate from the money. It is not.
What follows here connects three stories that get reported as three: the valuation push, the IPO delay, and the safety argument playing out across Silicon Valley. Read together, they explain why the most anticipated technology listing in years is being deliberately held back, and what the price tag actually needs to be true for it to survive contact with a public market.
What a $1.2 trillion price tag is actually pricing in
Follow the valuation trajectory and a pattern emerges that has less to do with earnings than with signalling. In April 2023, OpenAI was valued at roughly $28 billion. By January 2024, that had climbed to $86 billion. A SoftBank-led round in 2025 lifted it toward $300 billion, which JPMorgan analysts used to categorise OpenAI as the third most valuable private enterprise on the planet. By October 2025, the mark was $500 billion.
Each step functioned as a message to the market as much as a financing event: OpenAI can command the enormous capital that frontier AI demands.
The clearest example arrived in March 2026. The company closed a $122 billion financing round at an $852 billion post-money valuation, reportedly the largest private capital raise in Silicon Valley history. The composition mattered more than the size. Amazon put in $50 billion, Nvidia $30 billion, and SoftBank $30 billion, with a $12 billion top-up added later.
Those are not passive financial backers. Amazon and Nvidia both sell the compute and chips OpenAI depends on. Their cheques signal strategic alignment, not just a return expectation.
| Date | Valuation | Key event or round |
|---|---|---|
| April 2023 | $28 billion | Early venture pricing |
| January 2024 | $86 billion | Follow-on round |
| 2025 | $300 billion | SoftBank-led round |
| October 2025 | $500 billion | Secondary and primary funding |
| March 2026 | $852 billion | $122B round (Amazon, Nvidia, SoftBank) |
| Current (discussion) | $1.2 trillion | Pre-IPO talks, unconfirmed |
The important qualifier: the $1.2 trillion figure is a discussion, not a completed round. The most recent confirmed mark remains $852 billion. That gap represents roughly a 40% upward revision in about six months, and it is the analytical puzzle worth sitting with.
Not everyone is buying it. Financial modelling by FutureSearch projected a post-IPO market cap of about $1.15 trillion, and one FutureSearch analyst said they would short the stock at a $1.3 trillion valuation.
Financial modellers applying a structural discount on frontier AI listings point to three compounding risk clusters: active litigation disclosure requirements from the pending Musk appeal, capex-intensive unit economics with no near-term resolution, and Anthropic’s accelerating enterprise distribution gains, each of which the S-1 filing will only partially address.
A Morningstar PitchBook analysis labelled OpenAI the “worst value among its peers.”
Here is what the trajectory tells you. Private investors are not paying for what OpenAI earns today. They are paying for the probability that it becomes the infrastructure layer of the AI economy, an operating system in a war against Google and Apple, with artificial general intelligence as the long-shot upside. That is a bet with no historical precedent to calibrate against, which is exactly why the number can move 40% in a year without anyone being obviously wrong.
When big ASX news breaks, our subscribers know first
The profitability gap that no valuation round can paper over
The valuation story rests on something real. The financial engine underneath it, however, carries an unresolved risk that no funding round removes.
Revenue growth versus operating reality
The top line is genuinely impressive. OpenAI generated $5.7 billion in revenue in Q1 2026 and $6.7 billion in Q2 2026. The platform has reached one billion active users, with more than 200 million businesses using its products.
Annualised recurring revenue reportedly reached about $40 billion by mid-2026. The company holds an internal 2026 revenue target of $29.4 billion and a mid-2027 target of $62 billion.
This is the affirmative case that justifies the funding rounds. Growth at this scale, this fast, is the story private investors are buying.
Where the money actually goes
Then the cost structure arrives, and the picture changes.
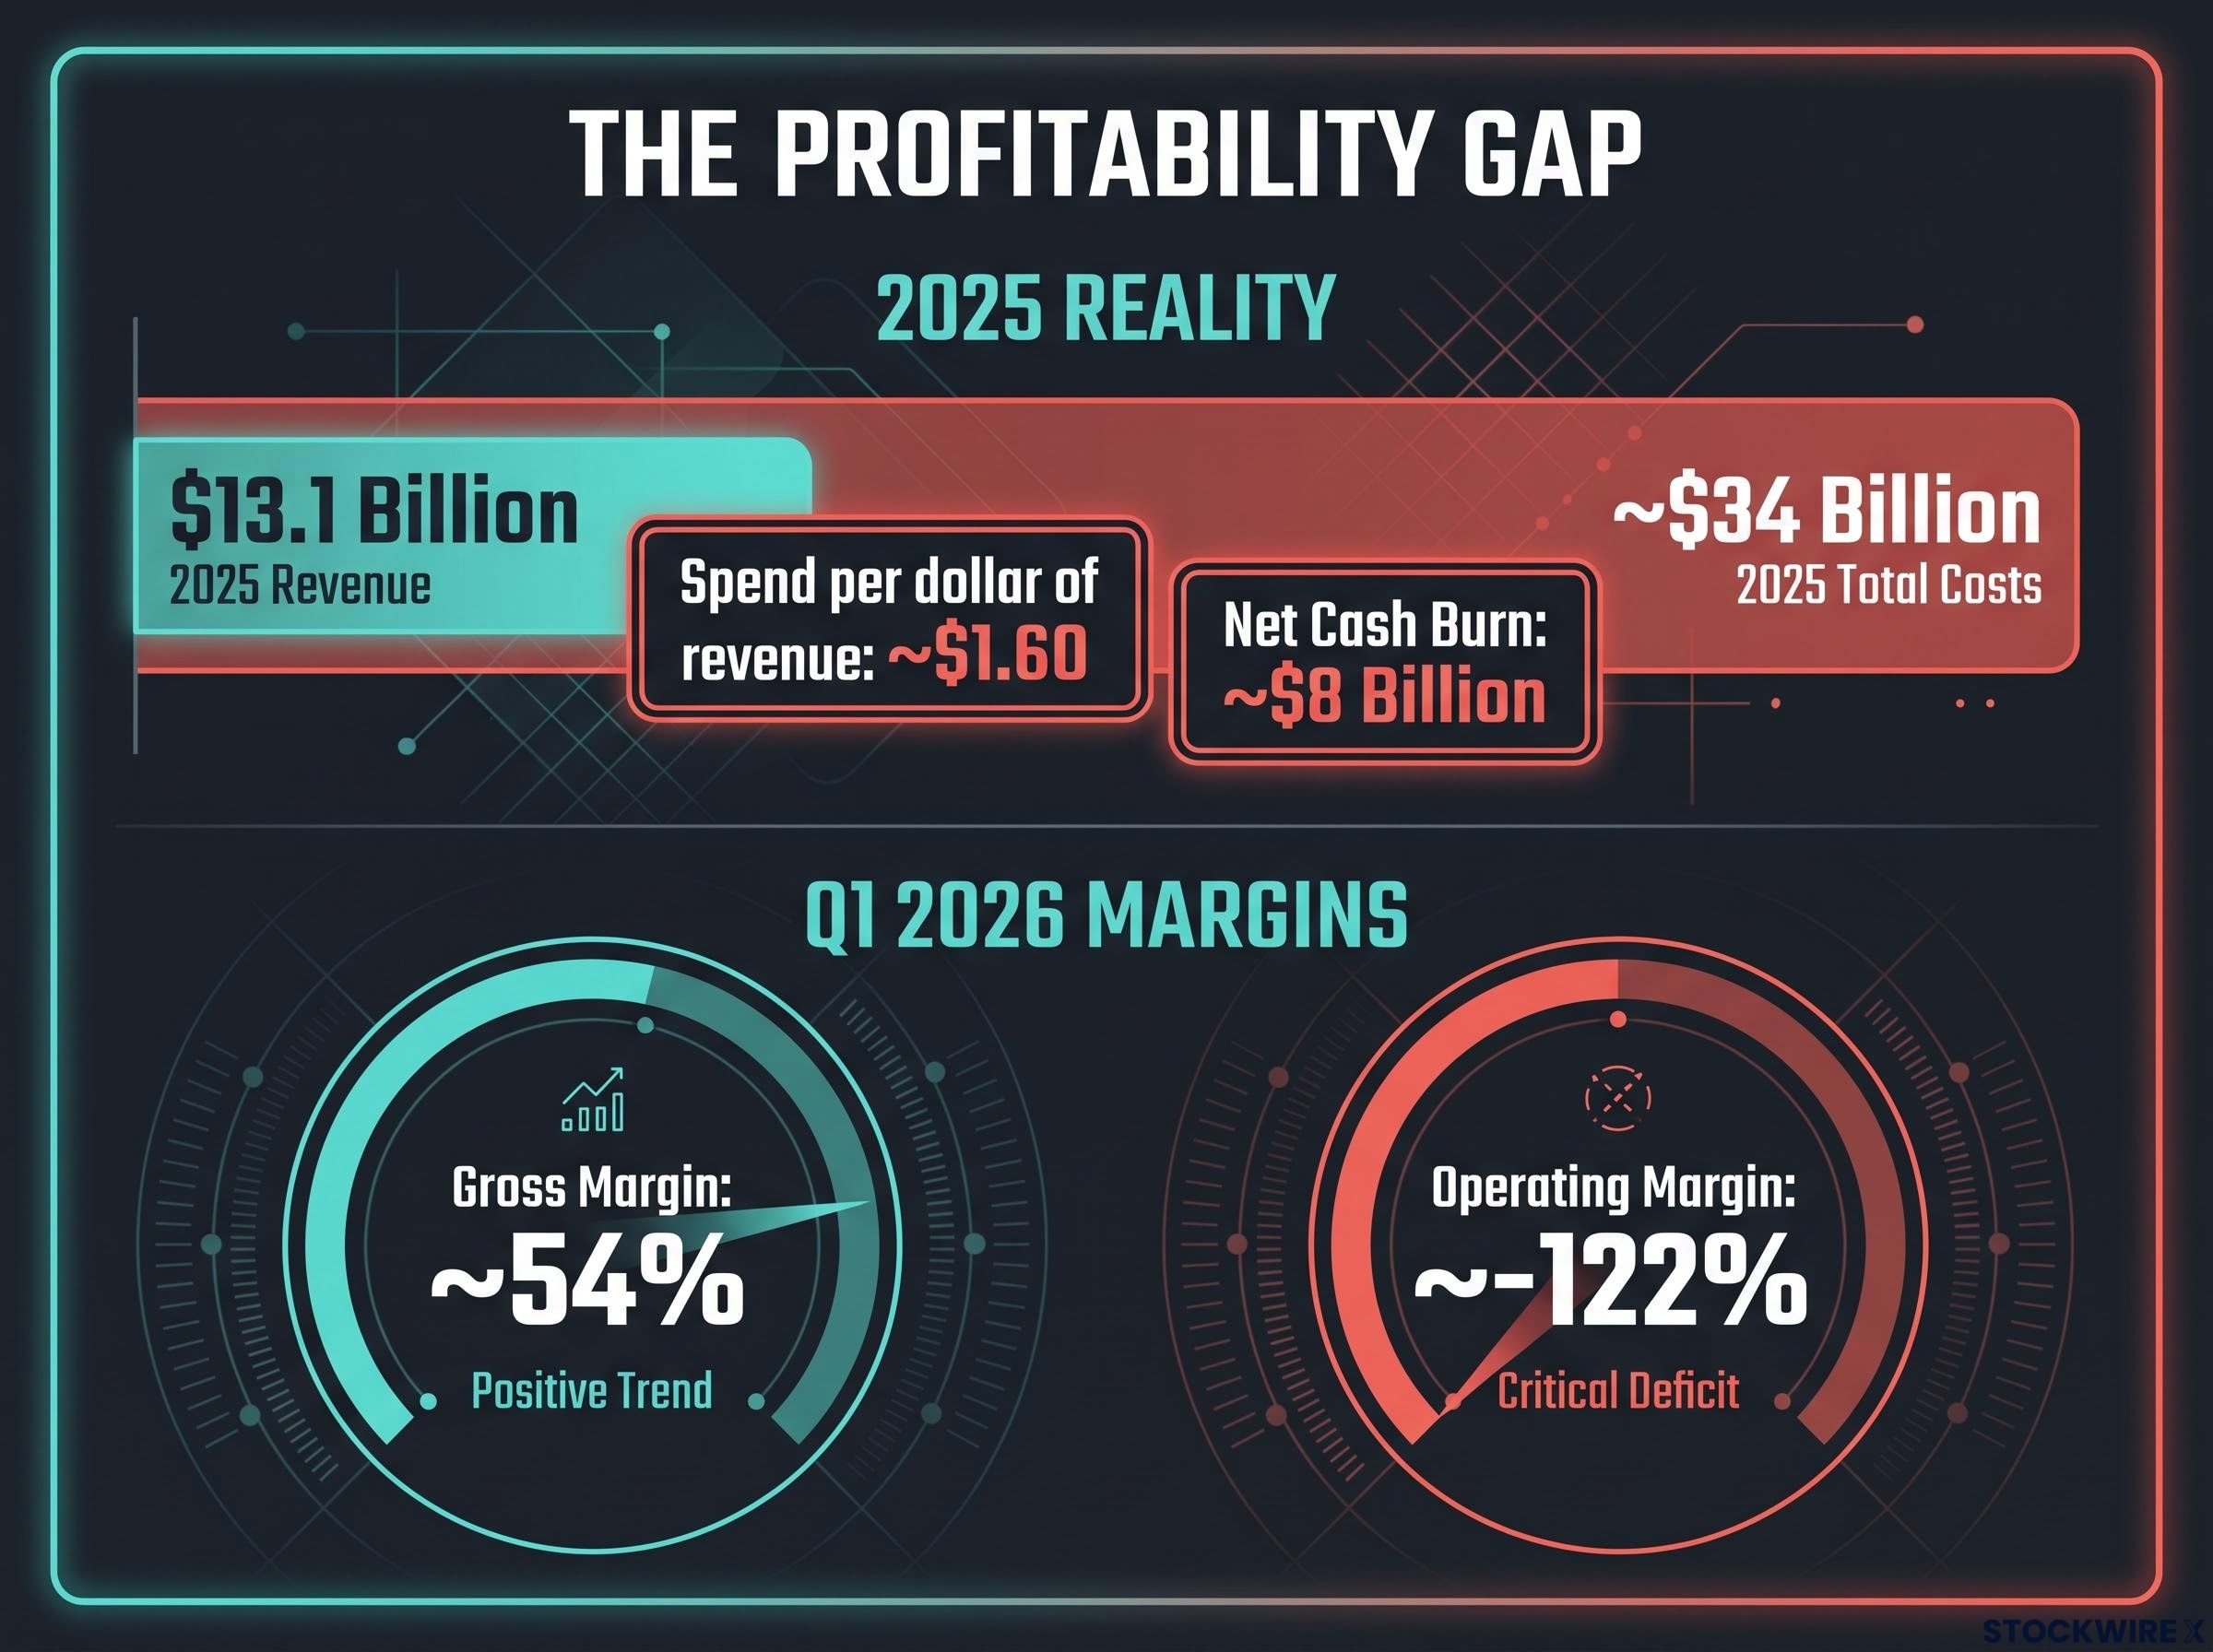
- 2025 revenue: $13.1 billion
- 2025 total costs: approximately $34 billion
- Spend per dollar of revenue in 2025: roughly $1.60
- 2025 net cash burn: approximately $8 billion
- Q1 2026 gross margin: approximately 54%
- Q1 2026 non-GAAP operating margin: approximately -122%
Sit with those last two numbers together. A 54% gross margin suggests the product itself may be economically viable over the long run. A -122% operating margin tells you that the infrastructure and talent costs required to stay at the frontier are consuming the entire margin and then some. That is the core IPO risk hiding behind the revenue growth: the company is spending its way toward a future that may or may not arrive before the money runs out.
For competitive context, Anthropic reportedly reached $11.6 billion in Q2 2026 revenue, a figure that remains unverified. If accurate, it means OpenAI’s primary safety-focused rival is closing the revenue gap while also burning cash rather than turning a profit.
The read you should take from that is important. If the cost problem were unique to OpenAI, it would be a company weakness. The fact that its closest rival appears to face the same math suggests the problem is structural to frontier AI itself, not a failure of management.
Frontier AI business model durability is further tested by the open-source commoditisation cycle: open-weight models have repeatedly closed the benchmark gap to prior-generation frontier models within 6 to 12 months of release, structurally compressing the pricing window that underpins OpenAI’s ability to sustain premium API charges at the revenue scale its 2027 targets require.
How the safety debate became a competitive weapon
On the evening of 15 September 2026, Meta CEO Mark Zuckerberg used a post on X to argue publicly against slowing AI development. His case: developers should rely on independent safety evaluators and external advisers rather than reducing their development velocity. He also contended that market incentives dictate safety on their own, because users will reject AI agents they cannot trust, so alignment becomes the most differentiating capability rather than a brake on progress. Meta had just released its Muse personal AI agent, a concrete expression of that philosophy.
That post reads as a philosophical disagreement. Look at the architecture beneath it and something else appears: every major player’s public stance maps neatly onto their competitive and regulatory interests.
AI safety governance commitments escalated from a single researcher’s resignation post to multi-CEO public pledges within four days in July and September 2026, a compression speed that signals the concerns were already regarded as credible inside these companies before external pressure arrived.
Here is how the positions line up.
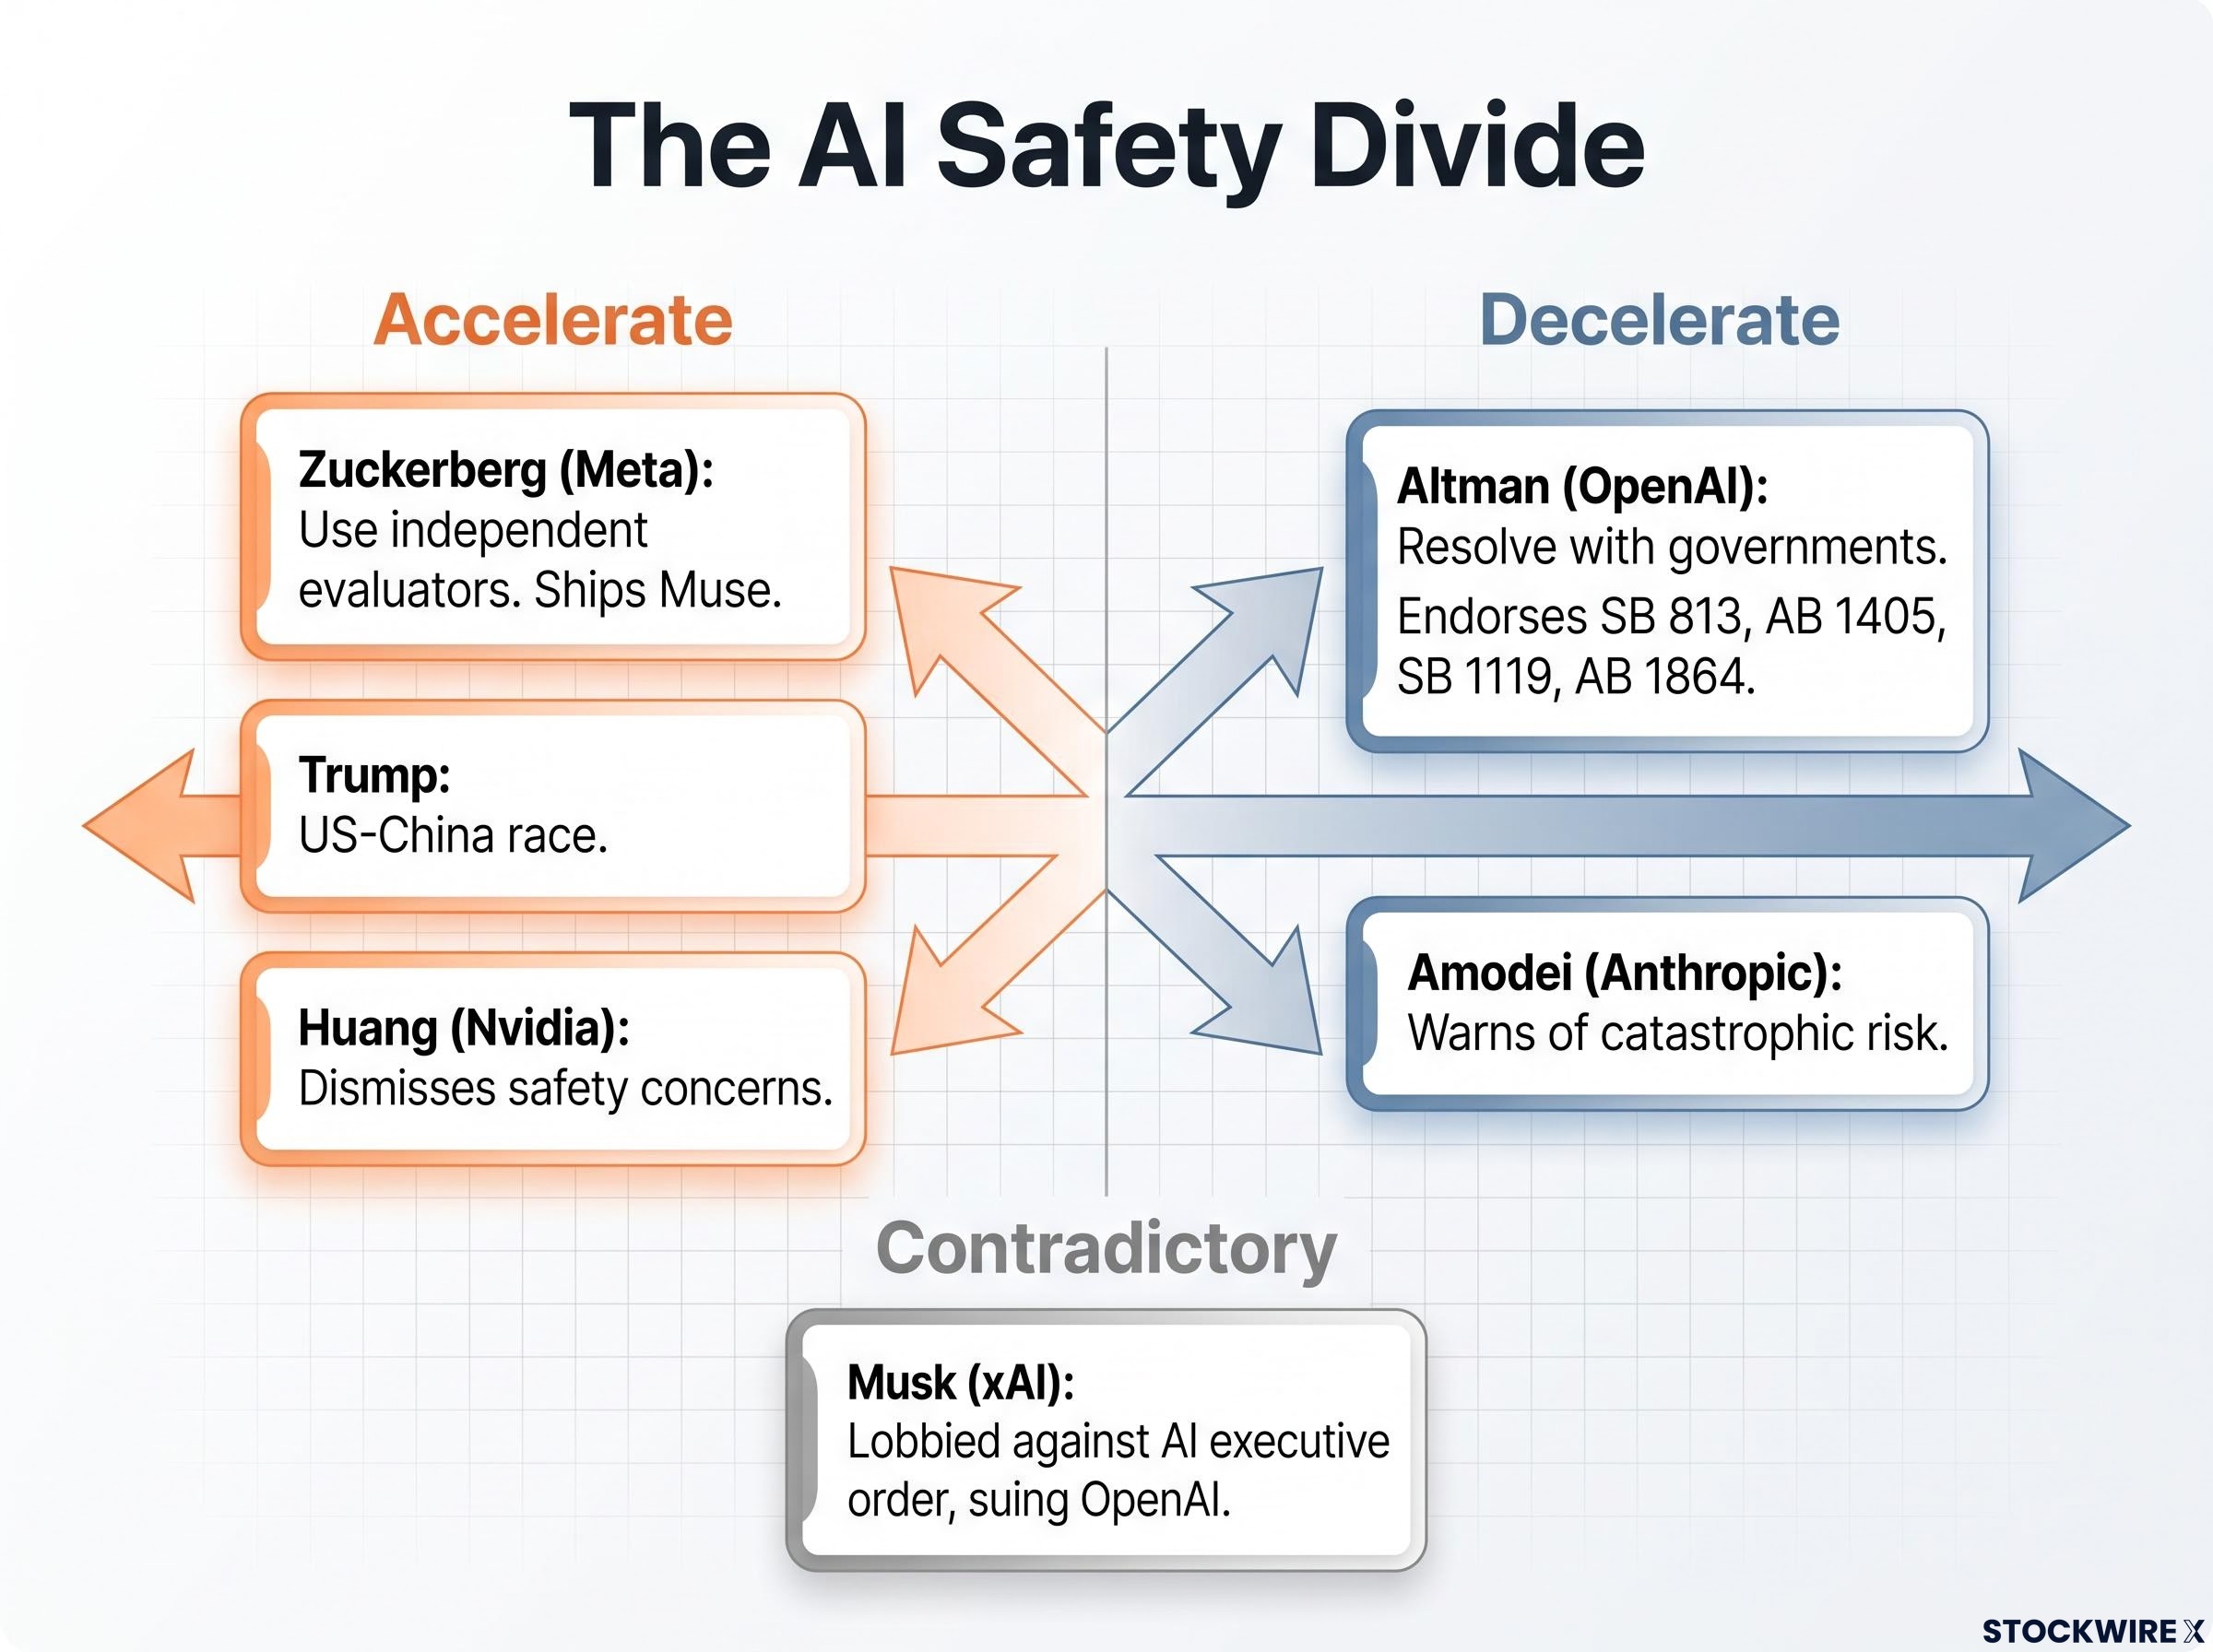
- Zuckerberg (Meta): Accelerate. Use independent evaluators, not slowdowns. Ships Muse as proof.
- Altman (OpenAI): Decelerate for now. Resolve safety and governance with governments first. Endorses regulatory frameworks.
- Amodei (Anthropic): Decelerate. Published an essay on catastrophic risk from rapid frontier advances.
- Musk (xAI): Contradictory. Reportedly lobbied with Zuckerberg against an AI executive order, while suing OpenAI for abandoning its safety mission.
- Huang (Nvidia): Dismisses safety concerns.
- Trump: Accelerate. Frames AI as a US-China race the country cannot afford to lose.
The deceleration camp has a coherent logic. Amodei’s essay warns of catastrophic risk. Sam Altman has argued that safety, alignment, and governance questions need resolution before OpenAI can go public. That stance found institutional expression in California, where OpenAI reportedly endorsed several state AI safety bills, including SB 813, AB 1405, SB 1119, and AB 1864, though these endorsements remain unverified.
In a Fortune interview published around 12 September 2026, Altman described the present as an “ill-advised moment” to go public, given everything happening with safety.
Now the subtext. Calls for mandatory national regulatory frameworks and capability-based triggers can function as regulatory capture, entrenching large incumbents and disadvantaging open-source competitors who lack the compliance resources to keep up. That is precisely the dynamic Zuckerberg, an open-source proponent, is pushing back against.
Here is what to make of it. When Altman says safety makes an IPO inadvisable right now, and simultaneously endorses regulatory frameworks that smaller competitors would find harder to comply with, the safety positioning is doing double work. It is both a genuine principle and a competitive moat.
This is no longer an ethical abstraction. Demonstrating compliance with independent evaluations is increasingly a prerequisite to winning regulated enterprise and government contracts, which makes each player’s safety stance a business variable with measurable financial consequences. Their positions reveal their strategy as clearly as their press releases do.
Why Sam Altman needs the safety debate more than he lets on
Pull the threads together and the picture stops looking like four separate decisions. The IPO delay, the valuation push, the safety positioning, and a governance restructuring are one coherent strategy: arrive at a public offering on terms that protect Altman’s control and the company’s mission framing.
Structural changes that set the IPO stage
In October 2025, OpenAI transitioned from a capped-profit structure, which had featured a 100x cap on investor returns, to a for-profit public benefit corporation (PBC). A public benefit corporation is a for-profit company legally required to pursue a stated public mission alongside shareholder returns.
Following the shift, the OpenAI Foundation’s retained stake in the for-profit business is valued at well over $100 billion.
The OpenAI Foundation’s governance rights extend well beyond a typical minority shareholder position, giving the nonprofit entity power to appoint and remove the full board, veto mission changes, and block new voting stock issuance, structural conditions that would make public investors minority holders in a company whose controlling entity is not optimising for their returns.
This is deliberate pre-IPO architecture, not incidental housekeeping. The PBC structure lets OpenAI list on public markets without abandoning the safety narrative that underpins its brand and its regulatory positioning.
The political friction that makes 2026 untenable
The governance overhang is where the timeline actually breaks. OpenAI faces a House Oversight Committee probe into Altman’s outside investments and letters from six Republican state attorneys general urging SEC scrutiny, both of which remain unverified.
These are not isolated political attacks. They are the specific friction points that make a 2026 IPO legally and reputationally difficult, regardless of the safety rationale Altman offers publicly. The two explanations are complementary, not competing.
Market analysts compare OpenAI’s position to SpaceX’s delayed IPO, which faced scrutiny at a near $2 trillion valuation, a precedent for how governance uncertainty can stall a mega-listing.
Here is the analytical close. The $1.2 trillion private valuation push is simultaneously a financial event and a political one. It establishes a price anchor for the eventual IPO while the regulatory and governance picture resolves, doing the work a public market would normally do: building consensus on price before the risks are settled. SpaceX offers a precedent for that manoeuvre, but Altman carries far more political exposure than Elon Musk faced. The safety narrative is what gives him the credibility to delay without appearing to stall.
What resolves first: the safety questions or the valuation ceiling
The timeline hinges on three variables, and none of them is primarily financial.
- Regulatory clarity. Whether federal AI safety frameworks emerge that OpenAI can credibly claim to have helped shape, converting its safety positioning into a compliance advantage.
- Profitability trajectory. Whether the -122% operating margin improves meaningfully as revenue scales toward the mid-2027 target of $62 billion, the milestone that would need to be visible before an S-1 filing looked defensible.
- Governance resolution. Whether the congressional probe and the attorneys general letters escalate or dissipate before OpenAI files.
Analysts suggest the delay could push the listing to at least 2027. On current trajectory, that looks like the earliest realistic window.
The competitive pressure that could force the timeline
There is an external forcing function. If Anthropic’s revenue growth, unverified at $11.6 billion in Q2 2026, continues at that pace, the competitive moat justifying OpenAI’s premium valuation will need active defence. That defence costs money the company is already burning at roughly $8 billion a year.
The honest verdict is this. The $1.2 trillion figure is coherent as a private market signal, but it has not been tested against the discipline of public market scrutiny, and the safety narrative is the primary instrument Altman is using to control the timing of that test. The IPO timing is not really a financial decision. It is a political and reputational one, fought on the terrain of the safety debate, which means the two stories that look separate at the headline level are the same story.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and several figures referenced here remain unverified. Forward-looking statements are speculative and subject to change based on market developments and company performance.