#
If you thought the only thing that mattered about your super was the percentage your employer pays in, the rules that took effect on 1 July 2026 have quietly rewritten the game. The mechanics of how and when your retirement money lands have changed, and most workers have no idea it happened.
Three shifts sit at the centre of it. The Superannuation Guarantee rate is now locked at 12%, the general concessional contributions cap has jumped to $32,500, and employers face strict new deadlines for getting your money into your fund.
Together, these changes affect how fast your savings start compounding and how much of your income you can legally shield from tax.
Here is what this covers: a clear framework for auditing the payments landing in your account, and a practical method for using the newly expanded thresholds to reduce your taxable income before this financial year slips away. You will finish knowing exactly what to check on your next payslip and how much room you have to work with.
Understanding the 2026-27 contribution limits
Before you can optimise anything, you need to know the hard numbers that govern the system this financial year. Two figures do most of the heavy lifting.
The first is the Superannuation Guarantee rate, which is now 12%. This is the legislated ceiling under current law. It reached 12% on 1 July 2025 and holds at that level for the 2026-27 year, meaning your employer must contribute the equivalent of 12% of your ordinary earnings into your fund.
The second is the general concessional contributions cap, which sits at $32,500 for 2026-27. That is up from $30,000 in 2025-26, an increase the Australian Taxation Office attributes to indexation in line with Average Weekly Ordinary Time Earnings (AWOTE).
Here is the part that trips people up. Concessional contributions are the before-tax money going into your super, and the $32,500 cap is a combined total. It covers your employer’s 12% SG, any salary sacrifice you arrange, and any personal contributions you claim a tax deduction for, added up across every super fund you hold.
Money going in under this cap is taxed at just 15% inside the fund, well below most workers’ income tax rates. That is the entire appeal, and it is why the cap matters.
Salary sacrifice gains compound most powerfully when your starting balance is already working hard, and retirement savings benchmarks by age reveal how far the average Australian sits from the ASFA comfortable retirement threshold at each career stage, which shapes how aggressively the contribution room should be used.
The jump to $32,500 means your old assumptions about hitting the ceiling are now outdated. If you set your contributions to max out the previous $30,000 cap, you now have an extra $2,500 of room to shield more income from the tax office.
| Rule | 2026-27 Figure | Effective Date |
|---|---|---|
| General concessional contributions cap | $32,500 | 1 July 2026 |
| Superannuation Guarantee rate | 12% | 1 July 2025 (maintained) |
| Contributions tax rate (concessional) | 15% | Ongoing |
One exception is worth flagging. If your total super balance is under $500,000, you may be able to use unused cap amounts carried forward from the previous five years, letting you contribute above $32,500 in a single year without penalty.
When big ASX news breaks, our subscribers know first
How payday super changes your monitoring routine
The bigger structural change this year is not about how much goes in. It is about when.
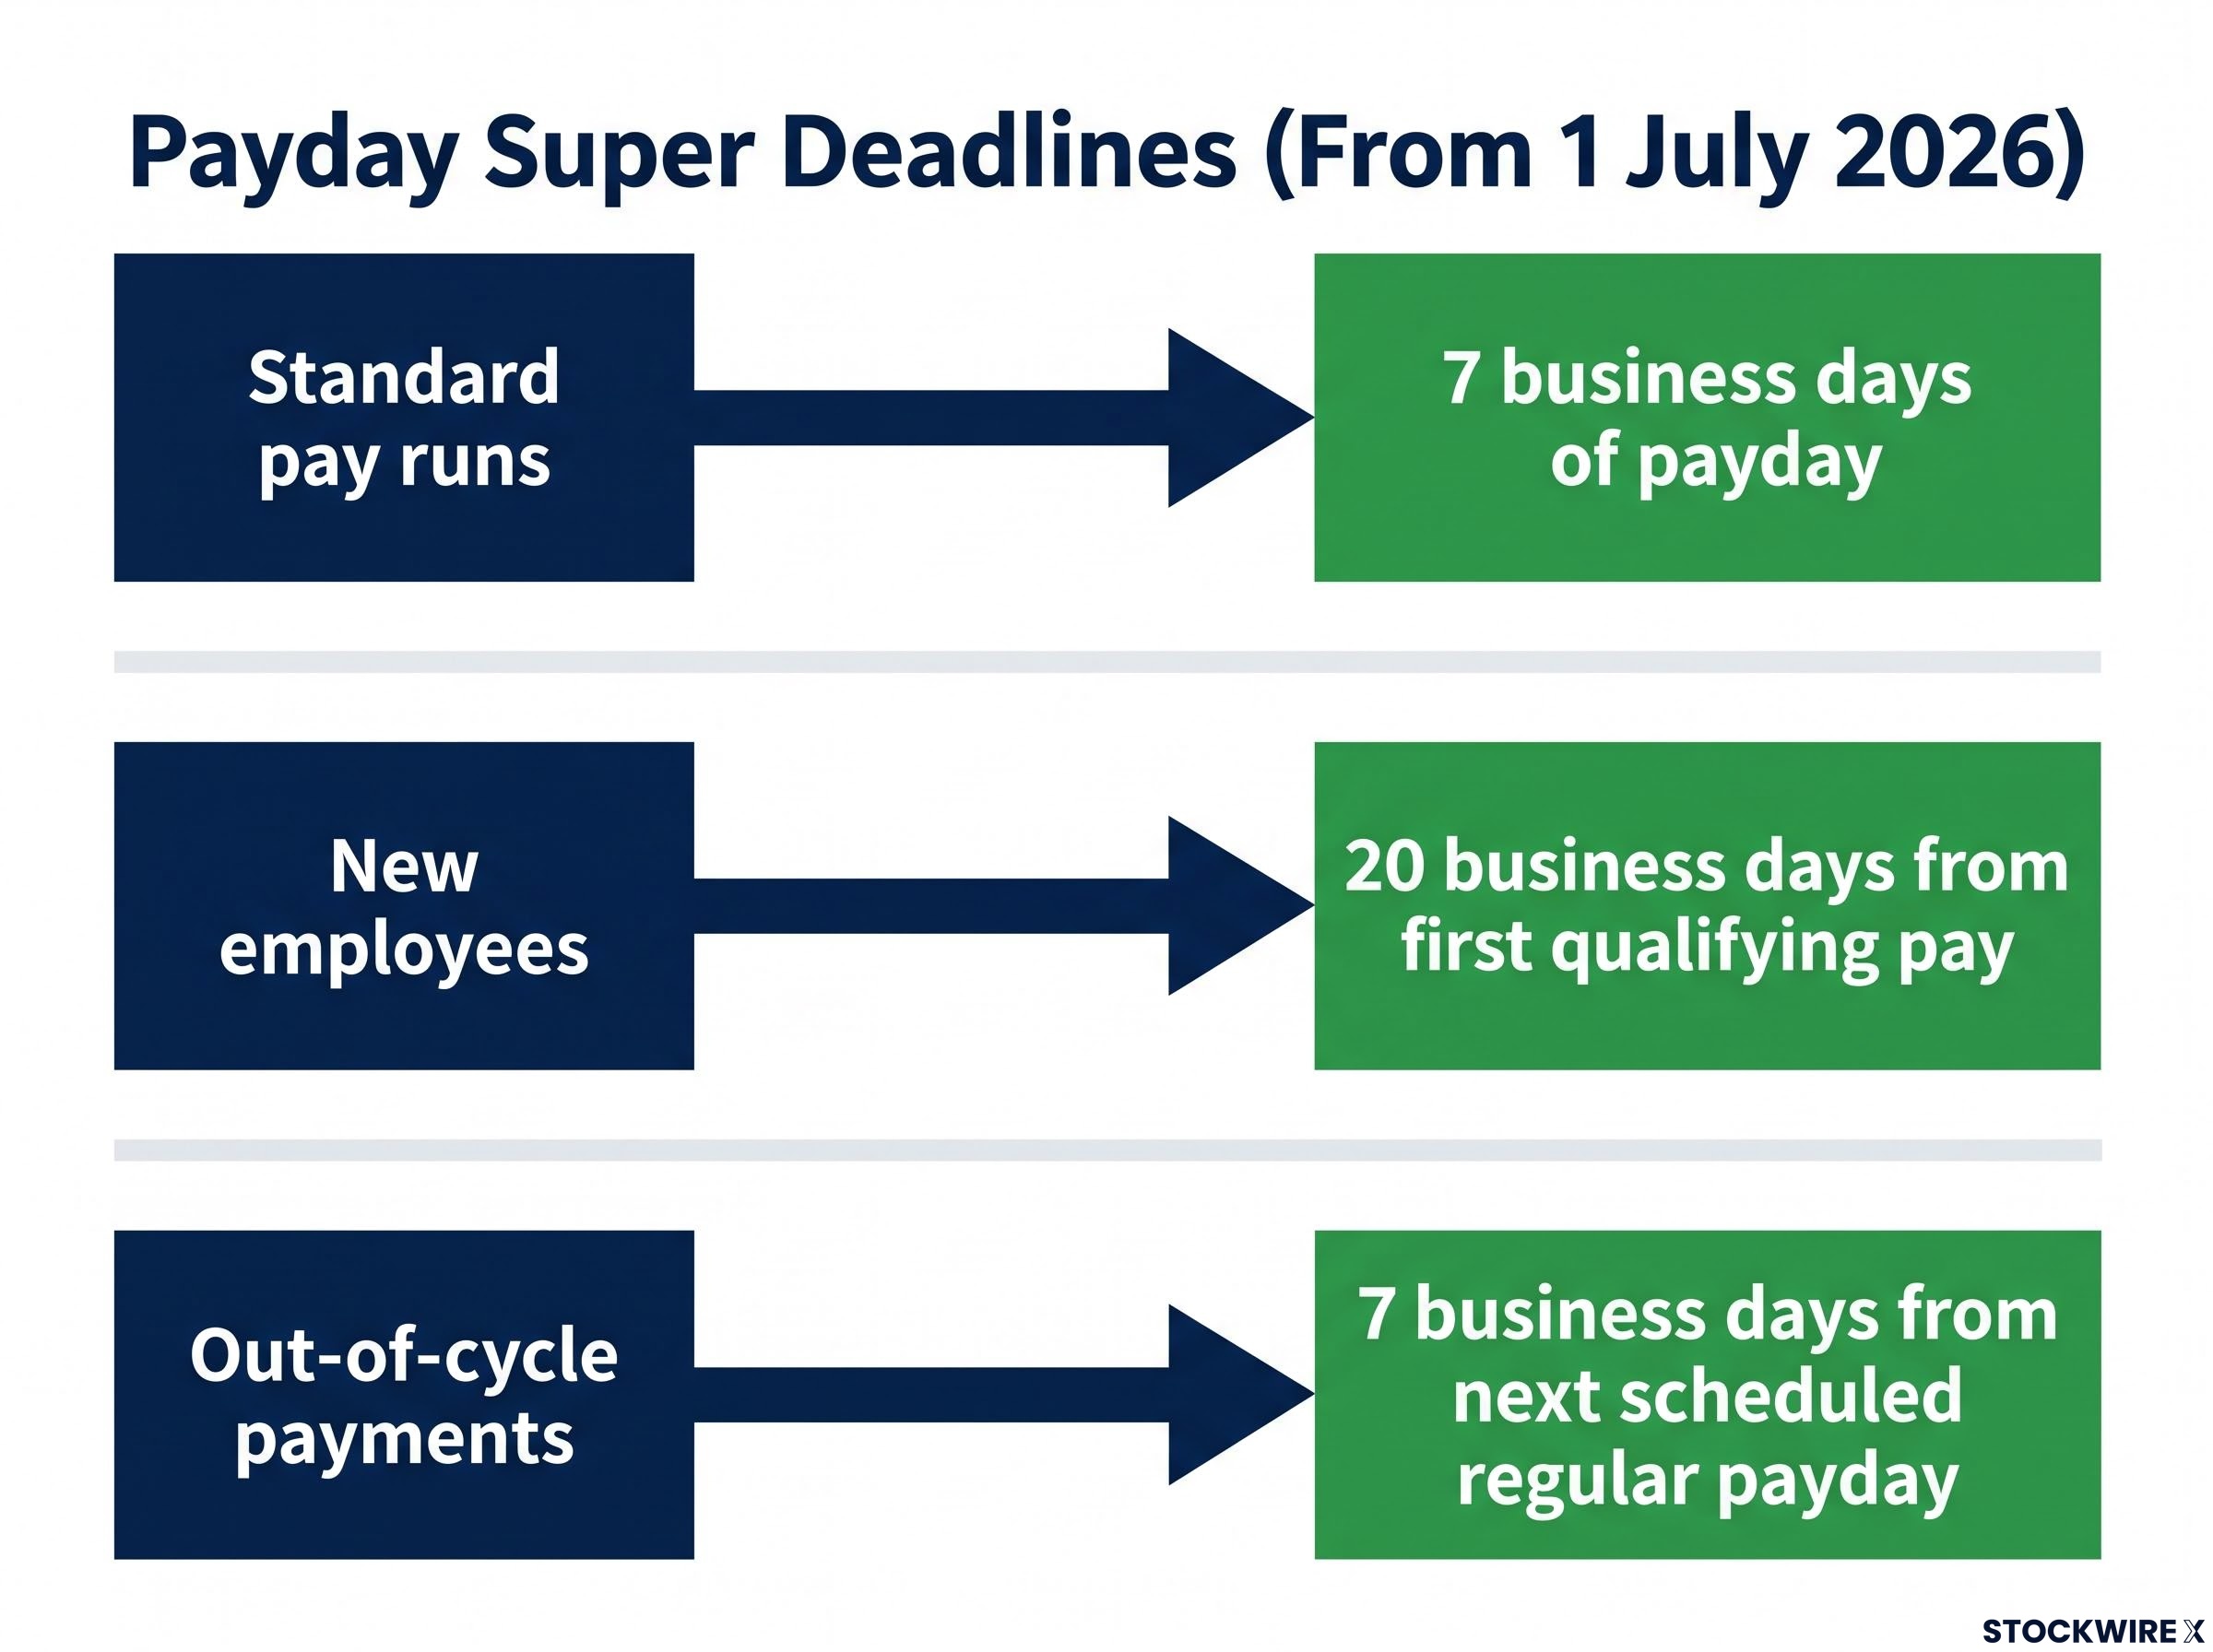
From 1 July 2026, payday super requires your employer to ensure SG contributions are received by your fund, with enough information to allocate them to your account, within 7 business days of each payday. This replaces the old system, where employers could wait until the end of each quarter to pay.
The ATO payday super rules set out the precise wording that contributions must be received by your fund within 7 business days of each payday, which is the benchmark you use when deciding whether a delayed payment warrants a formal enquiry to your employer.
That quarterly grace period was where the trouble lived. It let some employers hold your super for months, effectively using it as working capital, while your money sat idle instead of compounding.
The shift to a 7-day countdown changes what a delay means. Missing super is no longer a tolerated administrative lag; it is an immediate compliance breach you have every right to flag.
The rules do carry specific exceptions, so it helps to know which deadline applies to your situation.
- Standard pay runs: contributions must reach your fund and be allocatable within 7 business days of payday.
- New employees: your first super contribution can take up to 20 business days from your first qualifying pay.
- Out-of-cycle payments: bonuses and corrections attract a 7-business-day deadline measured from your next scheduled regular payday, not the date the bonus is paid.
The enforcement teeth here are sharp. If contributions are not received on time, in full, and to the correct fund, the employer faces the Superannuation Guarantee Charge (SGC), which includes nominal interest and administration components. Missing the window by even a single day can trigger it, and processing delays on the employer’s side do not extend the deadline.
What this means for you is simple. Check your super account after your next pay cycle and confirm the contribution has actually landed. You have moved from passive recipient to active monitor, and catching a missed payment early means your money starts working weeks or months sooner than it would have under the old rules.
Maximising the $32,500 cap with salary sacrifice
Now for the part where the numbers work in your favour. Salary sacrificing is the mechanism that turns the expanded cap into real money in your pocket, and the logic behind it is a straightforward tax swap.
When you salary sacrifice, you divert part of your before-tax pay into super, where it is taxed at the flat 15% contributions rate rather than your personal marginal income tax rate. For many workers on marginal rates of 32.5% or 37%, that swap saves roughly 17.5 to 22 percentage points of tax on every dollar redirected.
The extra $2,500 of cap room this year opens up a fresh slice of income you can move from your high marginal rate down to 15%. But to use it, you first need to know how much space you actually have.
Calculating your available contribution room
Your available room is the gap between your mandatory employer contributions and the legal maximum. Here is how to find it.
- Project your total annual salary for 2026-27.
- Calculate your mandatory employer SG at 12% of that salary.
- Subtract that SG figure from the $32,500 cap.
The result is the amount you can add through salary sacrifice or personal deductible contributions before you hit the ceiling.
Take a worker on $90,000. Their employer SG at 12% comes to $10,800. Subtract that from $32,500 and you are left with $21,700 of available cap room.
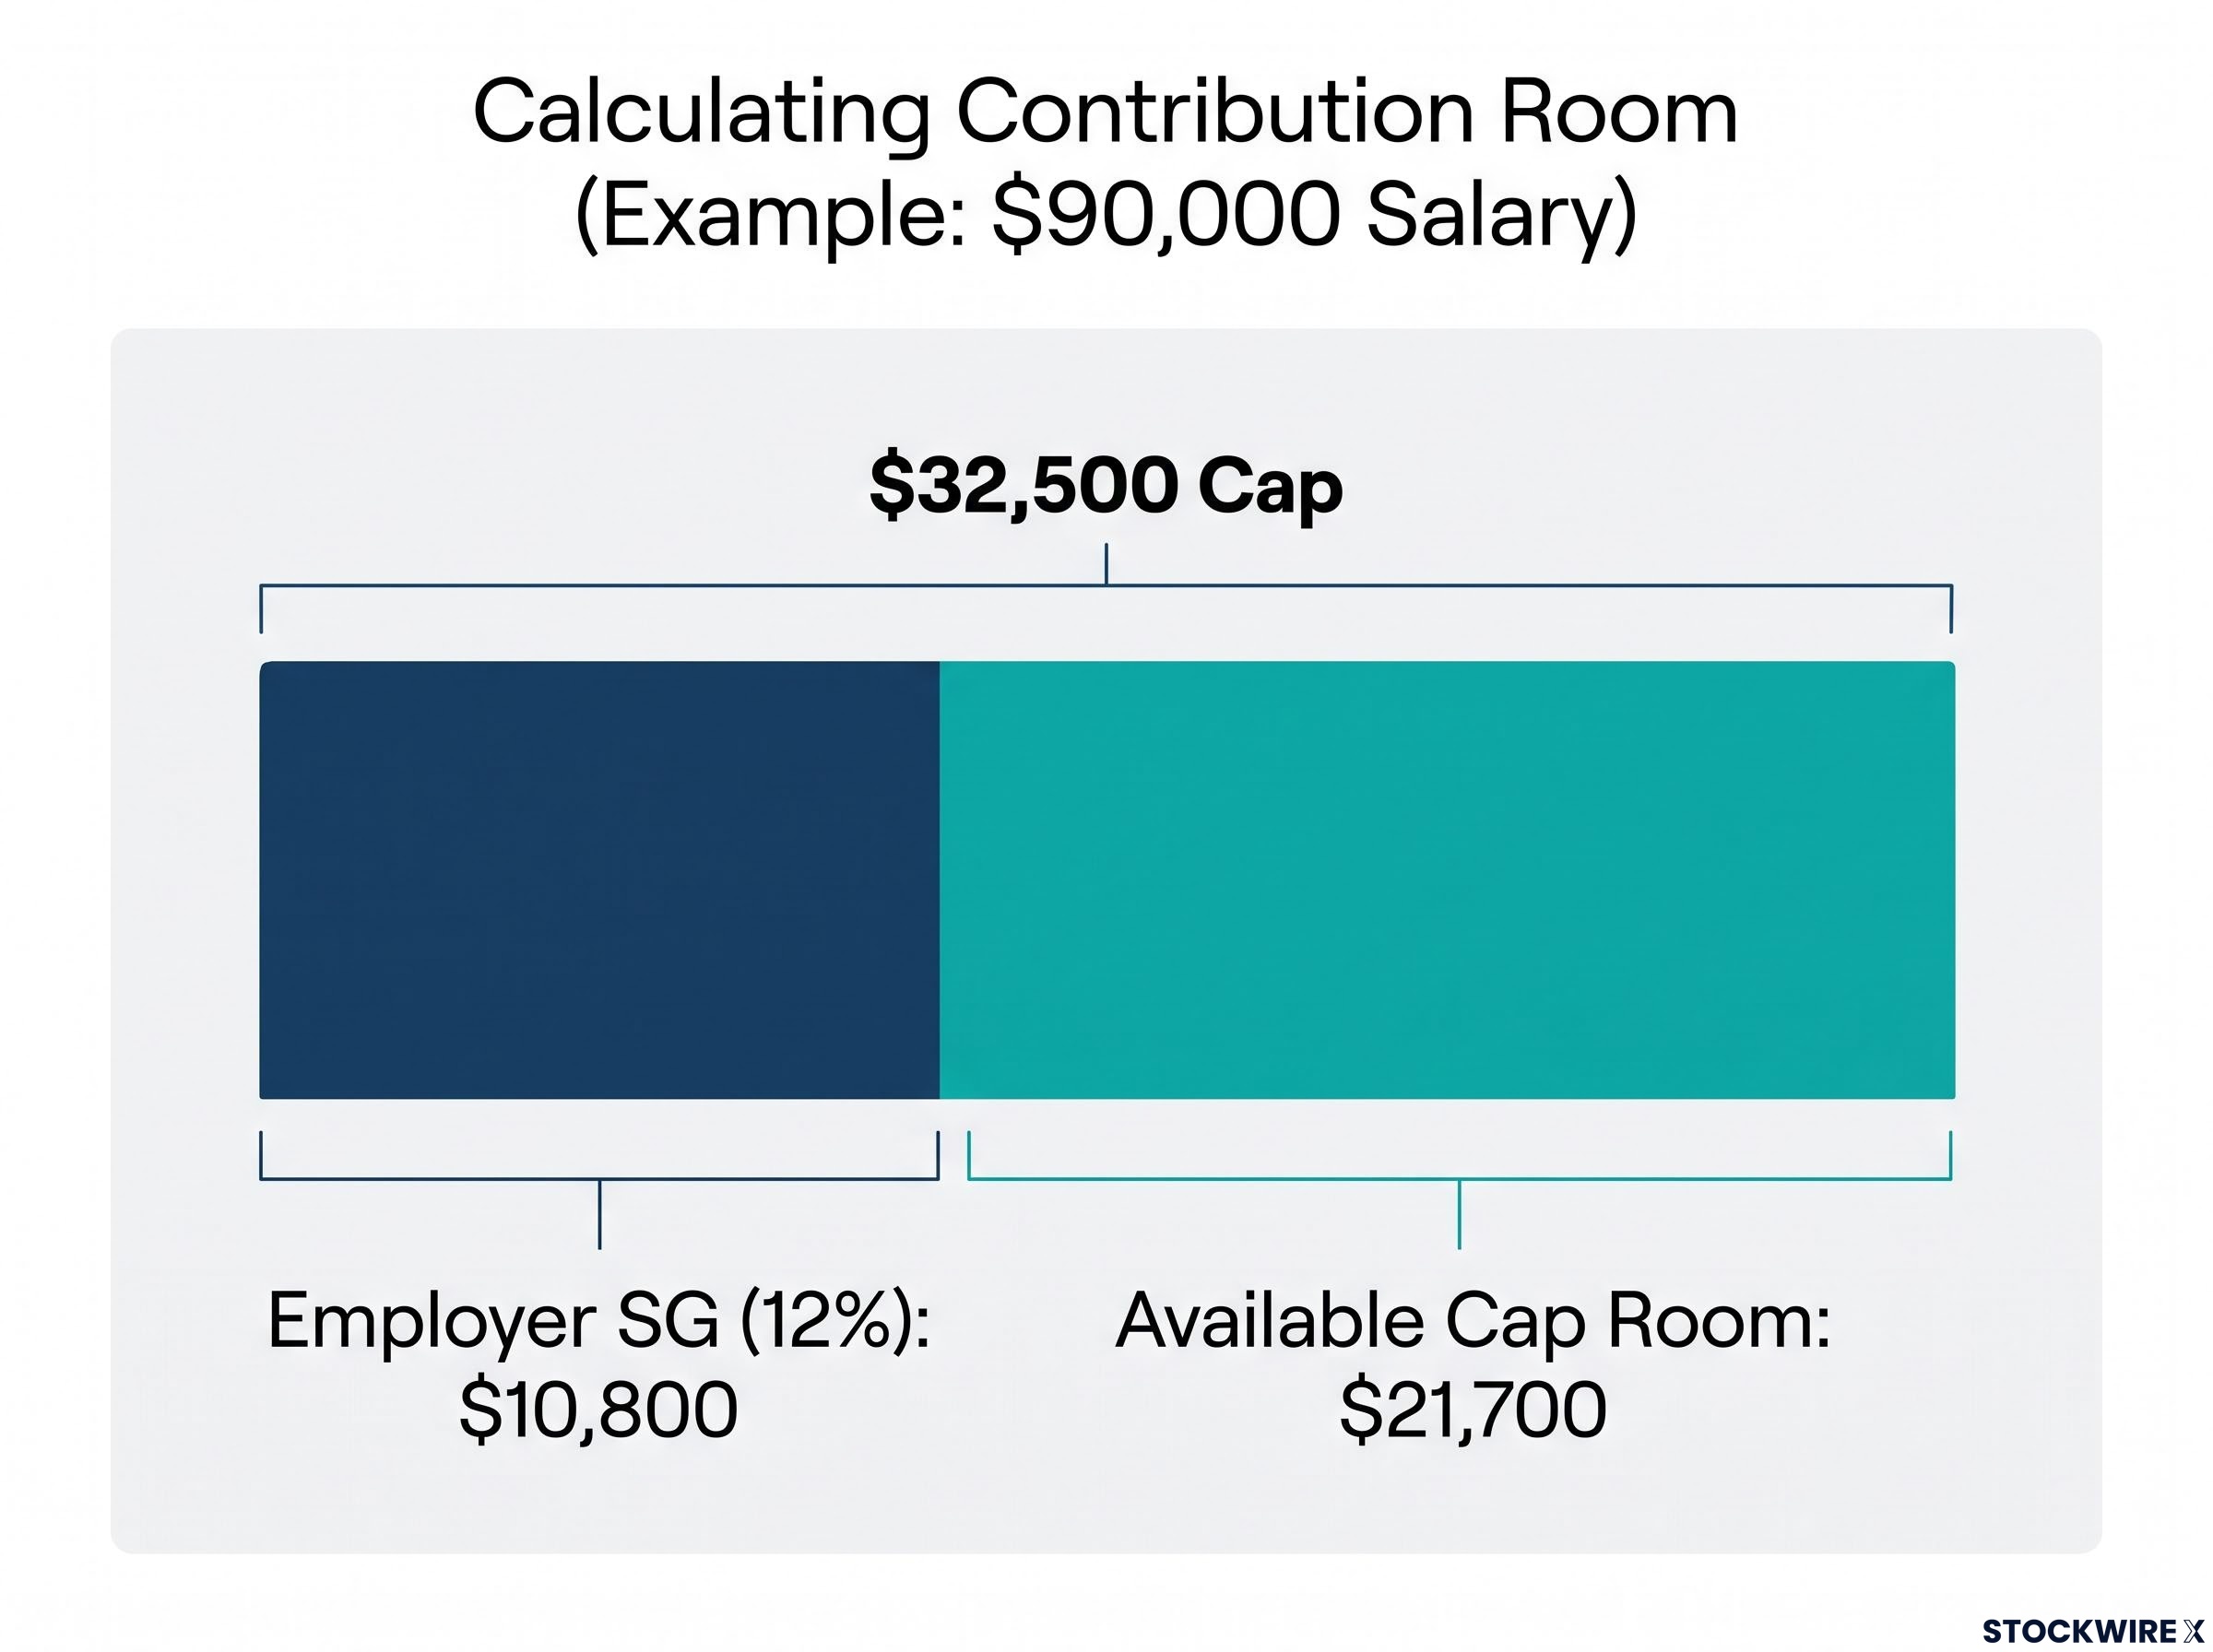
That $21,700 represents income the worker could redirect into super at the 15% rate instead of paying tax on it at their marginal rate. Seeing that gap laid out shows you exactly how much control you hold over your final tax bill. The mandatory contributions are fixed, but the space above them is yours to use or leave on the table.
Setting this up is usually a matter of speaking to your payroll department and nominating a fixed dollar amount or percentage per pay. The change flows through automatically from there, so the effort is front-loaded and the benefit recurs every cycle.
The hidden traps of aggressive super contributions
Before you rush to the payroll office, the boundaries deserve as much attention as the benefits. Getting the strategy wrong can cost you more than doing nothing.
The first trap is breaching the cap. If your combined concessional contributions push past $32,500, the excess is added to your assessable income and taxed at your marginal rate, with only a 15% offset to account for tax already paid inside the fund. In practice, that neutralises the advantage you were chasing, which is why precision matters as much as ambition when you adjust your payroll settings.
The second is liquidity. Money sacrificed into super is locked away, and that is a serious consideration if you have near-term goals.
The liquidity trade-off Once your money enters super, you generally cannot touch it until you reach preservation age or meet another release condition. For younger workers saving toward a house deposit or education, tying up cash for decades in exchange for a tax benefit may not be the right call.
For workers who need capital accessible before retirement, maintaining some liquidity outside super through ETFs held in a brokerage account balances the tax efficiency of salary sacrifice against the practical reality that super is a locked vehicle until preservation age.
The third concerns your income level. High earners may face Division 293 tax, an additional charge on concessional contributions that reduces the relative benefit of aggressive salary sacrifice and should be weighed against your overall tax position.
At the other end, if you sit on a marginal rate at or below 19%, swapping that for the 15% contributions tax delivers a negligible saving. You may be better off keeping the cash flow, and salary sacrifice could even reduce your eligibility for government co-contributions or income-tested benefits.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Auditing your super strategy for the financial year
Three actions turn all of this into a working plan. First, verify the 7-day payment cycle by confirming your recent contributions have actually reached your fund. Second, calculate your exact cap room using the $32,500 limit minus your projected 12% employer SG. Third, adjust your salary sacrifice arrangement with payroll so your total before-tax contributions sit just under the ceiling.
With the rules active since 1 July 2026, every pay cycle that passes without optimisation is a missed chance for tax-advantaged compounding you cannot get back.
Monthly contribution automation — where salary sacrifice is set to redirect within one pay cycle and a parallel ETF contribution is scheduled the same day — removes the behavioural friction that causes most self-directed strategies to lapse within the first few years of implementation.
So make it concrete this week. Pull up your latest payslip, open your fund’s transaction history, and check that the numbers line up. It is the fastest way to see whether the new system is working for you, and whether there is money you are leaving on the table.