The dollar sank to four-week lows on Thursday and gold pushed above US$4,100 an ounce, yet AI stocks were being sold hard at the same time. One election result sent your currency, commodity and tech exposure in what look like opposite directions. If that seems contradictory, you are probably missing one piece of the puzzle.
That piece is interest rates. Democrats swept both the House and the Senate in Tuesday’s midterms, and the result flowed through Treasury yields into almost every asset you might own.
Now the market faces its next test. Friday’s October nonfarm payrolls report is expected to show 65,000 new jobs and unemployment holding at 4.2%. A surprise in either direction could confirm the post-election moves or undo them.
Here is how one political event, shifting rate expectations and a single jobs number connect across currencies, commodities and equities. Once you see the links, you can read the next move yourself.
What did markets actually do after the midterms?
Start with the scoreboard. The dollar and Treasury yields fell, gold rose, oil whipsawed and tech went from rally to rout inside 24 hours.
Wednesday and Thursday told different stories. Wednesday brought a broad relief rally. Thursday brought a severe sell-off in AI and semiconductor stocks that wiped out those gains.
Be aware that quoted levels differ by source and time of day. That is normal in fast markets. Where figures conflict, the later readings below are the more reliable guide.
| Asset | Wednesday move | Thursday level or move | Main driver |
|---|---|---|---|
| Dollar Index (DXY) | Down 0.34% (FXStreet: low near 101.35) | 101.25 per Reuters, lowest since 30 September (FXStreet: about 101.70) | Lower yields, less expected borrowing |
| 10-year Treasury yield | Falling broadly | 4.847%, down 4.5 bp, lowest since 10 September | Expectations of less fiscal spending |
| Gold | Early snapshots around US$4,030-4,050 | Above US$4,100/oz | Softer dollar, falling yields |
| WTI crude | Fell about 8.3% to US$88.12; December contract near US$86 | Rebounded above US$90 | Demand outlook versus Iran supply risk |
| Nasdaq Composite | Up 1.4% | Down about 4% in the morning, nearly 5% intraday | AI data centre regulation fears |
If you hold dollar, gold, energy or tech exposure, one headline moved every piece of it differently. Looking at any single asset in isolation would have given you a misleading read.
The dollar and the major pairs
Each major currency pair also had its own local story layered on top of the dollar’s weakness, according to FXStreet:
- EUR/USD: Found support near 1.1200 and edged slightly higher, with German industrial production data due.
- GBP/USD: Traded choppily around 1.3470, struggling to extend a multi-day rise.
- USD/JPY: Slipped to near 157.80 as hawkish Bank of Japan (BoJ) minutes and intervention risk supported the yen.
- AUD/USD: Fell to three-week lows around 0.6940 after discouraging remarks from the Reserve Bank of Australia’s (RBA) Andrew Hauser.
The euro makes up about 57.6% of the index, so the euro-driven dollar index can swing on European data and ECB signals as much as on US yields, which helps explain why each major pair told its own local story.
When big ASX news breaks, our subscribers know first
Why did one election move yields, the dollar, gold and oil together?
The signal was simple: a Democratic sweep. Reuters reported that investors expected less government borrowing and spending as a result. Everything else followed from that one shift.
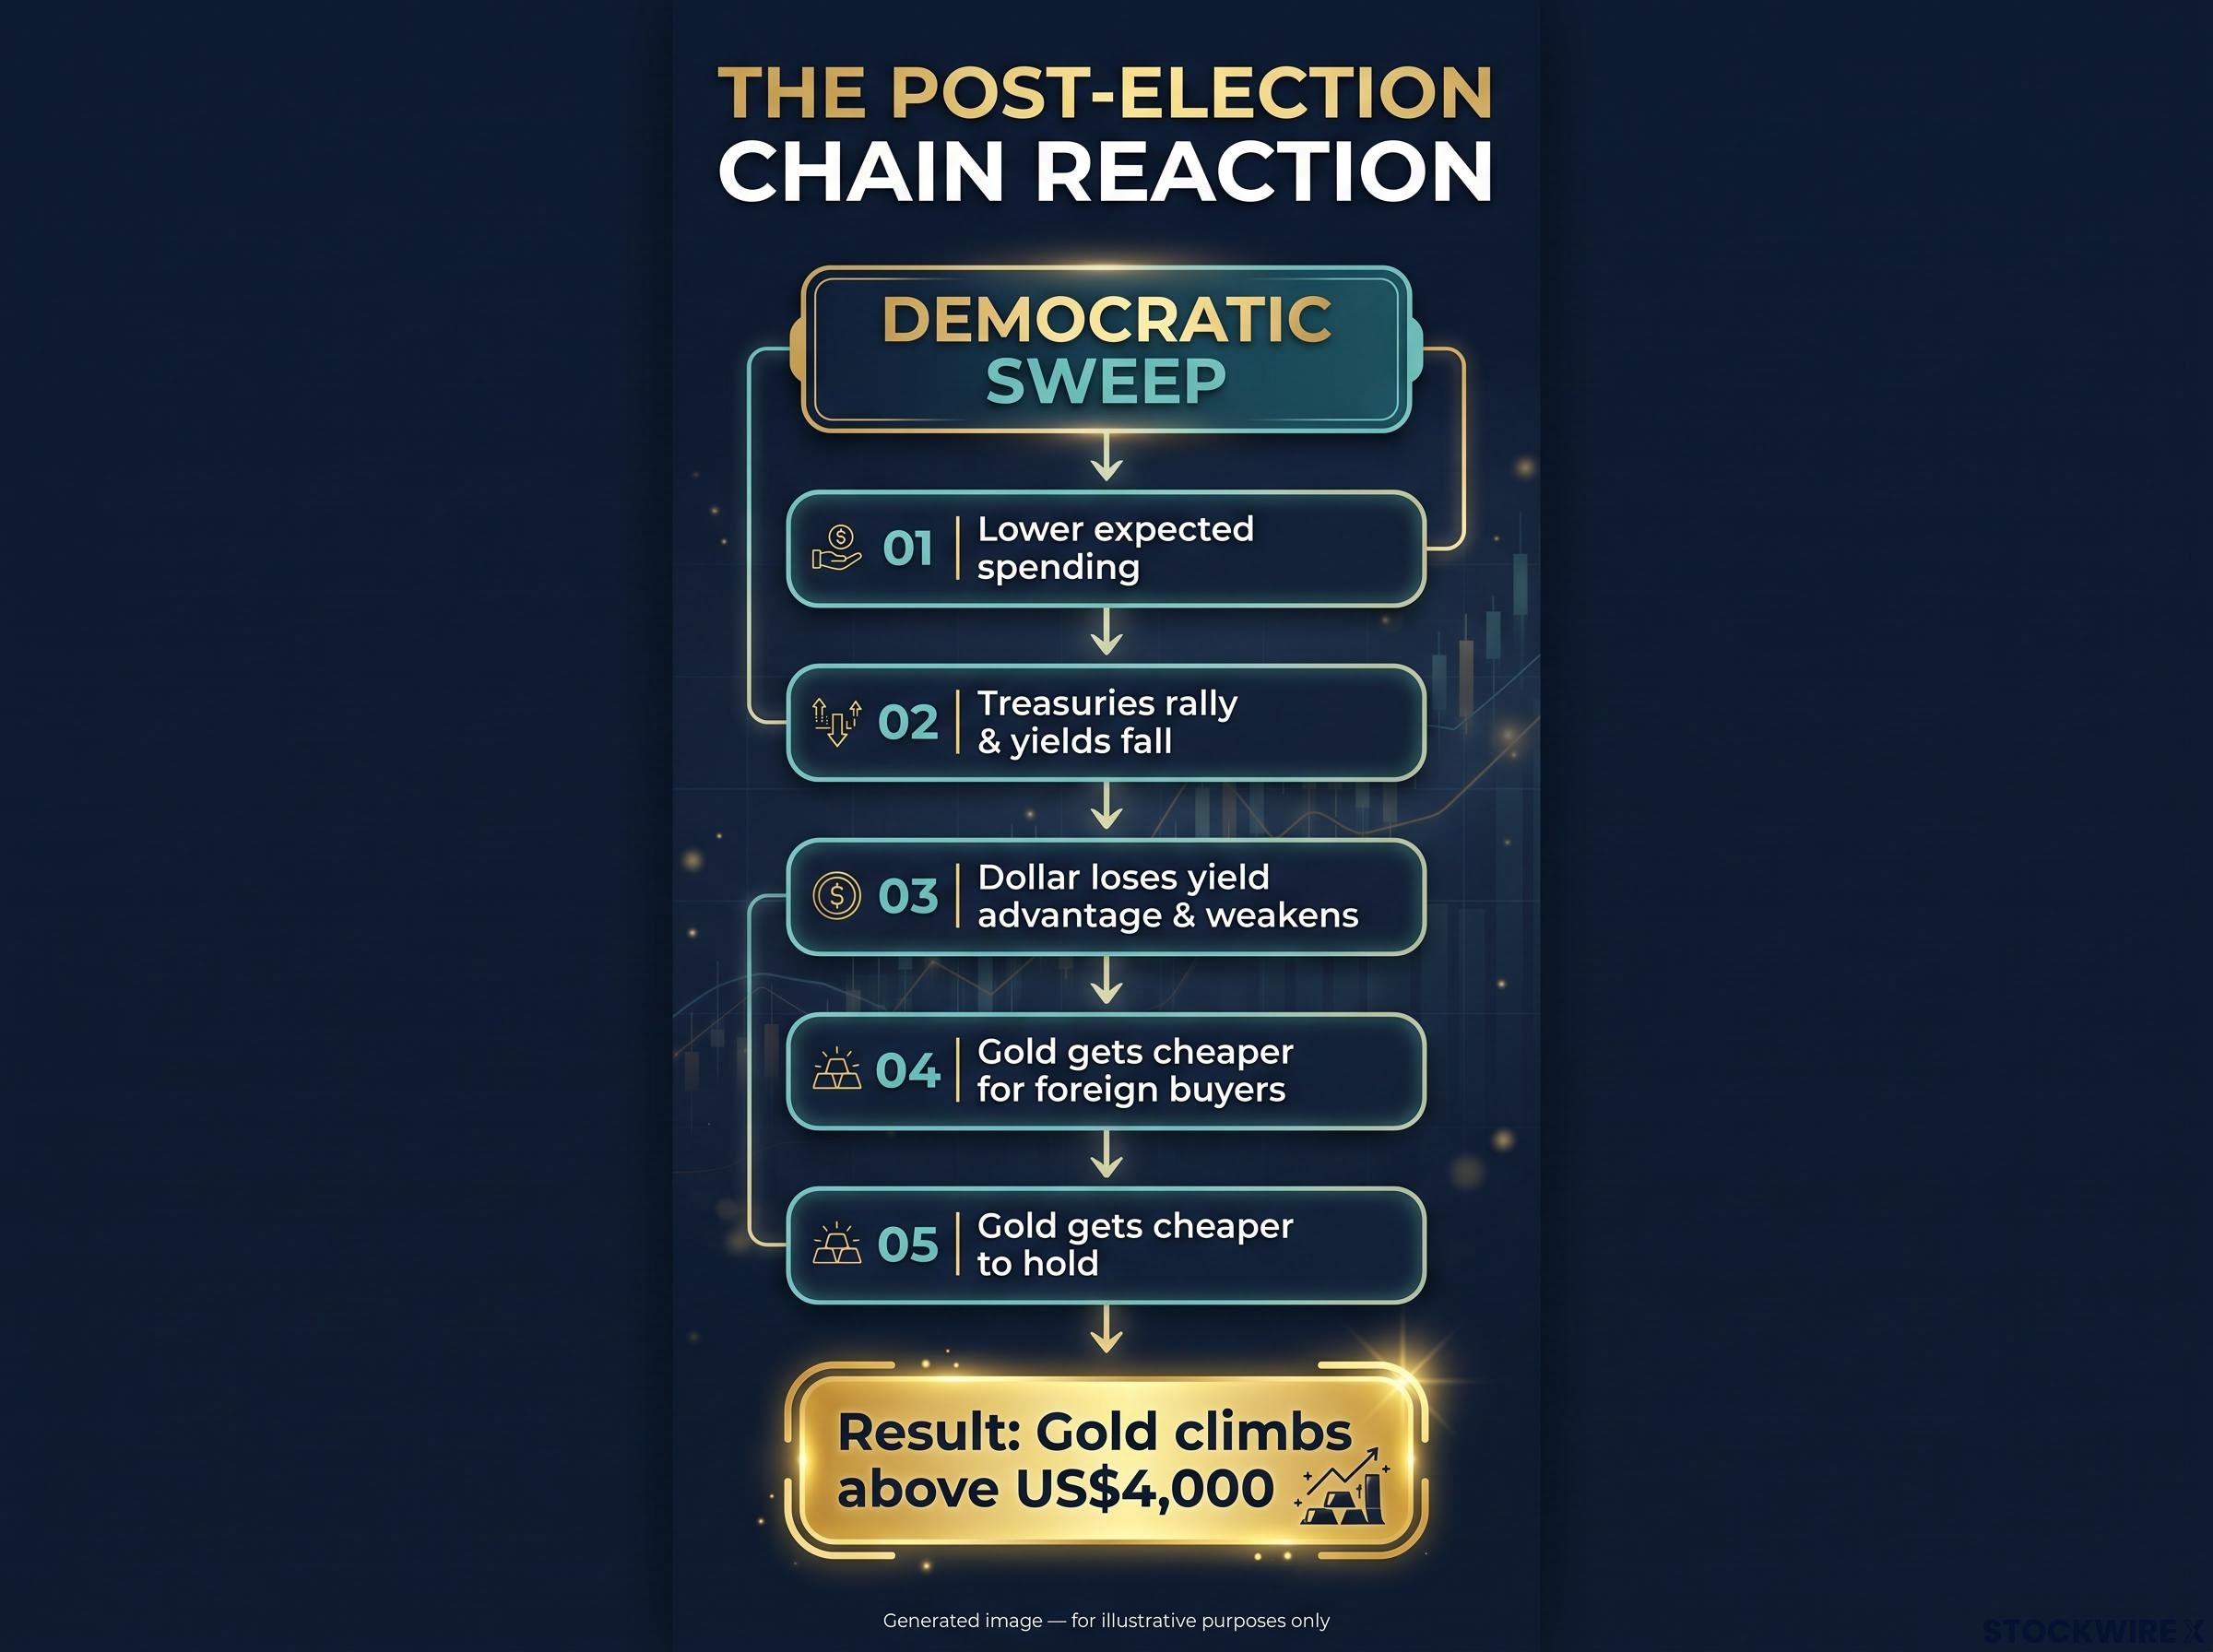
The yield-dollar-gold chain
Here is the chain, step by step:
- Lower expected spending means the government is expected to issue less debt and stoke less inflation.
- Treasuries rally as investors anticipate fewer new bonds competing for buyers, and yields fall.
- The dollar loses its yield advantage, meaning dollar assets now pay less relative to assets in other currencies, so the dollar weakens.
- Gold gets cheaper for foreign buyers, because it is priced in dollars.
- Gold gets cheaper to hold, because lower yields cut its opportunity cost: the income you give up by owning an asset that pays no interest.
Morningstar tied gold’s climb above US$4,000 directly to the softer dollar and falling yields. Once you know this chain, you can anticipate which assets will move together whenever yields shift.
What the election did not do is change the Federal Reserve’s path.
Not a Fed story CME FedWatch put the probability of at least one 25 basis point hike in December at 80.7%, up from 77.4% a session earlier. Markets still expect the Fed to raise rates.
That matters for you because the yield drop rests on fiscal expectations, not monetary policy. ING kept a bias toward a 5.25% 10-year yield, suggesting the decline may not last. Wells Fargo’s global head of FX strategy, Erik Nelson, holds a bearish medium-term dollar view and forecasts EUR/USD at $1.16 by year-end.
Why oil broke the pattern
Oil answers to a separate driver. The political reading was bearish: less spending implies weaker demand and lower inflation, which helped send WTI down about 8.3%.
Then supply risk reasserted itself. Traders reassessed the threat of disruption around Iran and the Strait of Hormuz, and WTI climbed back above US$90.
Oil is pulled between a demand story and a geopolitical supply story. When you see it diverge from gold, that tug of war is usually why.
Is the AI-stock sell-off a correction or something structural?
Thursday’s damage was severe and concentrated in the companies most dependent on building AI infrastructure.
| Company | Reported move | Exposure |
|---|---|---|
| SanDisk | Down about 17% | AI memory and storage demand |
| AMD | Down more than 13% | AI chips |
| Micron | Down more than 12% | Memory |
| Marvell | Down about 11% | Networking |
| TSMC | Down about 7% | Chip manufacturing |
| Nvidia | Down more than 6% | AI chips |
The trigger was fear that Democratic control of Congress and key states could slow or regulate power-hungry data centre construction. That would hit demand for chips, memory and networking gear. Reuters added that falling stock and bond prices were already making data centre projects harder to finance.
Data centre valuation resets have already appeared elsewhere, with Australian contractors giving back 20-30% in weeks as financing shocks hit multiples, even though underlying earnings kept growing strongly.
Positioning gave the headline extra force. The AI trade was crowded and expensive, so investors had a ready reason to cut exposure. Maxim Group’s Tom Forte said investors feared data centre expansion could slow.
The case for a correction:
- The trade was overextended, and the election simply prompted profit-taking.
- Nvidia fell far less than memory, storage and networking names, pointing to rotation within AI rather than rejection of it.
The case for something structural:
- Tougher permitting, power, water and emissions rules could follow Democratic wins.
- Reuters reported that ballot initiatives could limit construction, and tighter financing could slow the whole buildout.
Daniel Ives, Yorkville Ives (via MarketWatch): Investors are becoming more selective, favouring companies with demonstrable AI returns over chip and memory firms that depend on infrastructure buildout.
SimCorp’s Melissa Brown sees a slowdown, not an end, to AI investment. For you, the pattern of losses is the clue: the market is questioning the infrastructure layer, not AI itself. Evidence on permitting and financing will settle which view wins.
How could Friday’s payrolls report reinforce or reverse these moves?
The Bureau of Labor Statistics releases October’s figures on Friday 6 November 2026. Forecasts range from about 55,000 (CNBC’s FactSet survey) to 65,000 jobs.
| Measure | October consensus | September |
|---|---|---|
| Nonfarm payrolls | +65,000 | +29,000 |
| Unemployment rate | 4.2% | 4.2% |
| Average hourly earnings, monthly | +0.3% | +0.1% |
| Average hourly earnings, annual | +2.9% | +3.0% |
Three ways the report could land
The dollar’s drop was timed to the election, but data can overtake it quickly. Here is how each outcome would likely travel through the chain you just learned:
| Scenario | Yields and dollar | Gold | Tech |
|---|---|---|---|
| Strong jobs or wages | Likely higher | Under pressure | Rate-sensitive names may stay weak |
| Weak jobs or wages | Likely lower | Supported | Could help, though very weak data raises recession worries |
| Mixed report | Depends on wages | Depends on yields | Focus shifts to wage inflation |
A modest jobs gain with steady unemployment but firmer wages could swing attention to wage inflation, especially with consensus at just 65,000 jobs.
The Federal Reserve policy statement says the Committee weighs labor market readings, inflation pressures and financial developments when judging policy, which is why a jobs number can shift rate expectations even when the political backdrop has not changed.
What history says, and its limits
History leans positive for shares after midterms. Charles Schwab data cited by CNBC shows an average six-month return of +12.4% since 1974, positive in all 13 cycles, and an average three-month return of +5.7%, positive in 11 of 13. J.P. Morgan Asset Management puts the average one-year S&P 500 return at about +15%.
This episode is unusual, though. An expected Fed hike, elevated oil and Hormuz risk sit alongside an AI cycle that relies on data centre construction. Treat the post-midterm pattern as a tendency, not a forecast; Friday’s data and Treasury yields can override it in the near term.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
What to watch when the jobs number lands
When the report hits, check four things in order. Compare headline payrolls with 65,000, then wage growth against 0.3%. Watch how the 10-year yield reacts, and keep an eye on oil headlines involving Iran and Hormuz.
Markets trade surprises rather than absolute levels, so reading the payrolls report well means looking past the headline to wages and the revisions to the prior two months, which often reshape the narrative within minutes of the release.
The lesson from this week reaches beyond one election. Political events, rate expectations and data releases all work through the same channels, so a single framework reads every one of them.
Your next step is simple: set the actual print beside consensus and note which asset moves first. If yields lead, the dollar and gold should follow the chain. If oil moves alone, supply risk is doing the talking.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.