The U.S. Treasury market is posting yields near multi-year highs. The Treasury Department has tripled its per-operation buyback ceiling in a matter of weeks. And a prominent volatility analyst is projecting a 25% to 40% market drawdown beginning sometime after the midterm elections.
Three data points, one relationship. The elevated yields are the problem. The buybacks are the managed response. And the window after the November midterms is when that management is widely expected to end.
Most readers arrive at a bond market downturn outlook sensing that the current calm may not be structural. That instinct deserves a fair hearing. What follows here is a read on what the intervention data actually tells you about the stability you are seeing now, and what the risk window looks like once the electoral constraint lifts.
What the yield data is actually telling you right now
Start with the numbers, because they set the anchor for everything else. As of 23 September 2026, Trading Economics placed the 10-year Treasury note yield at 4.98% and the 30-year Treasury bond yield at 5.32%. Those are not routine levels.
The 10-year sits near its highest since late 2023. The 30-year is approaching territory not seen since 2007, a reference point that tells you how far the long end has repriced. Here is how September progressed:
- 9 September 2026: 10-year at 4.845%, 30-year at 5.295%
- 10 September 2026: 10-year at 4.954%, 30-year at 5.368%
- 22 September 2026: 10-year near 4.959%, 30-year near 5.296%
- 23 September 2026: 10-year at 4.98%, 30-year at 5.32%
Reuters captured how sharp the move had become around 9 September:
The 10-year briefly touching 4.8568% on 9 September was not an isolated event; the four forces driving the sell-off that week, a hotter core CPI print, structural fiscal anxiety, AI infrastructure uncertainty, and simultaneous curve-wide selling, each remain active in the data through late September.
The 10-year briefly touched 4.8568%, its highest level since November 2023, before settling near 4.835%.
Now pull back and look at what the pattern reveals. These yields did not drift up in the absence of official support. They climbed, and then held, while Treasury was actively running buyback operations designed to steady the long end.
That is the central interpretive fact. The operations are happening. The yields are still here.
For anyone weighing duration exposure, meaning how sensitive a bond position is to interest-rate moves, this matters directly. The persistence of these yields through multiple buyback operations tells you that official support is moderating volatility at the margins, but it has not changed the underlying rate environment.
That is the difference between a managed situation and a resolved one. Current levels reflect a structural repricing, not a temporary spike that intervention has already corrected. If you are treating these yields as a spike to be reversed, the data is not on your side.
When big ASX news breaks, our subscribers know first
How the buyback programme works, and why the market is not buying it
Follow the escalation, because the sequence is the story. Before August, Treasury capped its long-end liquidity-support buyback operations at $2 billion apiece. Then the ceiling started moving.
On 19 August 2026, a Treasury press release raised the maximum to at least $4 billion per operation for both the 10-to-20-year and 20-to-30-year sectors, effective from 9 September through 4 November 2026. Weeks later, on 10 September, Treasury said it would buy as much as $6 billion of debt maturing in 10 to 20 years, tripling the earlier baseline. The executed operation around 10-11 September came in at roughly $5.187 billion, below the ceiling but far above where per-operation sizes had sat.
Treasury’s August 19 press release formalised the shift, specifying that the change in per-operation size reflected a need for greater liquidity support in the long-end sectors, language that sits at some distance from a declaration of orderly market functioning.
| Date | Operation Cap | Notes |
|---|---|---|
| Pre-August 2026 | $2 billion | Baseline per-operation limit |
| 19 August 2026 | At least $4 billion | Doubled; effective 9 Sept to 4 Nov 2026 |
| 10 September 2026 | Up to $6 billion | 10-to-20-year sector; tripled from baseline |
Notice how Treasury describes what it is doing. It labels these operations deliberately:
Liquidity support buyback operations for longer-dated nominal coupon securities.
That phrasing is a signal, not decoration. Language about liquidity support points to concern over how well the long end is functioning, over market depth, rather than a declaration that conditions are fundamentally sound.
The market delivered its own verdict. Reuters framed the reaction bluntly on 10 September with the headline “Edgy bond investors unconsoled by Bessent’s big buyback.” Long-end yields rose to multi-month highs after the expanded announcement.
That is the read you should take from it. Yields climbing after a $6 billion buyback is the market telling you the programme’s scale does not match the pressures it is trying to manage.
The arithmetic supports that skepticism. According to CryptoBriefing, the expansion adds roughly $14 billion in additional quarterly buybacks to a total of about $69 billion in planned purchases across all maturities for the quarter. A JPMorgan Chase investor education note published 22 September 2026 laid out the same operation schedule, with the 10-to-20-year cap at $6 billion and long-end operations at or above $4 billion.
Set those figures against a multi-trillion-dollar outstanding Treasury stock and the coverage looks thin. Large nominal numbers can obscure how modest the relative footprint is, which is exactly why you should not let a headline figure stand in for genuine stabilisation when making duration and liquidity decisions.
What the structural drivers tell you about the intervention’s shelf life
The question underneath all of this is simple. If the buybacks are not working, why are yields where they are? The answer is three structural drivers, and they build on each other rather than sitting side by side.
- Inflation persistence. CNBC coverage links the rise in long-end yields to resurgent inflation tied to higher oil prices and expectations that policy rates stay elevated. The original source goes further, describing the inflation backdrop as structural rather than purely oil-driven.
That distinction is the one to hold onto. An oil-price component could ease on a deal. A broader structural inflation problem does not, which means the yield pressure it creates is resistant to any single near-term fix.
Term premium and dealer depth: the less visible pressures
The second and third drivers are harder to see on a chart but shape everything at the long end.
- Term premium repricing. Across CNBC and Reuters coverage, investors are demanding higher compensation for holding longer-dated debt. Term premium is simply the extra yield investors want in exchange for taking on the risk of holding a bond for longer.
When that premium rises, it reflects a systematic reassessment of duration risk, not a passing dislocation. It also means the long end is exposed to sharp price moves if rate expectations shift again.
- Dealer balance sheet constraints and liquidity depth. Treasury’s own “liquidity support” framing is the evidence here. When auction supply is large and conditions are stressed, dealer capacity to absorb it becomes a live concern.
These last two interact in a way worth understanding. Constrained dealer capacity amplifies the price impact of any sudden change in rate expectations, so a term-premium shift lands harder when balance sheets are already stretched.
The two competing readings of all this frame the debate. JPMorgan’s material treats the enlarged buybacks as a credible tool within a manageable situation. Reuters’ reporting treats them as managing the symptom while leaving the causes untouched.
Bessent’s approach operates as informal yield curve control rather than the formal, target-anchored version seen in Japan: no published yield ranges, finite capped operations that expire automatically, and no Federal Reserve participation, which is precisely why the long end has continued drifting upward despite the interventions.
Here is what the three-driver structure means for you. Because the drivers are independent, relief in one area does not resolve the others. If you treat oil prices falling as your signal to re-enter long duration, you are still exposed on inflation persistence and on liquidity depth, and being right on one of three is not a strategy.
That is also the foundation for the risk thesis that follows. If the structural drivers are not resolved, the managed stability is only as durable as the political will to maintain it.
The post-midterm risk window: what the analysts see and what remains unverified
This is where the analysis has to be honest about its own evidence. The forward-looking thesis comes from one named source, Jim from Kai Volatility, and it deserves both a fair hearing and a clear label.
The core argument runs like this. The administration is expected to use every available lever, buybacks and liquidity injections included, to hold stability through the midterms, roughly 44 days away at the time of discussion, placing the election in early November 2026. Once the election passes, the electoral constraint lifts, and the conditions for deterioration become operative.
The projection attached to that thesis is specific:
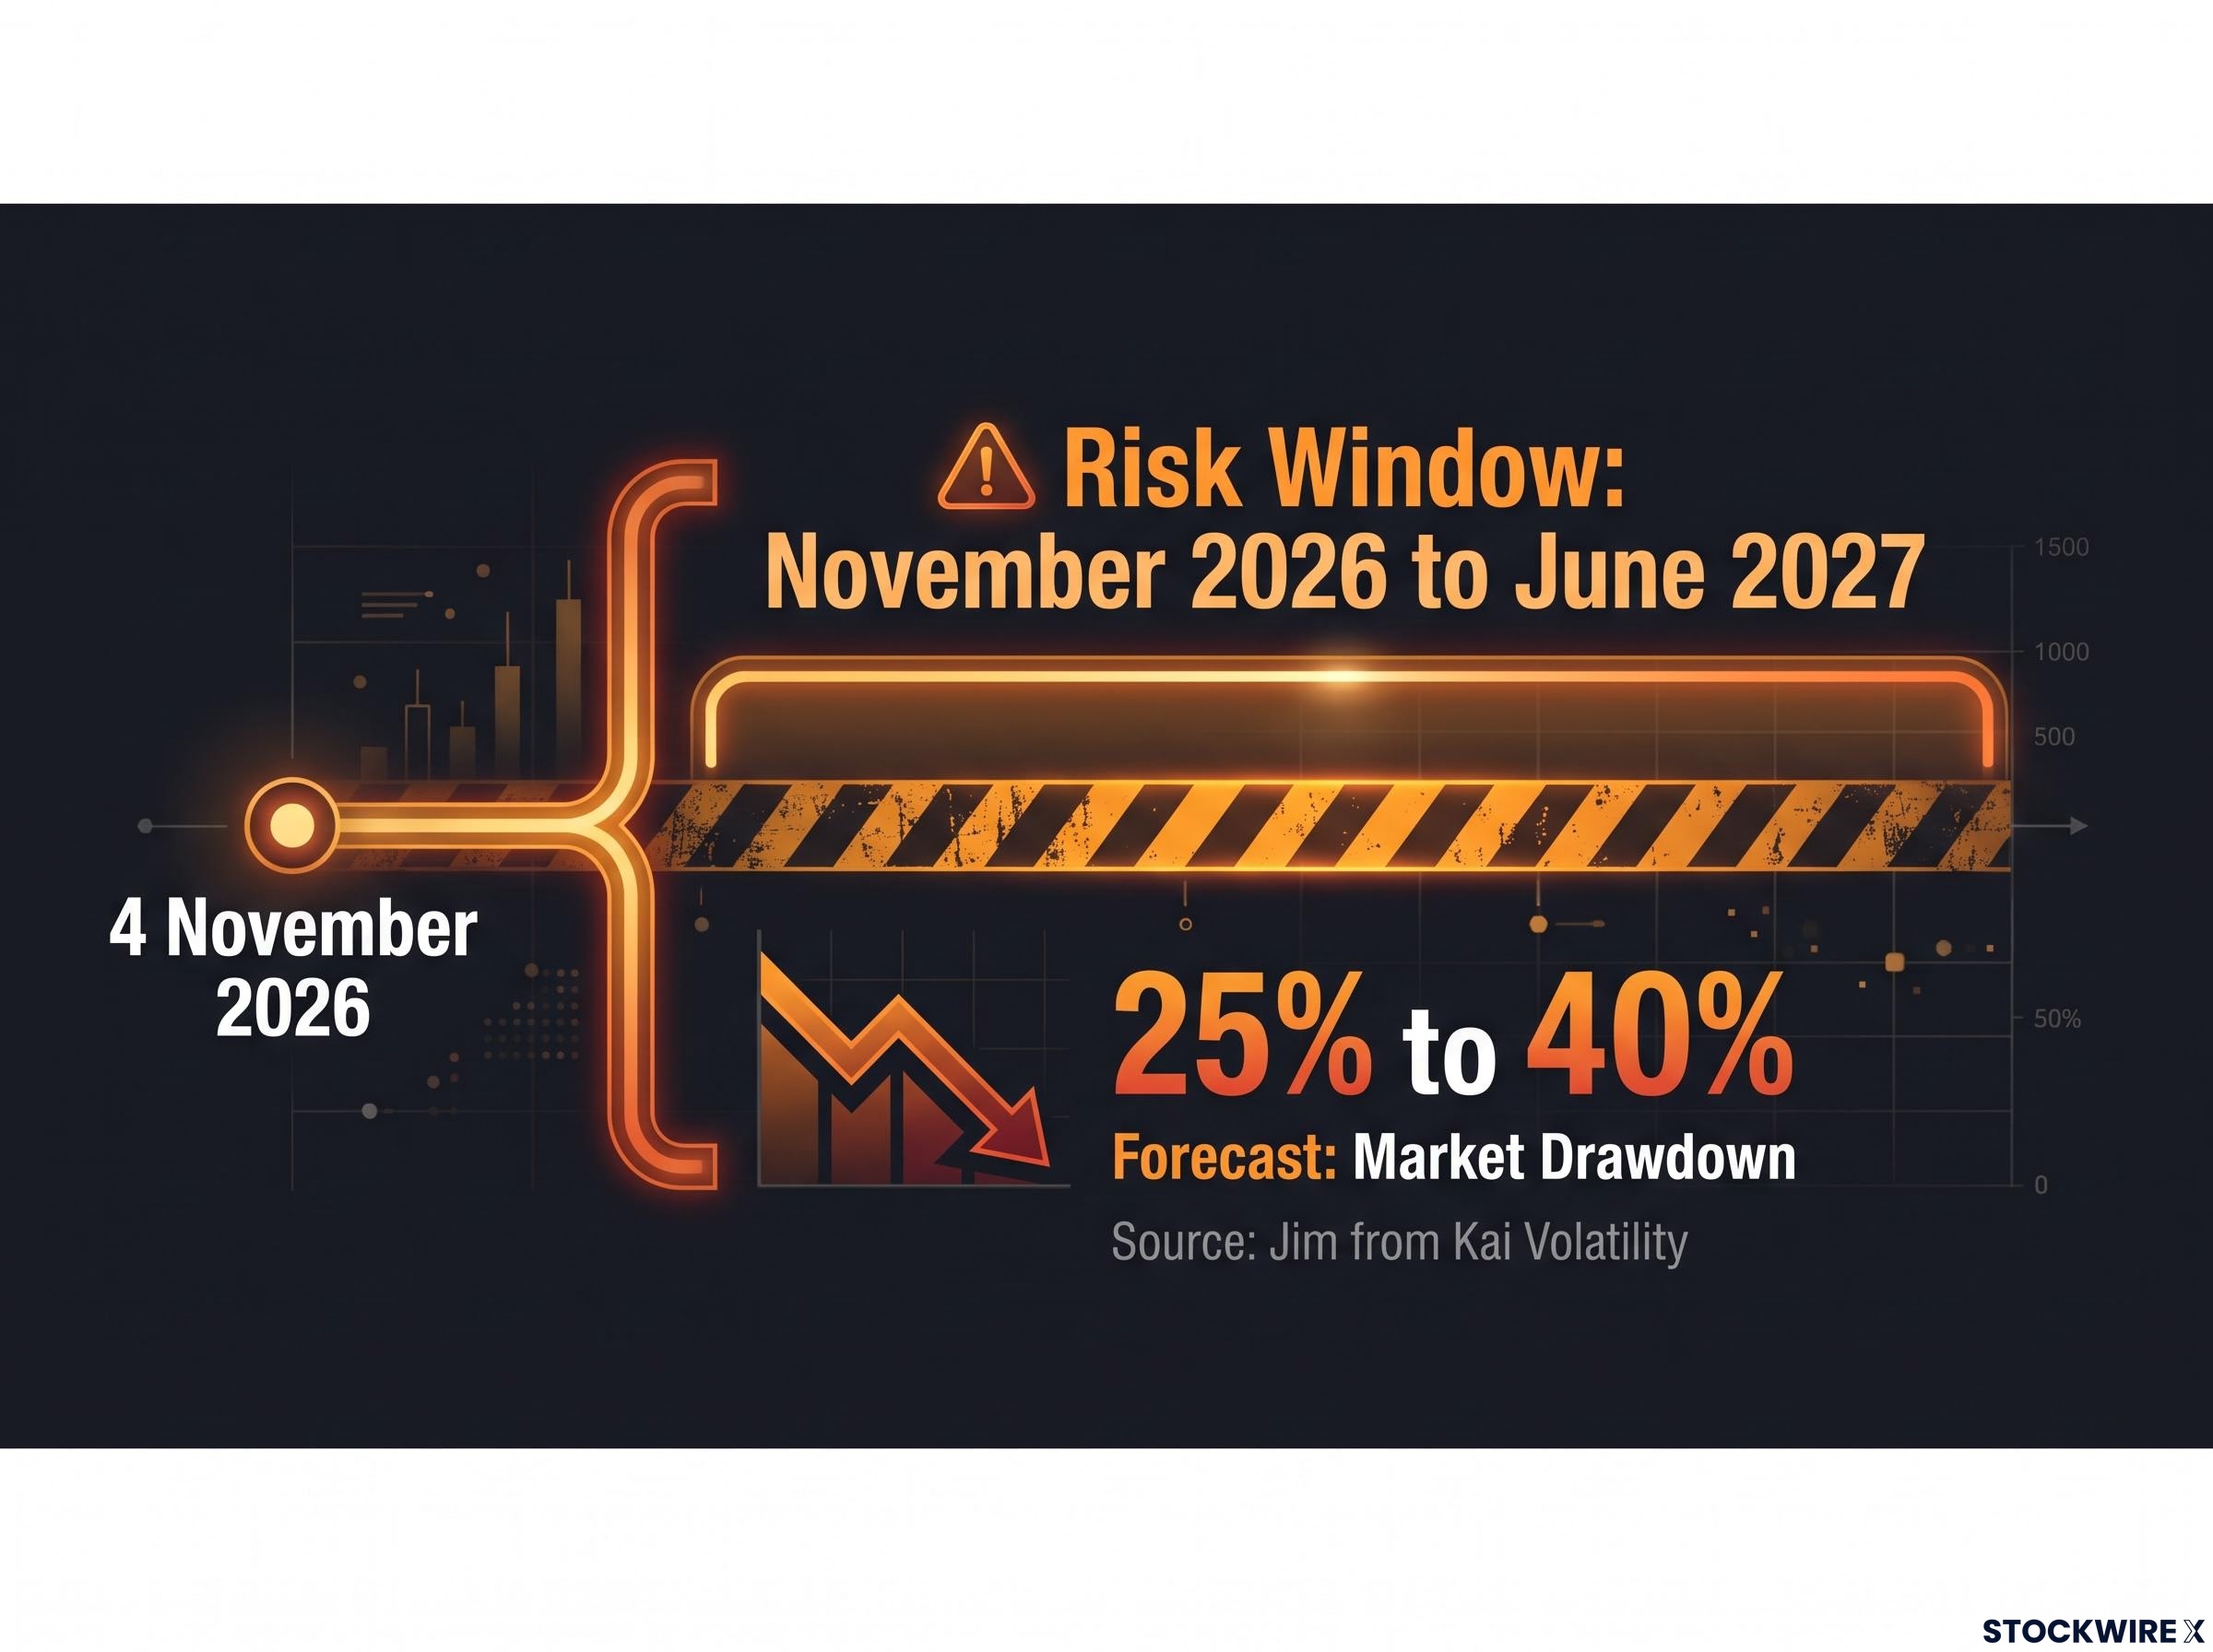
A market decline of 25% to 40%, potentially comparable in magnitude to the COVID-era drawdown, with onset projected between the midterms and approximately June of the following year.
That gives you a roughly seven-month positioning horizon, from early November 2026 through around June 2027. The COVID-era drop is the magnitude comparator, and the decline is framed as a genuine crisis rather than a routine correction, explicitly above a 20% threshold.
Now the honest part. No major bank or institutional forecast with a comparable numeric projection was located in available research. The 25% to 40% range originates with the original source, not with a Wall Street consensus.
The same source also flags a contested midterm outcome as a specific tail risk, one that could accelerate the timeline and pull deterioration forward, potentially even before the election. Three things are worth watching as the window approaches:
The Senate result as a market variable adds a layer the current article’s monitoring framework does not fully account for: prediction markets place the Senate near a coin flip, and the historical configuration of full opposition control of both chambers has produced the strongest post-midterm equity returns, a dynamic that interacts directly with whether the electoral constraint on buybacks lifts cleanly or into contested-outcome uncertainty.
- A contested election outcome, which the source names as an acceleration catalyst
- Inflation data releases that test the structural, oil-independent thesis
- Treasury auction demand metrics that reveal whether liquidity concerns are deepening
Here is how to weight all of this. The absence of institutional corroboration does not make the thesis wrong. It does mean the horizon is currently framed by a single analyst’s interpretive model rather than market consensus, and your risk management should reflect that distinction, neither dismissing the risk outright nor treating the specific numbers as settled fact.
Three variables to watch before the midterm window closes
You do not need to accept or reject the projection to act sensibly. You need a monitoring framework, and the data will tell you whether conditions are tracking toward the risk scenario or away from it. Three variables carry the signal, ranked by how directly they speak to the bond market.
- Treasury auction demand. Watch bid-to-cover ratios, meaning the value of bids received relative to the amount on offer, and indirect bidder participation, which captures foreign and institutional demand. Weak auction demand would confirm the liquidity concern is deepening rather than stabilising, the most direct signal the bond market gives.
- Inflation data releases. The structural inflation thesis is only tested when oil-independent indicators move. Headline CPI bouncing with energy prices tells you little. Core measures staying sticky while oil is stable is what would validate the structural read.
- Contested election signals. Polling data and state-level electoral developments matter because the original source names a contested outcome as an acceleration catalyst that could pull the risk window forward.
Anchor all of this to a hard date. The buyback programme runs through 4 November 2026, which sits right at the electoral deadline and gives you a concrete monitoring endpoint. Measure any deterioration against the 23 September baseline of a 4.98% 10-year and a 5.32% 30-year.
Here is the convergence to watch for. If auction demand weakens while yields hold elevated and oil-independent inflation stays sticky, all three structural drivers are firing at once. That is precisely the conditions profile the Kai Volatility thesis needs to materialise on schedule, and it is far more actionable to track than any single forecast.
What changes after the midterms, and what does not
Pull the threads together and the central distinction is this. The current calm is not a resolution of the structural drivers examined above. It is deliberate, time-bound management by Treasury, and its shelf life is tied to a political calendar.
The hard anchor is not speculative:
The expanded buyback programme runs through 4 November 2026, aligning almost exactly with the midterm election.
That date matters because it converts a political story into a structural one. The transition from managed stability to open risk is not a prediction about whether conditions change. The conditions, elevated yields, structural inflation, term-premium repricing, thin liquidity coverage, are present right now. The open question is only whether the management continues.
On the projection itself, keep the honesty intact. The 25% to 40% drawdown is one analyst’s model within a data environment where no major institution confirms comparable magnitude, and you should size your caution to the structural evidence, not to that single number.
The two interpretive poles define the range you are operating within: JPMorgan’s managed-stability reading on one side, Reuters’ insufficient-intervention reading on the other. The case for caution on long-duration exposure does not depend on the 25% to 40% figure being correct. It depends on whether the structural drivers are resolved before the electoral management ends, and the current data gives little sign that they will be.
So the frame is durable. Watch the three variables, treat 4 November 2026 as a hard horizon, and evaluate your most rate-sensitive positions against the structural evidence rather than the surface calm.
For readers wanting to stress-test the portfolio implications of yields moving materially higher from current levels, our deep-dive into a 6% yield scenario quantifies how mortgage rates, equity multiples, and corporate borrowing costs reprice if the long end continues its structural drift.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and the drawdown projection discussed here is speculative, single-source, and subject to change based on market developments.