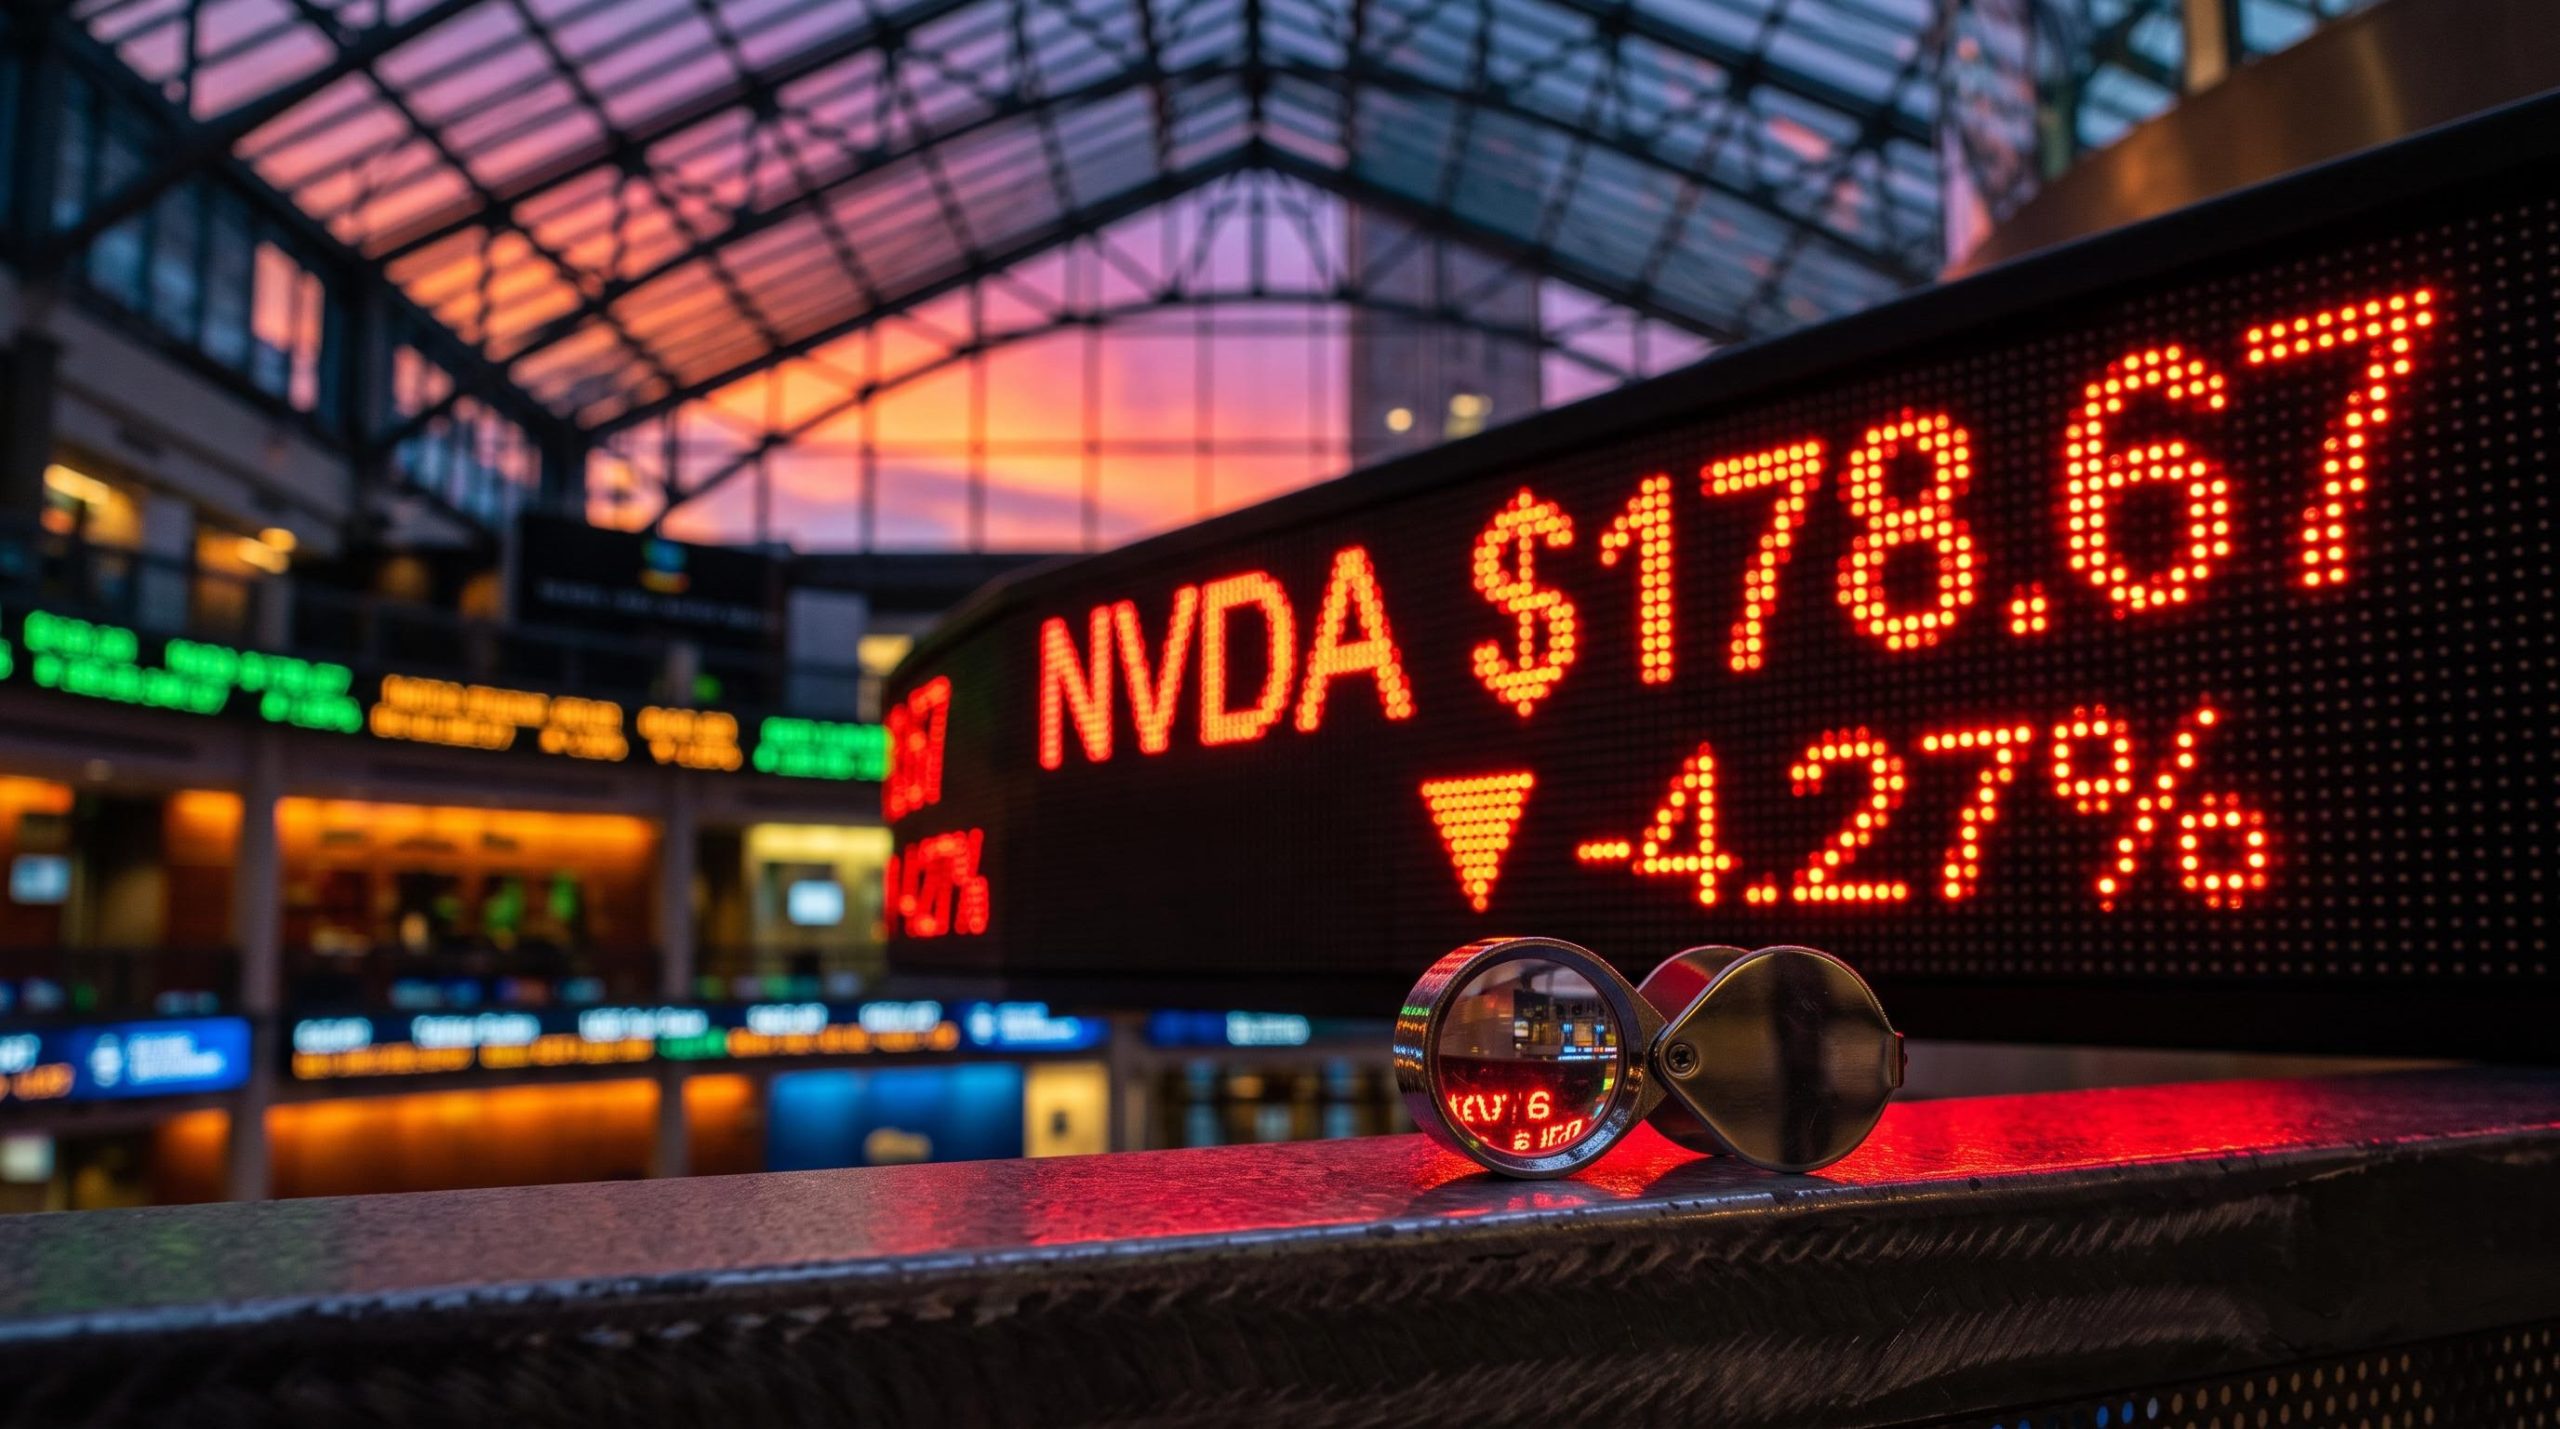
Nvidia’s board opened an independent investigation into its chief executive on Sunday, 8 November 2026. By the time the market opened the next day, the stock was already sitting deep in a drawdown. Nvidia stock closed at $178.67 on Monday, down 4.27%, but that one-day fall is the smallest part of the story.
The shares are being squeezed by three separate pressures at once. The first is the governance probe. The second is a burst of bearish put buying, and the third is an earnings test for the debt-funded cloud companies that buy Nvidia’s chips: CoreWeave reports on 10 November and Nebius on 12 November.
According to the original source coverage, roughly $1.5 trillion of market value has gone since the October peak. That figure is approximate.
The useful question is which of these pressures is doing the damage. Read on and you will be able to separate a governance shock from a broader repricing of AI financing, and you will know which signals deserve your attention this week.
How much of the Nvidia stock sell-off is the probe, and how much was already priced in?
The headline move looks like a scandal sinking a stock. On Monday, Nvidia fell $7.97 to $178.67. The original source puts its market capitalisation at about $4.3 trillion, against roughly $5.8 trillion at the peak.
Look further back, though, and the picture changes. The stock’s highest close was $237.47 on 7 October 2026, and its intraday high was about $239.24. Verified closing data puts Monday’s price roughly 24.8% below that October close.
The probe arrived on a stock that had already lost about a quarter of its value.
The earlier October slide fits a pattern of debt, not demand, driving the damage: leveraged names fell far harder than cash-rich hyperscalers such as Microsoft and Meta, which slipped only about 1% in the week of the chip rout.
The original source describes the fall as “nearly 30%” from the peak area. The verified close data does not support that figure. The gap may come from the source using intraday prices rather than closing prices, so 24.8% is the number to work with.
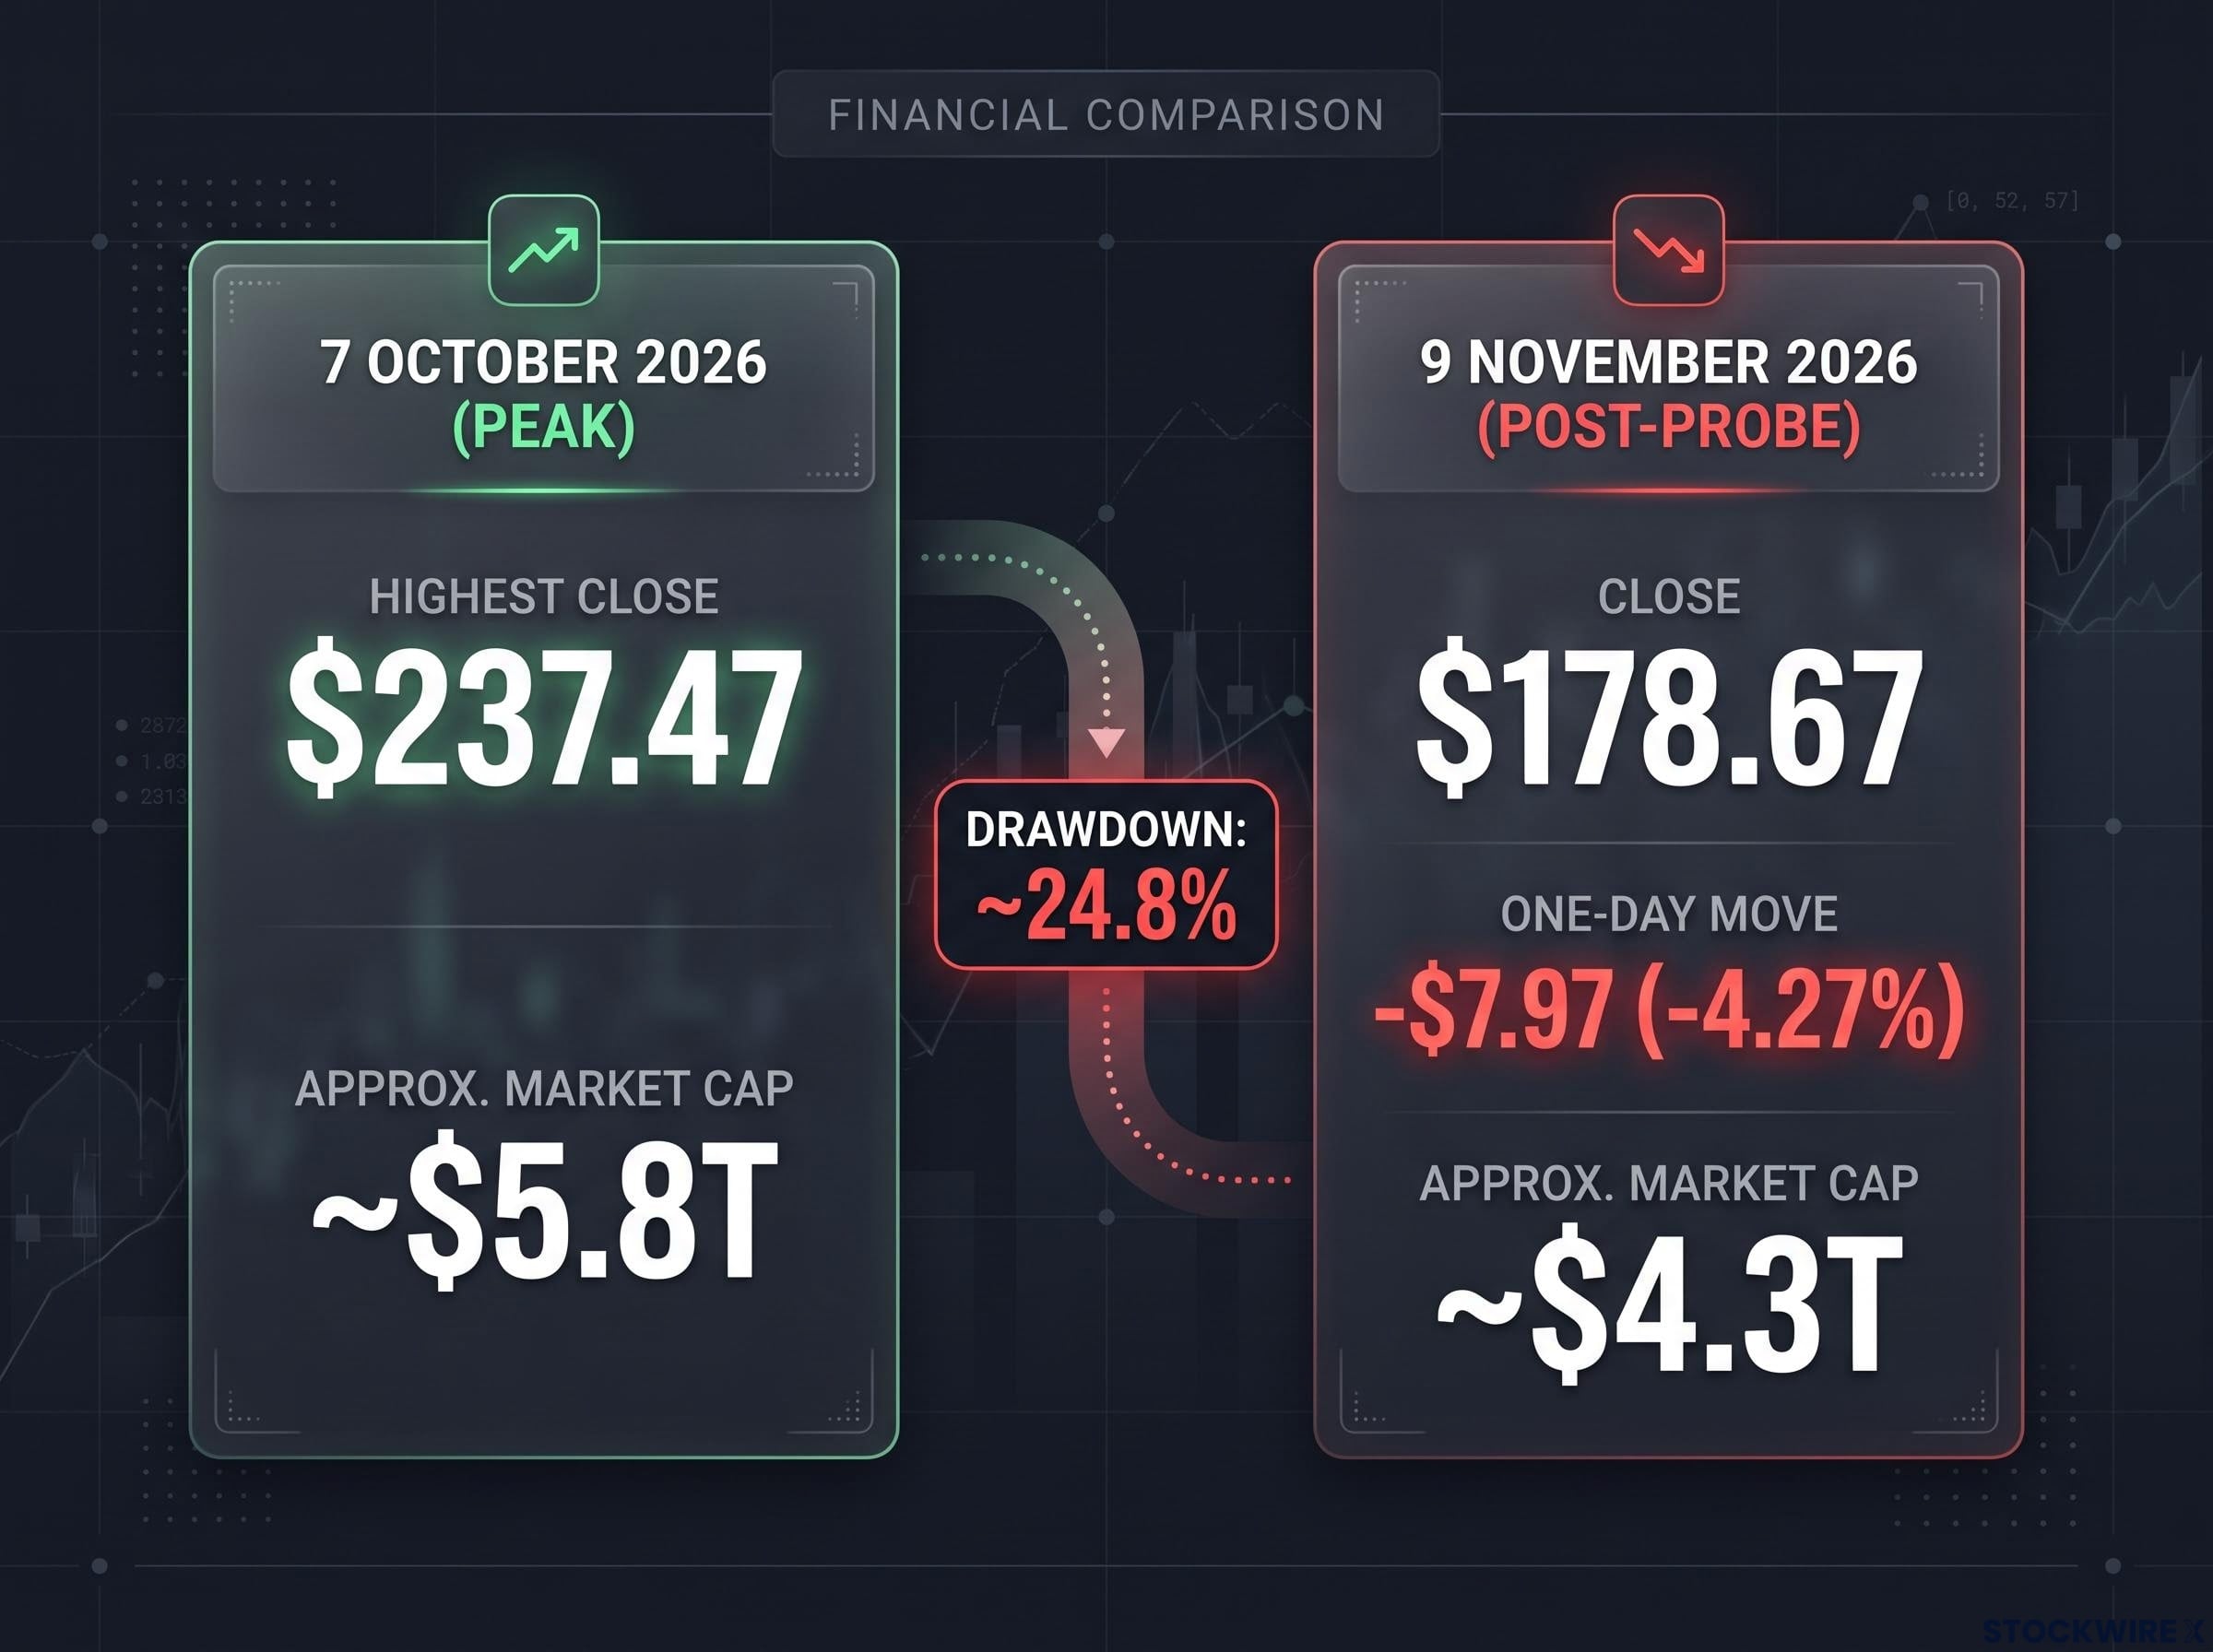
Nvidia’s stock had already suffered a ~24.8% drawdown from its $237.47 peak before the one-day -$7.97 drop following the probe.
| Measure | Figure | Date | Note |
|---|---|---|---|
| Highest close | $237.47 | 7 October 2026 | Verified close |
| Intraday high | ~$239.24 | October 2026 | Sources differ on the date |
| Latest close | $178.67 | 9 November 2026 | After the probe news |
| One-day move | -$7.97 (-4.27%) | 9 November 2026 | Closing basis |
| Approx. market cap | ~$4.3T vs ~$5.8T | Now vs peak | Source-attributed, approximate |
| Drawdown from highest close | ~24.8% | Since 7 October | Not the ~30% cited by the source |
The timing makes this harder to explain away. Nvidia had raised its forecasts the week before the news broke, so the earlier slide was not about the company’s own guidance. New Street Research estimates that up to 10% of Nvidia’s revenue may be tied to China directly or indirectly. That is an analyst estimate, not a line the company discloses.
What the board has and has not said
The confirmed facts are narrow. A committee of independent directors, working with outside counsel, will examine whether Jensen Huang was the target of a foreign-intelligence effort. Huang has said he will cooperate fully, and Nvidia said it has no reason to believe US national security or its proprietary information was compromised.
Reports link the probe to a relationship Huang has acknowledged with a Chinese businesswoman, whom US officials reportedly believed had acted as an intelligence asset. Reuters framed the issue as whether Huang was targeted, not as an allegation that he spied. Guo Jiakun, a spokesperson for China’s Foreign Ministry, called the claims “completely groundless.”
Nvidia has announced no finding of wrongdoing, and the probe remains open. The presenter in the original source suggested Huang could be temporarily sidelined, but that is speculation. If you judge the stock only through the governance headline, you risk misreading what actually has to be resolved before sentiment can recover.
When big ASX news breaks, our subscribers know first
What are the bearish options bets on Nvidia stock actually saying?
A put option gives its buyer the right to sell a stock at a set price, called the strike, before a set date. Buyers profit if the share price falls far enough below the strike to cover the premium they paid. The puts traded from Friday through Monday tell a story that gets more extreme the further down the strike ladder you go.
| Strike and expiry | Approx. premium | Breakeven | What it implies |
|---|---|---|---|
| November $180 put | ~$620,000 | ~$175.96 | Near-term momentum trade, already breached |
| 27 November $155 put | ~$1.38M | ~$151.15 | Another leg lower, about 13.5% below the morning price |
| April 2027 $120 put | ~$810,000 | ~$117.24 | Serious deterioration |
| November $110 put | ~$250,000 | Not given | Serious deterioration |
The $180 trade was a short-term bet, and the stock has already traded through it. The $155 put is a wager on a further drop while the probe runs, and the source reports that 84% of it printed on the trading floor, which suggests institutional activity. The $120 and $110 strikes need roughly 33-37% more downside, the kind of fall that would take Huang’s removal, findings of wrongdoing or a broad AI repricing.
Then the scale shrinks.
About $3 million versus $4.3 trillion The deep-strike puts carry roughly $3 million of combined premium, set against a company valued at about $4.3 trillion.
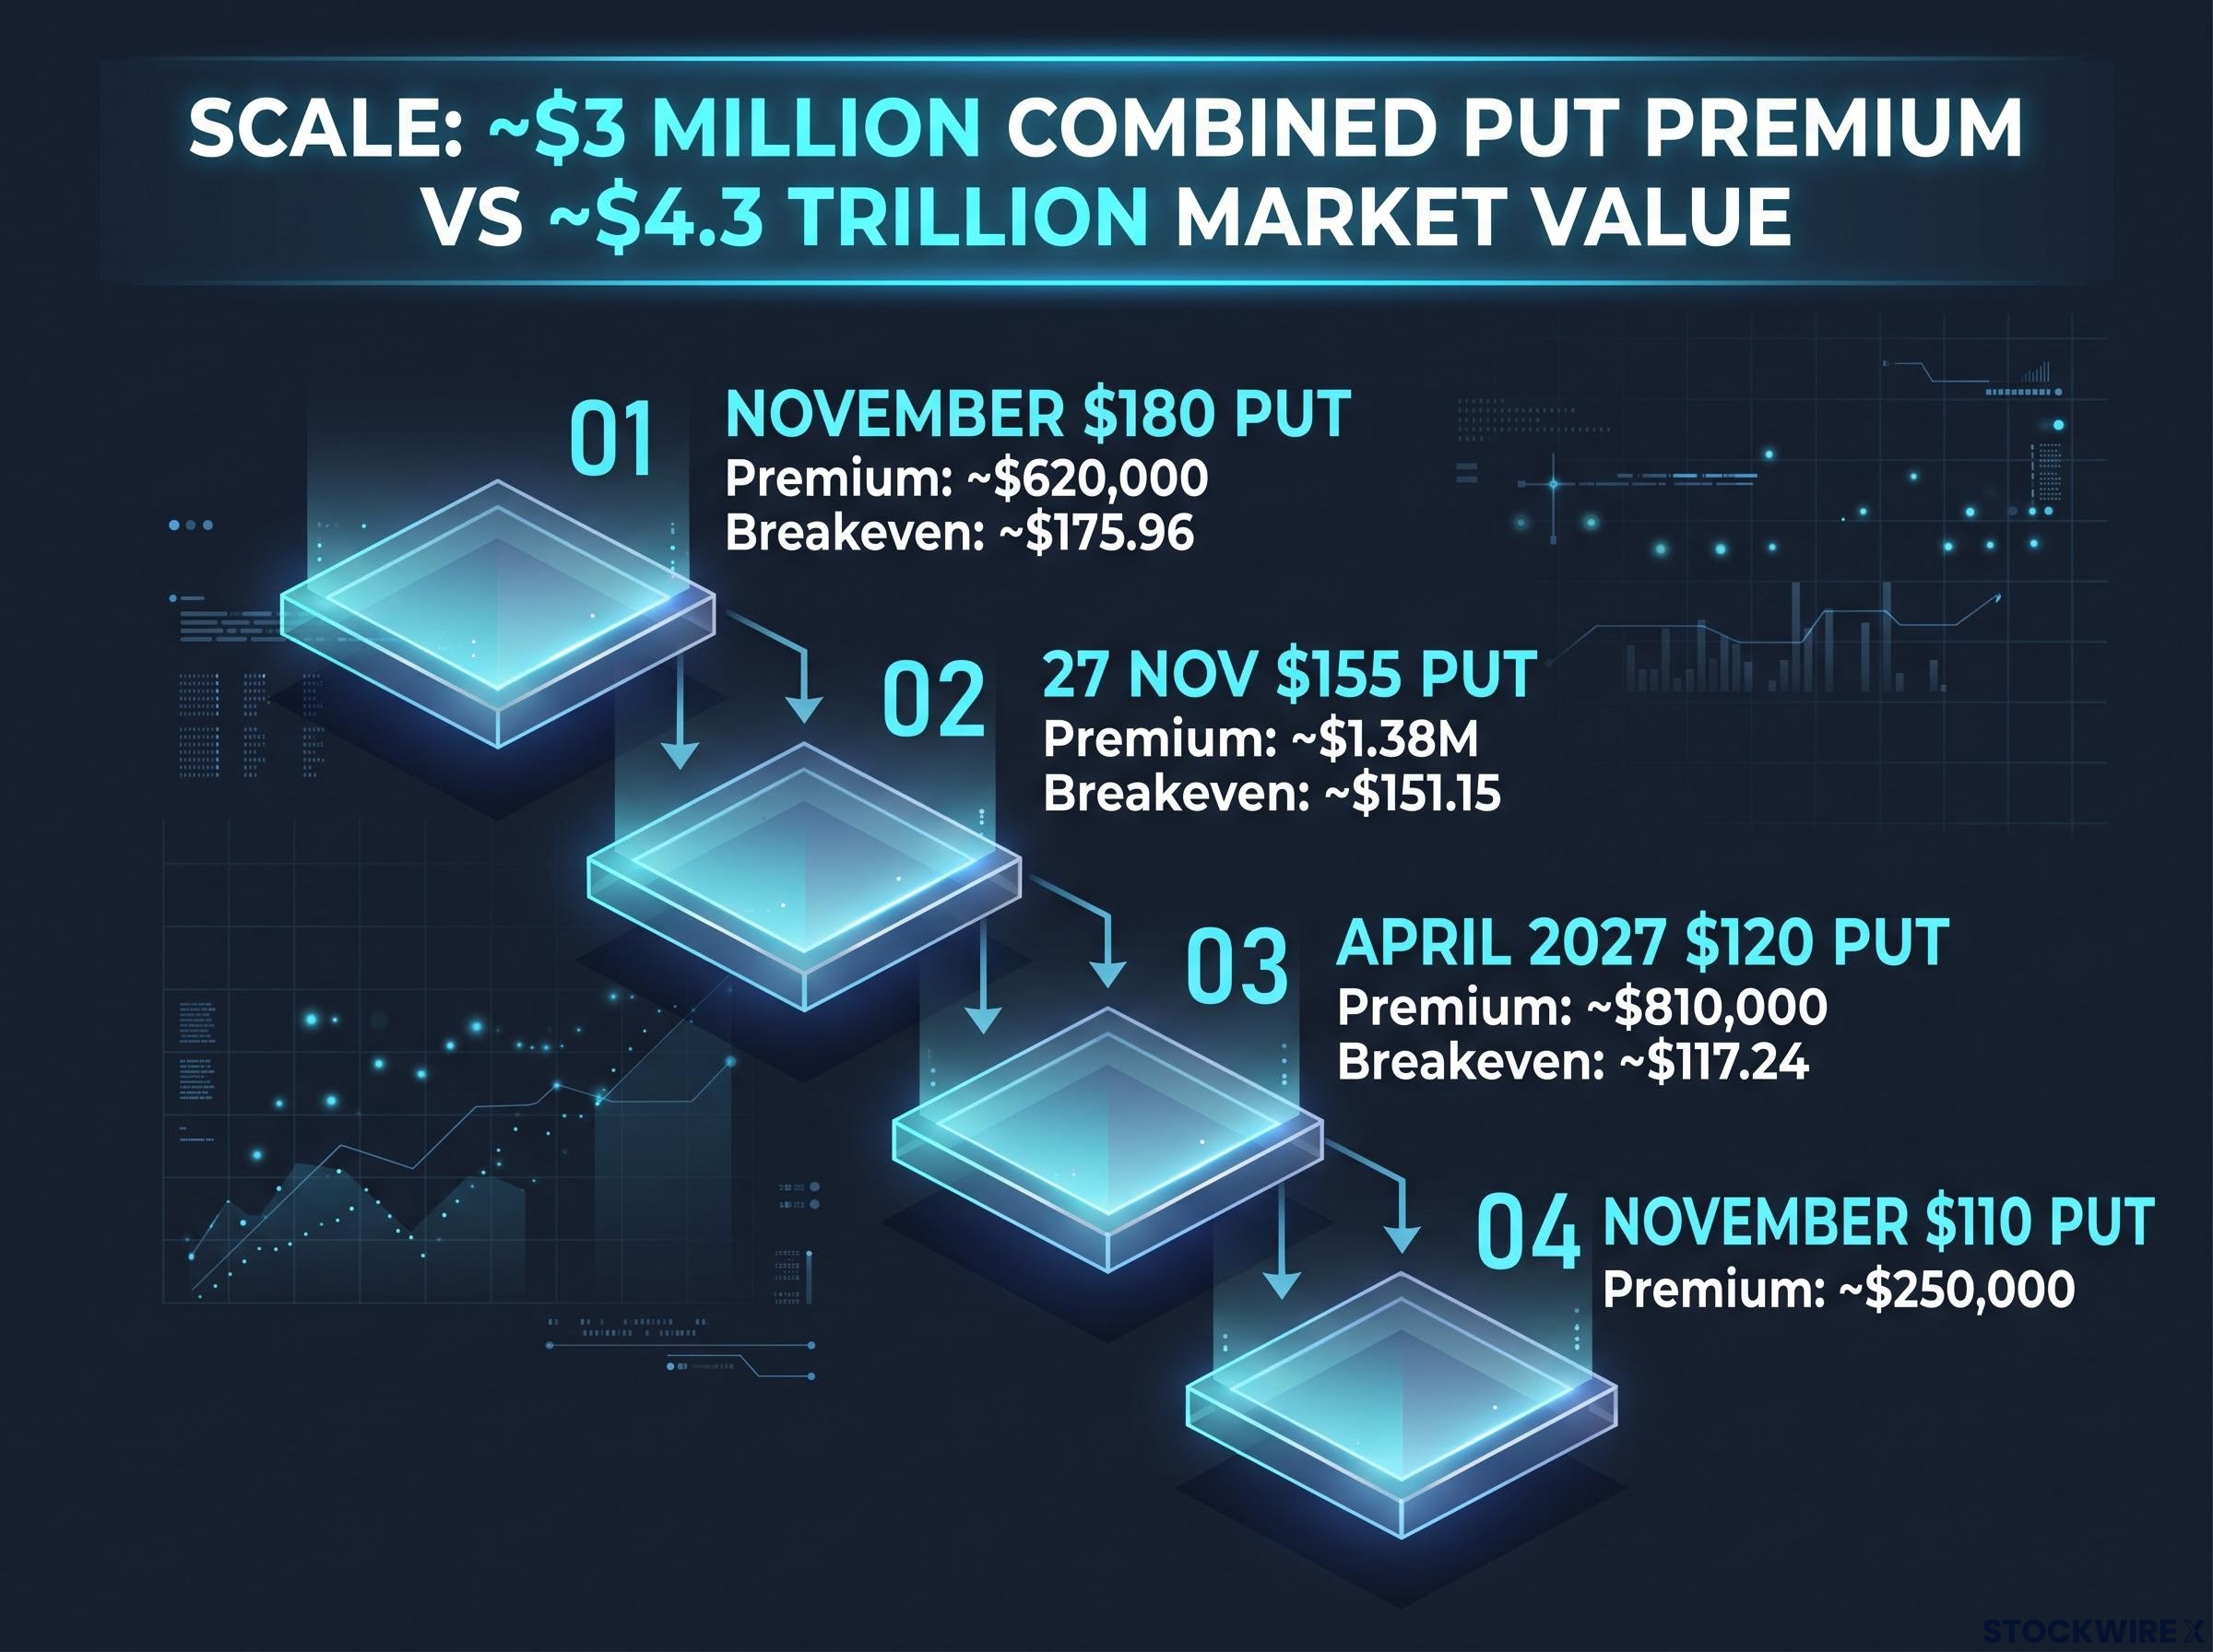
The combined premium for deep-strike puts represents roughly ~$3 million, a tiny fraction of Nvidia’s ~$4.3 trillion market value.
The tape has limits. Trading volume counts contracts being closed as well as opened. Open interest, the number of contracts still outstanding, does not show which direction a trader is betting. Any single put could be a hedge on an existing holding or one leg of a spread rather than an outright bet on a fall.
Public data also conflicts with the source. One $180 put contract (11 November expiry) showed volume of 11,013 against open interest of 4,121. The only $120 contract located expired on 6 November and last traded at $0.01, which does not point to new buying. No public data surfaced for the $110 strike, and the figures are daily totals with open-interest updates still pending.
Treat the options tape as a gauge of sentiment, not a forecast. The presenter argued that whether the stock closes its recent price gap this week is the stronger signal, and that view deserves more weight than a few million dollars of premium.
Why does Nvidia’s role as the “central banker of AI” make neo-cloud earnings matter?
Bloomberg coverage has described Nvidia as the central banker of AI. According to the original source, the company has lent or invested more than $300 billion across the sector in recent years. The label matters because of how money moves around the industry.
“Neo-clouds” are newer companies that rent out AI computing power from data centres packed with Nvidia chips. The financing loop works like this:
- Nvidia sells chips and networking equipment to these cloud and AI-infrastructure companies.
- The customers borrow heavily to buy that equipment and build data centres.
- Nvidia invests in some of them or supports their expansion.
- Nvidia may help create demand by buying capacity the customers cannot sell.
- The customers’ revenue and valuations then support more borrowing and more Nvidia purchases.
Step four is not hypothetical. Reuters reported that Nvidia agreed to buy unsold CoreWeave capacity through April 2032, up to $6.3 billion.
None of this is evidence of fraud, and the loop can reflect real long-term demand. The risk is that financing, chip orders and valuations feed each other faster than revenue from end users of AI can justify.
The numbers show the strain. CoreWeave carried about $51.61 billion of debt at 30 June, up from $14.56 billion a year earlier. In Q2 it posted revenue of $2.58 billion, a net loss of $626 million and net interest expense of $640 million, while its backlog stood at about $104.2 billion, with more than $25 billion of new commitments signed early in Q3.
| Measure | CoreWeave | Nebius |
|---|---|---|
| Debt | ~$51.61B (30 June) | ~$10.06B debt and leases vs ~$8.04B cash |
| 2026 capex plan | $35-39B | $20-25B |
| Backlog | ~$104.2B plus $25B+ new | ~$40B |
| Q3 report date | 10 November, after the close | 12 November, before the open |
Nebius also has a $775 million asset-backed facility and expects more than $9 billion of customer prepayments in 2026. Capex, or capital expenditure, is the money a company spends on long-term assets such as data centres.
CoreWeave debt risk is shaped by more than the backlog: bonds yielding 15-16% and a return on capital estimated below its borrowing costs mean each new debt-funded dollar can erode value, which is why investors treat the 10 November print as a financing test.
These two reports are a read on whether Nvidia’s customers can keep funding their build-outs, and that feeds straight into Nvidia’s own demand outlook. Strong results could support the sector even while the probe stays unresolved.
Can Nvidia manage key-person risk if Jensen Huang is sidelined?
Key-person risk is the danger that a company suffers if one individual can no longer do their job. At Nvidia, that individual sets the strategy.
“Not an ordinary CEO” Stacy Rasgon of Bernstein argues that Nvidia is not an ordinary company and Huang is not an ordinary CEO. Huang shapes long-term strategy and reportedly manages roughly 60 direct reports.
Huang also owns about 3.58% of the company, around 871 million shares as of 23 March 2026, according to the 2026 proxy statement. The source’s 3.4% figure is a rounding. The board’s task, as CNBC put it, is to show independence while protecting shareholders from unnecessary disruption.
Experts disagree on how well placed the board is to do that:
- Dan Ives: replacing Huang would be nearly impossible.
- David Larcker (Stanford): without a meaningful succession plan, the board would need outside advisers to build one.
- Charles Elson (governance expert): the episode shows why a succession plan has to exist before a crisis.
- Jill Fisch (Penn Carey Law): questioned whether long-serving directors are independent enough.
- Jeffrey Sonnenfeld (Yale): called the lack of an obvious successor remarkable and floated a symbolic, non-operating role for Huang.
- Ben Emons (strategist): Huang’s full cooperation suggests little to hide, although confidence could still suffer.
The presenter in the original source shares part of Fisch’s doubt, noting that the board is largely made up of Huang supporters. Nvidia’s own proxy warns that relying on a longstanding executive team without effective succession could harm performance. No successor has been publicly named.
No precedent matches this case exactly: a founder CEO, alleged targeting by foreign intelligence and national-security implications at a company worth roughly $4 trillion. Probes into other mega-cap CEOs suggest markets can look past uncertainty when findings are limited and a credible successor exists. For you, that means succession disclosures and any change to Huang’s role will matter more than the probe’s verdict itself.
Where the Nvidia stock thesis goes from here: three signals to watch
The probe is open with no finding. The drawdown is real, but most of it came before the investigation was announced. The options tape reflects sentiment more than conviction, and the neo-cloud financing loop is the more structural variable underneath the share price.
Three signals will tell you which force is winning:
- CoreWeave and Nebius results: watch what management says about debt, funding costs and turning backlog into revenue.
- Board updates: any statement on the probe’s findings, Huang’s role or a succession plan.
- Price and positioning: whether the stock closes its recent gap, or whether open interest builds in the deep-strike puts.
If the financing test holds and the board shows a credible plan, the governance discount has room to fade. If either falters, the October peak will look further away.
For readers weighing the neo-cloud side of the trade, our detailed coverage of Goldman’s neocloud thesis explains how 15-20-year lease contracts underpin the case.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.