The Nasdaq Composite fell 2.9% on Friday, 30 October 2026, to close at 25,437.00, its worst session since 5 June. The tech stock sell-off was deep enough to push the Nasdaq 100 briefly into correction territory (a fall of 10% or more from a recent peak) before buyers lifted it back above that line by the close.
Two results did the damage. Intel lost roughly 29% in a single day after a guidance shock, and Amazon disclosed a cash burn large enough to unsettle even investors cheering its cloud growth.
The common thread is a change in what the market wants from artificial intelligence spending. Ambition no longer earns a premium on its own. Proof of payback does.
Here is why investors are now penalising spending that has not yet returned cash, and what the rotation into energy and defensive stocks tells you about where money is moving.
Why is the market now punishing AI spending that has not paid back yet?
For two years, the investor question was how much AI infrastructure the largest companies could build. On Friday, it became a different question: who pays for it, and when does it start earning cash?
The damage spread well beyond the Nasdaq.
| Index | Close | Point move | % move |
|---|---|---|---|
| Nasdaq Composite | 25,437.00 | -747.73 | -2.86% |
| S&P 500 | 7,580.07 | -140.32 | -1.82% |
| Dow Jones Industrial Average | 51,770.31 | -572.25 | -1.09% |
| Russell 2000 | 2,811.84 | -47.37 | -1.66% |
The Nasdaq now sits 7.8% below its 6 October record. The VIX, a measure of expected market volatility often called Wall Street’s fear gauge, peaked at 23.93 intraday before settling near 19.4.
The core problem is timing. AI outlays hit balance sheets immediately and lose value as the equipment depreciates. The revenue they are meant to generate depends on how quickly businesses adopt AI tools and how much they will pay.
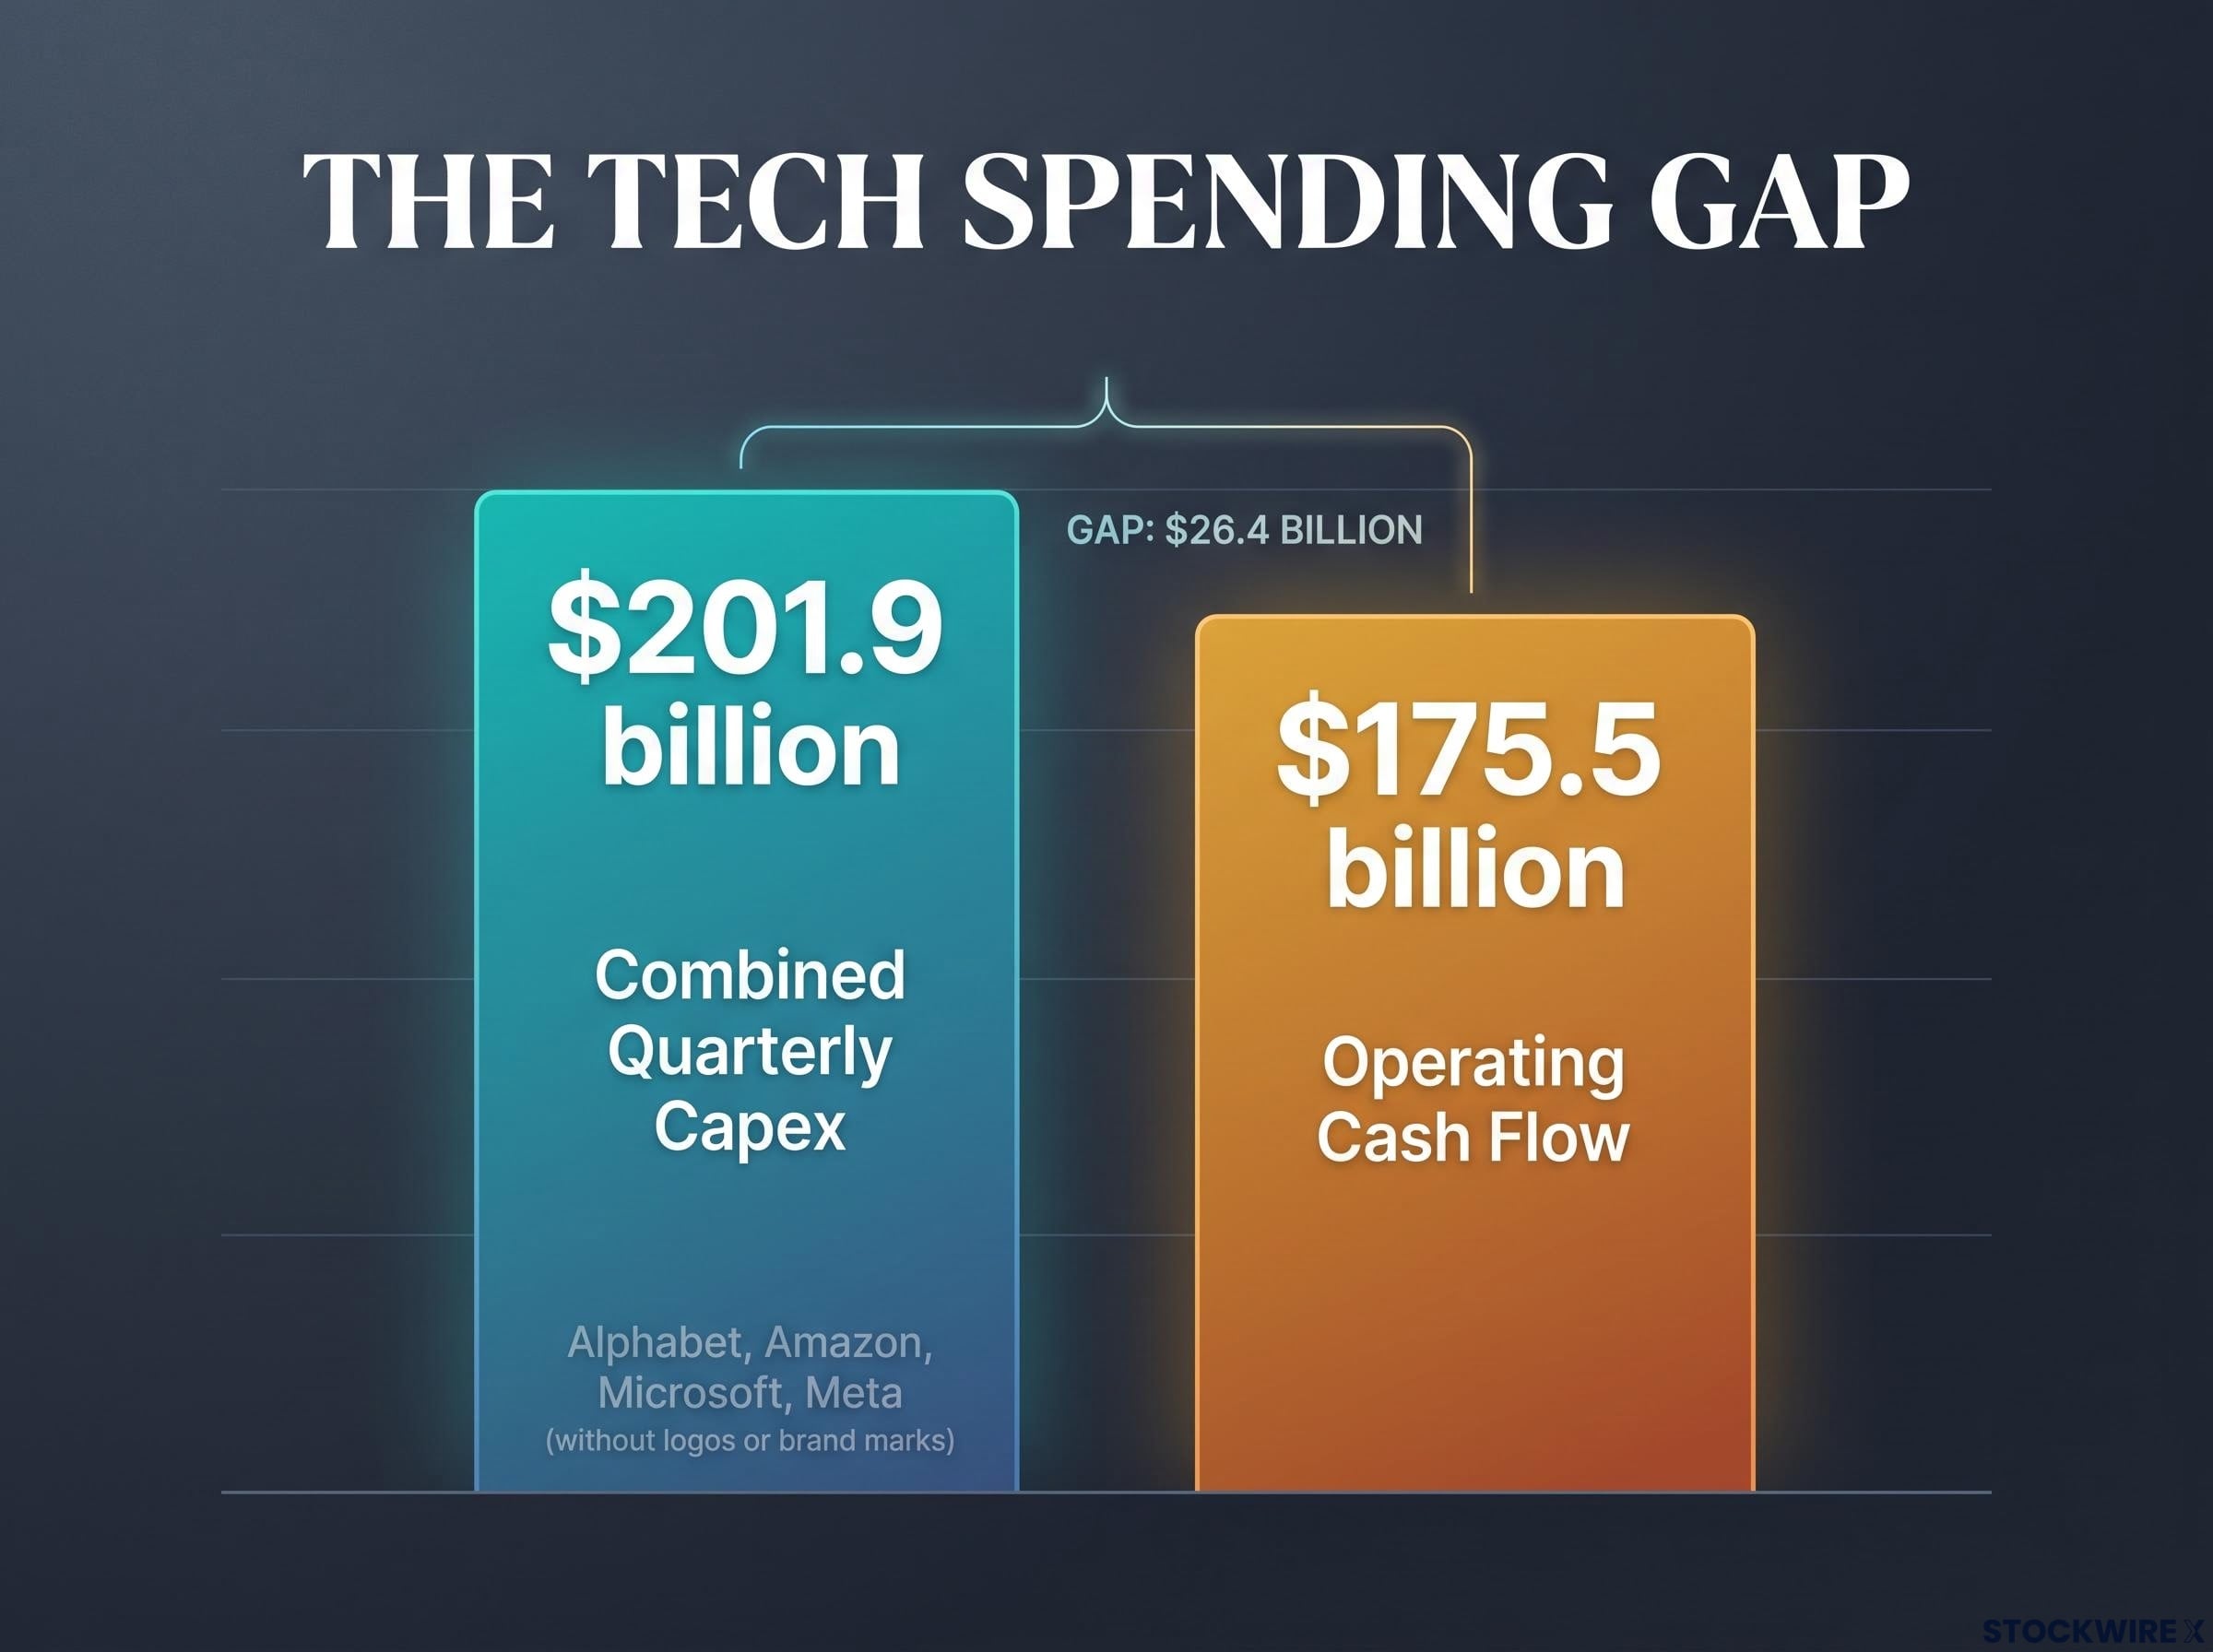
The scale makes the gap hard to ignore. Reuters cited a J.P. Morgan forecast of about $900 billion in global AI capital expenditure (capex, or spending on physical assets) in 2026. FourWeekMBA’s own calculations from company filings put combined quarterly capex at Alphabet, Amazon, Microsoft and Meta at about $201.9 billion, against roughly $175.5 billion of operating cash flow. Aggregates vary depending on what they include, but the direction is consistent.
Lofty valuations amplify every disappointment. When expectations sit this high, a headline earnings beat cannot rescue a stock if guidance implies slower growth or heavier spending.
The shift began earlier in the year, when AI capital expenditure started to be treated as a valuation risk rather than a growth signal, with stocks falling on strong revenue beats if the payback timeline stayed unclear.
Execution is being scored Oliver Pursche of Wealthspire Advisors said companies falling short of high AI expectations are being penalised, while those meeting them continue to perform well.
The broader earnings season was strong. According to LSEG, 82% of 299 reporting S&P 500 companies beat estimates, with third-quarter earnings growth tracking 31.6%. That those results offered no shelter tells you the market is now pricing cash returns and guidance, so a company’s quarterly numbers alone no longer explain its share price.
When big ASX news breaks, our subscribers know first
Intel’s record drop and Amazon’s cash burn: what each one exposed
Headlines blended Friday’s two catalysts into one story about AI spending. They are different problems, and that is why strength in one place could not offset weakness in the other.
Intel: a PC and memory squeeze
Intel’s fourth-quarter outlook landed well short of what analysts expected.
| Q4 2026 metric | Intel guidance | Analyst consensus |
|---|---|---|
| Revenue | $15-16 billion | About $17 billion |
| Adjusted EPS | $0.25 | $0.43-$0.44 |
The shares fell about 29.2%. Reuters reported the stock was headed for its biggest one-day decline ever, and contemporaneous coverage described it as the largest in the company’s history.
The cause sits in personal computers, a business that made up roughly half of Intel’s third-quarter revenue. Intel forecast PC unit declines of about 12% in 2026 and 10% in 2027, with weakness lasting at least through the first half of 2027. Rising memory prices, driven partly by memory production shifting toward AI applications, are squeezing demand.
Amazon: strong cloud growth, negative free cash flow
Amazon’s problem looked almost opposite. Amazon Web Services (AWS) revenue jumped 39% to about $46 billion, its fastest growth in nearly five years.
The rest of the report was harder to cheer. Earnings per share of $1.89 missed consensus by about 4%, e-commerce growth was the slowest in three years, and free cash flow (cash left after capital spending) came in at negative $42.4 billion for the quarter. Amazon expects about $220 billion in 2026 cash capex and meaningfully more in 2027.
AWS has not stalled. The concern is that the cost of building AI capacity is outrunning the cash the business generates.
Amazon is not alone in this position: Alphabet reported its first-ever quarter of negative free cash flow in July, after $44.9 billion of capex overwhelmed operating cash flow.
The shares fell about 7% after hours before recovering to close down 1.4% on Friday. If you hold either stock or a broad tech fund, the message is that revenue growth and demand headlines matter less right now than guidance and free cash flow.
What does the chip sell-off say about AI demand?
Intel’s warning tore through semiconductor screens. The chip index fell 7.2% on the day, taking its October loss past 15%, while the semiconductor ETF dropped 8.24%.
PC hardware names took the heaviest hits:
- AMD: down 10.9%
- Dell: down 10.8%
- HP: down 9.6%
Memory is the link between AI and the PC slump. Suppliers are prioritising high-bandwidth memory, a fast chip type built for AI systems, which leaves less for PCs and pushes their costs higher. Samsung underlined the shortage by hosting OpenAI CEO Sam Altman and about 50 executives to deepen cooperation on memory and AI infrastructure.
That shortage cuts both ways. It hurts PC makers but benefits memory producers, shifting profit within the chip sector rather than draining it.
The cyclical reading
On this view, PC weakness, memory scarcity and inventory adjustments are temporarily depressing chip demand while data-centre spending keeps expanding. Intel itself said data-centre demand exceeds available supply, with shortages potentially lasting through 2027 and 2028. The sell-off, read this way, reprices near-term earnings rather than rejecting the AI buildout.
The structural reading
The more cautious view holds that the industry may be building capacity before end-user revenue catches up, leaving chip suppliers exposed to cancelled orders. Reuters compared the AI spending cycle with past infrastructure booms, though today’s buyers are profitable hyperscalers rather than the mostly unprofitable start-ups of 2000.
For investors, “chips” is not one trade. PC-exposed names and AI data-centre names face different pressures, so judge your exposure by end-market rather than by sector label.
Why energy and defensives caught the bid
Beneath the tech rout, part of the market quietly rose.
| Sector | Move on 30 October |
|---|---|
| Information Technology | -4.24% |
| Industrials | -1.57% |
| Communication Services | -1.11% |
| Energy | +1.91% |
| Consumer Staples | +1.38% |
Utilities and health care also gained, although one market summary put energy’s rise closer to 1.6%. Over the week, the S&P 500 slipped 0.57% and the Nasdaq 2.00%, while the Russell 2000 added 1.29% and the equal-weight S&P 500 notched a fourth straight weekly gain. Staples and utilities each rose more than 10% in October.
The energy bid rested on hard profits, not mood.
| Company | Q3 net income | Prior year | Adjusted EPS vs consensus |
|---|---|---|---|
| ExxonMobil | $15.4bn | $7.5bn | $4.23 vs about $4.12 |
| Chevron | $9.9bn | $3.5bn | $5.28 vs about $4.89 |
Exxon shares rose more than 2%. Both companies benefited from high oil prices and unusually strong refining margins tied to war-related supply disruption in Iran and Ukraine.
Part of the energy windfall reflects structure rather than only conflict, as US oil production has tripled since 2008 and now recirculates a large share of high-price income through the domestic economy.
That source of strength is also its limit. Energy gains could reverse if geopolitical risk eases, and staples and utilities are sensitive to interest rates, according to The New York Times.
If your portfolio is concentrated in large-cap growth, this session shows how much of your return rides on a handful of AI-linked names. Rotation can cushion a fall without replacing tech leadership.
What the sell-off settles, and the signals to watch next
Friday’s move was a repricing of AI execution, financing and near-term demand risk. On evidence through 1 November, it does not prove the AI investment cycle has ended. AWS growth of 39.3% and data-centre demand exceeding supply both argue the buildout continues.
Three signals will shape what comes next:
- Cash disclosures: further capex and free-cash-flow updates from the largest cloud spenders.
- PC and memory pricing: whether cost pressure eases through the first half of 2027.
- Rotation durability: whether energy and defensive leadership holds as yields and oil move.
If you are weighing your tech exposure, the useful question is no longer how much a company spends on AI, but how soon that spending turns into cash.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.