The Czech National Bank is expected to keep its main interest rate on hold today, and almost nobody in the market disagrees. Every economist polled by Bloomberg lined up behind the same forecast. The controversy is not the decision itself but what the market thinks comes after it.
Because while the CNB sits still, traders have quietly priced in more tightening over the next twelve months than for any other central bank in the region. That is the paradox of the 17 September 2026 CNB interest rate decision: a fully priced hold sitting on top of an aggressive forward path that not everyone believes. The bank holds at 3.75% after hiking in June and pausing in August, even as Hungary cuts actively and Poland edges toward easing.
By the end of this piece, you will have a clear read on whether the tightening baked into Czech rates is realistic or overcrowded, what that positioning means for the koruna specifically, and which external variables to watch before the repricing risk turns from theory into a live trade.
The only hawk left standing: how the CNB diverged from its regional peers
Three central banks, three directions. That is the setup, and it matters more than any single rate level.
The CNB raised its two-week repo rate by 25bp to 3.75% on 18 June 2026, then held there on 6 August 2026. The National Bank of Poland (NBP) went the other way, cutting to 3.75% in March and holding through July with an easing tilt. Hungary’s Magyar Nemzeti Bank (MNB) is deeper into its own easing cycle, stepping the base rate down to 5.50% effective 26 August 2026.
| Central Bank | Current Rate | Recent Direction | Last Action | Forward Tilt |
|---|---|---|---|---|
| CNB (Czech) | 3.75% | Tightening | Held 6 Aug 2026 | Hawkish |
| NBP (Poland) | 3.75% | Easing | Held Jul 2026 | Dovish |
| MNB (Hungary) | 5.50% | Easing | Cut 26 Aug 2026 | Dovish |
Notice that the CNB and NBP share the same headline number, 3.75%. That equality is misleading. One bank arrived there by cutting, the other by hiking, and it is the direction of travel, not the current level, that drives currency positioning. Poland’s Governor Adam Glapiński has signalled cuts could be near, according to ING; the CNB is still talking about restrictiveness.
NBP policy divergence has already produced measurable EUR/PLN moves within single sessions, a pattern that mirrors the CNB dynamic: in both cases, it is the governor’s wording rather than the rate level itself that the market is trading, making communication tracking the more actionable variable.
Commerzbank’s read on the divergence Commerzbank analyst Tatha Ghose describes the CNB as “the only central bank in the region that is likely to raise interest rates in the coming months.”
The CNB’s stance rests on domestic pressure it cannot ignore. At its June decision, Reuters reported the bank citing core inflation at 2.9%, services inflation near 5%, a tight labour market driving wage gains, and strong credit growth, even as headline inflation sat at just 2.1%.
Here is what this tells you. The region trades under a single “CEE” label, but it is not one risk bloc. Position on the label rather than the policy direction and you will likely end up on the wrong side of the koruna trade that follows.
When big ASX news breaks, our subscribers know first
What 125 basis points of priced tightening actually means for the koruna
If the divergence is settled, the pricing is anything but. Look at how the tightening expectations built through September, and the escalation is hard to miss:
- 1 September 2026: ING noted the Czech market pricing “almost four rate hikes,” with Czech curves in hawkish mode.
- 7 September 2026: ING put priced tightening at “around 80bp” and flagged it as excessive.
- 17 September 2026: Commerzbank’s Michael Pfister said markets expect up to 125bp of CNB tightening over the next twelve months, with ING describing pricing that implies “more than four rate hikes.”
The mechanics here are straightforward. Hawkish CNB expectations widen the interest-rate advantage the koruna offers, which pulls in carry-trade inflows and pushes EUR/CZK lower. That support holds only as long as the expectations stay credible.
Rate differentials and currency positioning interact through a well-established transmission chain: the gap between domestic and external rates sets the carry return, which determines inflow volumes, which then moves the exchange rate, a framework that applies to EUR/CZK just as it does to EUR against any carry-funded currency pair.
ING’s caution on the pricing ING’s Frantisek Taborsky characterised around 80bp of priced Czech tightening as “excessive.”
That word matters. When several credible desks are quoting materially different figures for the same market variable inside a single week, the spread itself is a signal. It tells you positioning is stretched and the market is already arguing with itself. The next data point that undercuts the hawkish story is the one that moves the exchange rate hard, precisely because so many are leaning the same way.
Where EUR/CZK goes if the CNB actually delivers
The bullish koruna case has a number attached. ING’s target sits below 24.15, and the broader forecaster range for end-2026 EUR/CZK clusters at 24.10-24.50, drawing on ING, Komerční banka, and CBA Monitor.
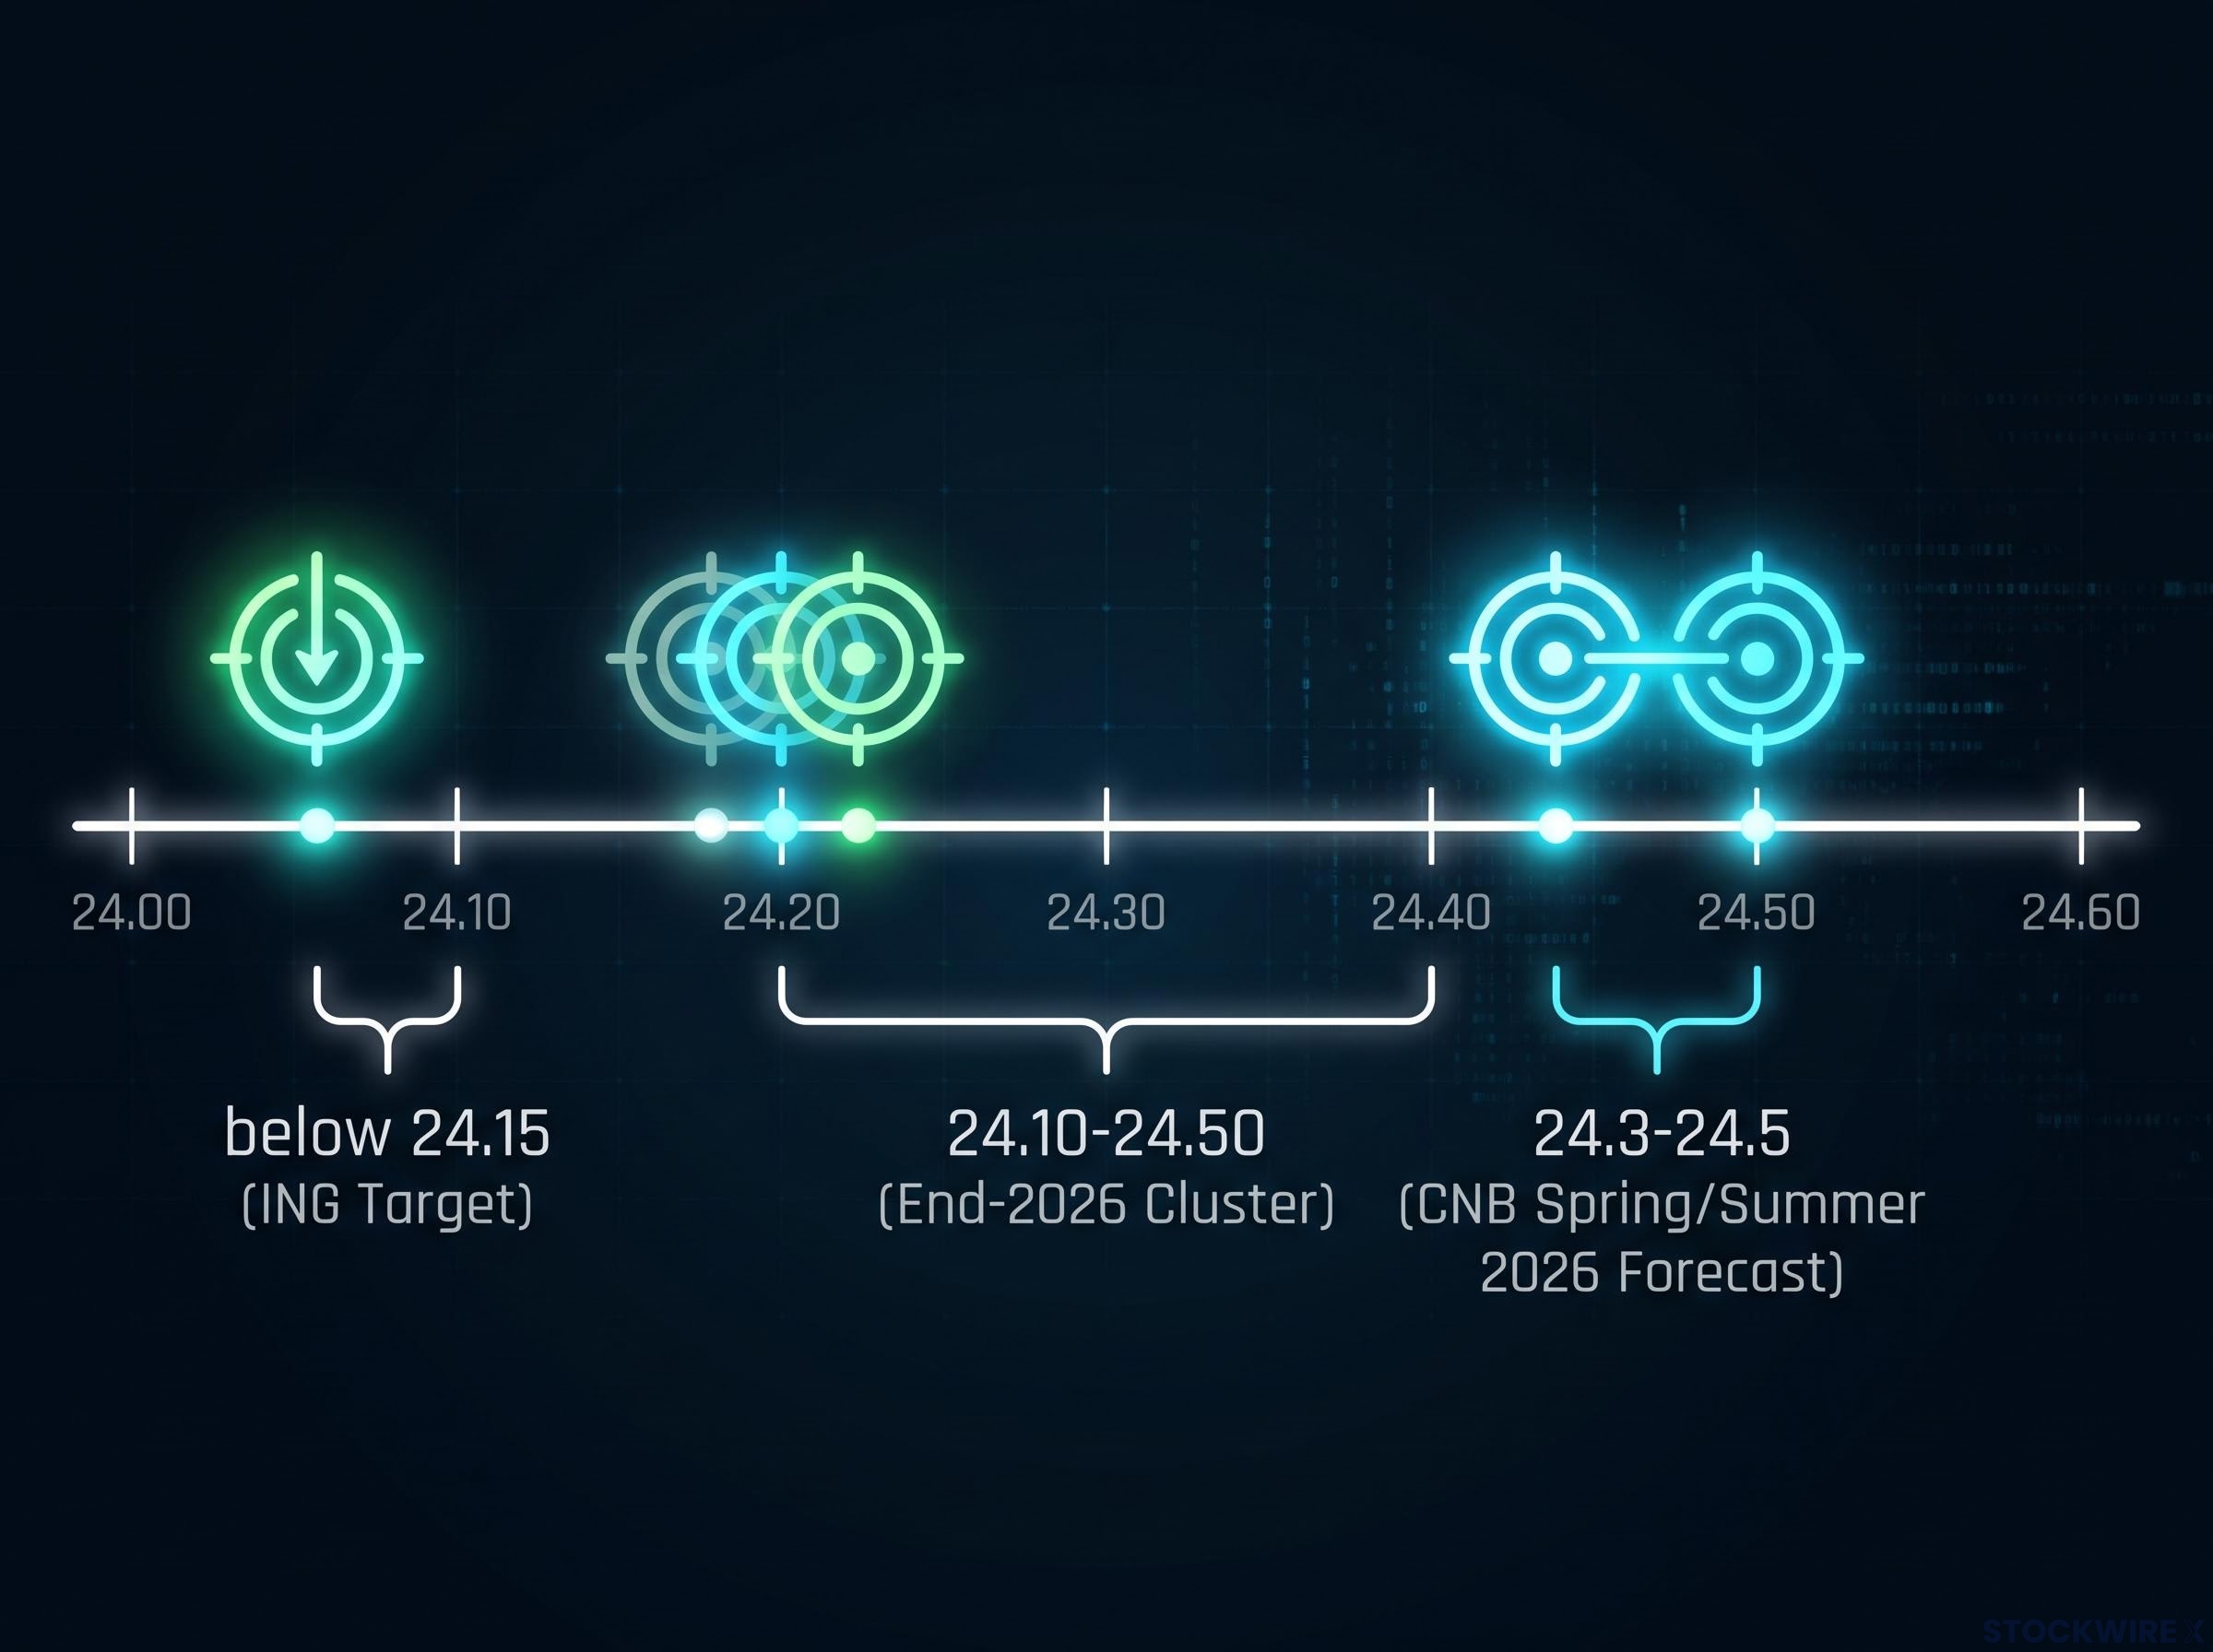
That range is explicitly conditional. It assumes the CNB delivers at least some of what is priced, not all of it. The CNB’s own Spring and Summer 2026 forecasts point to a broadly stable koruna around 24.3-24.5 with slight weakening later, which reads far more like a hawkish pause than a full hiking cycle.
In other words, the base case for koruna strength does not require the market to be right about 125bp. It requires the CNB to be hawkish enough to keep the differential attractive. Those are two different bars, and the gap between them is where the risk lives.
Why the analysts calling this excessive may have a point
The sceptical view is not a contrarian punt. It is the logical read of the CNB’s own communications.
Start with the meeting itself. ING flagged that today’s outcome is likely to look “dovish relative to market pricing” regardless of what the CNB actually decides, simply because a hold validates none of the 125bp of future hikes the curve implies. A pause that changes nothing still disappoints a market positioned for aggression.
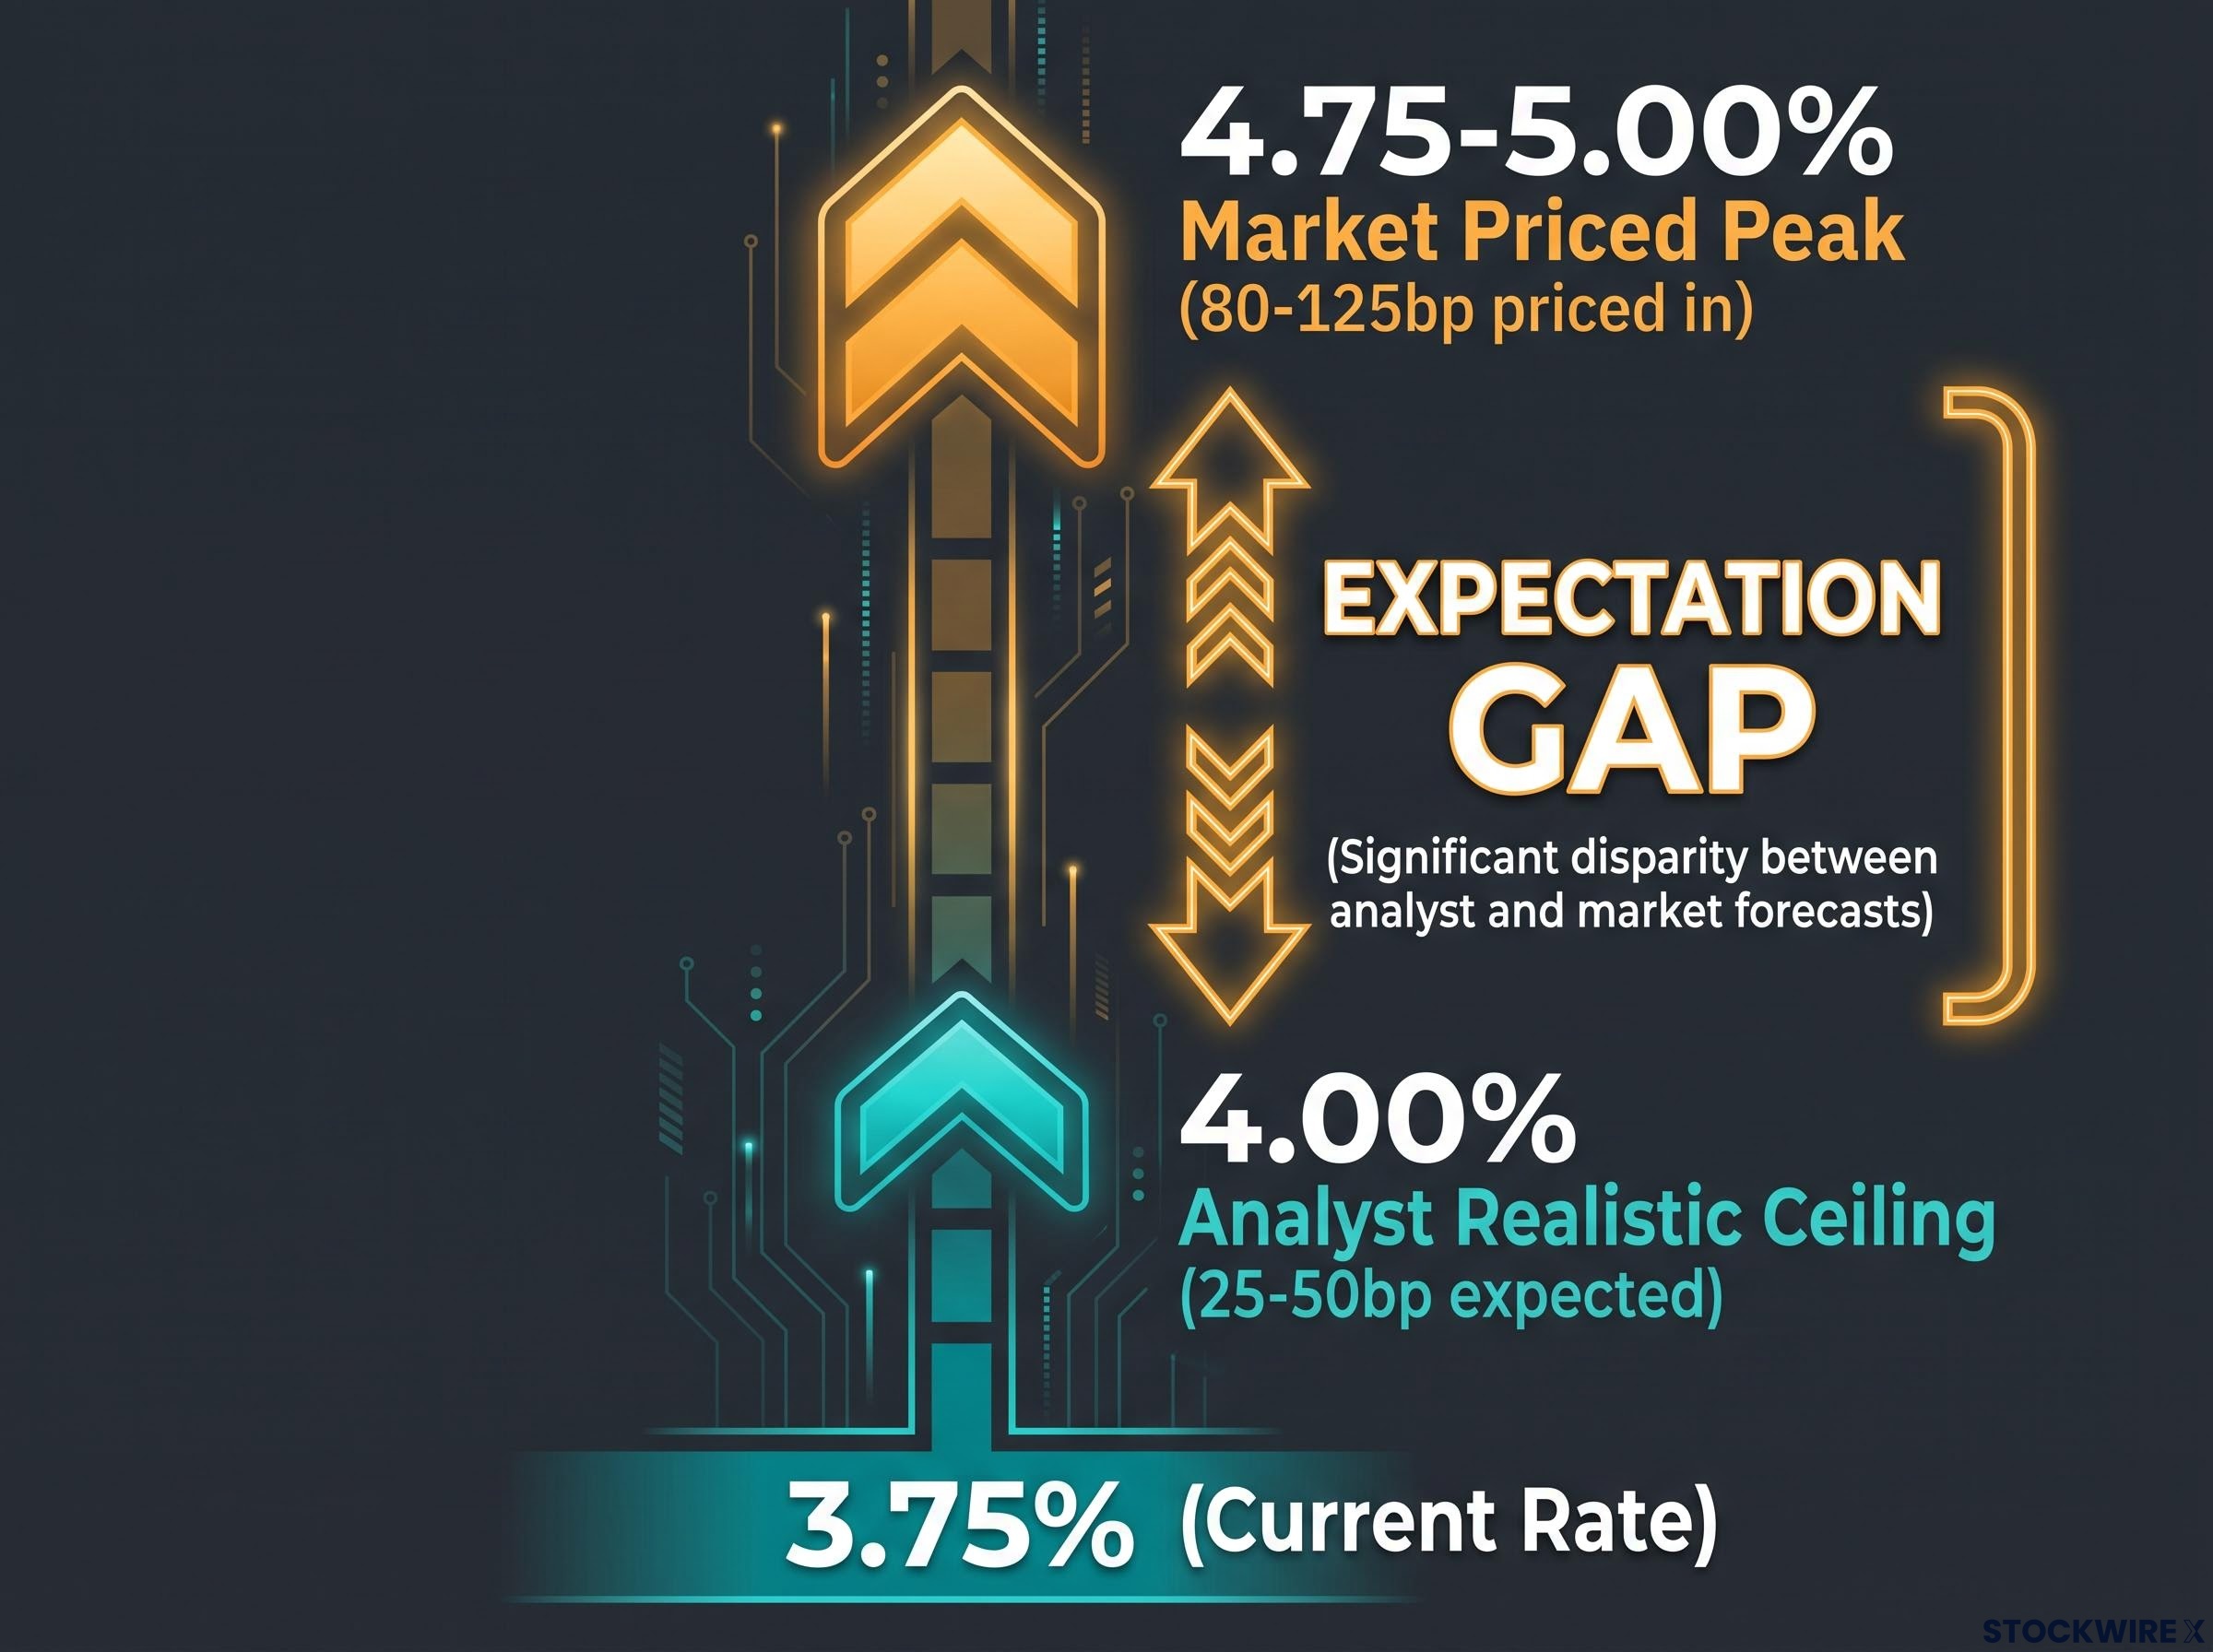
Then there is the ceiling. Analyst Metodi Tzanov, writing on 6 August 2026, doubted the CNB board would push the policy rate above 4%. Hold that against current pricing and the maths gets uncomfortable: 125bp of hikes from 3.75% implies a peak near 4.75-5.00%, well beyond where the CNB’s own reaction function appears to point. Commerzbank’s Pfister expects a hawkish pause and says expectations have “gone quite far.”
The downside is not hypothetical either. The koruna has repriced sharply before, twice in recent memory:
- Early 2025 dovish repricing: ING economists documented the koruna falling approximately 2.1% versus the euro between January and March as markets shifted to more accommodative expectations.
- January 2026 CPI surprise: a softer inflation print sent the koruna down roughly 0.5% in its biggest one-day drop since April, with forwards shifting from near-zero easing to roughly 12bp of cuts priced, per Commerzbank.
- February 2026 dovish note: ING recorded CZK rates testing local lows and pressuring CEE currencies, a slower-burn erosion of carry rather than a violent break.
The differential warning ING sees “scope for narrower rate differentials and moderate CEE currency weakness, especially in EUR/CZK and EUR/PLN.”
Put it together and the picture sharpens. If the CNB’s realistic ceiling is 4%, then a market pricing hikes toward 5% is not cautious, it is crowded. And a crowded hawkish bet in a currency backed by a relatively small market unwinds fast when the catalyst lands. If you hold long CZK or CNB-rate-linked positions, that downside has already been measured twice.
Three external variables that could override the entire rate story
Domestic pricing is only half the equation. The koruna outlook depends just as much on whether the global backdrop sits still long enough for the rate story to play out, and right now it is not sitting still.
Analysts consistently flag three external forces capable of overriding domestic rate support:
- US dollar and yield strength: ING pointed to US 10-year yields near 5% and a surging dollar hitting CEE currencies as of 17 September 2026, expecting EUR/CZK above 24.35 following the hold if these conditions persist.
- Energy prices and Middle East conflict: the CNB Bank Board lists geopolitical risk premiums and oil and gas supply disruptions among its key external risks. Finimize reported CEE currencies including the koruna sinking on strikes against Iran and LNG disruption on 3 March 2026, and again in July on renewed Strait of Hormuz tensions.
- Eurozone growth and risk sentiment: the CNB has referenced weaker growth outlooks for energy-importing European economies, and any European risk-off episode can drag regional FX lower regardless of local policy.
Energy price shocks do not merely push headline CPI higher; they also compress the room central banks have to act, because cost-push inflation from oil and gas supply disruption is not a problem that tighter domestic rates can solve, a constraint that bears directly on how credibly the CNB can sustain restrictiveness if another supply episode lands.
The energy episodes are the instructive ones. They show the koruna can fall even when rate expectations are hawkish, because inflation fear and growth fear pull in the same direction, per ING Think’s analysis of how energy shocks postpone rate cuts while pressuring currencies.
Here is where it leaves you. The CNB’s hawkish stance is a necessary condition for koruna stability, not a sufficient one. All three external variables can produce asymmetric outcomes where CZK slides even as the bank holds or hikes, because the carry trade unwinds faster than the policy rate climbs. For a late-2026 CEE FX view, this checklist matters more than the press conference transcript.
The CNB’s credibility problem and what it means for late-2026 CZK positioning
Two things are true at once, and holding both is the whole game.
The CNB’s structural hawkishness relative to the NBP and MNB is real and durable. But the distance between what the market has priced, 80-125bp, and the realistic ceiling analysts assess, roughly 25-50bp above the current 3.75%, is the single biggest risk facing koruna longs into late 2026. Market pricing implies a peak near 4.75-5.00%; Tzanov and Commerzbank point to 4.00% or marginally above.
The base case follows from that gap. Expect a hawkish pause today, one or possibly two hikes over the coming six months, and gradual repricing of the most aggressive expectations. That is consistent with EUR/CZK holding in a 24.20-24.50 range rather than a sustained break below 24.15.
The range to anchor on Base case EUR/CZK: 24.20-24.50. Komerční banka sees 24.10 at end-2026; CBA Monitor around 24.20; ING’s post-hold read sits above 24.35.
The signal to watch is not a rate change. It is language. Here are the three scenarios and their triggers:
- Hawkish surprise: the CNB signals a peak above 4.25%, validating current pricing and supporting EUR/CZK below 24.15.
- Base case: a hawkish pause with only 25-50bp of further tightening signalled, keeping the cross in range.
- Dovish surprise: any hint that the peak sits at or below 4.00%, the trigger for repricing lower and koruna weakness.
The takeaway for anyone holding koruna exposure is uncomfortable but clear. The support is genuine, and Commerzbank still expects CZK to outperform the Polish zloty. But the cushion is thinner than market pricing implies, and the bull case needs the CNB to say more than expected. The bear case needs only that it says less, which, on the evidence assembled here, is the more likely outcome.
For investors building a broader European FX positioning framework alongside EUR/CZK, our deep-dive into the EUR/CHF two-speed cycle examines how crowded rate-hike expectations reprice when a central bank signals a lower peak than markets assumed, a pattern directly relevant to the CNB credibility question.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments.