Central banks are supposed to have an easy option when the economy wobbles: stop tightening and wait. The trouble in September 2026 is that sitting still has become just as risky as moving.
With Brent crude above $108 per barrel and the 10-year US Treasury yield brushing 5%, doing nothing does not freeze financial conditions in place. The bond market keeps tightening on its own, and energy costs keep feeding inflation regardless of what the Federal Reserve announces.
That is the trap facing policymakers ahead of today’s Federal Open Market Committee (FOMC) decision, due at 2:00 p.m. ET on Wednesday, 16 September 2026. Push rates higher to fight energy-driven inflation, and you risk breaking rate-sensitive corners of the economy like housing and government debt servicing. Hold steady, and you risk letting price pressures become entrenched.
This is the Fed policy dilemma in its sharpest form, and it lands directly on your finances. Here is the framework for understanding how these colliding forces set your borrowing costs, shape your investment risks, and drive the price of everyday essentials, whatever the Committee decides this afternoon.
How yields, energy, and policy collide
To make sense of the current standoff, you need to understand three levers that do not always move together.
The first is the federal funds rate, the short-term interest rate the Fed sets directly. It currently sits in a target range of 3.50-3.75%. The second is long-term bond yields, like the 10-year Treasury, which the market sets through buying and selling, not the Fed. The third is commodity-driven supply shocks, sudden jumps in prices for things like oil that come from disruptions rather than booming demand.
Here is the point most people miss: the Fed controls the first lever, but only influences the second, and has almost no power over the third.
That is where the term premium matters. A term premium is the extra compensation bond investors demand for locking their money into long-dated debt. When government deficits are large and the pile of debt to be repaid keeps growing, investors get nervous about being repaid in full value and push that premium higher. The result is higher long-term yields even when the Fed has not touched its policy rate.
Term premium dynamics have become the dominant force reshaping long-duration debt pricing in 2026, with the ACM model estimating the US 10-year term premium at 70-80 basis points, a structural swing of roughly 220 basis points from its negative readings in early 2020.
You saw this happen in reverse recently. According to a VoxEU analysis of the period between September 2024 and early 2025, the Fed cut its policy rate by 100 basis points while the 10-year yield rose by roughly 100 basis points. Short rates went down; long rates went up. The bond market tightened your mortgage and corporate borrowing costs even as the Fed was easing.
That is the crucial takeaway for your portfolio. The Fed does not control all interest rates. The bond market can independently tighten the financial conditions you actually pay, even on a day the Committee sits on its hands.
This is why the current environment feels like a zero-sum game. The Fed is caught between three competing priorities, and pulling harder on one tends to strain the others:
- Inflation control: raising rates to cool energy-fed price pressures.
- Economic growth: avoiding a squeeze that tips housing and credit into recession.
- Financial stability: preventing stress in banks, real estate, and government debt markets.
Solving the inflation problem risks worsening the stability problem. That tension is the whole story of today’s decision.
When big ASX news breaks, our subscribers know first
Decoding the 5% yield and triple-digit oil
Now feel the weight of the pressures bearing down at once.
Borrowing costs have surged across the entire yield curve. The 10-year US Treasury yield hit an intraday high of 5.041% on 15 September 2026, its highest level since 2007, before settling around 5.00-5.01%, according to Reuters and TradingEconomics data. The 2-year yield climbed to roughly 4.59-4.66% depending on the reporting day, while the 30-year sits above 5.38%.
The IMF’s Global Markets Monitor described the early-September move as a “bear flattening,” where short-term yields rose faster than long-term ones. The signal underneath is not calm. It reflects investors bracing for both more inflation and more debt issuance at the same time.
Then there is energy. Brent crude traded at $108.49 per barrel on 15 September 2026, up 2.66% on the day, as a Saudi export halt and Libyan outages stoked supply fears, per Reuters. US retail gasoline averaged $4.319 per gallon nationwide on 14 September 2026, according to an IndexBox summary of EIA data.
Notice what is driving this. These are supply shocks tied to Middle East disruptions and strikes on Saudi infrastructure, not American consumers suddenly buying more fuel.
Supply-shock inflation transmission through logistics, airfares, and imported goods means the Dallas Fed now estimates the 2026 conflict has raised US headline PCE by approximately 0.6 percentage points on a Q4/Q4 basis, with the central bank scenario range running as high as 1.47 percentage points depending on Hormuz disruption duration.
That distinction is everything for policy. Rate hikes are designed to cool demand, but they do not produce a single extra barrel of oil. When a global supply shock drives up your cost of living, the Fed’s traditional tools are largely powerless to lower prices at the pump without engineering a recession severe enough to crush demand entirely.
IMF research on central bank supply shock dilemmas shows that when commodity-driven price pressures risk de-anchoring inflation expectations, tightening policy can impose severe output costs without addressing the underlying supply constraint driving prices higher.
Here is where the red lights are flashing.
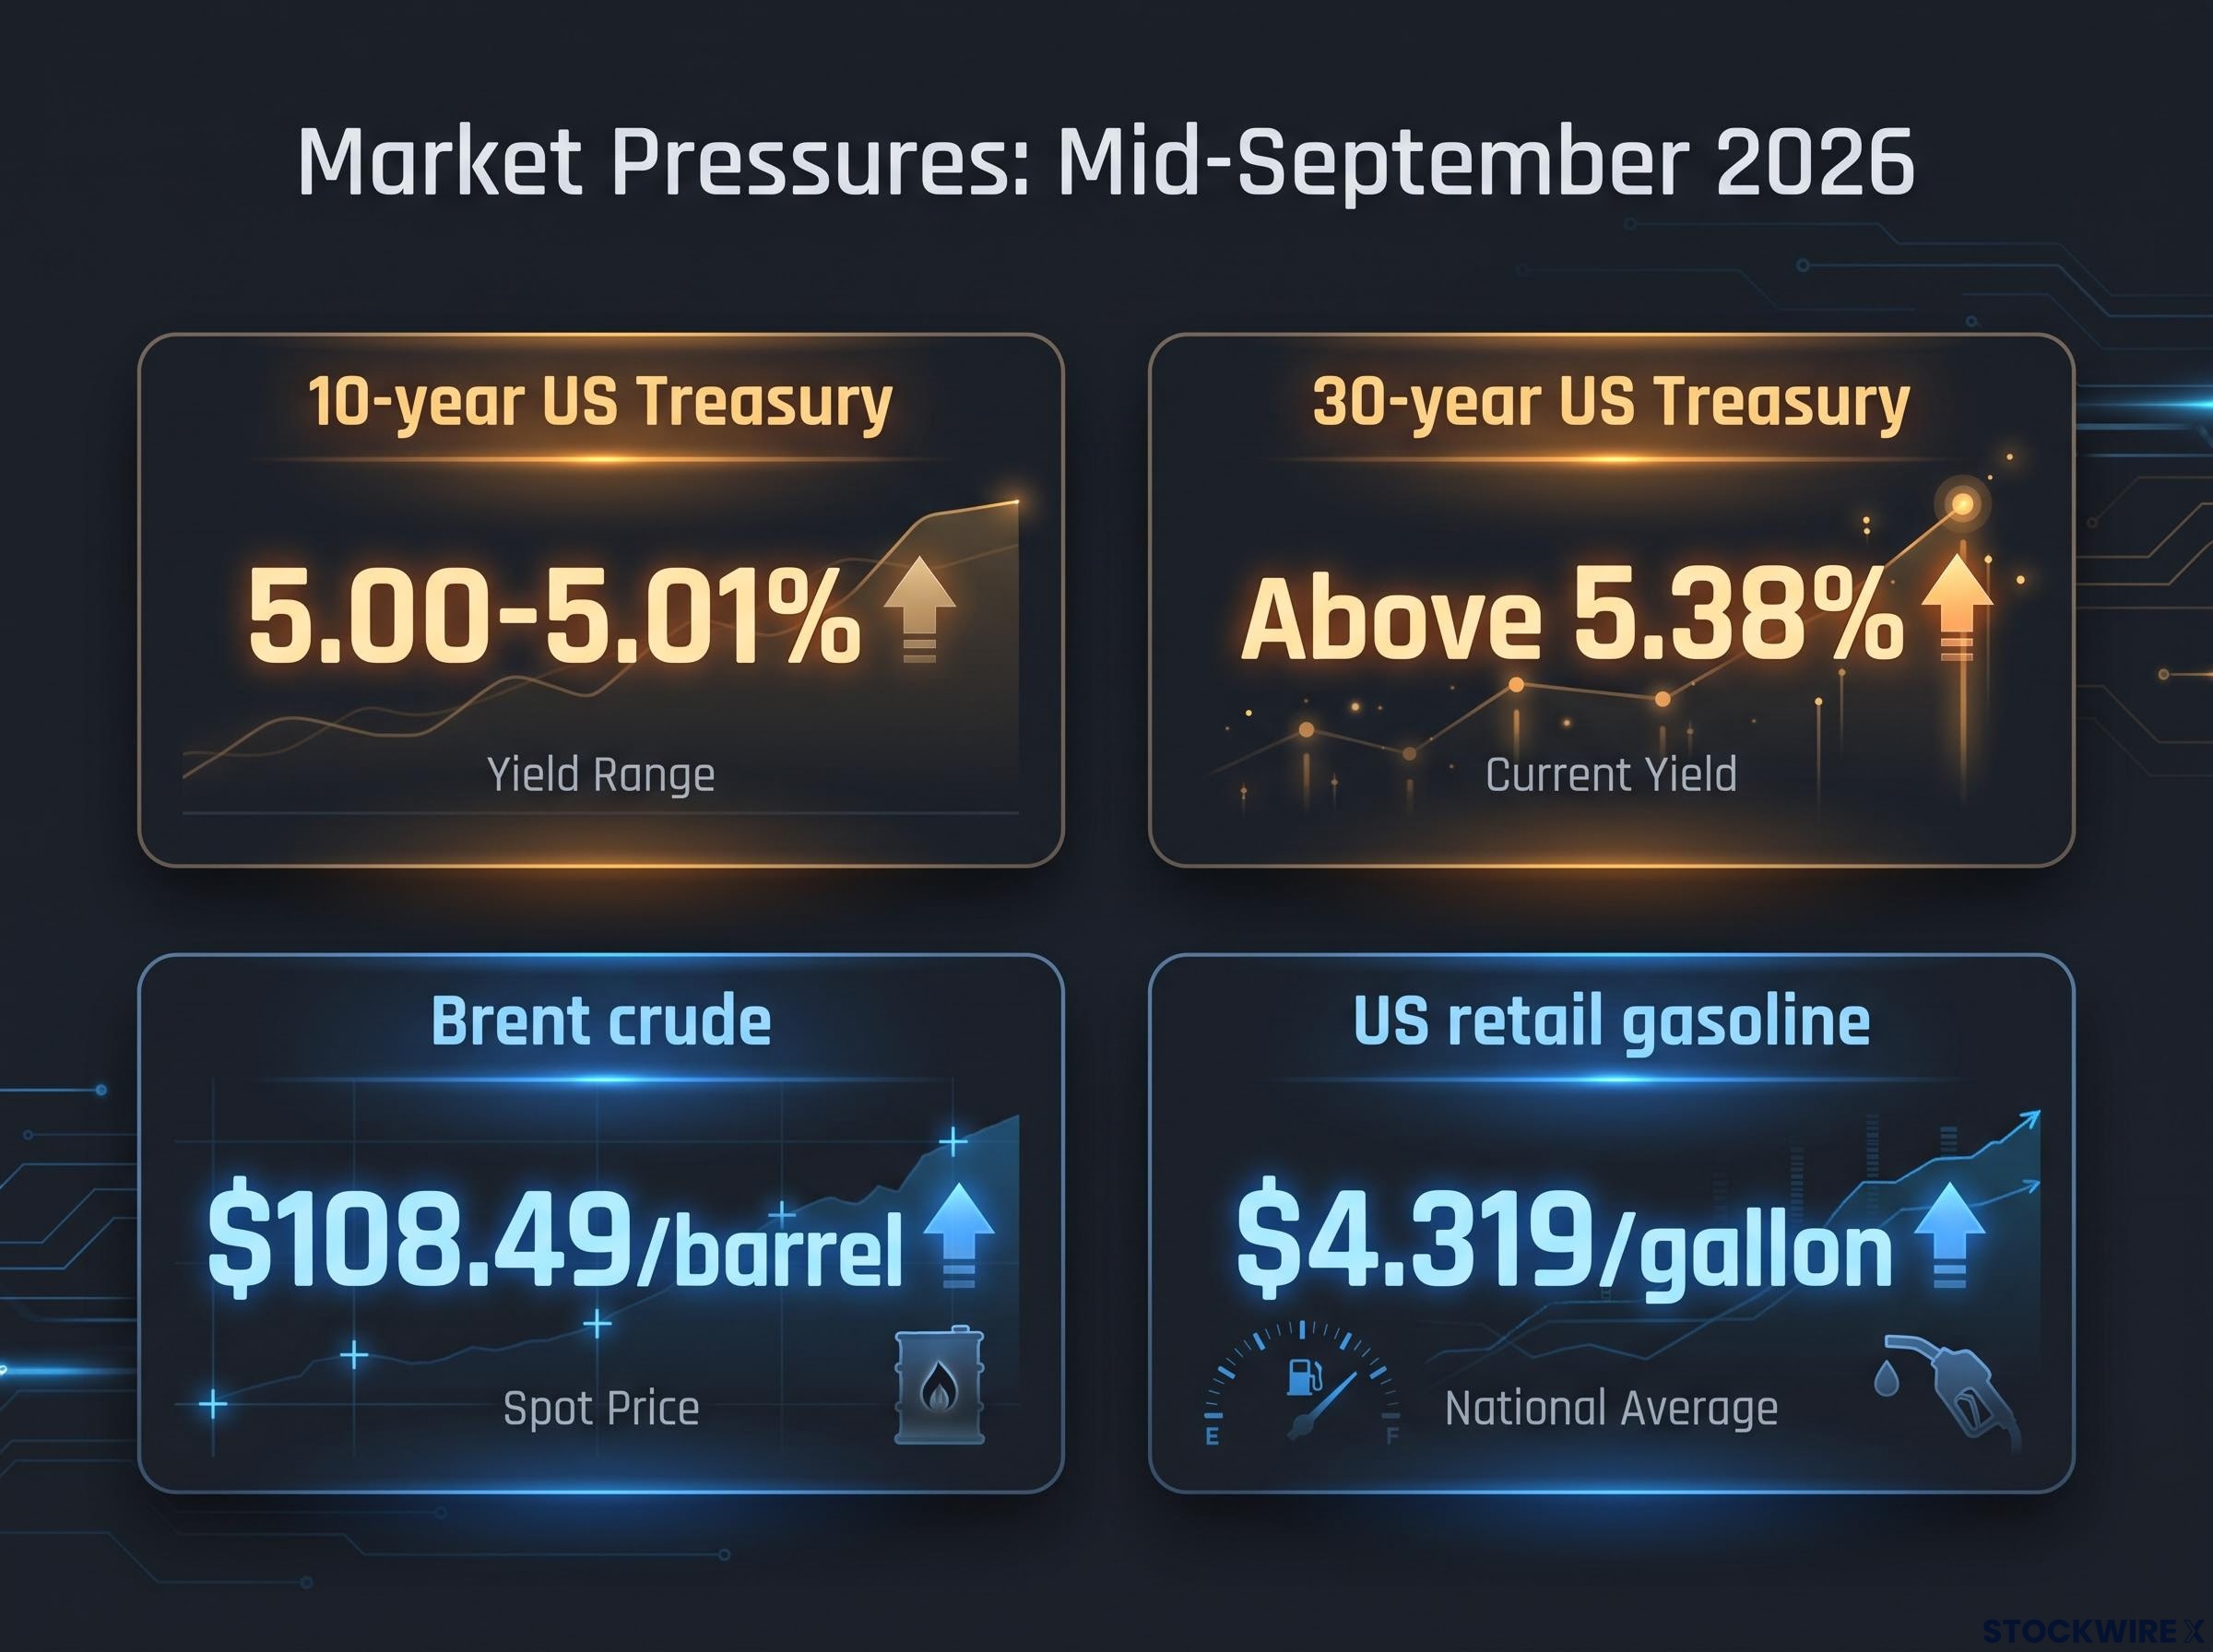
| Asset Class | Mid-September 2026 Level | Primary Market Driver |
|---|---|---|
| 10-year US Treasury | 5.00-5.01% | Inflation and deficit concerns raising term premiums |
| 30-year US Treasury | Above 5.38% | Long-run debt-sustainability fears |
| Brent crude | $108.49/barrel | Geopolitical supply disruptions |
| US retail gasoline | $4.319/gallon | Pass-through from elevated crude prices |
Term premiums versus short-rate expectations
Why yields are rising matters as much as the fact that they are.
Federal Reserve analysis of the 2023 Treasury Tantrum stresses a key distinction: long-term yields can climb because investors expect the Fed to hike more, or because they fear the government’s growing debt is unsustainable and demand a higher term premium to hold it.
Federal Reserve staff analysis of the 2023 “Treasury Tantrum” stresses a key distinction. Long-term yields can climb because investors expect the Fed to hike more, or because they fear the government’s growing debt is unsustainable and demand a higher term premium to hold it.
The read matters enormously. If yields are rising on debt fears rather than rate expectations, aggressive Fed hikes could over-tighten an economy the market is already squeezing. Misread that decomposition, and policymakers risk either needless recession or renewed inflation.
The collateral damage in housing and government debt
Move from the abstract numbers to where the pain actually lands, and two pressure points stand out.
The first is your ability to buy or refinance a home. When mortgage rates stay elevated, refinancing activity dries up and affordability collapses. History shows how fast this bites: in mid-2008, Reuters coverage documented how higher 10-year yields pushed mortgage rates above 6.5%, choking off mortgage applications and refinancing.
The commercial and residential real estate squeeze
Properties bought at rock-bottom rates now face brutal repricing.
A GlobeSt analysis from 21 August 2026 flagged that persistently high policy rates and Treasury yields are keeping long-term mortgage rates expensive and intensifying stress in commercial real estate debt markets. Buildings financed when long-term rates were near zero in 2020 now have to refinance at mid-single-digit yields.
Housing equity damage from sustained Treasury yields above 5% has been concrete and quantifiable: analysts have applied roughly 18% cuts to 2026 EPS estimates across homebuilder coverage, and Lennar has broken neckline support near $100 to trade around $80, confirming the transmission from yields to corporate earnings is already underway.
That strain does not stay contained. It flows onto the balance sheets of regional banks holding that real estate debt, which is exactly how a rate problem becomes a credit problem.
The second pressure point is the government’s own debt. The Committee for a Responsible Federal Budget (CRFB) estimates that sustained Treasury yields in the 4.5-5% range would add trillions of dollars to federal interest costs over coming years, crowding out spending on everything else.
“Higher Treasury yields, sustained in the 4.5 to 5 percent range, would add trillions to federal interest costs and materially worsen the government’s debt-service burden,” the CRFB has warned, noting long-term yields have already climbed from around 0.9% at the end of 2020 to well above 4% by 2024.
You should not read a rising national debt burden as merely a government problem. It is a direct threat to your future tax rates and to how much credit is available when you go to finance your next home.
This is the heart of the split. Hawks argue the Fed must prioritise inflation control now to avoid worse pain later. Doves counter that hiking into an already-fragile debt and housing environment risks triggering a debt spiral that no rate cut can easily reverse.
The disconnect between market pricing and economist forecasts
Here is what makes today genuinely combustible: the market and the economists flatly disagree.
Traders are positioned for action. According to MUFG analyst Lloyd Chan, cited by FXStreet, markets were pricing in greater than 90% odds of a 25 basis point hike at this meeting, though earlier readings from the IMF and CME FedWatch data put the probability closer to 52-70% depending on the data vintage. Either way, a large share of the market expects a move.
The economists see it differently. A Reuters poll from 9 September 2026 found roughly 70% of economists (65 of 93) expect the funds rate to hold steady at 3.50-3.75% at this meeting. TD Economics projected the target near 3.75% in every quarter of 2026, reinforcing the case for stability through year-end.
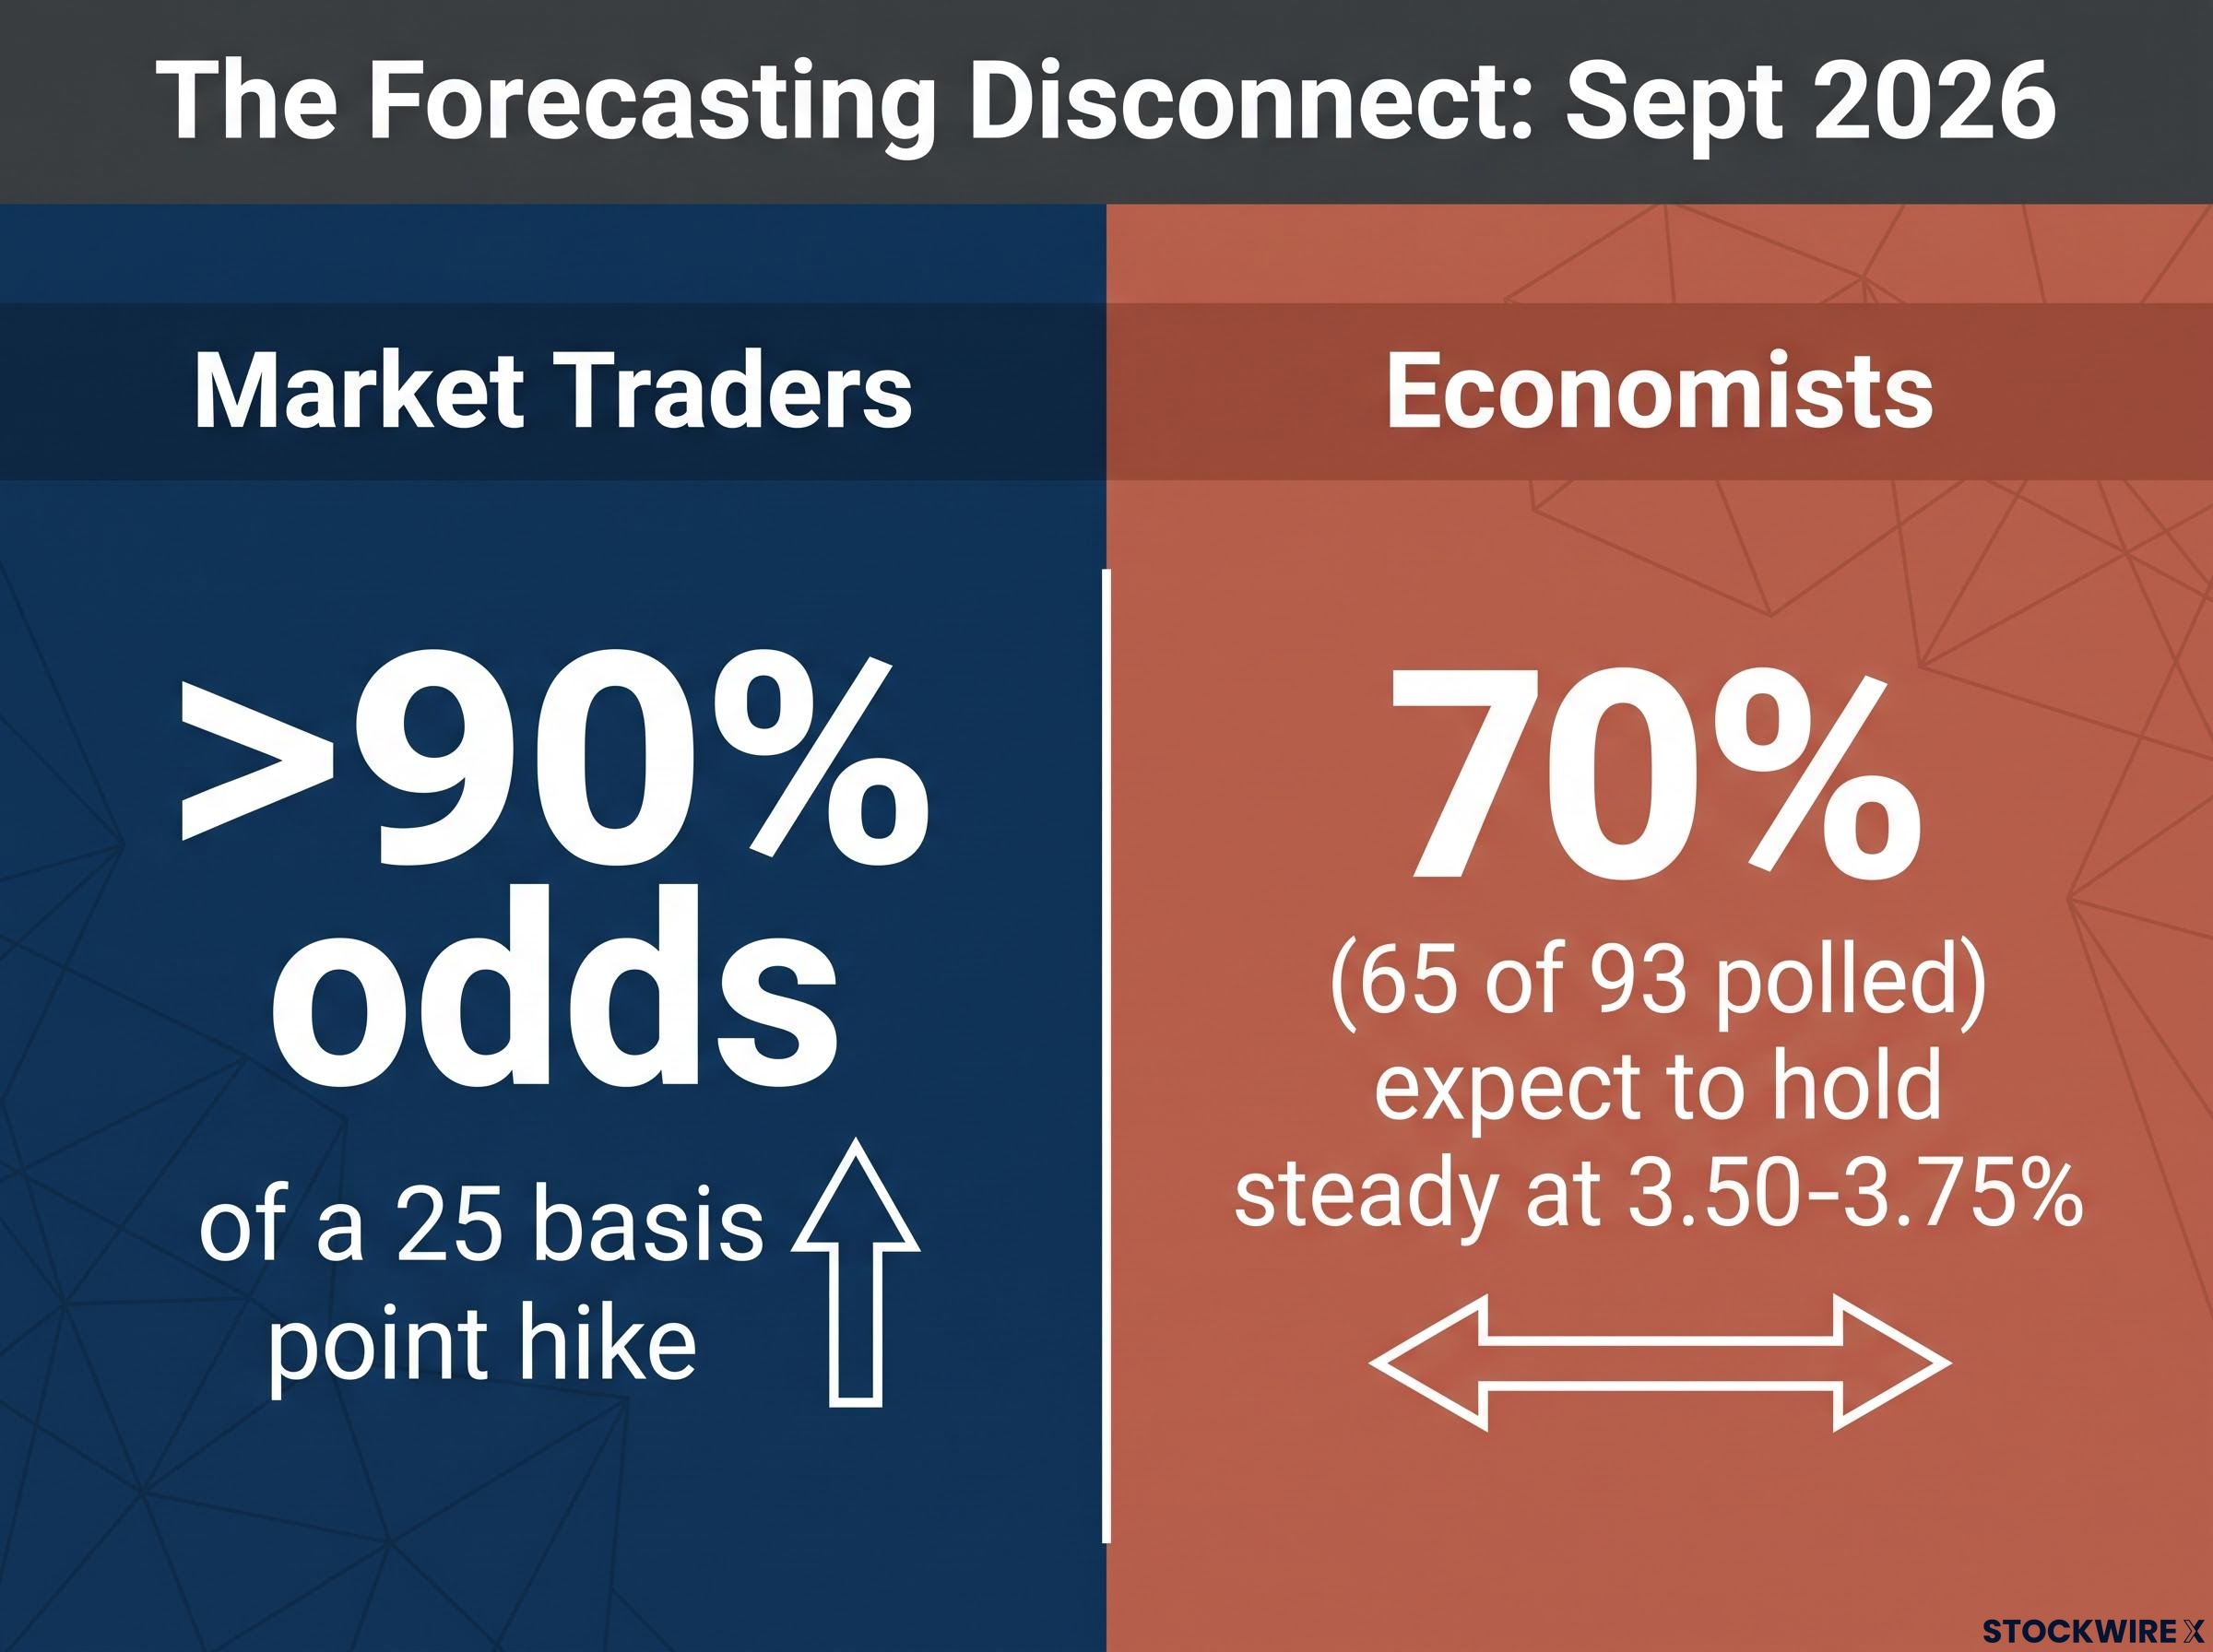
That gap is not academic. It means one large group of market participants is about to be wrong, and forced to reprice their bets fast.
For your portfolio, the maths is unforgiving. This forecasting divide means you should expect volatility regardless of what is announced this afternoon, because a surprise is effectively guaranteed for a meaningful chunk of the market. The only question is which side gets caught out.
Policymakers are trying to steer clear of three cautionary precedents, all of which end badly:
- 1970s stagflation: letting energy-driven inflation become entrenched, which eventually required brutal interest rates and a deep recession to reverse.
- The 1994 bond market rout: a surprise tightening cycle that inflicted sharp losses on long-duration bonds and destabilised leveraged investors.
- The 2023 Treasury Tantrum: a term-premium-driven yield spike that risks being misread as an inflation-expectations problem.
Whichever way the Committee moves, it is trying not to repeat any of those. Today’s call sets the tone for market direction through the end of 2026.
Positioning your portfolio for the upcoming rate path
Strip it all back and the conflict is simple to state and impossible to resolve cleanly. 5% Treasury yields argue for caution on tightening into a fragile debt and housing system, while $100-plus oil argues for leaning harder against inflation. The two forces demand opposite responses, and the Fed can only choose one direction.
The more useful move for you is to stop trying to predict the exact decision and start preparing for the environment it creates: a prolonged stretch of elevated volatility and restrictive financial conditions.
That means stress-testing your own debt against higher-for-longer rates, and staying defensive in the sectors most exposed to yield swings, particularly real estate and other rate-sensitive holdings. Assume conditions stay tight rather than betting on imminent relief.
Investors wanting to size the risk to their equity holdings from further real yield increases will find our deep-dive into the equity risk premium, which explains how the compression to 2.1% compares with the eve of the 2007 crisis and what historical mean-reversion episodes looked like for stock prices.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results, and these forward-looking scenarios are speculative and subject to change based on market developments and policy decisions. Whatever the Committee announces this afternoon, the collision of high yields, high energy costs, and high debt is not resolving quickly.