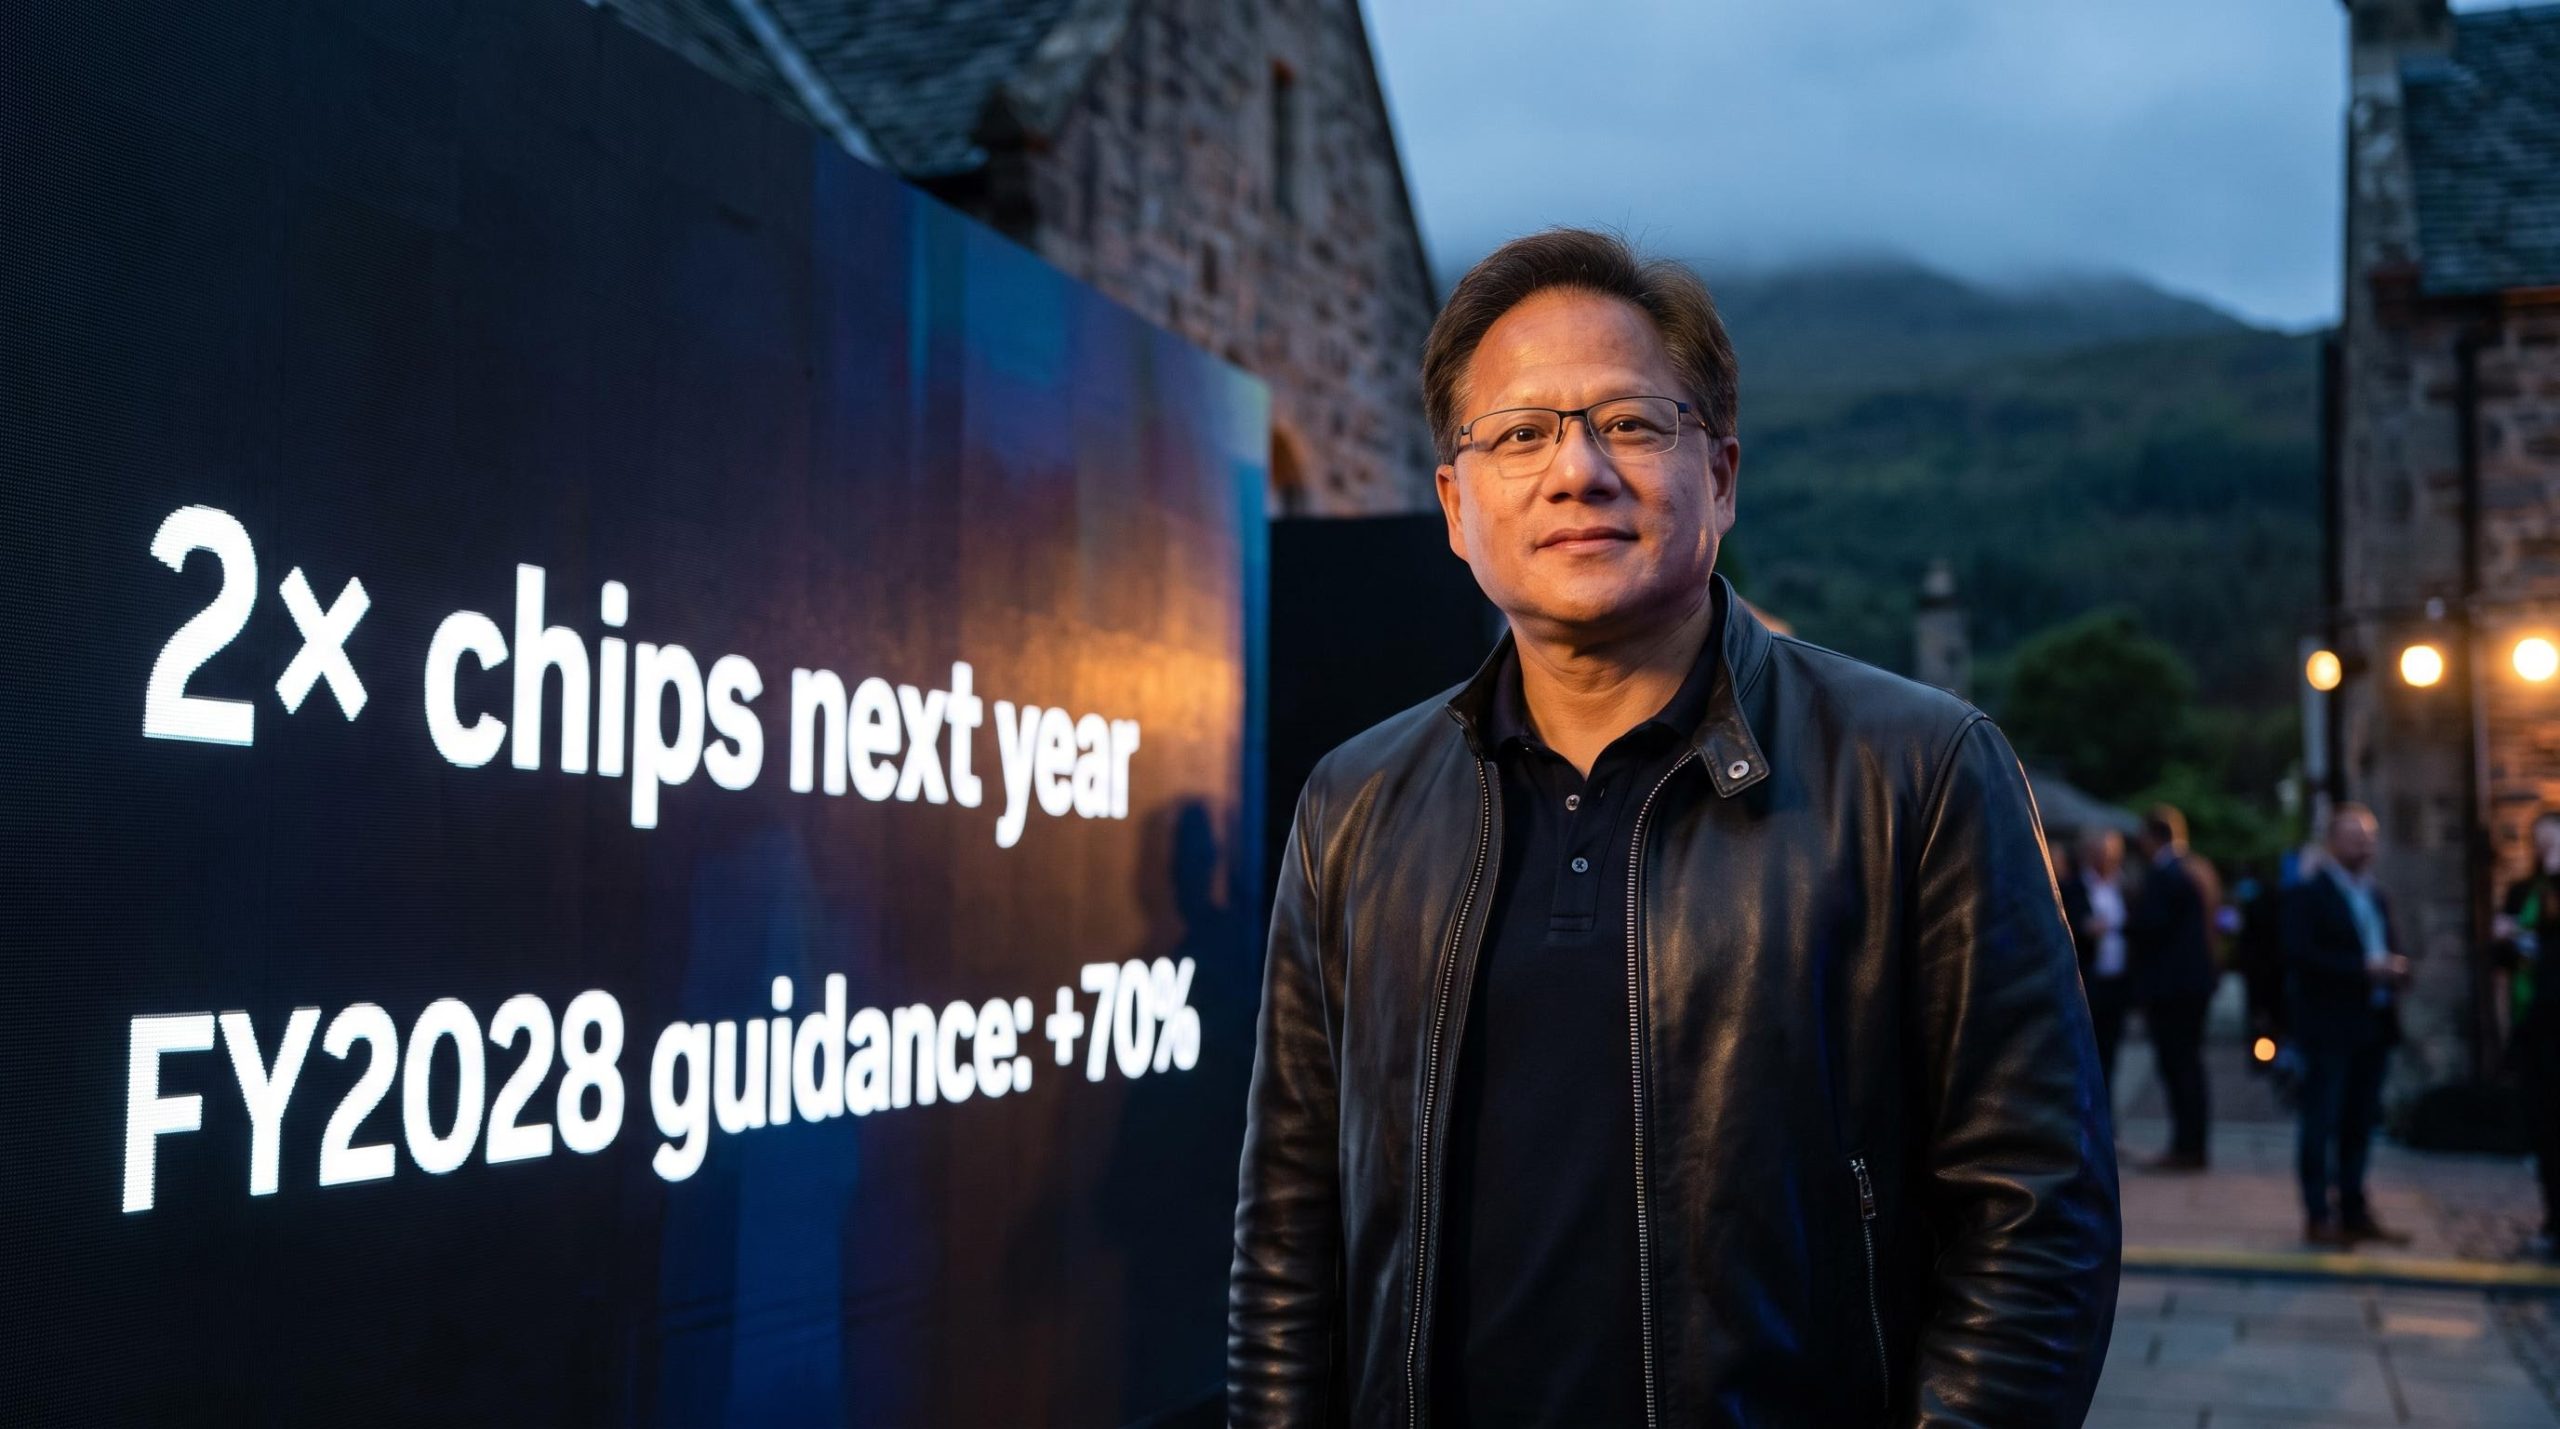
Nvidia CEO Jensen Huang told reporters in Scotland today that he expects to sell twice as many chips next year as this year, a projection he delivered at an AI summit attended by King Charles III. Nvidia’s stock gained roughly 2.54% on the day.
The remark is not a vague aspiration. It maps onto Nvidia’s formal fiscal 2028 revenue guidance of approximately 70% growth, a figure that arrived roughly 26 percentage points above what analysts had been modelling before the company issued its first year-ahead revenue outlook in August 2026.
That gap between what the Street expected and what management is now guiding is the number that demands attention. For anyone tracking where AI infrastructure spending is heading, this is the clearest public signal available about 2027.
What follows here unpacks what Huang actually said, where the demand is coming from, who is questioning the thesis, and what the forecast means for you if you hold Nvidia directly or carry AI infrastructure exposure through anything else.
What Huang actually said, and what the numbers behind it look like
Huang was direct with reporters at the Scotland summit: “We expect to sell twice as many chips next year as we do this year.” He attributed the projected volume increase to AI demand spreading across industries and national economies, with nearly every country Nvidia operates in signalling intent to invest.
One clarification matters immediately. The projection refers to chip units across Nvidia’s entire portfolio, not data-centre GPUs alone. The company does not publicly disclose aggregate chip sales figures, so the doubling claim is a directional statement about total volume.
That portfolio spans a wide range of products:
- Data-centre GPUs (the Blackwell and Rubin lines)
- CPUs
- AI server switches
- Optical networking chips
- Laptop chips
- Jetson platforms for robots and cars
- Chips for Nintendo’s Switch 2
The volume projection sits inside a formal financial framework. During its fiscal Q2 FY2027 earnings disclosures in August 2026, Nvidia guided to roughly 70% revenue growth for the fiscal year ending January 2028, its first formal year-ahead outlook. CNBC calculated that, on a consensus fiscal 2027 base of about US$396 billion, that growth rate implies fiscal 2028 revenue near US$673 billion.
Huang, at the Scotland AI summit “We expect to sell twice as many chips next year as we do this year.”
The scale of the surprise is where the story lives. Before the guidance, analysts had modelled fiscal 2028 revenue of roughly US$570 billion, implying about 44% growth, according to Fortune, LSEG, and Bloomberg-sourced data. CFO Colette Kress explicitly contrasted the company’s 70% figure against that 44% consensus.
| Estimate source | Implied FY2028 growth | Implied revenue |
|---|---|---|
| Pre-guidance analyst consensus | ~44% | ~US$570 billion |
| Post-guidance analyst consensus | ~63% | No updated figure disclosed |
| Nvidia management guidance | ~70% | ~US$673 billion |
Even after the guidance, Yahoo Finance data showed the Street averaging around 63% growth, still short of the 70% target. That 26-percentage-point gap between Nvidia’s guidance and the pre-announcement consensus is not a rounding difference. It tells you the company is seeing near-term demand materialise at a scale the market had not yet fully priced.
When big ASX news breaks, our subscribers know first
The demand machinery: who is buying, and how much
Huang’s forecast is not a top-down assertion. It rests on commitments already visible in the order book, and the machinery behind it comes from two structurally different sources.
Hyperscaler capex commitments
The primary driver is hyperscaler capital expenditure. Combined 2026 capex guidance from Amazon, Alphabet, Meta, and Microsoft reaches approximately US$725 billion, up 77% year-on-year from about US$410 billion in 2025, according to Matrixport and ValueAddVC. Goldman Sachs projects global hyperscaler capex will exceed US$760 billion in 2026, a figure that works out to roughly US$2 billion per day.
Hyperscaler capex commitments from Amazon, Microsoft, Alphabet, and Meta reached approximately US$130 billion in Q1 2026 alone, with full-year 2026 combined guidance touching US$725 billion and a US$1 trillion annual run rate already projected for 2027.
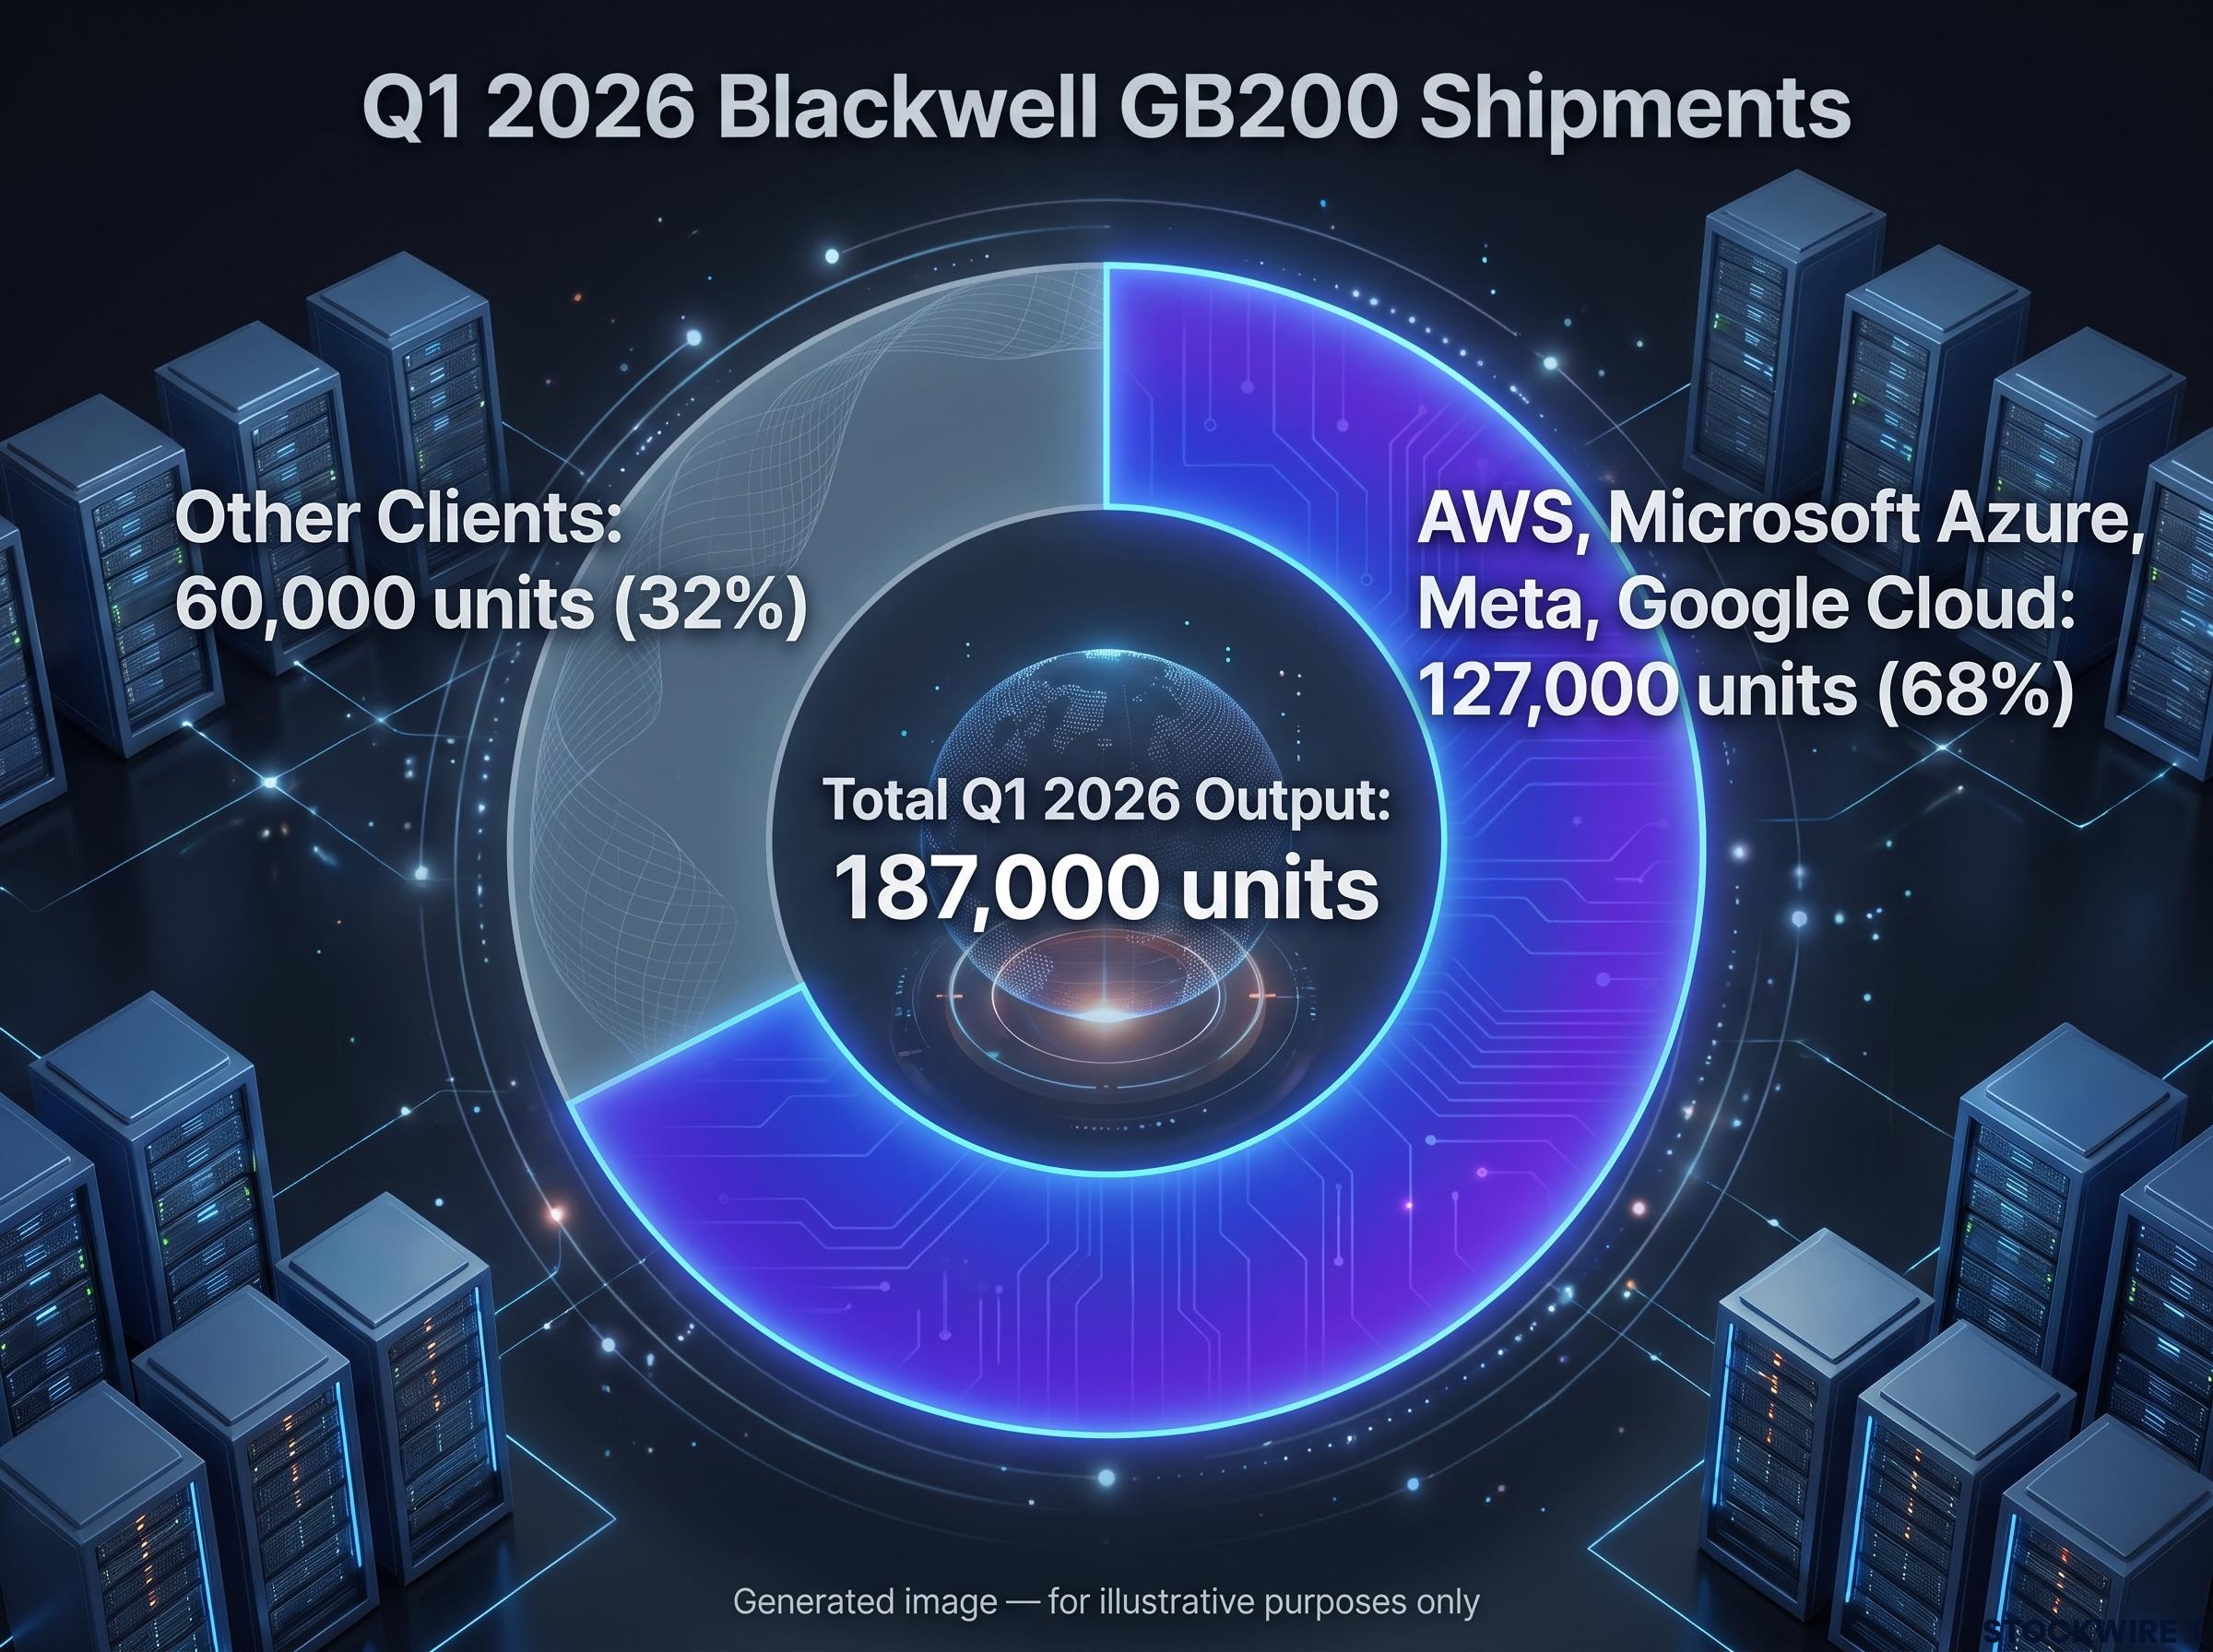
That capital flows directly into GPU procurement. Investigative reporting from The Editorial, based on supplier audit records, found Nvidia shipped 187,000 Blackwell GB200 units in Q1 2026. Four buyers, AWS, Microsoft Azure, Meta, and Google Cloud, took 127,000 of them, or 68% of the quarter’s output.
The longer arc is just as concrete. Over roughly four quarters through late 2025, Nvidia shipped around 6 million Blackwell GPUs, a figure Huang disclosed the preceding autumn and CNBC confirmed in October 2025.
That 68% concentration tells you something specific about the risk profile. Demand at this scale is not diffuse or speculative; it is driven by a small number of institutions making very large, committed purchases. That reduces short-term demand-volatility risk while raising customer-concentration risk at the same time.
Sovereign AI programs adding a second demand layer
The second demand pool operates independently of commercial return-on-investment cycles. Sovereign AI programs, where governments fund national compute capacity directly, are adding volume that does not depend on a hyperscaler’s quarterly earnings maths.
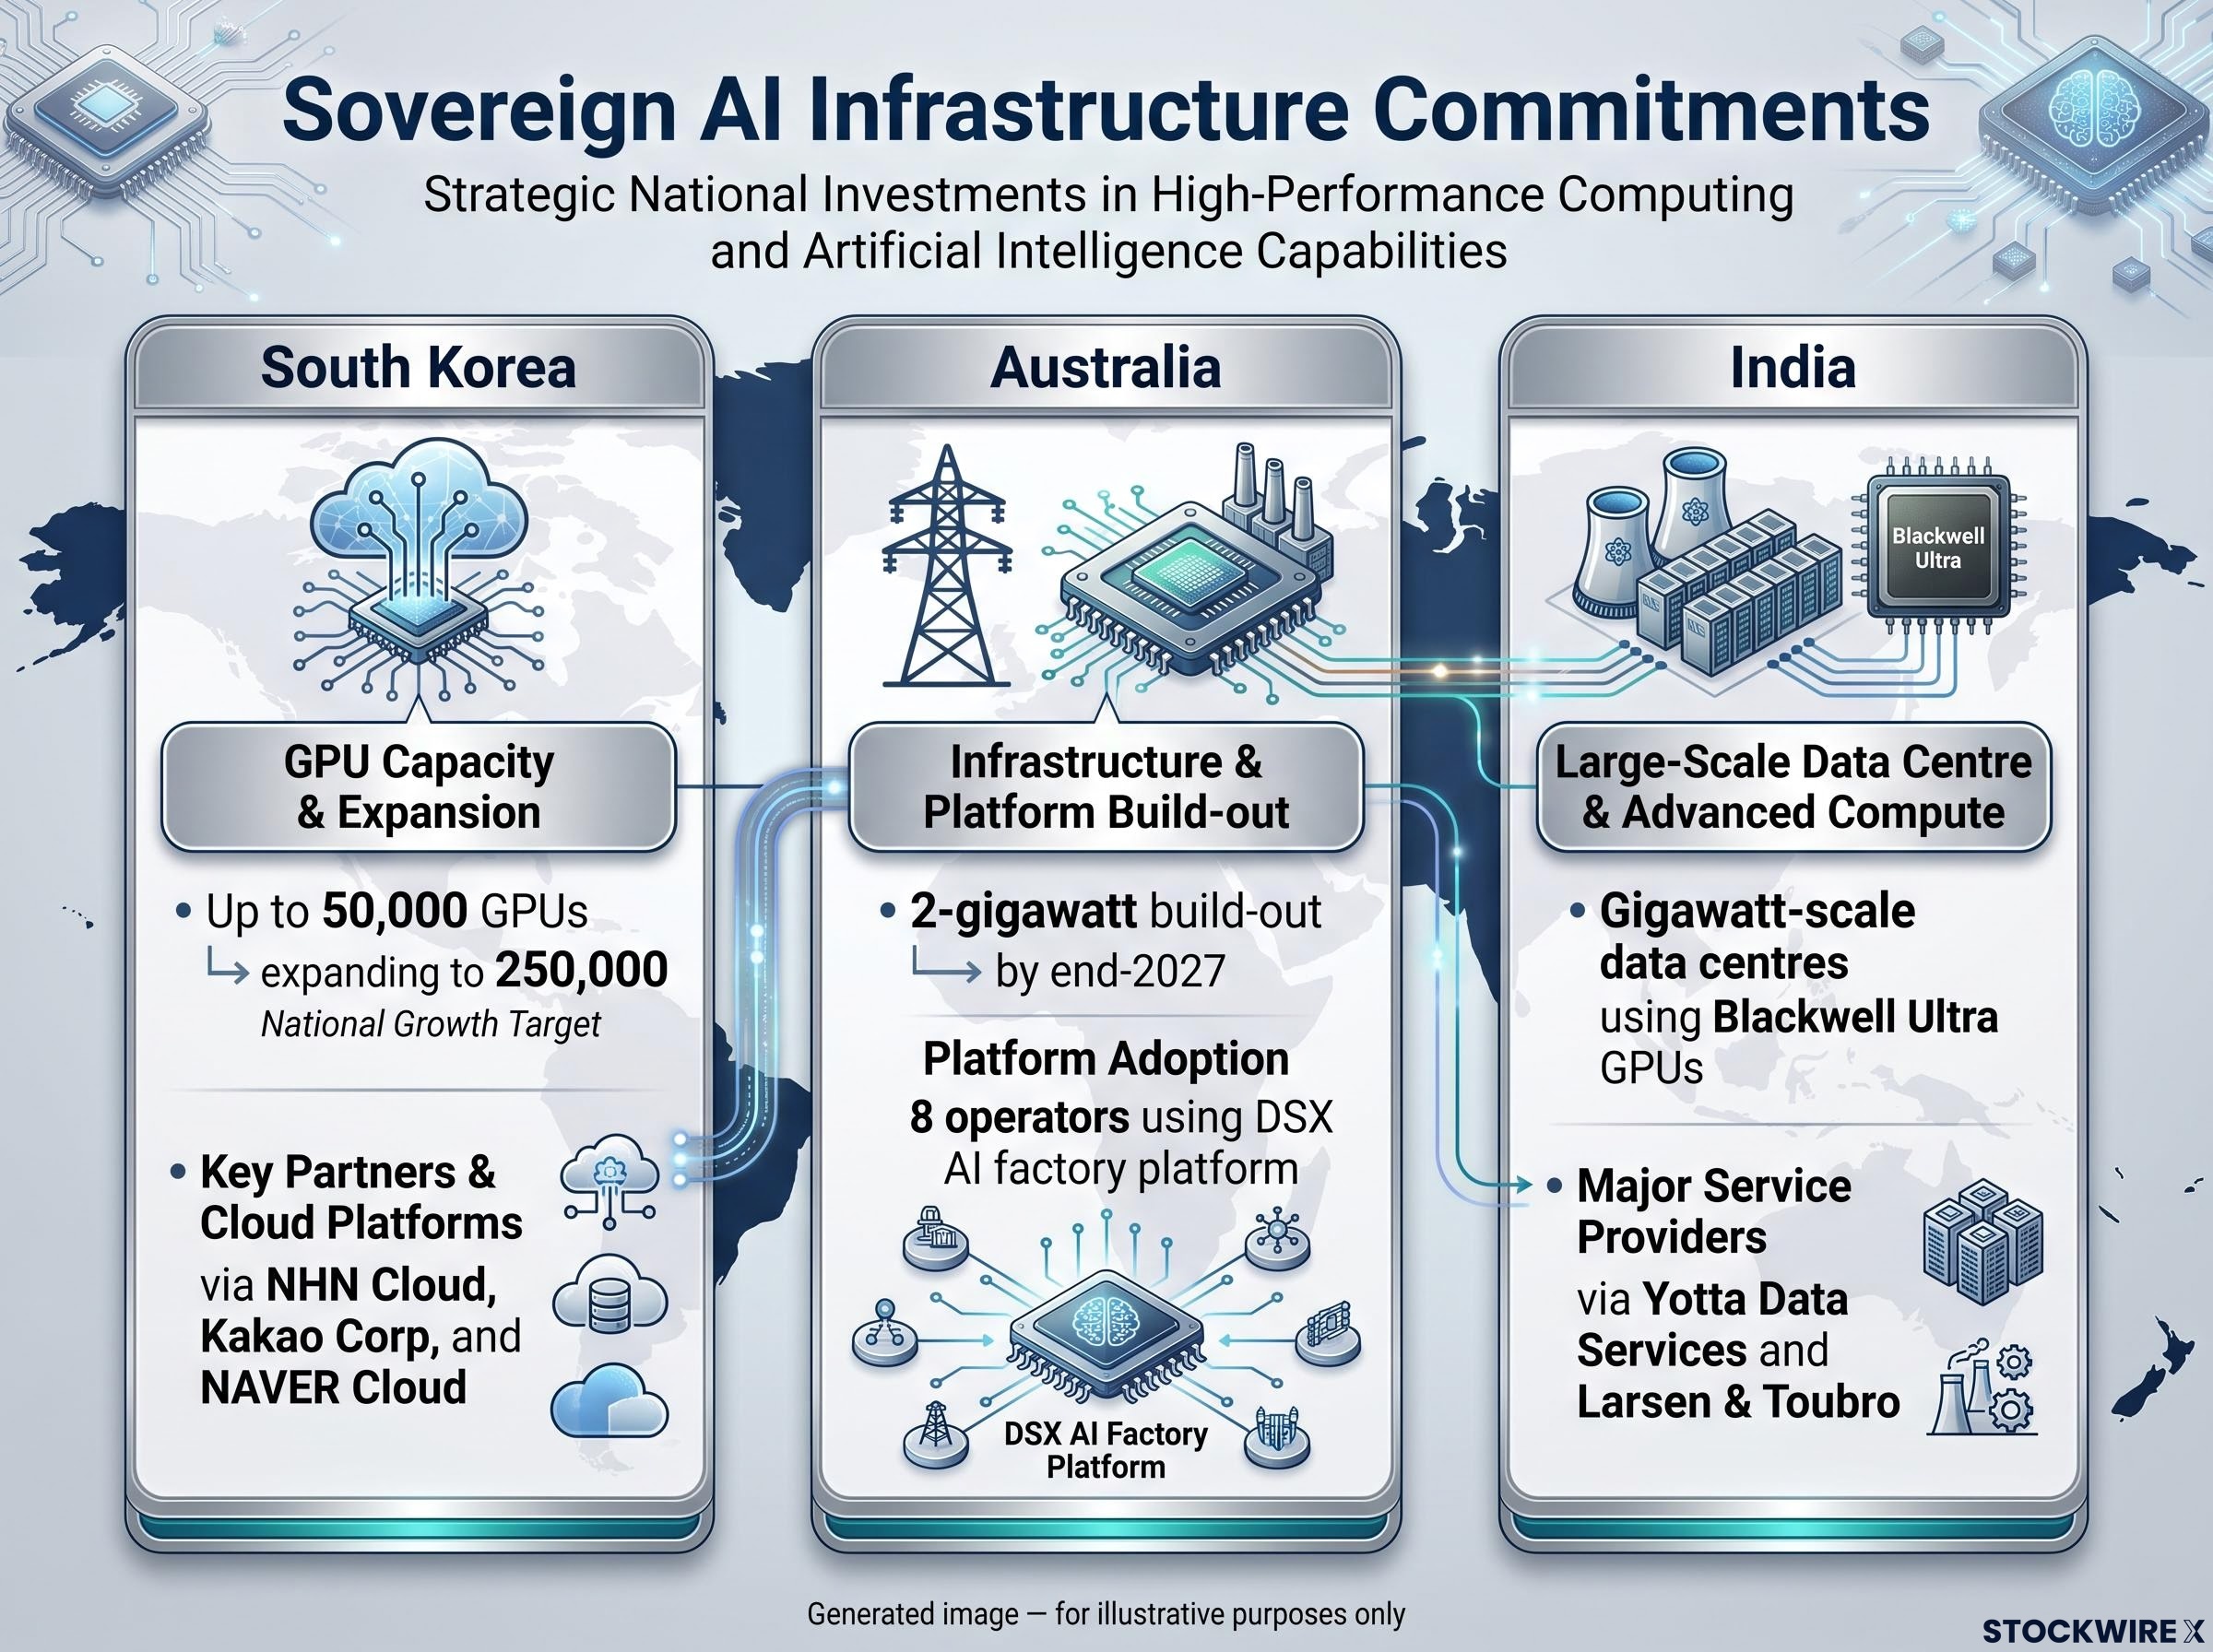
Three named examples show the breadth Huang described:
- South Korea: A government-led program deploying up to 50,000 of the latest Nvidia GPUs through NHN Cloud, Kakao Corp, and NAVER Cloud, with plans to expand toward 250,000 GPUs across sovereign clouds and AI factories.
- Australia: Eight designated operators targeting a coordinated 2-gigawatt build-out by end-2027, powered by Nvidia’s DSX AI factory platform.
- India: Yotta Data Services and Larsen & Toubro committing multi-billion-dollar, gigawatt-scale data centres with Blackwell Ultra GPUs at the core.
The distinction matters for durability. Sovereign demand rests on government mandates rather than commercial ROI calculations, which means it can persist even if hyperscalers pull back, but it also depends on sustained political and fiscal choices.
Nvidia management’s visibility claim The company has told investors it sees roughly US$500 billion in orders for its most advanced chips over the next 14 months.
If you separate these two streams, you get a clearer read on where volume growth is genuinely durable and where it leans on continued capital-allocation or political will.
Where analysts see the forecast coming apart
The bull case is specific. So is the bear case. A doubling of chip volume is management’s base case, not a guaranteed outcome, and the risks that would falsify it are named, not abstract.
Four structural risks stand out:
- Custom silicon competition. Google’s TPUs, AWS Trainium, and in-house accelerators from Meta and Microsoft all aim to reduce reliance on Nvidia. Trefis flags this as the primary long-term bear argument, and the stakes are high because these same hyperscalers account for more than half of Nvidia’s data-centre revenue. Displacement by even one or two of them would carry material consequences.
- Export controls. This is a demonstrated risk, not a hypothetical one. Nvidia’s FQ1 2025 data-centre revenue absorbed a US$2.5 billion shortfall tied to US restrictions on China-bound H20 chips, according to Proactive Investors. Trefis notes that new performance-density caps under legislation such as the MATCH Act could remove additional markets abruptly.
- ROI scrutiny and demand durability. ValueAddVC observed that Alphabet’s stock fell 7% in a single session after it raised capex guidance, illustrating investor unease that AI spending is running ahead of AI revenue. This is a demand-durability question rather than a near-term binary.
- Supply-chain constraints. Memory shortages have been flagged as a potential limit on Nvidia’s ability to hit delivery targets. (Reported as an analyst concern; not independently confirmed.)
The export-control loophole closure announced by the U.S. Commerce Department on 31 May 2026 demonstrated exactly how abruptly the regulatory floor can move: a new headquarters-based licensing standard eliminated a roughly one-year enforcement gap through which Chinese-affiliated companies had received restricted chips via third-country subsidiaries.
HashrateIndex’s hyperscaler AI ASIC market analysis tracks the deployment trajectories of Google TPUs, AWS Trainium, and in-house accelerators from Meta and Microsoft, finding that custom silicon adoption is accelerating but remains concentrated in narrow workload categories where third-party GPUs still dominate on performance breadth.
Business Insider, citing a skeptical analyst Spending on Nvidia GPUs by its largest customers may have peaked, with a demand decline described as “inevitable” as buyers scrutinise ROI on AI compute.
Of these, the export-control precedent is the most concrete for you to weigh. It has already stripped out a large revenue line in a single quarter, and it can happen again without warning. That gives Nvidia’s growth trajectory a regulatory optionality that revenue forecasts do not fully capture.
What the revenue guidance and chip forecast mean for AI infrastructure investors
Here is the interpretive frame that matters. The question is not simply whether Nvidia hits its targets. It is what the guidance, and the credibility debate around it, reveals about how to think about AI infrastructure exposure right now.
The fiscal 2028 guidance is structurally significant regardless of the exact landing point. The gap between management’s view and the Street’s prior view signals real visibility into near-term demand, and Nvidia’s claim of roughly US$500 billion in visible orders over the next 14 months is the demand-durability evidence behind it.
The market, however, is only partially endorsing the forecast. Post-guidance analyst consensus sits near 63% growth against management’s 70% target. That 7-percentage-point gap is itself an interpretive signal: it is essentially a quantified expression of how much structural risk the market is still pricing in.
For the longer horizon, Nvidia management has forecast US$3-4 trillion in annual AI infrastructure spending globally by the end of the decade, framing current orders as an early stage rather than a peak.
Nvidia management’s decade-scale thesis Global AI infrastructure spending is forecast to reach US$3-4 trillion annually by the end of the decade.
Whether you are long Nvidia directly, exposed through AI infrastructure funds, or evaluating adjacent plays in power, networking, or memory, this guidance sets the directional frame for the sector. To assess whether the doubling projection is on track, these are the indicators worth watching:
Semiconductor sector divergence in 2026 makes broad-basket AI exposure a misleading frame: Nvidia posted 85% revenue growth for three consecutive accelerating quarters while Qualcomm contracted 3.5% in the same period, confirming that end-market exposure rather than sector membership determines returns.
- Hyperscaler capex revision cadence at Q3 and Q4 2026 earnings
- Rubin production ramp progress into the second half of 2026
- Export-control legislative developments
- AI monetisation signals from the major cloud providers
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments and company performance.
What the forecast is anchored to, and which variables will decide it
The core tension is now clear. On one side, a management projection of double chip volumes backed by visible order flow and two distinct demand pools. On the other, a set of structural risks, each with a documented precedent or a named set of actors already acting on it.
That tension does not resolve neatly, and it should not be forced to. The bull case holds if hyperscaler capex stays elevated, sovereign programs deliver, and export controls remain contained. It comes under pressure if custom silicon scales, monetisation keeps lagging spend, or regulation removes a market without notice.
The read to carry out of this is not whether Huang is right. It is which of the named variables will decide the outcome, and what observable signals will move before the next earnings cycle. Watch the Rubin ramp in the second half of 2026, the Q3 and Q4 hyperscaler capex confirmations, the export-control legislative calendar, and whether the Street’s 63% consensus drifts toward or away from management’s 70%.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.