Meta Platforms said yesterday it will create a new non-voting Class C stock and pay it out as a dividend: one Class C share for every Class A and Class B share outstanding, with Nasdaq trading slated to begin in January 2027. Investors did not wait for the details to settle. Meta shares fell today as the market weighed what the new class could eventually be used for.
The plan arrives alongside a heavier spending outlook, with 2026 capital expenditure guidance now $135 billion to $145 billion. The dividend itself raises no cash on day one. Its value to Meta lies in what it permits later.
The structure also connects to Mark Zuckerberg’s control of the company and to California’s Proposition 40 wealth tax vote on 3 November.
Here is what you receive, what could dilute you, and what the voting gap means for your holding.
What shareholders actually receive, and why the stock fell
Start with the reassuring part. Your ownership percentage does not change. Every holder gets one Class C share per existing share, so the distribution works economically like a two-for-one stock split, with voting percentages left exactly where they are.
| Item | Detail |
|---|---|
| Ratio | 1 Class C share per Class A and per Class B share |
| Effective date | Amended charter intended to take effect 19 January 2027 |
| Listing | Nasdaq, subject to approval |
| Record and payment | Set by the board; payment within 5 business days of charter effectiveness |
| Cash raised at distribution | None |
| Intended uses | Capital raising, employee pay, acquisitions, financings, general corporate purposes |
The market’s concern sits elsewhere. Reported intraday declines on 22 October ranged from roughly 3% to 6%, with StockStory citing a 5.7% morning drop. Coverage tied the selloff to AI spending and the prospect of future issuance, not the dividend itself.
Meta’s latest 2026 guidance shows why:
- Capital expenditure of $135 billion to $145 billion, with the lower end raised from $130 billion
- Total expenses of $175 billion to $179 billion
- Negative free cash flow in the quarter
Reuters has reported long-term projections suggesting Meta may need hundreds of billions of dollars in fresh capital. The dividend does not dilute you. The share price tells you investors are already discounting what Meta may sell afterwards.
Meta’s latest earnings showed revenue up 26% but operating income down 37% after a $9.89 billion legal charge, which sharpens the question of how the company will pay for its AI buildout.
When big ASX news breaks, our subscribers know first
How non-voting shares let Meta fund AI without diluting Zuckerberg
The control arithmetic explains the design. Meta already runs two classes of stock, and Class C adds a third.
| Class | Votes per share | Role |
|---|---|---|
| Class A | 1 | Publicly traded voting shares |
| Class B | 10 | High-vote shares concentrated with Zuckerberg |
| Class C | 0 | Non-voting currency for raising capital and paying staff |
Every new Class A share Meta sells adds votes held by outsiders, shrinking Zuckerberg’s share of the total. According to the SEC information statement, financial adviser Moelis & Company reportedly analysed how much Meta could raise under the existing structure before his voting control fell below 50%. A zero-vote class removes that ceiling entirely.
Meta described the purpose in its filing as financing flexibility for infrastructure and AI investment without diluting existing voting control. It also said it intends to build a liquid Class C market to narrow any discount to Class A.
There is precedent. Alphabet created non-voting Class C shares through a stock-split dividend in 2014, and Snap floated with non-voting public shares. One limit applies: non-voting stock may not qualify for some tax-deferred acquisition structures under Section 368(a) of the Internal Revenue Code.
Proxy advisers ISS and Glass Lewis treat dual-class structures without credible sunset provisions as material governance risks, and the same scrutiny is likely to follow a three-class setup that caps outside investors’ influence.
For you as a holder, future capital will come from a class that cannot vote. Your claim on earnings stays intact, while your influence, and every outside investor’s, stops growing.
The Founder Alignment Agreement and the Proposition 40 question
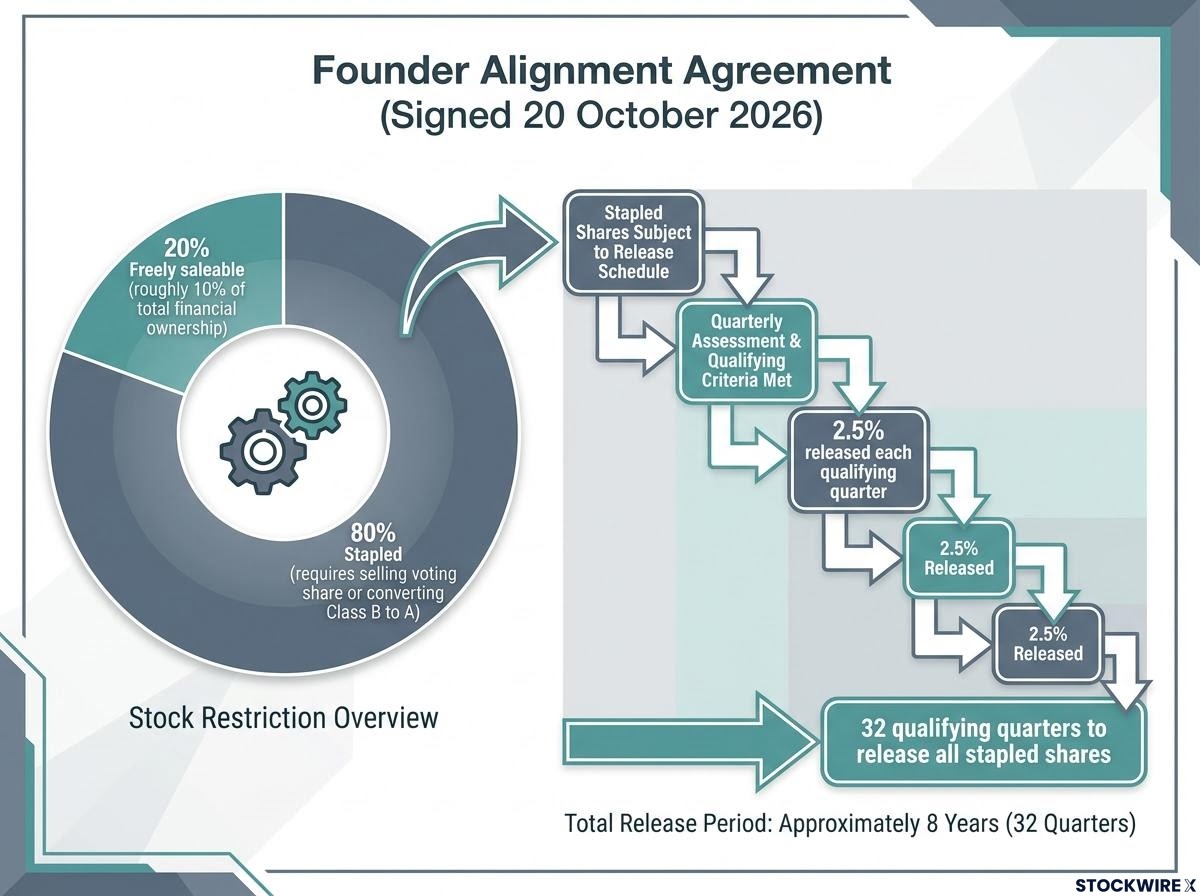
Alongside the recapitalisation, Meta and Zuckerberg signed a Founder Alignment Agreement on 20 October 2026, negotiated by an independent board committee. Zuckerberg commits to remain a resident of California, or wherever Meta is headquartered, for eight years. He withdrew a separate performance-based pay request and stays on a $1 salary.
The agreement controls how he can sell his Class C shares:
- 20% of his group’s Class C shares are freely saleable, roughly 10% of his total financial ownership in Meta.
- The remaining 80% are “stapled”, meaning selling one generally requires selling a voting share or converting a Class B share to Class A.
- 2.5% of the initial allotment is released each qualifying quarter, provided he stays full-time on the executive team or as executive chair.
- After 32 qualifying quarters, all remaining stapled shares are released.
Two readings of the same deal
Bloomberg framed the plan as a way to fund the AI buildout, pointing to the capex guidance and Meta’s listed uses. Morningstar and MarketWatch read it mainly as a path for Zuckerberg to stay in California with liquidity for a possible Proposition 40 bill.
That ballot measure, voted on 3 November 2026, would impose a one-time 5% tax on net worth above $1 billion for residents as of 1 January 2026, measured on 31 December 2026 and payable over five years. Before the deal, Zuckerberg had considered leaving the state.
The evidence supports both purposes. The dividend raises no cash, so any AI benefit depends on later issuance, while the residency terms directly explain the restrictions on his shares. For you, founder selling is now contractually staged, so large insider sales are less likely to surprise you, but his residency becomes a governance variable.
Readers wanting the policy background will find our full explainer on Proposition 40 useful, covering how the buy-borrow-die strategy shapes the billionaire wealth tax debate.
What investors should weigh: discounts, dilution and open questions
The most concrete risk is price. Meta’s own filing warns that Class C could trade below Class A because it carries no votes. Investing.com noted that a large discount would force Meta to issue more shares to raise the same money, increasing economic dilution.
Economic dilution works differently from voting dilution: later Class C issuance for cash, acquisitions or pay would leave per-share claims on earnings smaller even though voting percentages never move.
- Valuation discount: a lower Class C price raises the cost of each funding round
- Dilution: later issuance for cash, acquisitions or pay could reduce your economic share
- Liquidity: a new security can develop wider spreads if volume is thin
- Index treatment: FTSE Russell requires at least 5% of aggregate voting rights held by unrestricted public shareholders for eligibility
- Litigation: Zuckerberg-related entities reportedly could approve the plan by written consent, which may invite minority-shareholder suits
The counterargument deserves weight. The new shares change nobody’s percentages today and could prove a cheaper, more flexible financing tool than additional voting stock.
Treat the gap between Class C and Class A as the number to watch once trading begins. It determines how much each future dollar of AI funding costs you.
What is still unknown
- Neither S&P Dow Jones nor FTSE Russell has issued a ruling on Meta Class C.
- ISS, Glass Lewis and the Council of Institutional Investors had published no comment as of 22 October 2026.
- No lawsuit challenging the recapitalisation has been found.
- The board has not yet set the record date.
What the Class C plan settles, and what the next few months will decide
The structure removes the voting constraint on raising capital. It does not fund anything by itself, and it does not set the discount the market will apply.
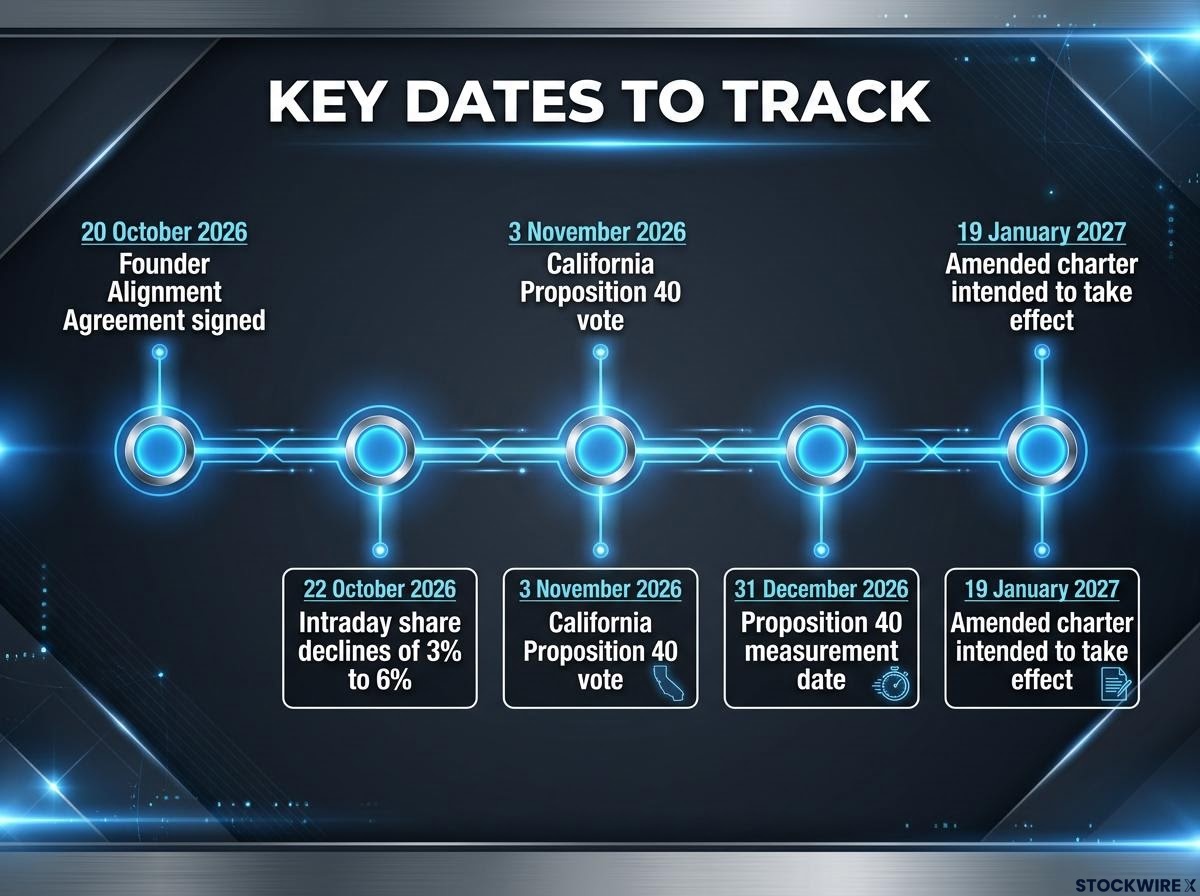
The markers to track are close together: the Proposition 40 vote on 3 November, the board’s record and payment dates, Nasdaq approval, the 19 January 2027 charter effective date and Meta’s first Class C offering. For holders, the decision comes down to whether the price of non-voting access matches your view of the returns Meta can earn on its AI spending.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.