The S&P/ASX 200 slipped 38.1 points, or 0.43%, to 8,793.20 on Thursday, even though eight of the market’s eleven sectors finished higher. The damage came from three places: energy, materials and consumer discretionary.
Those three sectors carry enough weight to override a broad but modest advance. Resource stocks sold off despite firmer oil, and a profit warning from Nick Scali dragged retailers lower.
The index has barely moved over the week. With Friday’s session still to come, a run of three straight weekly gains is at risk. NextDC gave holders some relief, bouncing after Wednesday’s collapse.
This wrap explains how a narrow group of sectors outweighed a wide advance, which stocks drove the moves, and what to watch heading into Friday.
Why did three falling sectors outweigh eight rising ones?
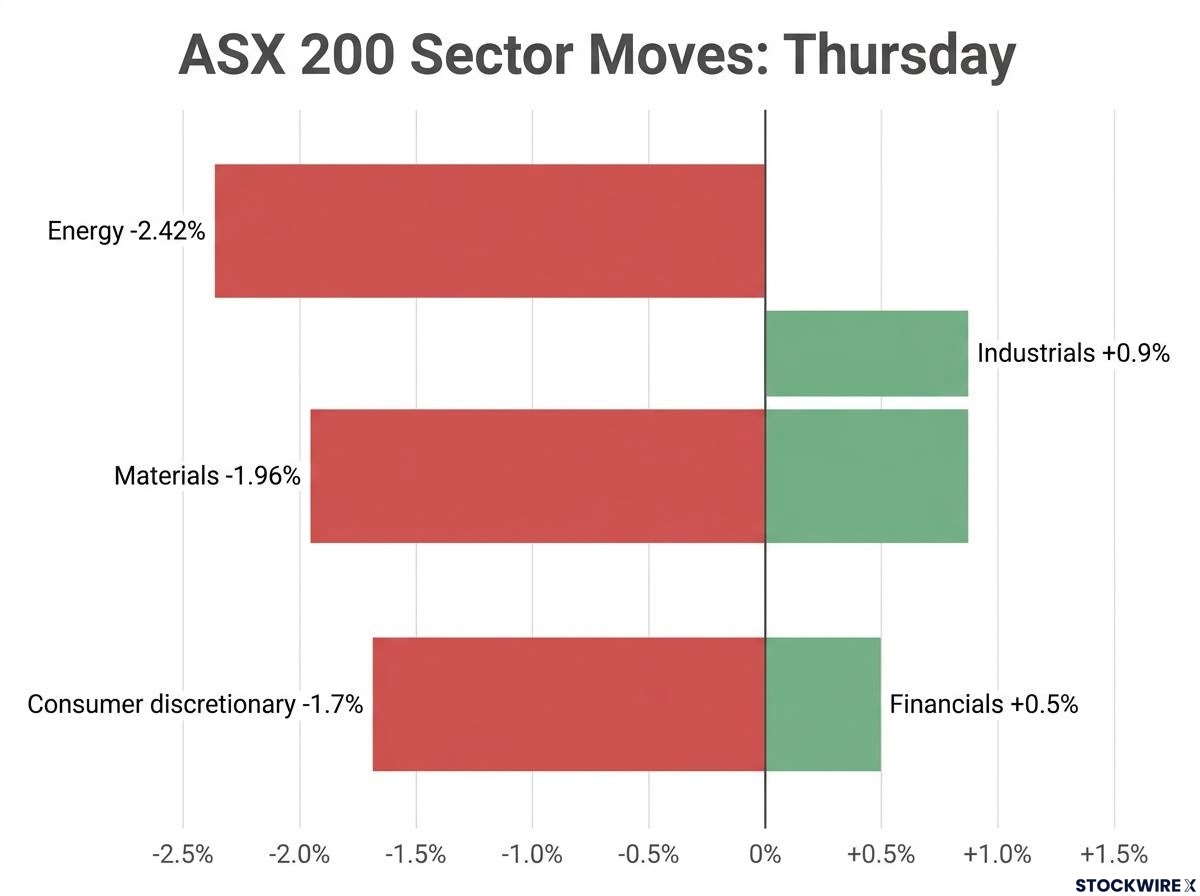
On paper, Thursday looked like a decent day. Financials rose almost 0.5%, industrials added about 0.9%, and technology, healthcare and utilities edged higher.
The falls were simply bigger, and they landed in heavyweight sectors.
| Sector | Move on 22 October |
|---|---|
| Energy | -2.42% |
| Materials | -1.96% |
| Consumer discretionary | About -1.7% |
| Financials | Up almost 0.5% |
| Industrials | Up about 0.9% |
| Technology, healthcare, utilities | Marginally higher |
If you hold an index fund, this is why your balance dipped on a day when most of the market rose. Before judging whether a session was genuinely weak, check the breadth and the weightings behind the headline number.
Energy and materials
Energy fell hardest on a day when Brent crude rose 0.8%. The selling reflected weakness in large index constituents and a wider retreat from resource stocks. Higher oil can also spook equity investors when they read it as an inflation and interest rate risk rather than a clean earnings boost.
Materials are heading for an eighth straight weekly fall. Iron ore slipped 0.2% to US$91.00 a tonne and is down about 7% over the past month, weighed by soft Chinese steel demand.
S&P Global analyst Paul Bartholomew expects negative mill margins, meaning steelmakers are losing money on each tonne they produce, along with lower pig iron output to restrain iron ore demand through the rest of 2026. Westpac sees prices softening towards about US$83 a tonne by the December quarter of 2027.
Currency and commodities
- Copper: about US$14,364/t, down 0.4% and roughly 3.4% below its 10 September record
- Gold: up 0.2% to about US$4,134/oz
- Brent crude: about US$109.70 a barrel
- Australian dollar: about US70.1¢, also softer against the euro and yen
Which stocks drove the session, from NextDC’s bounce to Nick Scali’s slump?
Winners
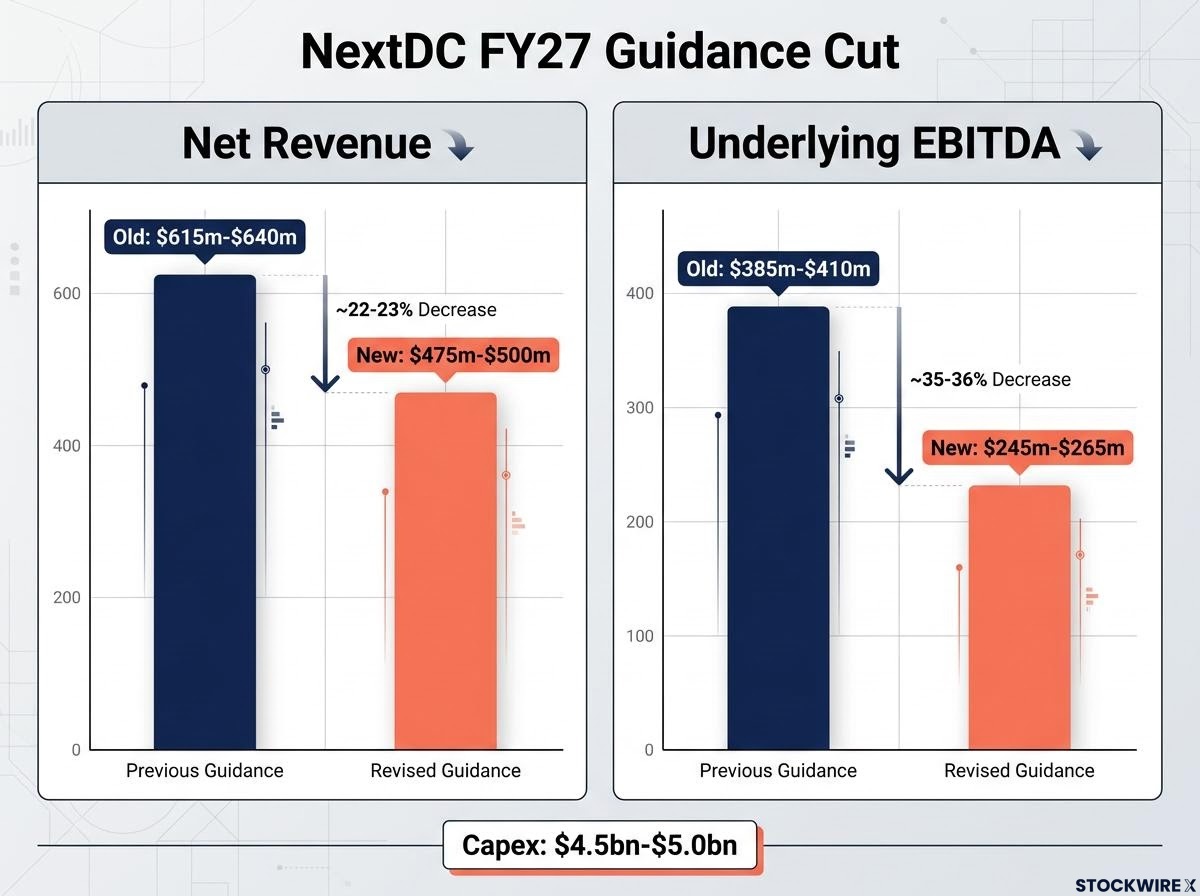
NextDC rebounded 7.5% to $5.75 after Wednesday’s roughly 42% plunge. That fall followed a sharp cut to FY27 guidance. Delayed electricity network works for its M3 Melbourne data centre have pushed the next grid supply increase out to FY28.
Net revenue guidance fell to $475m-$500m from $615m-$640m. Underlying EBITDA, a measure of earnings before interest, tax, depreciation and amortisation, dropped to $245m-$265m from $385m-$410m. Capital expenditure (capex), the money spent on building assets, is now $4.5bn-$5.0bn.
Citi’s view Citi analyst Siraj Ahmed said the earnings impact was “much higher than expected.”
The bounce does not undo that downgrade. Treat a one-day rebound as a pause, not a verdict on the timing risk that remains in place.
Pro Medicus climbed after securing a second major US contract this week. Brambles rose after an annual general meeting (AGM) update that held its full-year outlook despite problems in its US business. Bapcor surged on signs its turnaround is gaining traction, though the gain came off a low share price base.
Losers
Nick Scali fell 15.3% to a three-year low. It expects first-half FY27 net profit of $28m-$32m, down from $41m, after Australian and New Zealand written orders fell 15% in the September quarter. Harvey Norman, JB Hi-Fi and Temple & Webster followed it lower.
CommSec’s Steven Daghlian said consumer discretionary is down about 10% for the year. Rate worries add pressure: markets price a 43% chance of a November rate rise after RBA deputy governor Andrew Hauser flagged a worse inflation outlook.
Fortescue dropped 4%-4.5%. First-quarter shipments fell 6% to 46.8Mt, while sales reached only 42.9Mt amid talks with China Mineral Resources Group. The miner retained shipment guidance of 197Mt-207Mt.
| Stock | Move | Close or level | Reason |
|---|---|---|---|
| NextDC | +7.5% | $5.75 | Rebound after guidance cut |
| Pro Medicus | Higher | Not reported | Second US contract |
| Brambles | +3.16% | $21.23 | Outlook held at AGM |
| Bapcor | +14.19% | $0.885 | Turnaround progress |
| Nick Scali | -15.3% | About $12.03 | Profit guidance cut |
| Fortescue | -4% to -4.5% | Not reported | Weak shipments, China talks |
What should investors watch on Friday and beyond?
The index sits slightly negative for the week, so Friday decides whether three weekly gains become four. Materials are on track for an eighth weekly decline, and resource updates will test that trend directly.
- Local: Quarterly reports are expected from Mineral Resources, Whitehaven Coal and Zip, with AGMs from Temple & Webster, Reliance Worldwide and Aussie Broadband. Specific dates could not be independently confirmed.
- Local: Watch any further commentary on Fortescue’s year-end deadline for its China sales talks.
- US: Procter & Gamble, Newmont, Spotify, Blackstone and American Airlines report on Thursday night US time. No Magnificent Seven companies are reporting.
- US: Weekly jobless claims data is due and could shape Friday’s local open.
Friday’s resource and retail updates will show you whether Thursday’s weakness is spreading or contained. That should decide how cautious you want to be heading into the weekend.
What Thursday’s session changes, and what it leaves open
Breadth was positive, but concentrated selling in resources and retail set the tone. NextDC’s rebound eased the pain without solving its power delay, and the earnings hit stays in its forecasts.
Several variables remain open. Fortescue’s China sales talks, the November rate-rise odds and Friday’s company reports could each tip sentiment either way.
Keep an eye on whether materials stocks find support on Friday, because that sector is the weight holding the index back.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Forecasts cited are subject to market conditions and various risk factors.