The Fed just raised rates to 3.75-4%. The labour market is holding steady. And yet, on 2 October 2026, Chicago Fed President Austan Goolsbee told markets that another hike and a pause are both live possibilities, with neither carrying an edge.
That is an unusual place for a central banker to stand. Three weeks after breaking a four-meeting holding pattern with a quarter-point increase, the Fed is signalling that it genuinely does not know what it will do next, because it is waiting on the data rather than following a plan.
This matters now because the signals have shifted. From March through July 2026, the Fed held rates steady across four consecutive meetings. The 16 September hike broke that run. Goolsbee’s October remarks land in the immediate aftermath, with Personal Consumption Expenditures (PCE) inflation still at 3.7% year-over-year in July and no next meeting date yet on the public calendar. Here is what to actually watch as the evidence arrives, and how to position for a rate path the Fed itself has refused to pre-commit.
Why the 2% target is doing more policy work than the unemployment rate right now
To understand where rate expectations sit, start with which of the Fed’s two jobs is currently calling the shots. The Federal Reserve operates under a dual mandate: keeping prices stable and keeping employment as high as the economy can sustain. In normal conditions, it balances the two. Through 2026, that balance has not been in play.
The Fed’s dual mandate creates an inherent priority problem when both objectives cannot be satisfied simultaneously; with unemployment stable and inflation running 1.7 points above target, the mandate hierarchy resolves unambiguously toward price stability as the operative constraint.
Across appearance after appearance, from May through October, Goolsbee characterised the jobs picture in near-identical terms. On 12 May, speaking to Reuters, he described the employment market as “essentially stable.” Stable is not a word that triggers action. It is a word that removes one mandate from the decision entirely.
Inflation was a different story. Headline Consumer Price Index (CPI), which measures the average change in prices households pay, ran at 4.2% year-over-year in May. Core PCE, the Fed’s preferred underlying gauge that strips out volatile food and energy, hit 3.4% in May, which CNBC noted was its highest reading since October 2023. Every one of these numbers sat significantly above the Fed’s 2% target.
Goolsbee, 12 May 2026 (Reuters): The employment market was “essentially stable” while the latest inflation report was “disappointing” and moving “in the wrong direction.” CPI that month stood at 4.2% year-over-year.
Here is the full picture of how far inflation sat from target.
| Inflation gauge | Reported value | Reference period | Gap to 2% target |
|---|---|---|---|
| PCE (year-over-year) | 3.7% | July 2026 | 1.7 points above |
| Core PCE | 3.4% | May 2026 | 1.4 points above |
| CPI (year-over-year) | 4.2% | May 2026 | 2.2 points above |
When one mandate is materially breached and the other is not, the breached one becomes the operative constraint. That spread between actual inflation and the 2% goal tells you the Fed is not running a balanced trade-off right now. It is operating in single-objective mode, and that asymmetry shapes every signal you receive. When Goolsbee calls the labour market stable, treat it as descriptive context, not a policy trigger.
When big ASX news breaks, our subscribers know first
What is actually driving inflation, and why the Fed cannot simply wait it out
For most of 2026, Goolsbee’s explanation for sticky inflation pointed outward, to forces the Fed did not create and could not directly control.
In PBS NewsHour coverage, he framed the problem as a series of persistent supply shocks: higher oil prices tied to geopolitical conflict, and the ongoing effect of tariffs feeding through to consumer prices. He was blunt that the remedy would be uncomfortable, describing the task of fighting inflation as likely to be “painful.” The only route down, in his telling, was raising rates to narrow the gap between what the economy could supply and what buyers wanted.
Supply-shock inflation carries a quiet comfort for policymakers: it can fade on its own. Oil prices settle. Tariff effects wash through the system. If the driver is external and temporary, patience is a legitimate strategy.
When tariff pressures fade but inflation does not
Then came the pivot. On 21 September, Reuters reported Goolsbee warning that US inflation may have moved beyond tariff and energy shocks, and may now be powered by strong demand. That shift could require a faster pace of rate hikes.
Goolsbee, 21 September 2026 (Reuters): Inflation may have moved beyond tariff and energy shocks and is now being powered by strong demand, potentially requiring a faster pace of rate hikes. It was the sharpest escalation in his public communications to date.
This is the most important signal in the 2026 inflation story. Demand-driven inflation does not expire. It is sustained by an economy running hotter than its capacity, and the only tool that reliably cools it is tighter policy. A supply shock resolves itself; demand pressure has to be actively compressed by the Fed.
The three identified drivers break down like this:
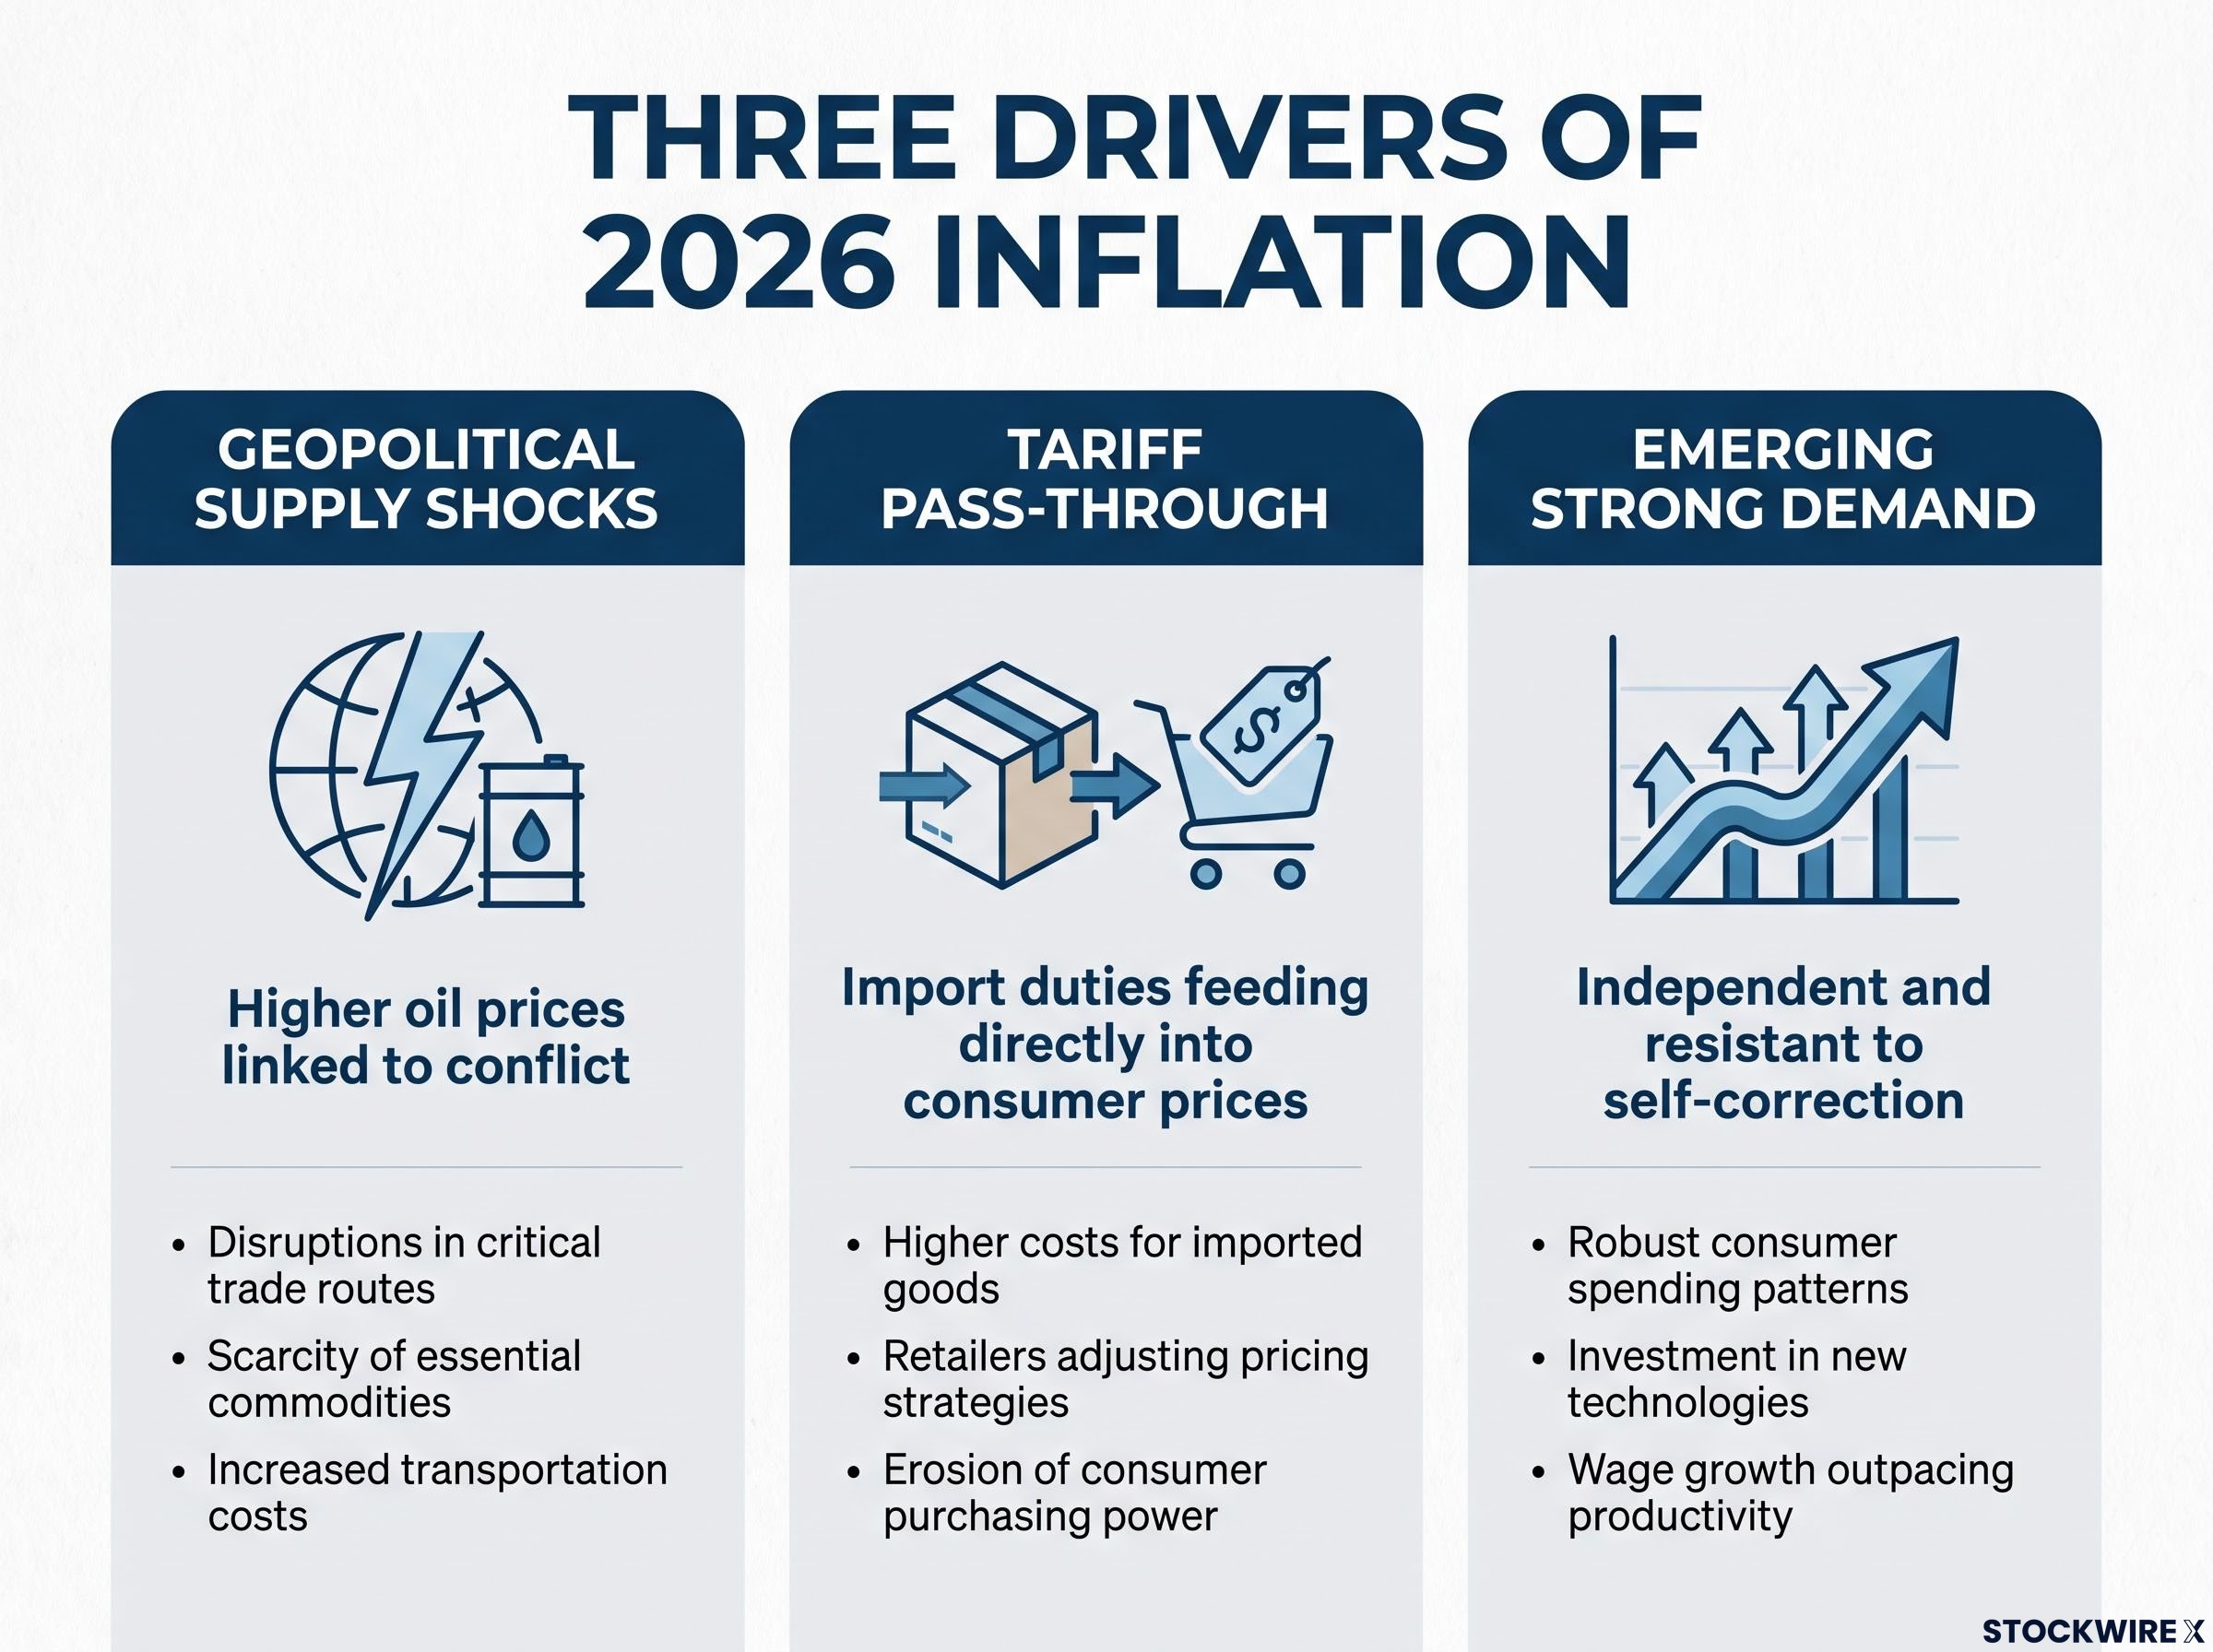
- Geopolitical supply shocks: higher oil prices linked to conflict, pushing input costs up across the economy.
- Tariff pass-through: import duties feeding directly into consumer prices.
- Emerging strong demand: the newest and most concerning driver, independent of the first two and resistant to self-correction.
The modest softening that justified the July hold was real but thin. CPI fell 0.4% month-over-month in June, then edged up just 0.1% in July, according to Fortune’s 2 September account. In June’s CNBC interview, Goolsbee had already described core inflation as “still well too high and trending the wrong way,” with services prices in particular refusing to cooperate.
The BLS CPI release for July 2026 confirmed the month-over-month sequence that shaped the Fed’s July hold decision: a 0.4% decline in June followed by only a 0.1% gain in July, a pattern encouraging enough to justify patience but too narrow to constitute the durable disinflation trend the Fed had set as its evidential bar.
That is the logic behind the “wait and see” stance. Modest monthly softening earns patience. It does not confirm a durable trend. And if demand is now the driver, patience alone will not finish the job.
What this means for you: the question of what is sustaining inflation decides how long rates stay elevated. If it is demand, higher-for-longer is not a risk scenario. It is the base case.
How to read the “both options on the table” signal
Goolsbee’s 2 October framing could be mistaken for indecision. It is the opposite. It is a deliberate statement of how the Fed intends to decide.
Goolsbee, 2 October 2026 (Reuters): Both a rate hike and a pause are “on the table.” The key is to “get some evidence” that the economy is heading back to 2% inflation.
The evidential bar here is specific, and it is high. The Fed is not looking for a single soft CPI print. It wants a pattern of convergence toward 2% across both headline and core measures, sustained long enough to rule out a blip. Goolsbee’s own words from Fortune capture it: after the June and July readings, he was comfortable holding to see “if this has legs, or is just a blip.” One month is a blip. A trend is evidence.
The Fed’s 2026 behaviour backs the words. It did not follow a pre-announced path. It responded.
| Date | Decision | Rate level | Rationale |
|---|---|---|---|
| 18 March 2026 | Hold | 3.5-3.75% | Elevated inflation, ongoing supply shocks |
| 29 April 2026 | Hold | 3.5-3.75% | Inflation still above target |
| 17 June 2026 | Hold | 3.5-3.75% | Awaiting durable disinflation signal |
| 29 July 2026 | Hold | 3.5-3.75% | Modest CPI softening; nine members voted to maintain |
| 16 September 2026 | Hike | 3.75-4% | Timelier return to the 2% goal |
Four holds, then a hike. That sequence is the proof of genuine data dependence. The Fed demonstrated it will wait, and then demonstrated it will move.
For you, “both options on the table” is not a non-answer. It is an instruction. Treat every incoming CPI and PCE release as a live policy input, not a data point on a predetermined track. That elevates the market-moving potential of each inflation print between now and the next decision, because each one shifts the odds rather than confirming a forecast.
The absence of forward guidance under the Warsh Fed means every inflation print now carries more market-moving weight than it did under prior communication regimes, because there is no Fed-provided probability anchor to dampen the repricing that follows a surprise reading.
What this means for portfolios in a rate-path-uncertain environment
Each of the investor consequences below follows directly from a documented feature of the current Fed stance. None of it is generic advice.
- Data sensitivity, tied to the optionality language: with each CPI and PCE print capable of swinging the odds between a hike and a pause, volatility around release dates is elevated in interest-rate-sensitive assets such as long-duration bonds and growth equities.
- Balanced duration, tied to the hold-then-hike pattern: Goolsbee’s willingness to hold in July and then open the door to faster hikes in September discourages heavy leveraged bets in either direction. Balanced duration exposure with room to adjust fits the actual posture better than conviction.
- Sector resilience, tied to the higher-for-longer possibility: with rates at 3.75-4% and PCE still at 3.7%, assets with genuine pricing power and low dependence on cheap financing tend to hold up better than speculative or heavily leveraged names when policy stays tight.
The signals worth watching between now and the next FOMC meeting
Two data series map most directly onto the Fed’s evidential threshold.
First, CPI month-over-month. This is the series that captures whether disinflation “has legs.” The June and July readings of -0.4% and +0.1% were encouraging but inconclusive. A string of soft monthly prints is what would tilt the Fed toward a pause.
Second, PCE year-over-year. This is the Fed’s preferred gauge and the one measured against the 2% target. At 3.7% in July, it shows how much ground still separates the economy from the goal.
Core PCE convergence toward the 2% target requires not just a falling annual rate but simultaneous movement across the Dallas Fed trimmed mean, Cleveland Fed median, and headline gauges, a five-point test the Fed applies before any easing cycle becomes credible.
One practical wrinkle: no next FOMC meeting date was publicly confirmed as of 2 October. That limits the market’s ability to price a specific event horizon, so watch Fed communications for the meeting announcement alongside the data.
The core misreading to avoid is treating this as either a pre-pivot moment or a confirmed tightening cycle. Both get the same signal wrong. The Fed has left the door open in both directions, and a portfolio built for one outcome carries more policy risk than the communications justify.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and these statements are speculative and subject to change based on market developments.
Where the Fed’s inflation-first stance leaves rate expectations heading into the next decision
Pull the threads together and the picture is consistent. The Fed is not signalling a pivot. It is not signalling an accelerating hike cycle. It is signalling that the data will decide, and the data do not yet decisively support either conclusion.
The counterargument deserves its place. Goolsbee himself called the fight against inflation likely to be “painful,” and overtightening is a real risk if the modest June and July improvements prove durable. That honesty is precisely why the Fed is watching before it commits. The 16 September hike to 3.75-4% proves it will act. The four prior holds prove it will wait.
Goolsbee, 2 October 2026 (Reuters): Both a rate hike and a pause are “on the table.” Fighting inflation, he has acknowledged, is likely to be “painful.”
The practical takeaway is this. The Fed’s rate path is genuinely undecided, not strategically ambiguous. With PCE at 3.7% and the 2% goal still well out of reach, calibrate your rate expectations not to a single outcome but to a probability distribution with both directions live, each inflation print shifting the odds. Investors who accept that uncertainty as the operating condition, rather than trying to pre-resolve it, will be better placed to respond as the evidence actually arrives.
For investors wanting to build a disciplined framework for filtering Fed communications by signal quality, our full explainer on reading FOMC minutes against live data covers the structural lag problem and the three situations where minutes retain genuine informational value despite arriving weeks after each decision.