The Federal Reserve raised interest rates in September for the first time since 2023, and the reasoning behind the move amounts to a consequential bet made on your behalf. Richmond Fed President Thomas Barkin stated it plainly: the hike was driven by a judgment that the risk of letting inflation run now outweighs the risk of letting unemployment drift higher. That is a deliberate ranking of the Fed’s two jobs, and it favours price stability over the labour market.
Why this matters now comes down to timing. The Fed held rates steady for the entire first half of 2026 before moving in September, so the shift from patience to tightening is not a reflex. It signals a specific read on where the danger sits, and rate decisions of this kind flow directly into mortgage costs, credit card rates, and the broader investment environment.
Here is what this analysis gives you: a framework for judging whether the Fed’s inflation-first rate strategy holds up against the current data, which variables could force a reversal, and what the realistic range of outcomes looks like from here. The goal is to help you read future Fed signals, not just this one decision.
The September rate move: what the Fed actually decided and why now
On 16 September 2026, the Federal Open Market Committee (FOMC) lifted the target range for the federal funds rate by 25 basis points to 3.75%-4.00%. The Board also raised the interest rate paid on reserve balances to 3.90%, effective 17 September 2026. According to CNBC’s coverage, this was the first rate increase since 2023.
The FOMC’s September 2026 press release confirms the target range increase to 3.75%-4.00%, the reserve balance rate adjustment to 3.90%, and the Committee’s explicit framing of the decision as support for a timelier return to the 2% inflation goal.
What makes the move significant is everything that came before it. Through the first seven months of the year, the FOMC left the target range untouched at 3.50%-3.75%, meeting after meeting.
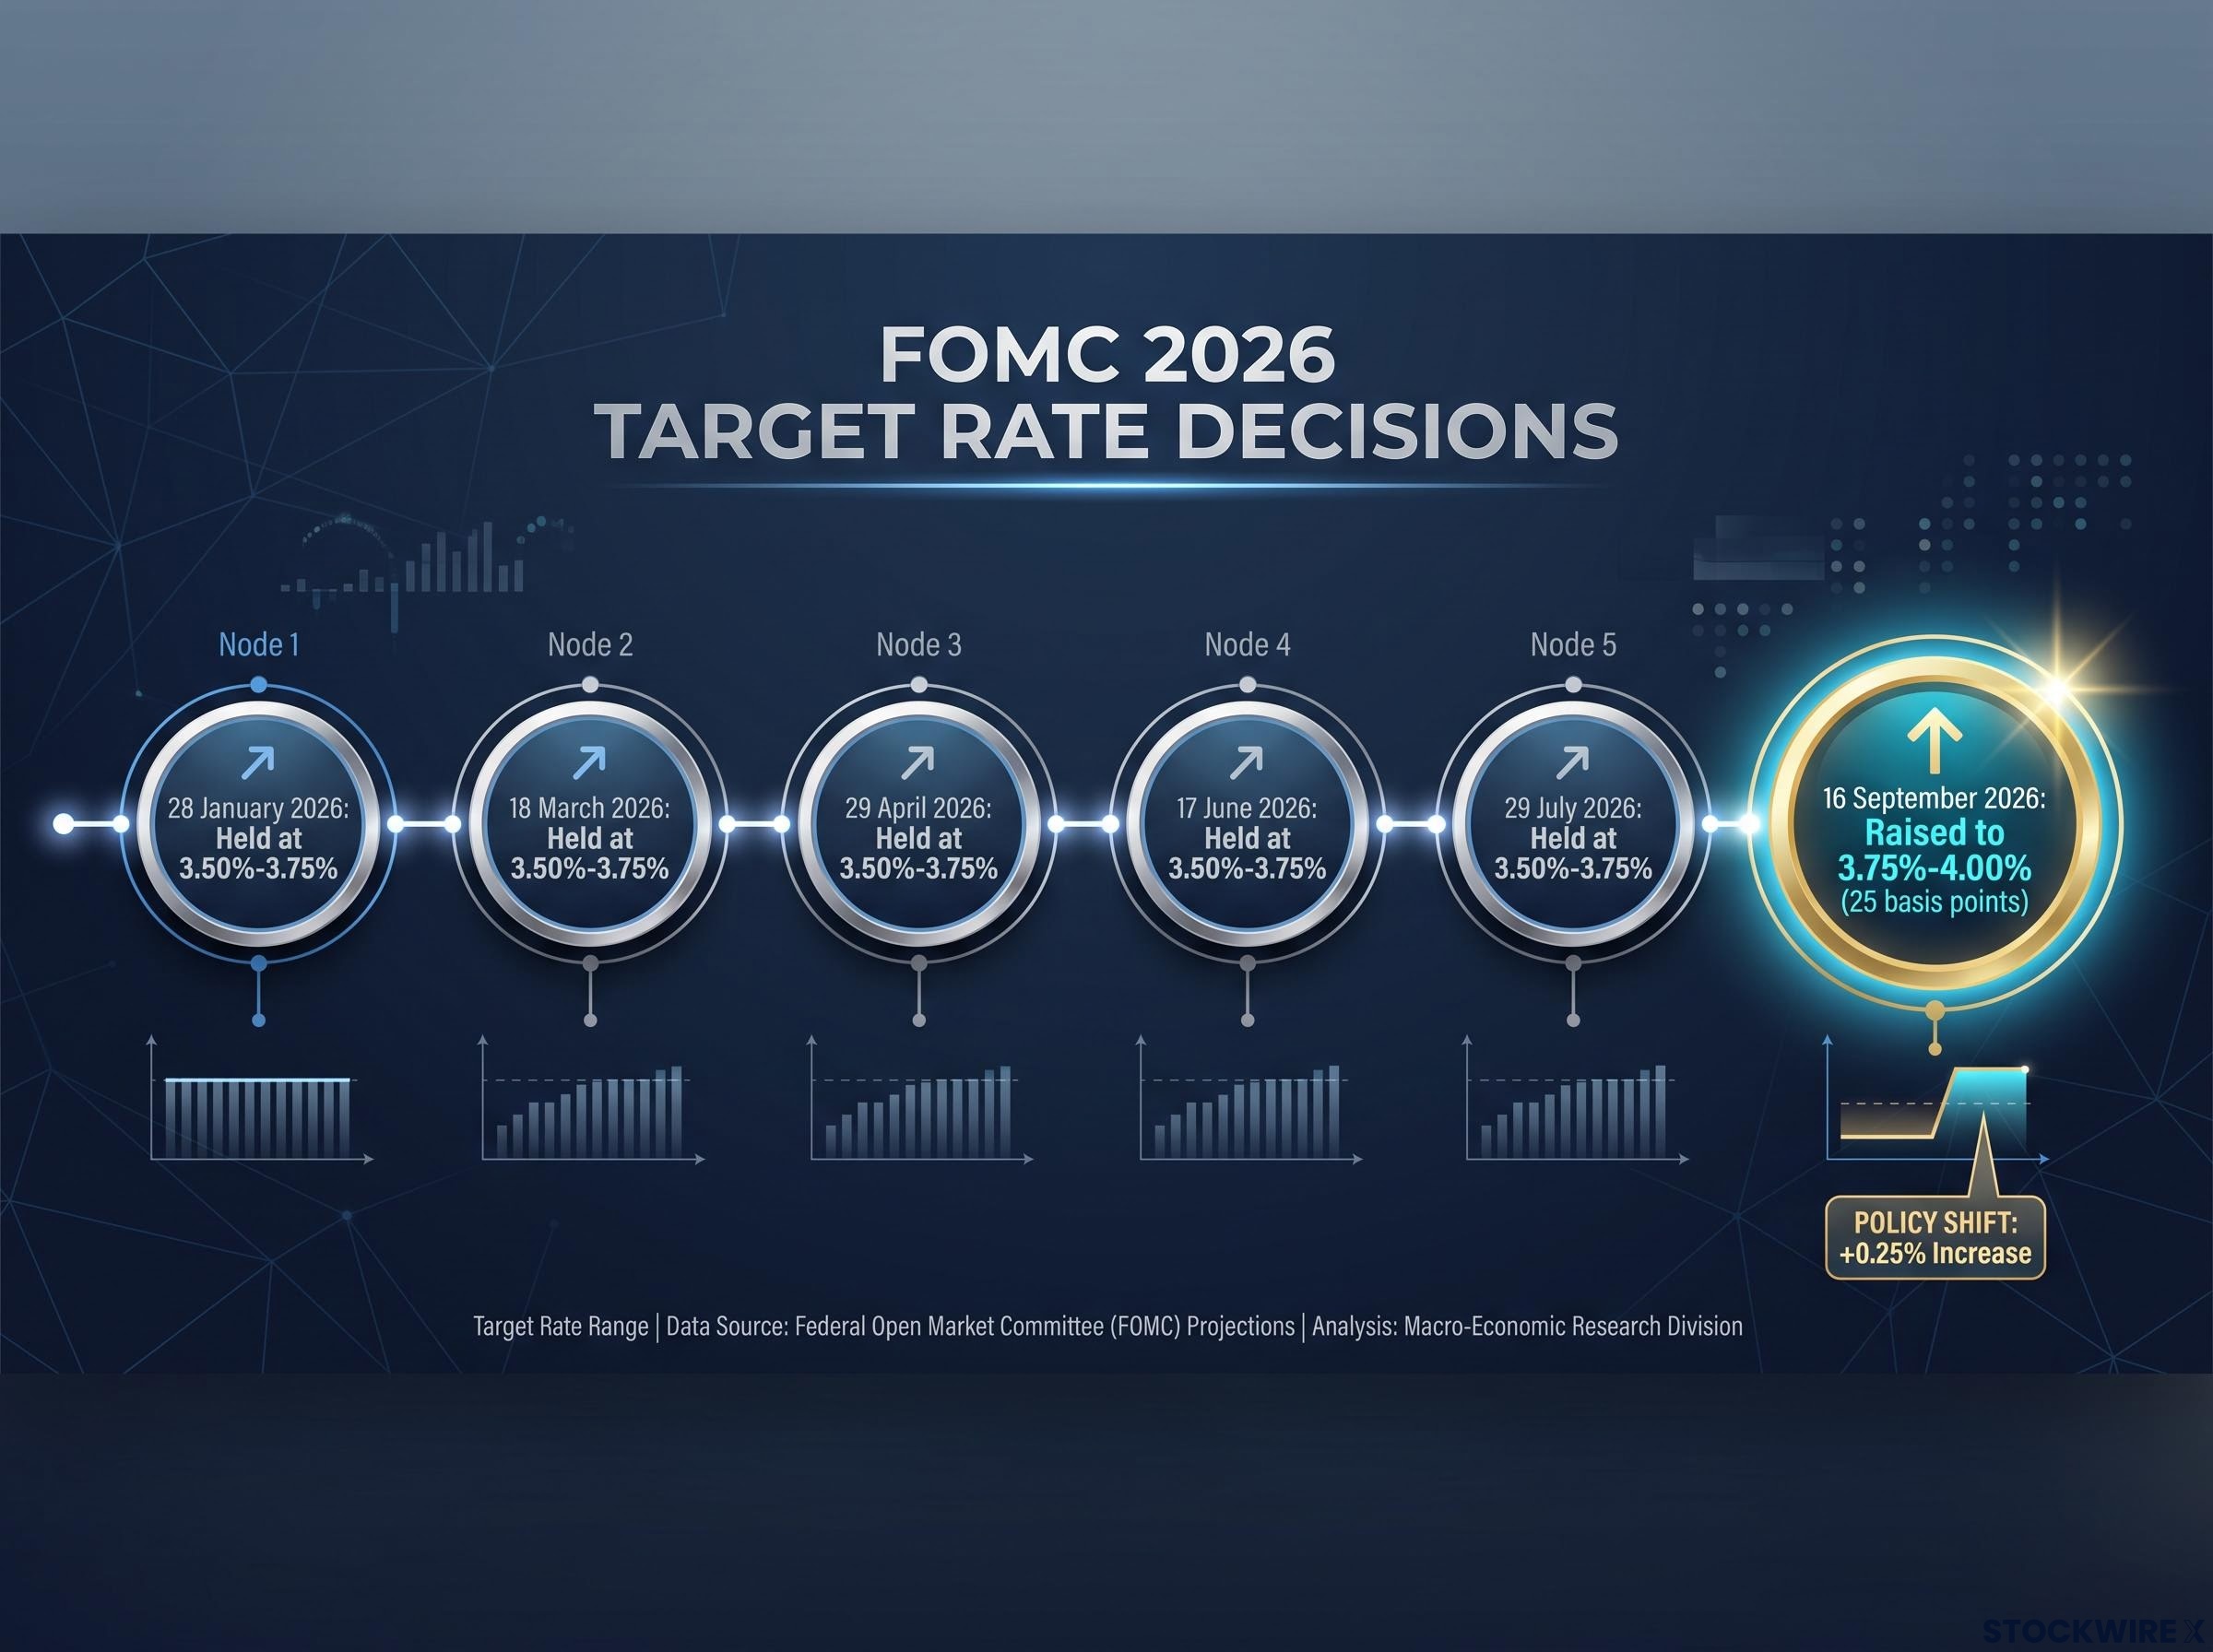
The pattern of restraint is worth seeing laid out:
- 28 January 2026: Held at 3.50%-3.75%
- 18 March 2026: Held at 3.50%-3.75%
- 29 April 2026: Held at 3.50%-3.75%
- 17 June 2026: Held at 3.50%-3.75%
- 29 July 2026: Held at 3.50%-3.75%
- 16 September 2026: Raised to 3.75%-4.00%
Five consecutive holds, then a hike. That sequence tells you the September decision was an inflection point, not incremental fine-tuning. The Fed had every opportunity to move earlier and chose not to, which means something in its risk calculus changed by late summer.
The Committee’s own language points to what shifted. The September statement framed the increase as support for a “timelier return” to the 2% inflation goal, and reiterated that inflation “remains elevated.”
The rate increase was designed to support a “timelier return to the Committee’s 2 percent goal” and to “deliver price stability.”
Barkin, speaking at a Baltimore event, gave the analytical anchor: the hike reflected a conscious judgment that inflationary risks now pose a greater threat than risks to full employment. That is the dual-mandate trade-off made explicit.
The Fed’s dual mandate creates an inherent ranking problem whenever price stability and maximum employment pull in opposite directions, and the September decision made that ranking explicit for the first time since the 2022-2023 tightening cycle.
For you, the practical read is that the cost-of-capital baseline has been reset upward after a year of stability. A first hike since 2023, following months of patience, is not noise. It resets the assumptions borrowers, businesses, and investors should be working from, and understanding what triggered it is the key to reading where rates go next.
When big ASX news breaks, our subscribers know first
Why inflation breadth, not just headline numbers, is driving the Fed’s calculus
The surface story is simple: inflation is elevated, so the Fed tightened. The more revealing story is why the Fed treats this inflation as durable rather than fleeting.
Barkin’s argument centres on breadth. He characterised inflationary pressure as widespread across the personal consumption expenditures (PCE) index, the Fed’s preferred inflation gauge, with a broad portion of categories advancing at a pace above 3%. A precise percentage figure has not been made public, so this is his qualitative read, not a hard statistic.
That distinction matters more than it might seem.
A broad portion of the personal consumption expenditures index is advancing at a pace exceeding 3%, characterising elevated inflation as widespread rather than concentrated in a narrow set of categories.
When price increases are concentrated in one or two areas, such as an energy spike or a specific tariff, they can self-correct as the shock fades. When they are spread across many spending categories at once, that suggests something more embedded. The FOMC’s September statement, describing inflation as “elevated,” lines up with Barkin’s characterisation.
PCE breadth across spending categories, not the headline rate alone, is the operative signal: the Dallas Fed trimmed mean and Cleveland Fed median gauges track this dimension of disinflation more precisely than core PCE and were both trending near 2% as recently as June, creating a divergence from the widening breadth Barkin described.
If breadth is genuinely wide, the Fed’s decision to prioritise price stability over employment softening reflects a fundamentally different risk environment than a single commodity spike would justify. You should treat that distinction as consequential, because it shapes how long this posture is likely to last. Duration of tightening depends on breadth, not the headline number alone.
When transitory stops meaning temporary
Barkin’s specific worry is that supply-side shocks such as tariffs and energy costs are not dissipating. The concern is not the current price level by itself, but what persistent price pressure does to expectations.
Here is the mechanism. When elevated prices linger long enough, firms and households begin factoring them into wage negotiations and contract pricing. At that point a shock that started as temporary becomes structural, because it is baked into how people set pay and prices going forward.
The historical reference point is the 1970s oil shocks. Repeated energy price increases, combined with accommodative policy and strong wage-bargaining institutions, allowed supply-side price rises to become embedded in expectations and wage contracts.
Economist Olivier Blanchard’s framework on supply shocks identifies three factors that determine whether a shock becomes embedded: its duration and perceived permanence, the credibility and aggressiveness of monetary policy in resisting second-round effects, and the strength of wage-setting mechanisms. Applied to today, with shocks that Barkin says are not fading and breadth that appears wide, the framework reinforces the logic of acting now. Once expectations shift upward, reversing them requires significantly more restrictive policy than heading them off in the first place.
What the labour market data actually say about the Fed’s room to act
An inflation-first stance only holds together if the employment side of the mandate can absorb it. The latest data suggest it can.
The August 2026 employment report from the U.S. Bureau of Labor Statistics, as reported by Reuters and Investing.com, showed unemployment steady at 4.1%, unchanged from July. Nonfarm payrolls rose by 162,000, the largest gain in five months, following an upwardly revised 21,000 in July. Labour force participation ticked up to 61.6% from 61.4%.
Here is how those figures stack up:
| Indicator | Value (August 2026) | Change from July |
|---|---|---|
| Unemployment rate | 4.1% | Unchanged |
| Nonfarm payrolls | +162,000 | Up from +21,000 (revised) |
| Labour force participation | 61.6% | Up from 61.4% |
None of that reads as distress. Reuters described job growth as having accelerated sharply while the unemployment rate held, and noted the strength kept a rate increase on the table for September.
Barkin’s own read on the economy is consistent with that picture. He described the labour market as neither overheated nor particularly constrained, a balanced assessment, and said the broader economy appears to be strengthening rather than softening.
He pointed to several drivers keeping momentum going:
- Resilient household spending
- Strength in defence
- Strength in manufacturing
- Activity beyond data centres and artificial intelligence
Barkin also assessed consumer balance sheets as not showing meaningful signs of strain, and suggested household spending is likely to hold up as long as employment conditions stay favourable.
What this tells you is that the Fed is not choosing between fighting inflation and protecting jobs in a crisis. With payrolls adding 162,000 a month and unemployment at 4.1%, it is making a proactive choice to lock in price stability while the labour market still gives it the room to do so. That resilience is the single most important variable keeping the strategy credible, and if payroll growth slows sharply or unemployment climbs, the Fed’s room narrows fast.
Labour market fragility can emerge faster than monthly unemployment figures suggest: the June 2026 payroll print came in at just 57,000 against a 114,000 consensus, accompanied by 74,000 in downward revisions to prior months, illustrating how quickly the resilient-jobs narrative can shift in the window between FOMC meetings.
The risks the Fed is accepting by prioritising inflation over employment
The Fed’s logic is coherent. It is also a bet, and it is worth being clear-eyed about what has to go right for that bet to pay off.
Three risks stand out, operating on different time horizons:
- Overtightening: If policy stays restrictive for too long, interest-sensitive sectors such as housing, durable goods, and business investment could weaken faster than the current labour data suggest, producing a gradual consumption downshift rather than a sudden break.
- Distributional impact: An inflation-first stance may secure macro stability while disproportionately hurting younger, less-educated, and minority workers, who tend to bear larger employment swings in downturns.
- Credibility versus flexibility: A rigid posture risks eroding trust if the Fed is slow to pivot once clear labour-market deterioration appears.
Each carries a different lesson for how you weigh incoming data.
What would force the Fed to change course
The near-term risk is overtightening. Economist Claudia Sahm has long warned, in commentary predating the current cycle, that tightening into a cooling labour market can push unemployment well above its natural rate, with hiring slowing faster than models anticipate once rate-sensitive sectors soften.
The longer-run risks are distributional and reputational, and they compound the longer rates stay elevated. Barkin assessed consumer balance sheets as sound now, but cumulative rate increases steadily raise debt-service burdens for variable-rate borrowers over time.
The concrete triggers that would shift the Fed’s calculus are worth watching for specifically: a meaningful and sustained rise in unemployment above the 4.1% baseline, a reversal in payroll momentum, or evidence that PCE breadth is narrowing rather than widening.
Barkin himself said the need for further tightening remains uncertain. That is the Fed’s own admission that the rate path is not on rails, and it tells you the next two or three data releases on inflation and employment carry unusual weight. Rather than treating every economic release as equally important, you can focus on the handful that would actually move the Fed.
What the Fed’s inflation-first bet requires you to watch from here
Pulling the threads together, the Fed’s posture is defensible given current data, but it is explicitly conditional. It holds only as long as the labour market stays resilient and inflation breadth remains the story, rather than inflation drifting back toward target on its own.
Three forward variables carry the most weight:
- PCE breadth: whether the share of categories running hot keeps widening or starts to narrow
- Payroll and unemployment trajectory: whether job growth holds near recent levels or momentum reverses
- Tariff and energy shocks: whether these supply-side pressures fade or deepen
The next formal decision points are the November and December 2026 FOMC meetings, and Barkin’s own words are the signal to keep in view.
The need for further monetary tightening remains uncertain.
That uncertainty is the most actionable thing he said. It means the Fed has made one move and left the next one genuinely open, operating in data-dependent mode rather than executing a script.
For you, whether you are managing a portfolio, weighing a refinance, or timing business investment, the practical implication is that the rate environment is unresolved. The data releases between now and year-end carry above-normal significance, and tracking these three variables lets you gauge the Fed’s likely direction without waiting for the next announcement to tell you what happened.
For readers wanting to stress-test the assumption that rate decisions reliably produce intended outcomes, our dedicated guide to the Fed’s actual limits examines Friedman’s long and variable lags framework and the historical episodes where Fed interventions amplified rather than resolved economic instability.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking assessments discussed here are speculative and subject to change based on economic developments and policy decisions.