ASIC has set up a new Markets Expert Advisory Group of up to about 12 members. The group will help decide which reforms come first, and those reforms could change what you pay to trade, how easily smaller listed companies change hands and how your trades settle. The regulator announced the group on 6 November 2026, following its 27 October roundtable with exchanges, banks, fund managers and super funds.
The group is consultative only. ASIC had not yet named individual members in its latest material, so for now the group’s significance lies in the agenda it inherits.
That agenda is fairly specific. The roundtable’s priorities give a useful read on where trading costs, small-cap liquidity and the basic design of Australian markets may be heading.
Why thin small-cap liquidity sits at the centre of the roundtable agenda
Anyone who has tried to sell a few thousand shares in a small miner or tech stock knows the problem. The gap between buyers and sellers is wide, and trading volume dries up quickly once you move outside the big index names.
Participants at ASIC’s second Financial Markets and Innovation Roundtable on 27 October 2026 made this a common priority. They included ASX, NSX, Susquehanna and Vanguard. Their concern was sharpest outside the largest index-included companies, and ASIC tied the problem to effects that compound one another.
ASIC’s warning: Thin liquidity outside the largest index-linked companies can reduce research coverage, weaken price formation and constrain access to capital.
Price formation is the process by which buying and selling settles on a fair market price. When it weakens, the price on screen tells you less about what a company is actually worth.
Thin order books are also behind much of the small cap volatility seen on the ASX, with sharp price swings often reflecting scarce buyers and sellers rather than any change in a company’s underlying business.
ASIC’s published material points to several causes, and most of them come down to economics:
- Market data and connectivity costs weigh more heavily on small caps, because each security earns less trading revenue.
- Market-maker economics are poor in thinly traded stocks. A market maker is a firm that continuously quotes prices to buy and sell, and in these stocks it has fewer chances to turn over inventory.
- Short-selling settings were raised as something to examine, not as a proven cause.
- Friction at handover points between systems and intermediaries adds cost.
- Concentration in the closing auction was flagged for further study.
Some of the incentive tools already exist. ASX’s market-maker scheme pays incentives to market makers who meet its requirements. Participants floated further ideas, including differentiated disclosure or trading arrangements, post-listing support, wider retail product ranges such as ETFs, and allocated market makers, where a market maker is assigned to particular securities.
Allocated market making is the overseas idea the material names. It does not nominate a preferred jurisdiction or suggest copying any model unchanged.
If you hold or trade smaller companies, the discussion points to lower access costs and better market-maker incentives as the most likely ways to narrow spreads. Nothing has been decided yet.
What faster settlement, tokenisation and longer hours could mean for your costs
The second theme is market plumbing. Settlement, the step where cash and shares actually change hands, now takes two business days (T+2). Participants discussed moving to T+1, tokenisation (recording assets as digital tokens on shared ledgers), CHESS-related issues and longer trading hours.
The T+2 settlement cycle also governs practical matters such as when sale proceeds become available and when a purchase qualifies for a declared dividend, which is why any shift to a shorter window would be felt by ordinary account holders.
ASX’s replacement for CHESS, its clearing and settlement system, is moving forward. Release 1 went live on 20 April 2026, and the later settlement phase is expected in 2029. At an ASX workshop on 14 October 2026, T+1 was described as the near-term target. Financial Standard reported on 28 October that the runway could stretch to around 2030.
The catch is that faster settlement does not remove costs. It moves them earlier in the process.
| Reform | Potential benefit | Main caveat | Latest status |
|---|---|---|---|
| T+1 settlement | Shorter exposure to counterparty and market risk | Compresses funding, FX and confirmation timelines | Medium-term target, not implemented |
| Tokenisation | Less friction, better collateral management | Could fragment liquidity across venues | Project Acacia tested 20 wholesale use cases; not yet at scale |
| Longer trading hours | Better access for overseas investors | Thinner liquidity and wider spreads in extra hours | Under discussion |
The overseas evidence shows the trade-off. A European Commission analysis found preliminary evidence that the gap between US and EU settlement cycles raised costs for EU fund managers, particularly ETFs holding US securities. Investor Daily reported that overdrafts and tighter cut-offs for Australians trading US shares can push costs up.
If you buy US shares or ETFs, that mismatch is already a cost issue. The direction of Australian settlement policy affects your costs well before any local change arrives.
Participants also set conditions. Any new model should tackle real, demonstrated problems while avoiding liquidity fragmentation, damage to netting (offsetting trades so fewer payments move) and fresh concentration risks. Tokenisation, the ASX workshop noted, does not require T+1 or atomic settlement, where cash and assets swap instantly.
What changes for retail investors
Investors who are less at ease with digital services could be affected if paper CHESS holding statements are phased out. Shorter settlement windows may cause confusion about settlement dates and funding obligations. Longer hours could also expose less experienced traders to low-liquidity periods. ASIC linked all of these changes to coordinated rollout and investor education.
How the Markets Expert Advisory Group fits into a wider reform pipeline
Against that backdrop, the advisory group’s remit is deliberately modest:
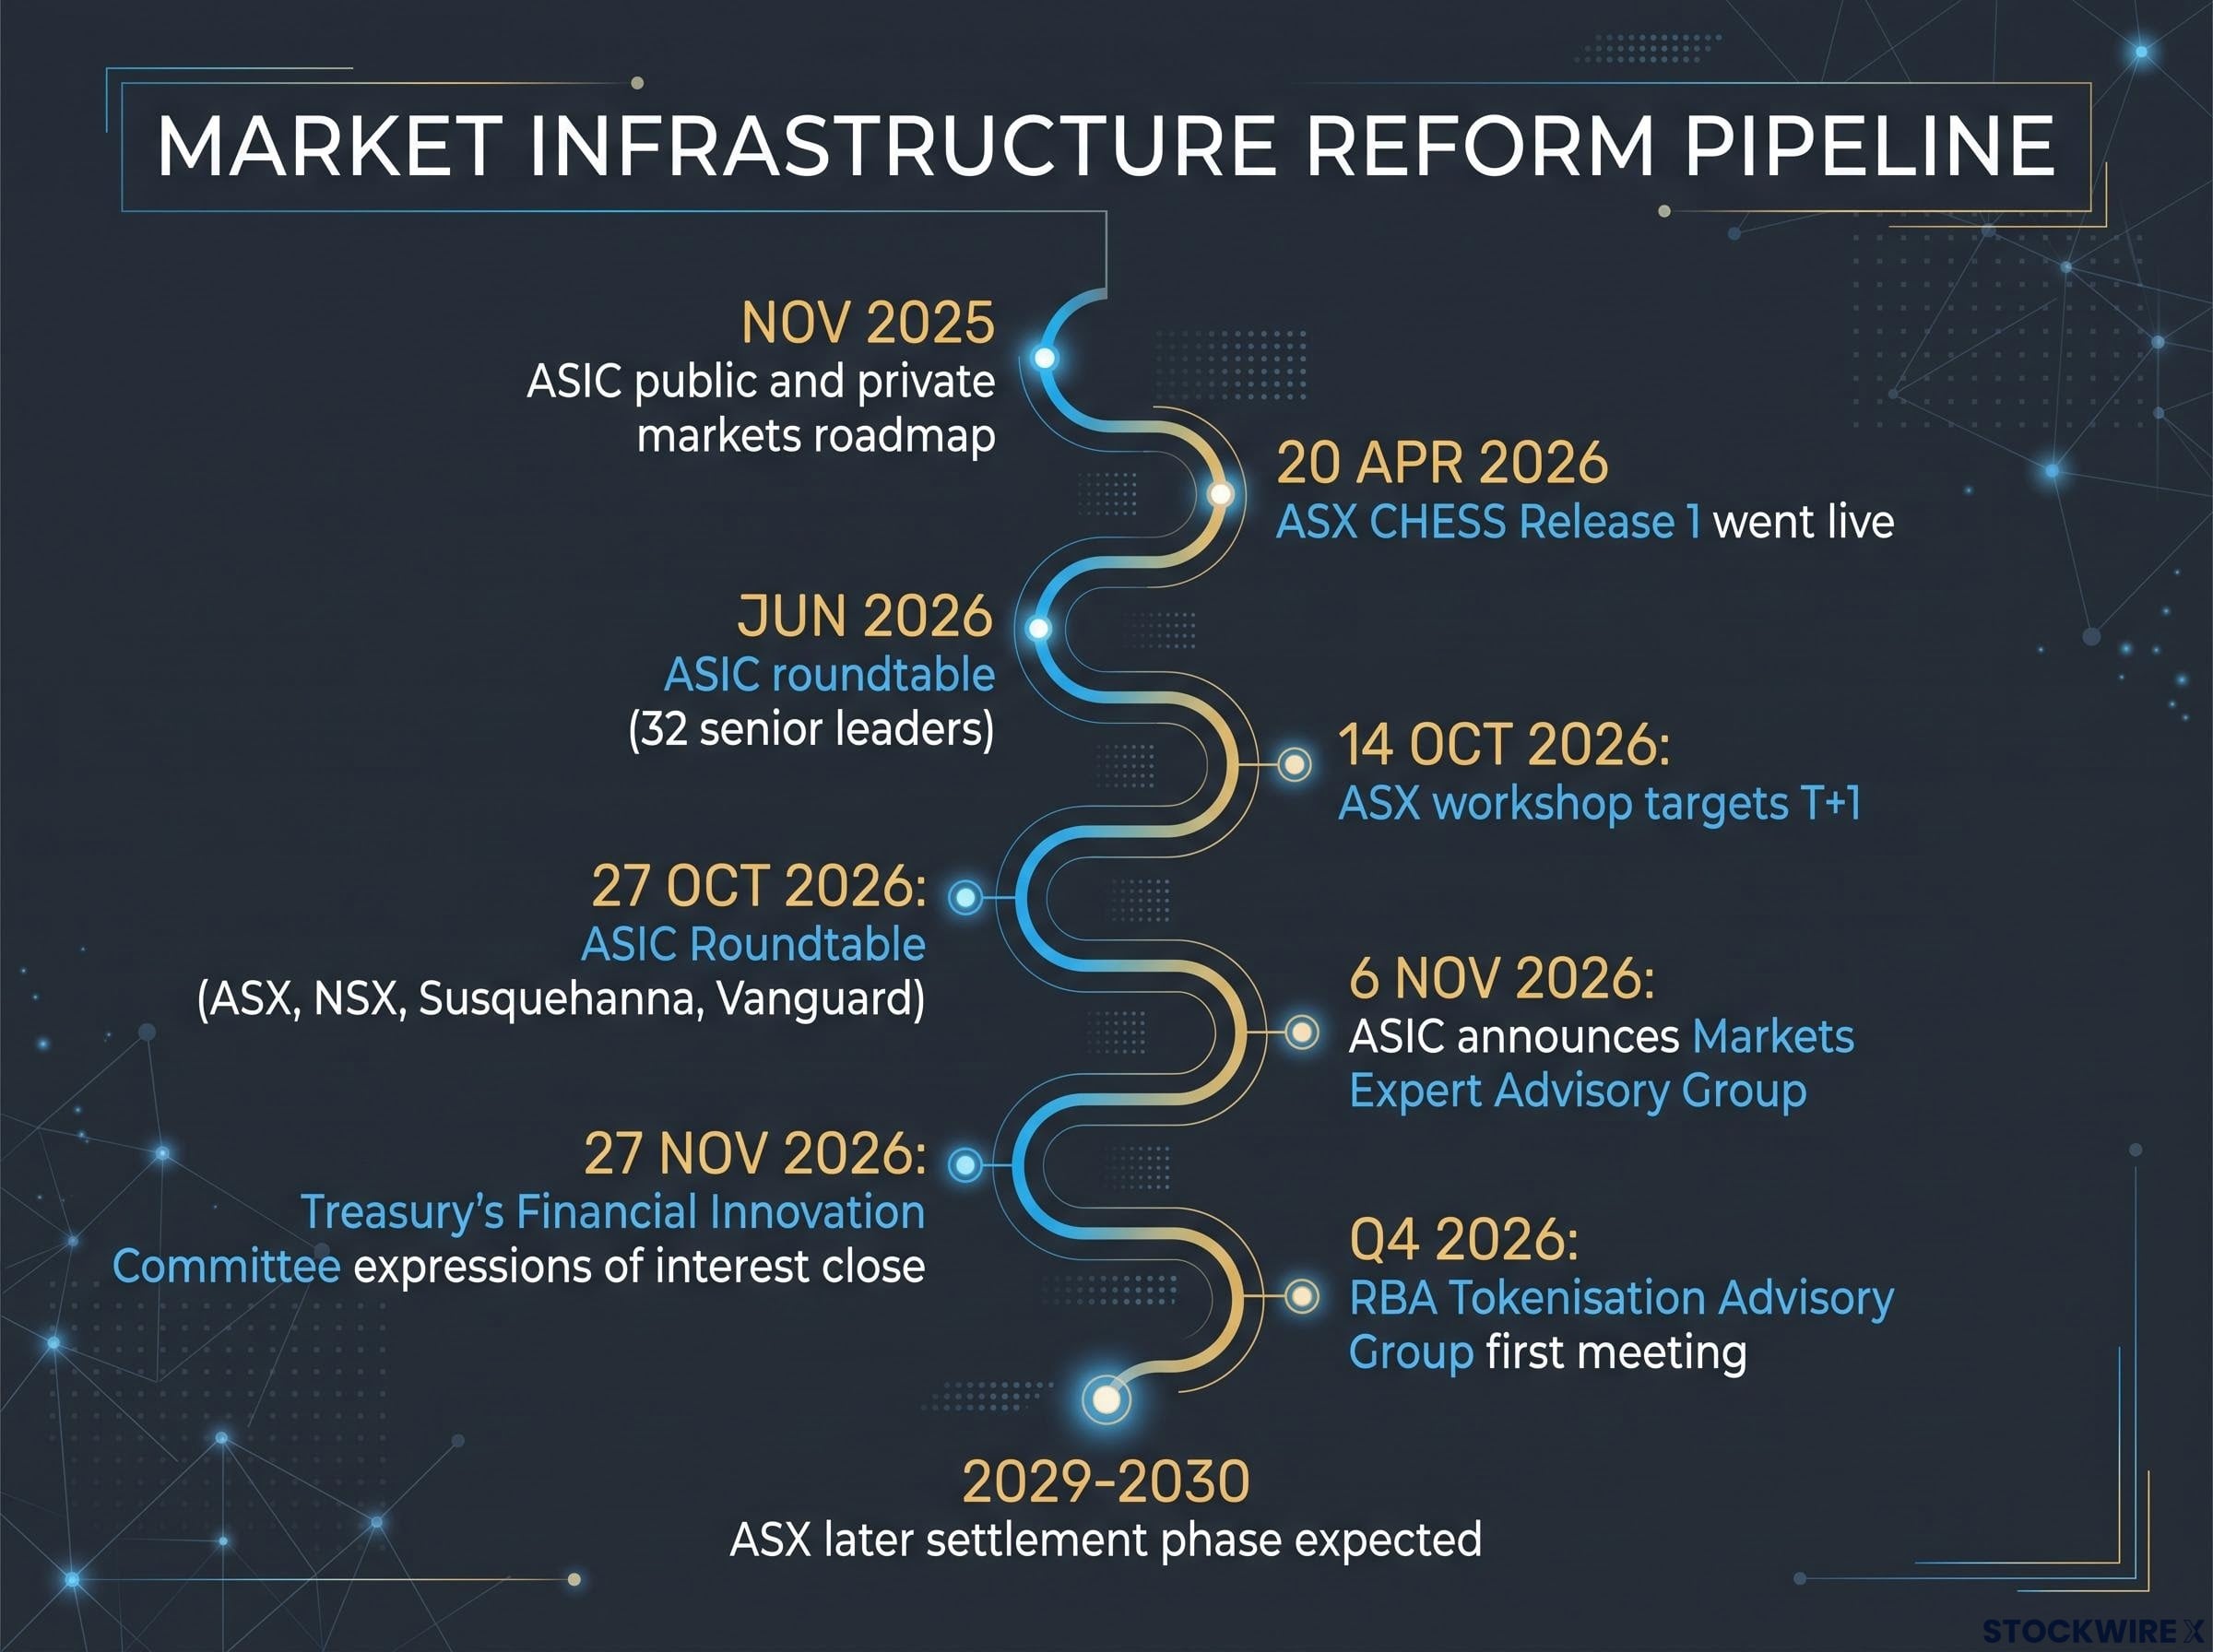
The market infrastructure reform timeline spans from late 2025 through to the expected 2029-2030 ASX settlement phase.
- Size: up to about 12 members, appointed in their personal capacities
- Chair: ASIC Commissioner Simone Constant
- Cadence: meets roughly every two months; time-limited
- Authority: consultative only, with decisions staying with ASIC
- Publication: ASIC has promised updates, but has published no fixed timetable for releasing the group’s advice or minutes
The strategic driver is scale. AustralianSuper put superannuation at about $4.8 trillion in October 2026, and ASFA reports 2035 estimates ranging from $6.1 trillion to $8.5 trillion. ASIC’s own release cited different figures, so treat these projections as estimates. Constant also highlighted how widely Australians invest, noting that one in two hold assets beyond their super or home, and warned of threats including cyber attacks, AI and uncertain credit conditions.
The group builds on earlier work. ASIC released a public and private markets roadmap in November 2025, and its June 2026 roundtable brought together 32 senior leaders. In October, participants asked for a market infrastructure roadmap that sets out reforms and their implementation requirements in one place.
The advisory group sits inside a broader four-stage reform programme that sequences digital-money experimentation, infrastructure accountability and enforcement recalibration, with execution on committed milestones by 2027 the key test.
The group also sits alongside other bodies doing related work:
- Treasury’s Financial Innovation Committee: expressions of interest close 27 November 2026
- RBA Tokenisation Advisory Group: about 20 participants planned, first meeting in Q4 2026
Rules will not be made in this room. Its value lies in sequencing, which means the member list, first meeting outcomes and any roadmap will show which reforms move first.
Four signals to watch as the advisory group takes shape
The roundtable’s priorities point in three directions: lower access costs for smaller companies, careful sequencing of settlement and tokenisation reforms, and closer coordination between regulators and industry. Four markers will show how quickly any of this moves:
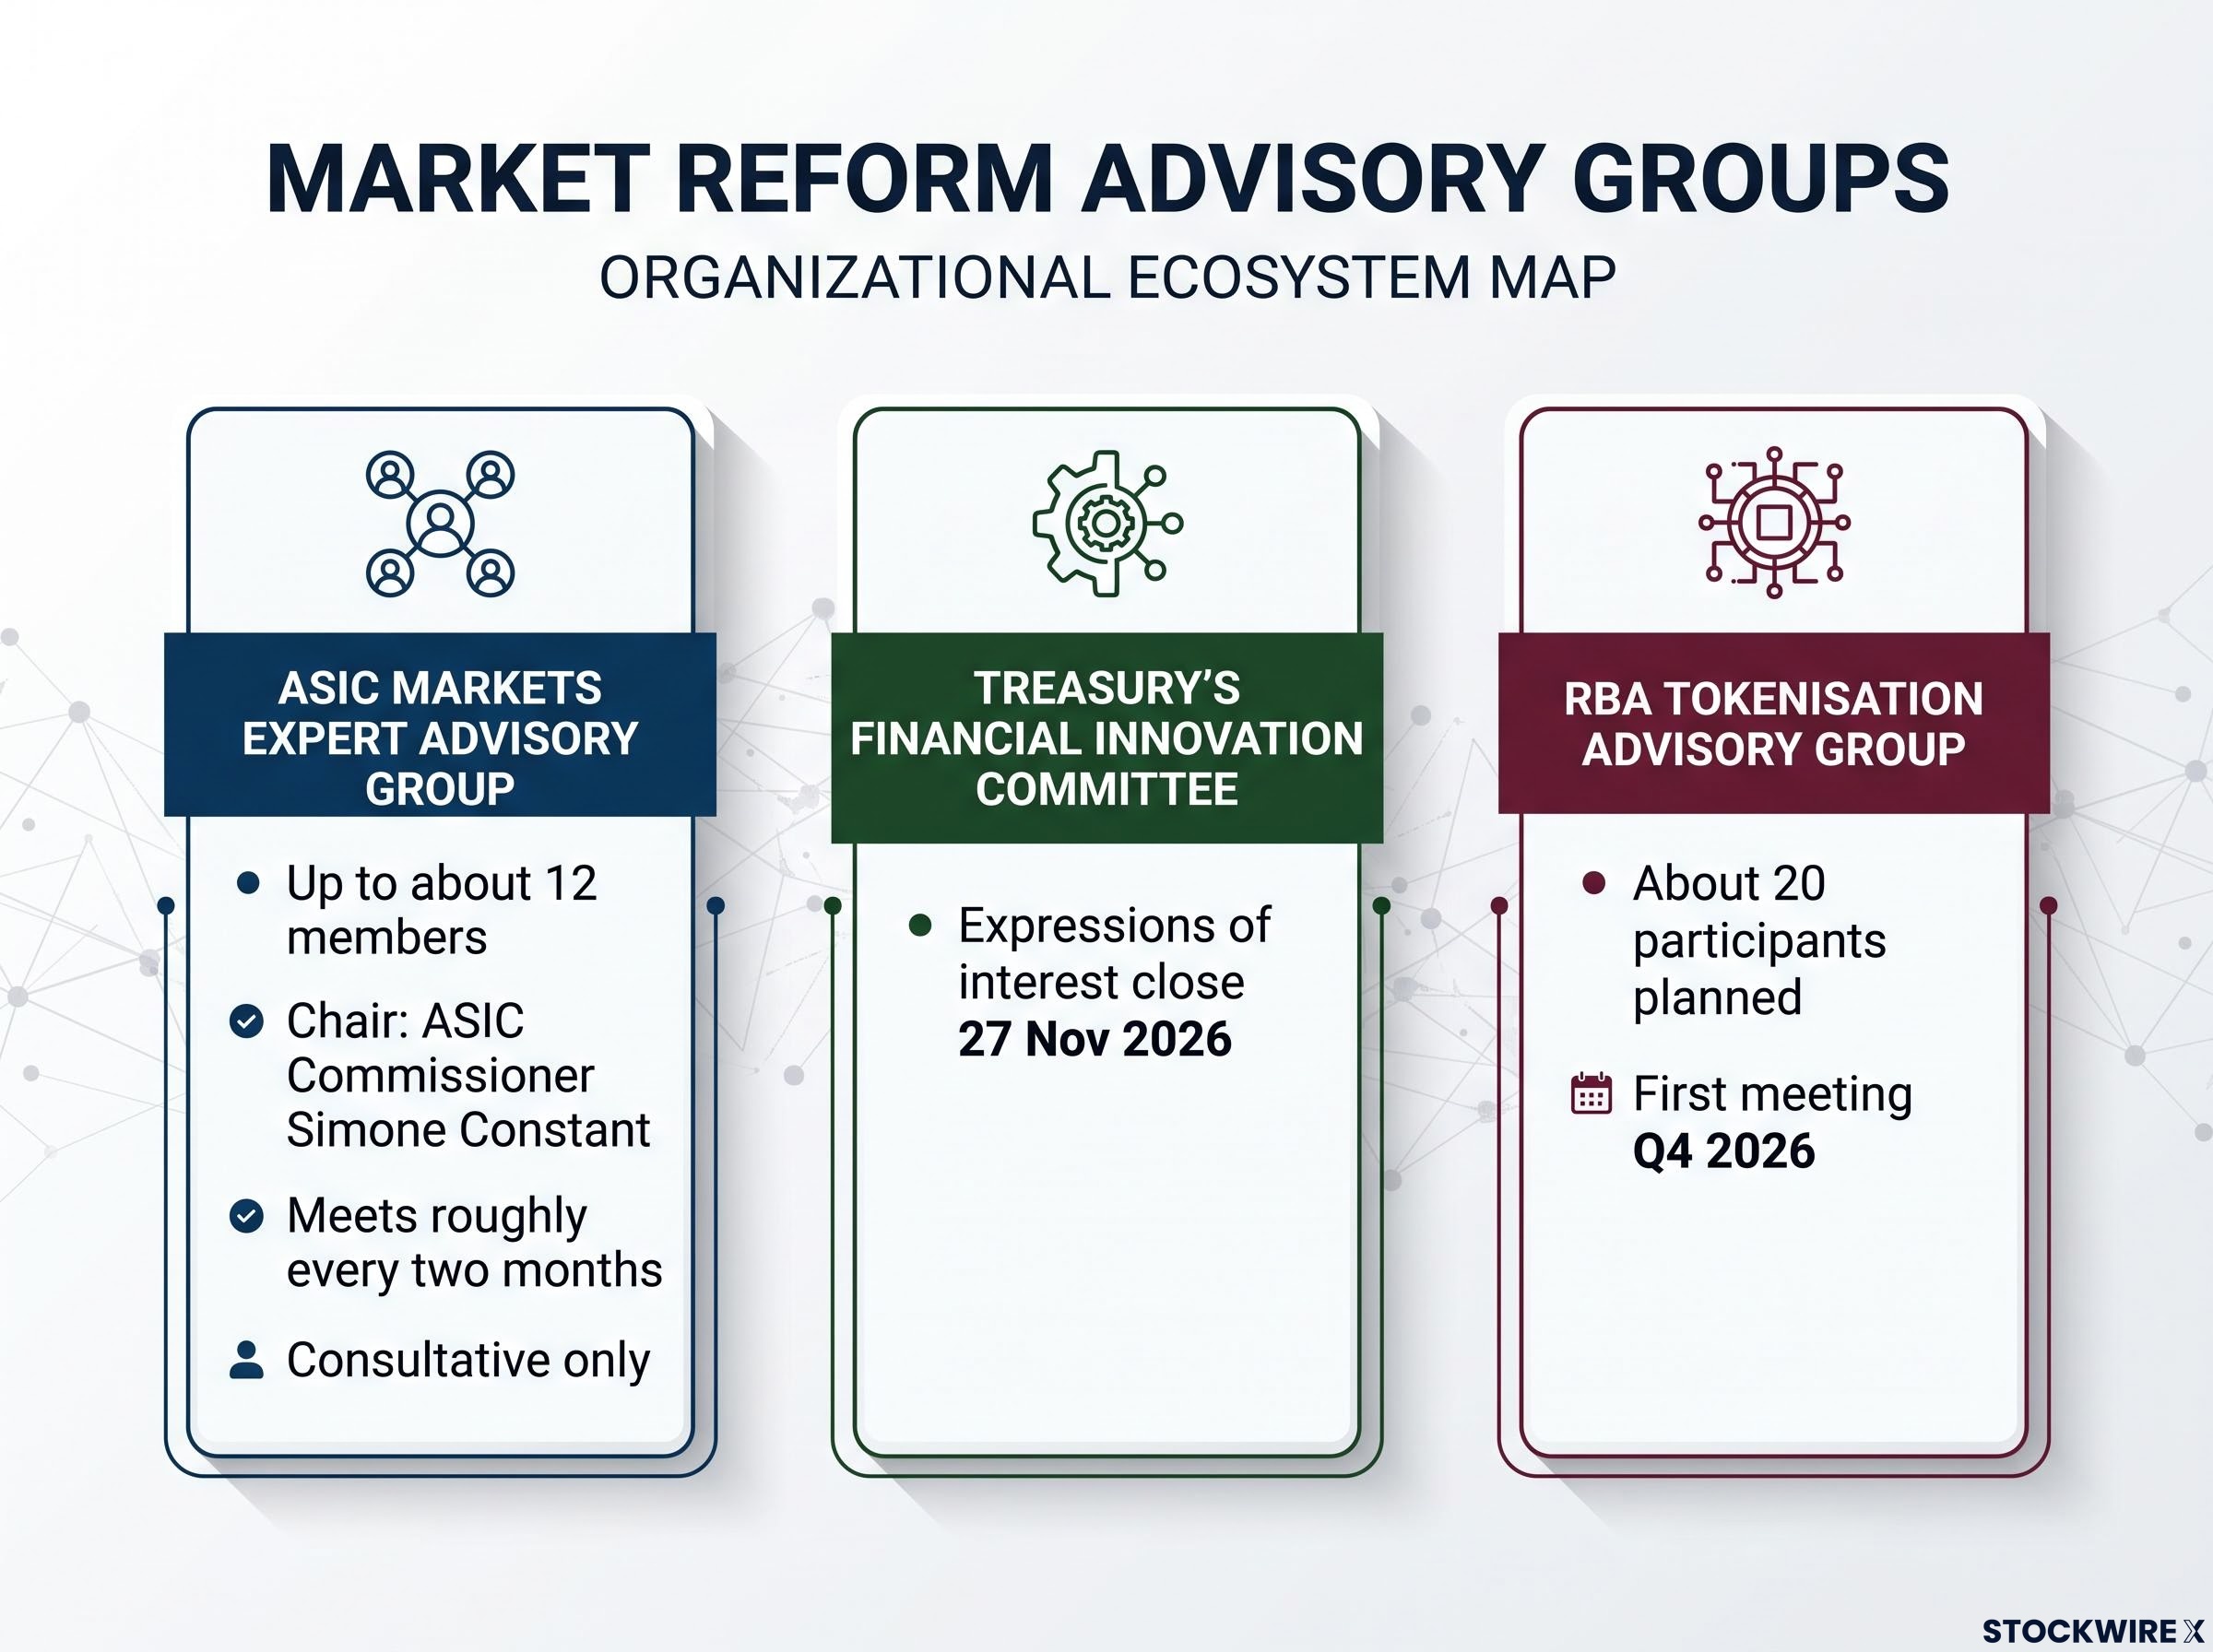
The ecosystem features the ASIC advisory group of up to about 12 members and the RBA group of about 20 participants alongside the Treasury Committee.
- Member appointments: who sits at the table shapes which issues get airtime.
- The first meeting: watch for any published update from ASIC.
- A market infrastructure roadmap: this would set out timing and sequencing.
- Financial Innovation Committee membership: expected after expressions of interest close on 27 November 2026.
Together, these signals will show whether lower trading costs and deeper small-cap liquidity are moving from roundtable talking points towards practical change.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.