In 1999, buying shares of Cisco Systems felt like buying the future itself. The company dominated the plumbing of the internet, its revenue and earnings climbed for the next two decades, and yet investors who bought at the peak spent years, in real terms, waiting just to break even.
The business was never the problem. The price was.
Here is the tension this piece resolves: business quality and investment quality are two separate decisions, and investors routinely treat them as one. The damage from overpaying is not revealed when a stock disappoints years later; it is locked in the moment you hit buy. That same pattern repeats across fast-casual restaurant stocks, legacy consumer brands, and commodity memory businesses that look unstoppable right before they turn.
This gives you a concrete way to judge whether a stock’s price already assumes everything goes right. You will work through three live case studies with real numbers, and you will leave with a reusable mental model, not three stock tips. The goal is to change the question you ask before you buy.
Why paying too much for a great business still destroys returns
Go back to the peak of the dot-com boom. Cisco Systems traded at astronomical multiples during 1999-2000, flagged at the time by investors like Jeremy Grantham of GMO as a textbook case of a wonderful company at an impossible price. The business survived and thrived. Peak buyers still endured decades of disappointing returns, because the earnings simply could not grow fast enough to justify what they had paid.
The mechanism here is not exotic. The price you pay sets your required rate of return, and a price that already embeds flawless execution leaves you no room when reality falls short.
Put a number on it. Pay 100 times earnings for a company growing profits at 20% a year, and you are waiting roughly six years just for the earnings to catch up to your purchase price. If that growth disappoints even slightly, you never get there.
Warren Buffett learned a version of this himself. He has acknowledged that buying Coca-Cola at elevated valuations in the late 1990s was a mistake; the brand stayed dominant, but slower subsequent growth capped his returns for years.
This is why intrinsic value is best thought of as a range, not a single figure. A low case, a mid case, and a high case. The current price needs to sit low enough in that range that something can go wrong and you still do acceptably.
Intrinsic value estimation is not a single calculation but a range of plausible outcomes, and the terminal value assumption alone typically drives 60-80% of any discounted cash flow model’s total implied worth, making it the variable most worth stress-testing before you commit capital.
The “good company, bad investment” problem Howard Marks of Oaktree Capital frames it bluntly: a good company becomes a bad investment the moment the price ignores the gap between what the business is worth and what the market is charging for it. Price discipline, not admiration, is what protects your return.
When a price embeds perfection, overpaying hurts you through three distinct channels:
- Multiple compression: the market re-rates the stock lower even as the business performs, shrinking your return.
- Earnings disappointment: growth comes in below the optimistic path baked into the price.
- Time-value drag: you wait years for earnings to grow into the valuation, earning nothing while you wait.
The shift this section asks of you is small but decisive. Stop asking “is this a good company?” Start asking “does this price make sense given what could realistically happen?” Every case study that follows is a test of that second question.
When big ASX news breaks, our subscribers know first
Cava Group: when the business is real but the math is not
Give Cava Group full credit first, because it earns it. This is not a hype story propped up by price hikes. Customer traffic rose by more than 5%, which drove revenue growth of roughly 31%. Traffic-led growth is the healthier kind: real people walking in more often, not the same customers paying more.
The scale is real too. Cava operated 476 restaurants averaging around $3 million in annual sales each, with a plan to more than double its footprint to over 1,000 locations by 2032, pushing into Midwestern markets.
So the operation is genuine. The trouble starts when you ask what price that operation is trading at.
What the valuation math actually requires
Restaurant-level profit margins have already slipped to approximately 26% under food and labour cost pressure. That matters, because the stock’s valuation assumes those margins hold or improve while the chain doubles in size.
Here is the model from the original Everything Money analysis. It runs three scenarios across revenue growth and margin assumptions.
| Scenario | Assumptions | Intrinsic value |
|---|---|---|
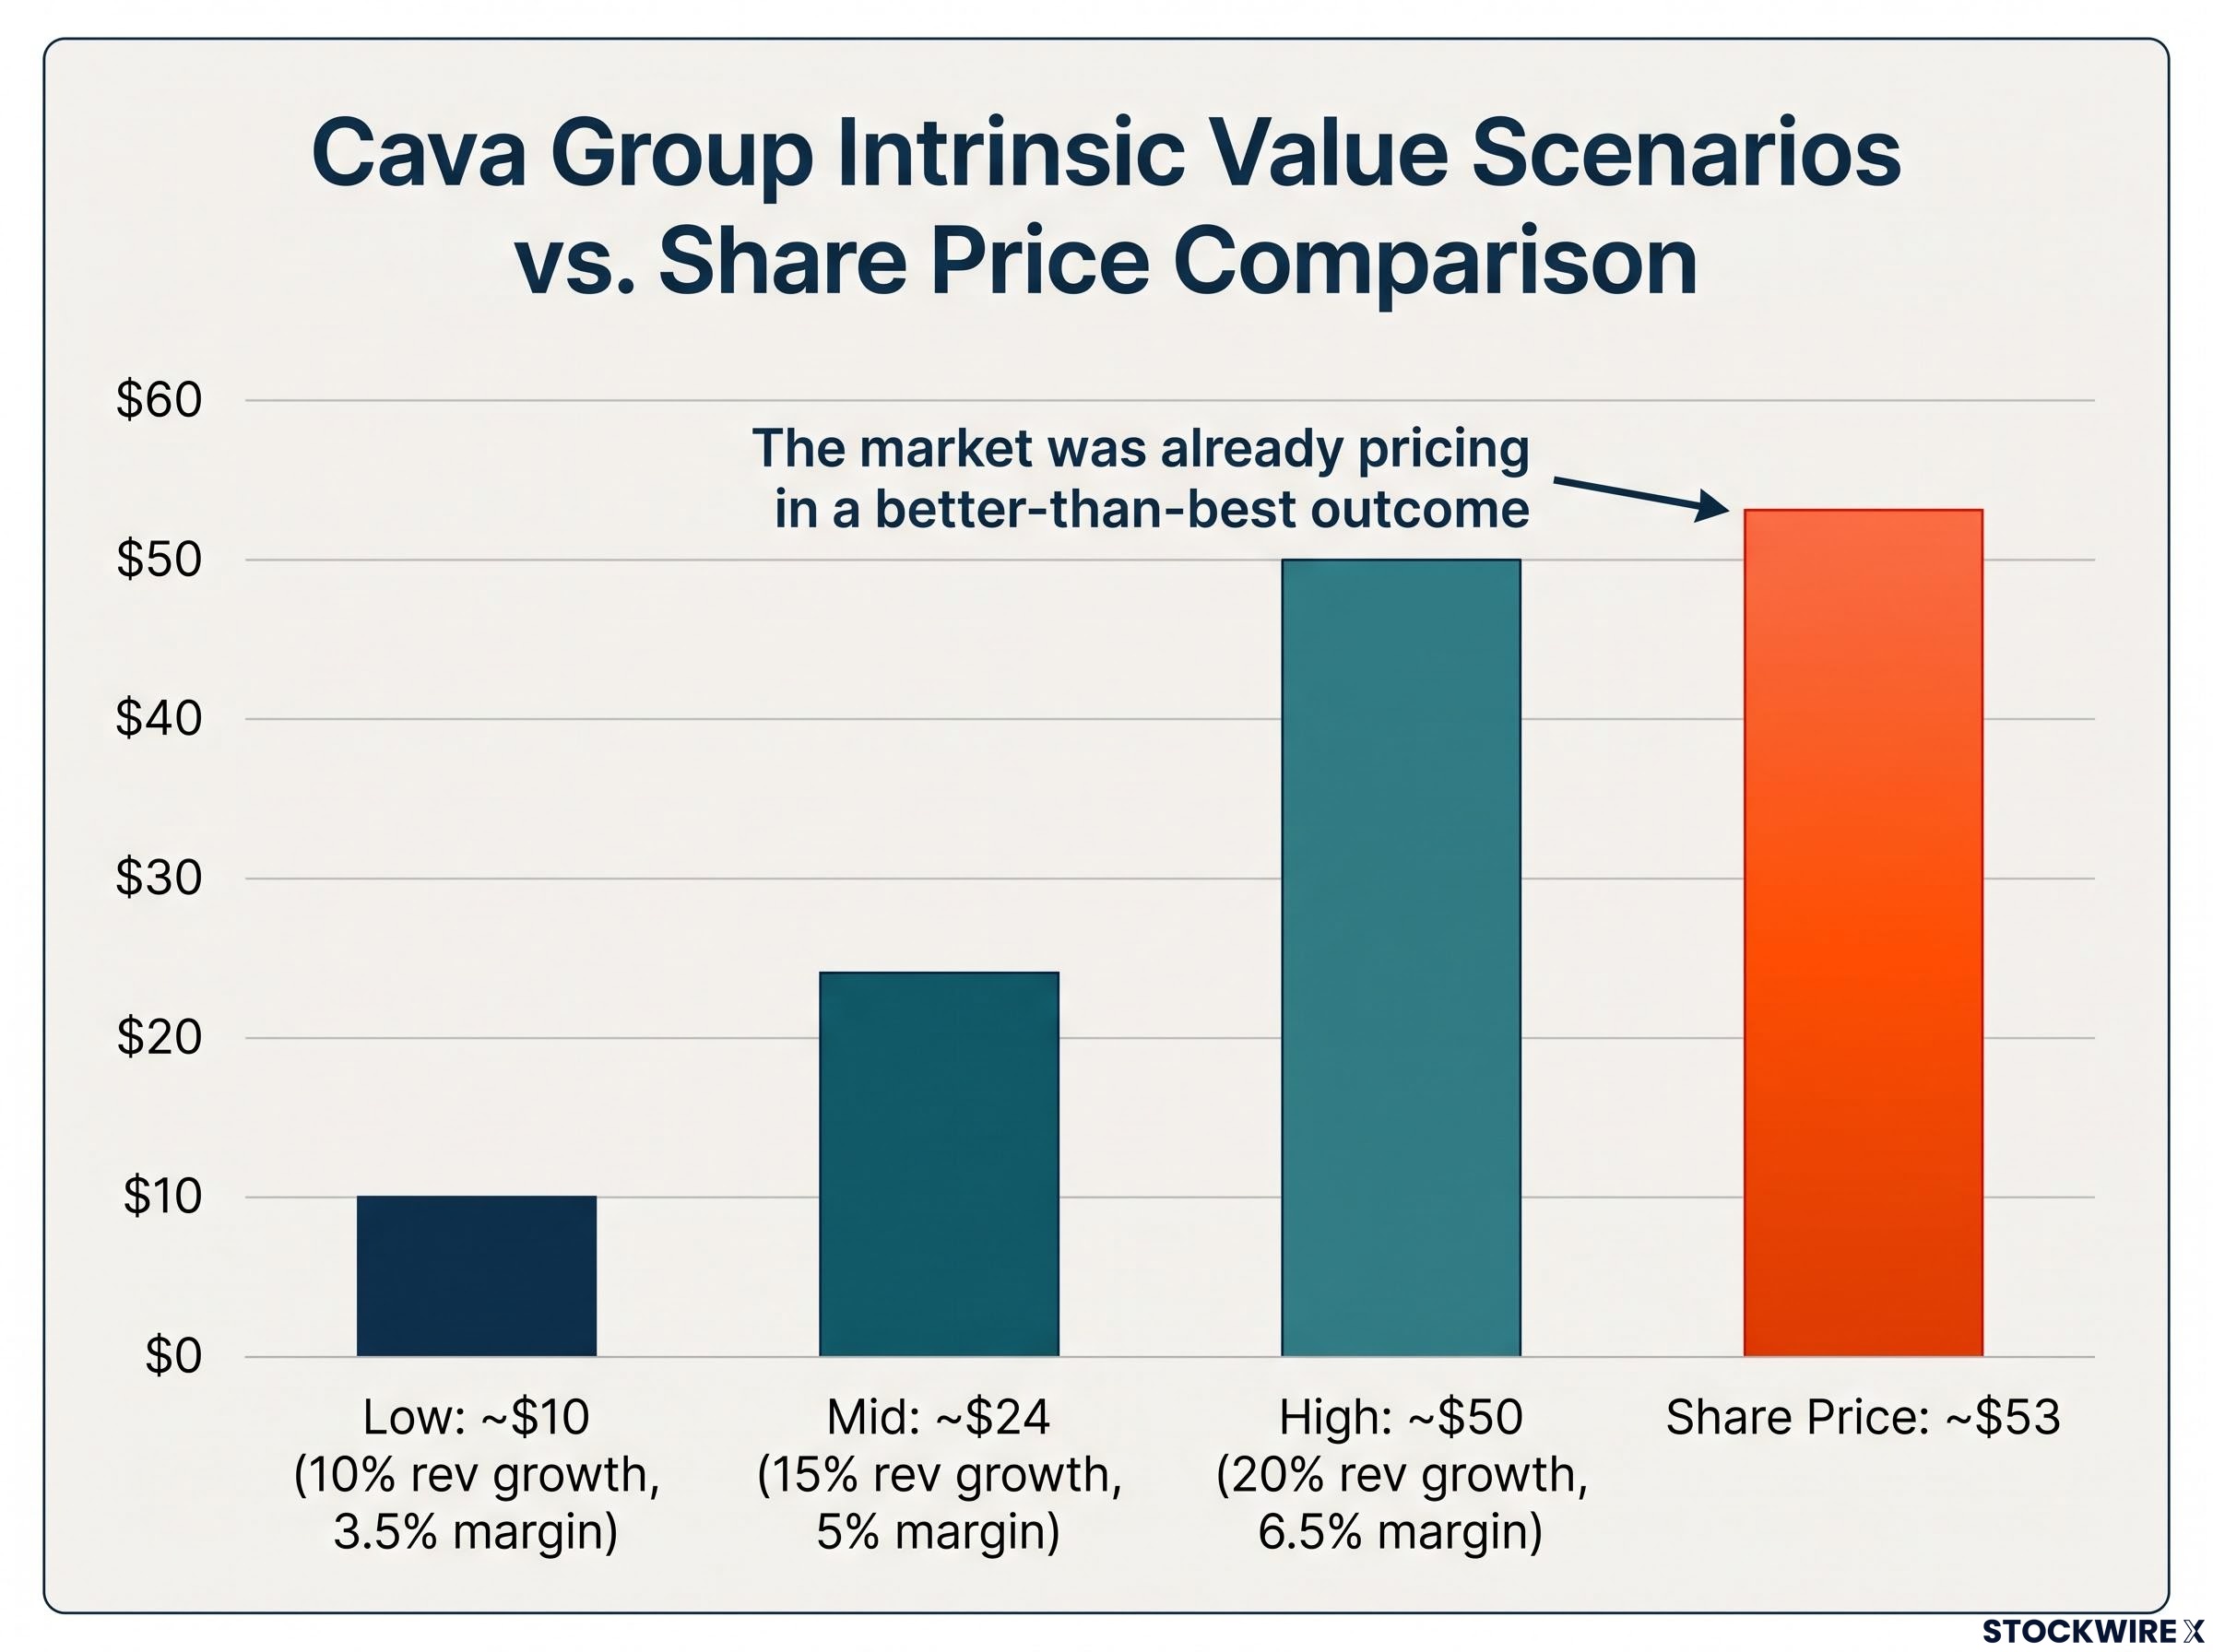
| Low | 10% revenue growth, 3.5% margin | ~$10 |
| Mid | 15% revenue growth, 5% margin | ~$24 |
| High | 20% revenue growth, 6.5% margin | ~$50 |
The gap that matters High-case intrinsic value: approximately $50. Share price at the time of analysis: approximately $53. The market was already pricing in a better-than-best outcome.
Sit with that. The price does not simply assume Cava succeeds. It assumes Cava succeeds faster and more profitably than almost any restaurant chain in history, with no cushion if margins stay compressed or the expansion runs slow.
Then there is the cash problem momentum buyers tend to skip past. Over the prior five years, Cava’s cumulative free cash flow was negative, and shareholder dilution ran to roughly 22% through new share issuance. That dilution is a direct cost: each existing share now represents a shrinking slice of whatever future earnings arrive.
The multiples compound the discomfort. The original analysis put the stock at roughly 130 times free cash flow and 95 times earnings. More recent figures (Perplexity-sourced and not independently confirmed) show a trailing price-to-earnings ratio near 97x and a trailing price-to-free-cash-flow figure around 344x. On valuation grounds, Morningstar issued a sell recommendation.
Cava may well succeed. The point is that the price already gives you full credit for it. That is how momentum manufactures FOMO, and FOMO is how you end up paying for a scenario that has almost no room to disappoint.
Recency bias is the cognitive shortcut that makes momentum feel like evidence: ARKK attracted nearly US$28 billion in assets after a 150% return in 2020, just before the fund fell roughly 81% over 22 months, a pattern that repeats whenever strong recent performance is treated as confirmation of durable quality rather than a signal to check what price already assumes.
Darden Restaurants: the danger of paying fair value at the wrong moment
Overpaying does not always wear a stretched multiple. Sometimes it looks like buying a solid business at “roughly fair value” at precisely the wrong moment in its cycle.
Darden Restaurants has a genuine operational moat. Its scale in food procurement, advertising, and technology is something smaller rivals cannot match, and Olive Garden alone generates over $5 billion in annual revenue. This is a steady, dividend-paying cash machine.
But full-service dining is one of the first things households cut when money gets tight, and that cyclicality is the whole problem.
Three structural headwinds sit underneath the steady surface:
- Consumer discretionary cyclicality: sit-down dining is a classic early casualty of a spending slowdown.
- Upscale segment deceleration: comparable sales growth across the premium brands slowed to roughly 1%.
- COVID-19 recovery maths: prior five-year revenue growth figures were flattered by rebound from pandemic disruption, overstating the underlying trend.
The portfolio tells the story in its own numbers. LongHorn Steakhouse posted comparable sales up 9.5%, while the upscale segment crawled at about 1%. That spread is the uneven reality hiding inside a headline sales figure that was also temporarily boosted by a calendar week shift.
Now the valuation. Darden carried a market capitalisation of roughly $23 billion and an enterprise value near $33 billion, implying about $10 billion in net debt. Returns on capital averaged roughly 12% over five years and 13.5% over ten, with net profit margins around 9%. These are good, stable numbers.
The intrinsic value model produced a range of $150 (low), $200 (mid), and $280 (high), against a share price of about $200. The stock sat squarely at the midpoint, trading at roughly 18-20 times earnings.
Fair value is not a margin of safety Paying the midpoint of an intrinsic value range means you are buying the median outcome. The upside requires everything to go right, and the downside hits immediately if consumer spending softens.
A margin of safety calibrated to business quality, requiring a 30% discount for high-moat predictable businesses and 40-50% for cyclical or leveraged firms, is what converts a theoretically fair price into one that absorbs bad news before it arrives.
For you, that is the trap. “Roughly fair value” is not a safe entry point for a business tied to consumer cyclicality. You are paying for the median result, which delivers median returns, and any deterioration drops you below the value you paid.
There is a cash-flow pressure point too. Darden’s dividend consumes real resources: roughly $700 million a year in payouts against about $1.1 billion in annual free cash flow, so more than half the cash is committed before reinvestment. Darden proves the overpayment problem is not confined to momentum darlings. Even a steady cash generator can trap your capital when you buy on the assumption that a cyclical category will stay stable.
SanDisk and the commodity trap: extraordinary margins that history says cannot last
Start with the numbers that make SanDisk look transformed. Revenue up roughly 372% year-over-year. Gross margins expanding from around 26% to approximately 84%. Net margins of about 56%, against a ten-year average of 21%. Return on capital at 44.5%, and free cash flow surging to $11.5 billion versus a five-year average near $2.5 billion.
On the surface, this looks like a business that permanently changed gear. The mechanics underneath say otherwise.
Reading the signals that the cycle is turning
SanDisk, now a standalone flash memory business separated from Western Digital, is a commodity operation. It sells NAND flash, undifferentiated memory where producers compete on cost per bit. The margin spike came from an AI-driven demand surge colliding with constrained supply.
Here is the tell. Roughly two-thirds of the revenue growth came from price increases rather than volume. When price, not volume, drives the gains, you are not watching a durable competitive advantage. You are watching a cycle peak.
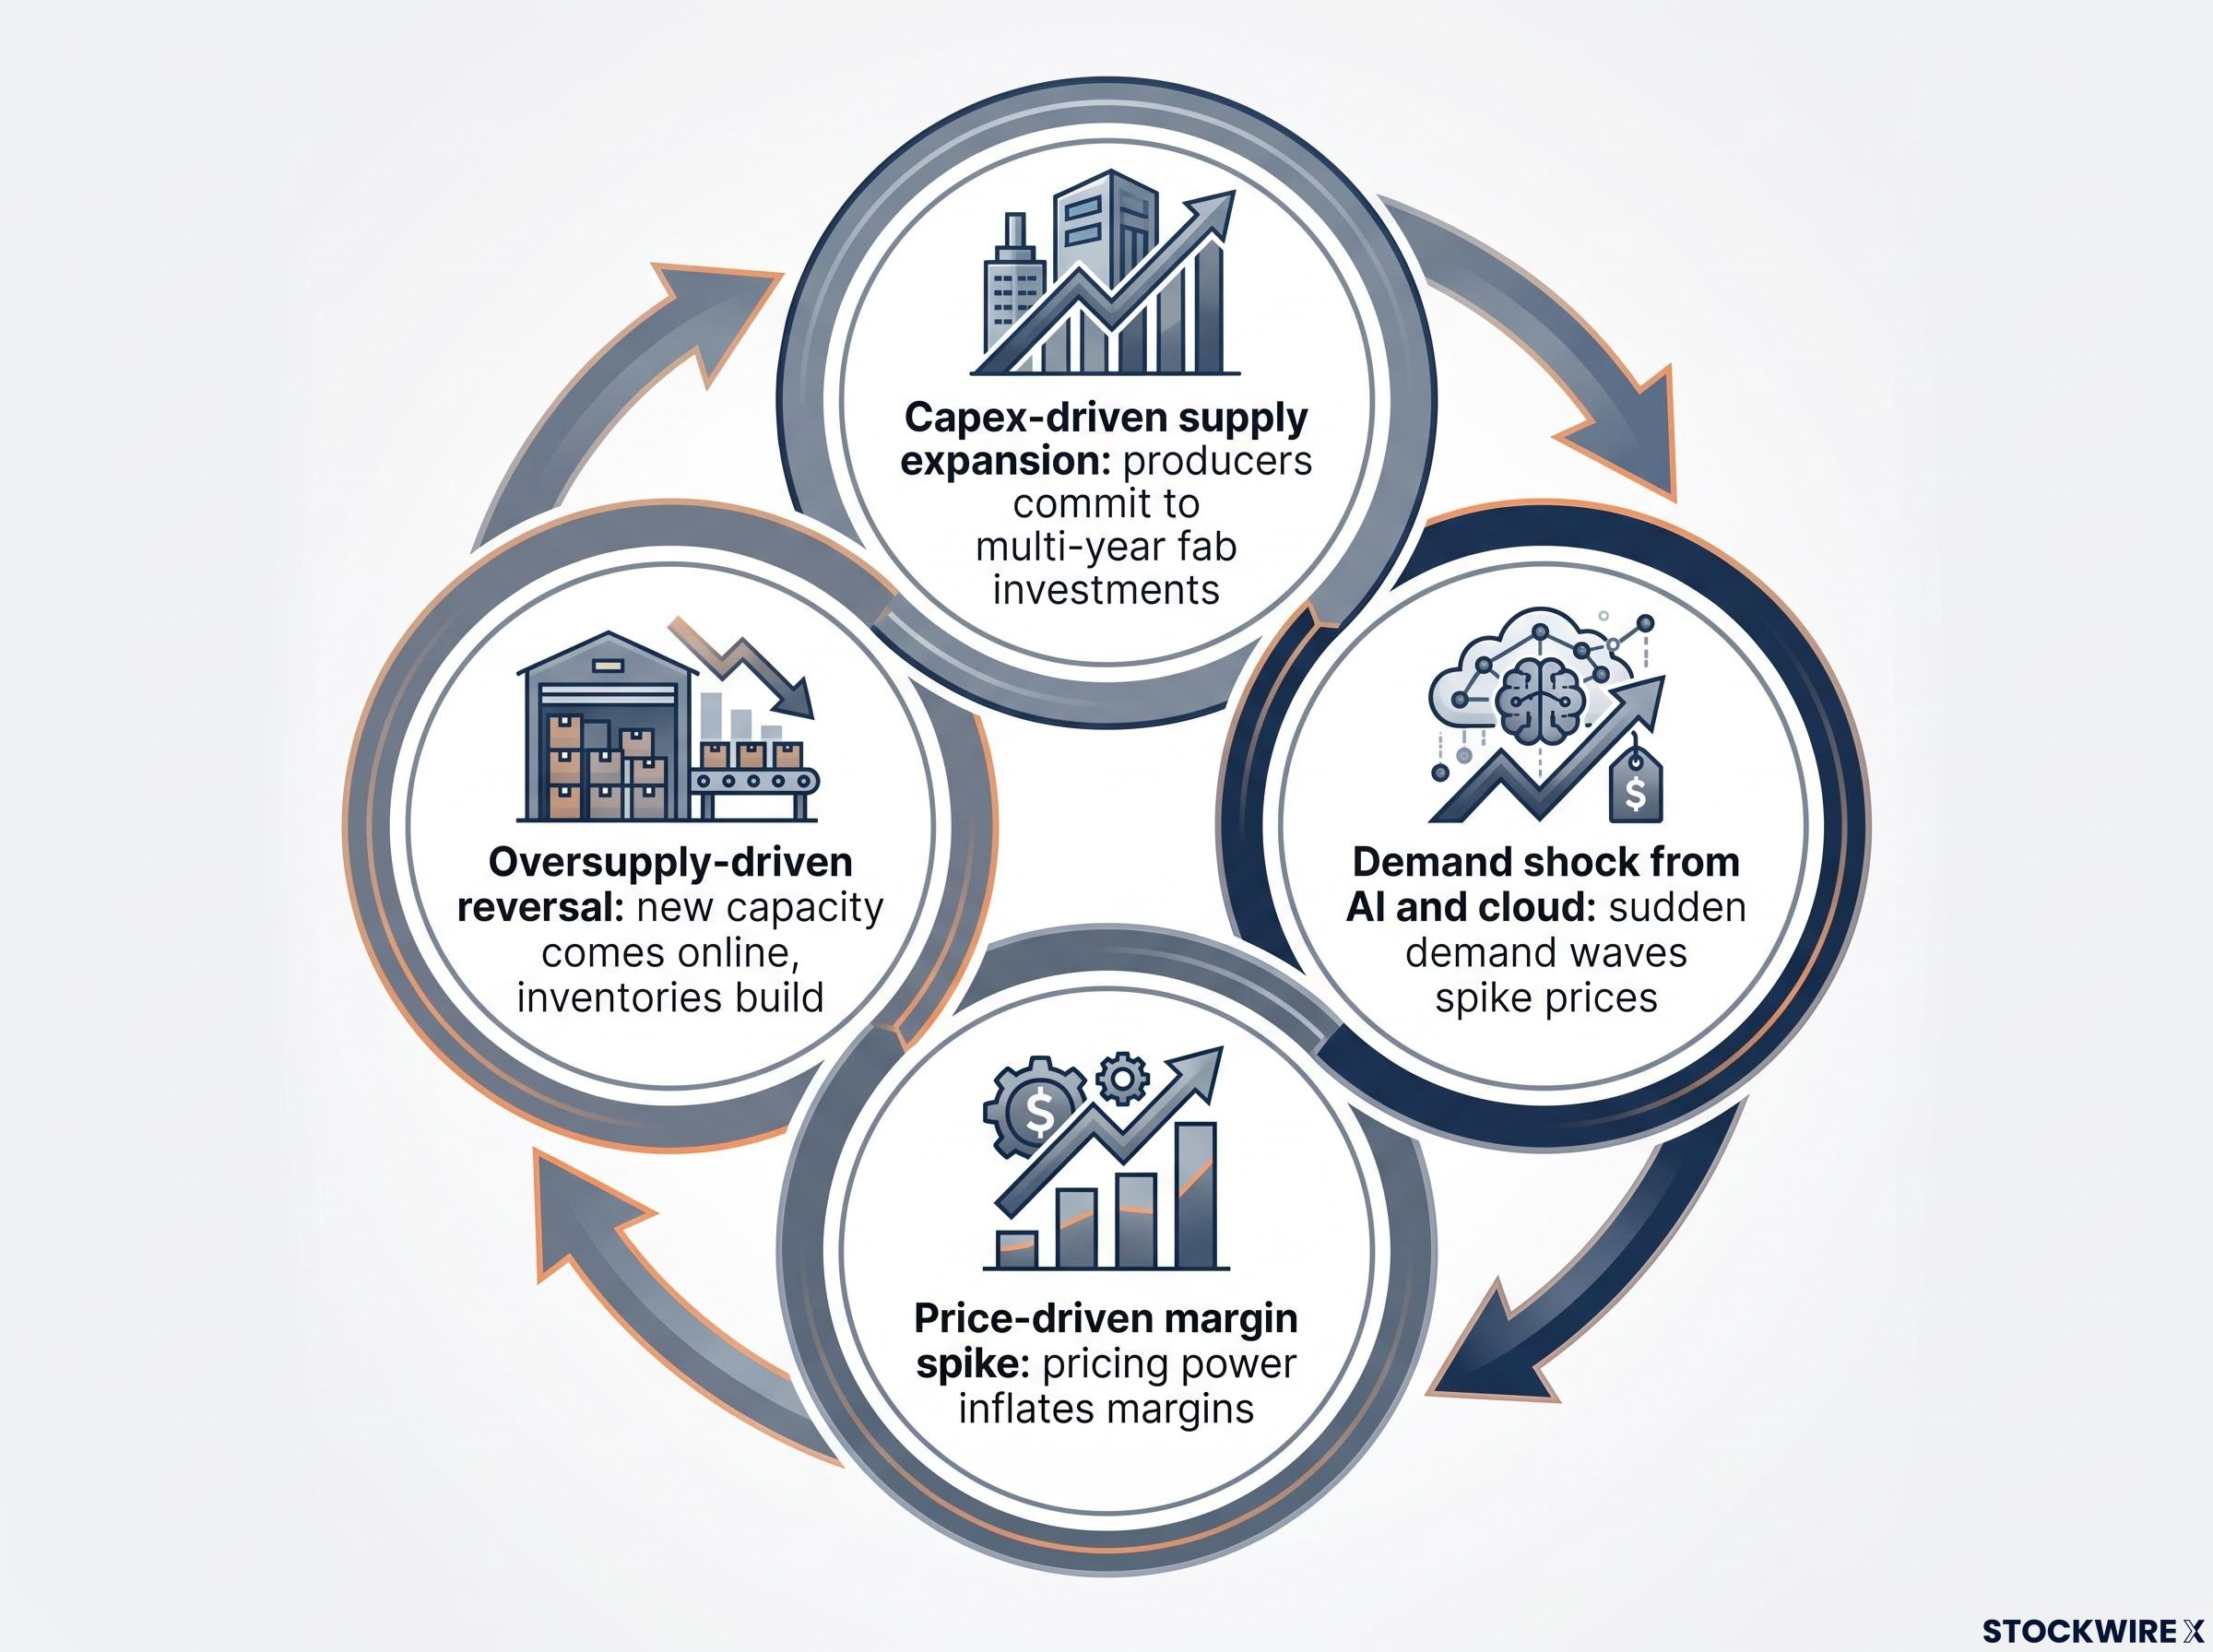
NAND memory moves through four repeatable phases:
- Capex-driven supply expansion: producers commit to multi-year fab investments, locking in capacity that arrives years later.
- Demand shock from AI and cloud: sudden demand waves absorb supply and spike prices.
- Price-driven margin spike: with supply tight, pricing power inflates margins far above the long-run average.
- Oversupply-driven reversal: new capacity comes online, inventories build, and marginal-cost pricing drags margins back down.
The valuation reflected exactly this uncertainty. SanDisk carried a market capitalisation near $281 billion, with analyst earnings-per-share estimates rising from roughly $212 to $450. At a 20 times multiple, that implied a share price near $9,100 against a then-current price around $1,800.
Pricing a commodity cycle is guesswork The intrinsic value model spanned $170 to $5,400, a range so wide it tells you the honest answer is that nobody can value a cycle-peak commodity business with confidence.
The reversal signs are already visible, and analysts watch four of them: shifting capex plans among NAND producers, inventory normalisation, average selling price stabilisation, and bit-shipment growth relative to end-market demand.
Perplexity-sourced data (not independently confirmed) shows Western Digital’s flash gross margin at 32.5%, down 6.4 percentage points sequentially on pricing pressure, with management describing the industry as being in a “mid-cycle pause” caused by NAND oversupply. The consumer segment had already contracted about 32% in the most recent quarter at the time of the original analysis.
The lesson for you is precise. When roughly two-thirds of a company’s growth comes from price rather than volume, you are not buying a business advantage. You are renting a position in a commodity cycle, and commodity cycles always turn. The numbers look most transformational at the exact moment they are most vulnerable to reversal.
For readers wanting to understand why commodity cycles produce such dramatic and temporary margin spikes, our full explainer on commodity cycle dynamics covers the supply-lag mechanics, demand shock patterns, and historical duration of prior episodes that define how long peak margins can persist before reverting.
Applying scenario thinking before you buy
Three case studies, three distinct ways to overpay. Cava is momentum and FOMO: paying above the high case for a real but priced-for-perfection growth story. Darden is false safety at fair value: buying the median outcome in a cyclical category. SanDisk is cycle-peak confusion: mistaking a commodity price spike for a durable margin improvement.
The corrective for all three is the same discipline: scenario-based valuation. Rather than guessing a single target price, you build a range and then check where today’s price sits inside it.
Here is the five-step process:
- Estimate low, mid, and high revenue growth rates for the business.
- Assign a profit and free cash flow margin to each scenario.
- Apply an appropriate exit multiple for each case.
- Discount those outcomes back to today at your required rate of return.
- Compare all three results to the current price.
Cava is the clean worked example. The model produced $10, $24, and $50 across its three scenarios, and the price sat at roughly $53, above even the high case. That single comparison tells you the market was pricing in an outcome better than the most optimistic projection.
The margin of safety test Howard Marks’ principle applies directly: if the current price sits at or above your high-case intrinsic value, you are paying for everything to go right. That is rarely a bet worth making.
There is a serious counter-argument, and it deserves respect. Warren Buffett, Charlie Munger, and Terry Smith of Fundsmith have all argued for paying a fair or even premium price for durable compounders, on the logic that quality pays for itself over time. Even they acknowledge the catch: when growth slows, multiple compression punishes you regardless of business quality. Cisco, Coca-Cola, and Walmart all kept compounding as businesses while delivering years of dead money to investors who bought at peak multiples.
The scenario exercise is not about predicting the future. It is about knowing what future the current price already assumes, so you can decide whether you are being paid enough to take that risk.
Business quality and investment quality are two separate decisions
Admiring a business and buying its stock at any price are two different acts. Conflating them is where most overpayment errors begin, and all three cases here are variations on that single mistake.
What makes this genuinely hard is worth naming. FOMO is not irrational when a stock keeps rising, and the market can hold a stretched valuation in place far longer than any model suggests it should. That is exactly why discipline has to be a pre-committed framework rather than an in-the-moment judgement call. You decide your scenarios before the emotion arrives.
The next high-momentum stock you encounter will feel precisely the way Cava feels now: a real business, strong numbers, relentless upward pressure. The question to carry into that moment is not “is this a good business?” It is: “what does this price assume about the next five years, and do I actually believe that?”
Internalise that one distinction and you will make fewer emotional purchases at peak multiples, and you will have a cleaner basis for deciding when a premium price is genuinely earned rather than just crowd enthusiasm wearing a convincing costume.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.