

Transurban bolsters Sydney footprint in $4.5 billion toll road deal
Transurban Group has agreed to acquire Canada Pension Plan Investment Board’s (CPPIB) interests in two Sydney toll road joint ventures for total cash consideration of $4.5 billion, inclusive of stamp duty. The transaction covers CPPIB’s 25% interest in NorthWestern Roads Group (NWRG) and CPPIB’s 10.5% interest in Sydney Transport Partners (STP), lifting Transurban’s stakes across the Westlink M7, NorthConnex, and WestConnex corridors.
When big ASX news breaks, our subscribers know first
What Transurban is buying and what it will own
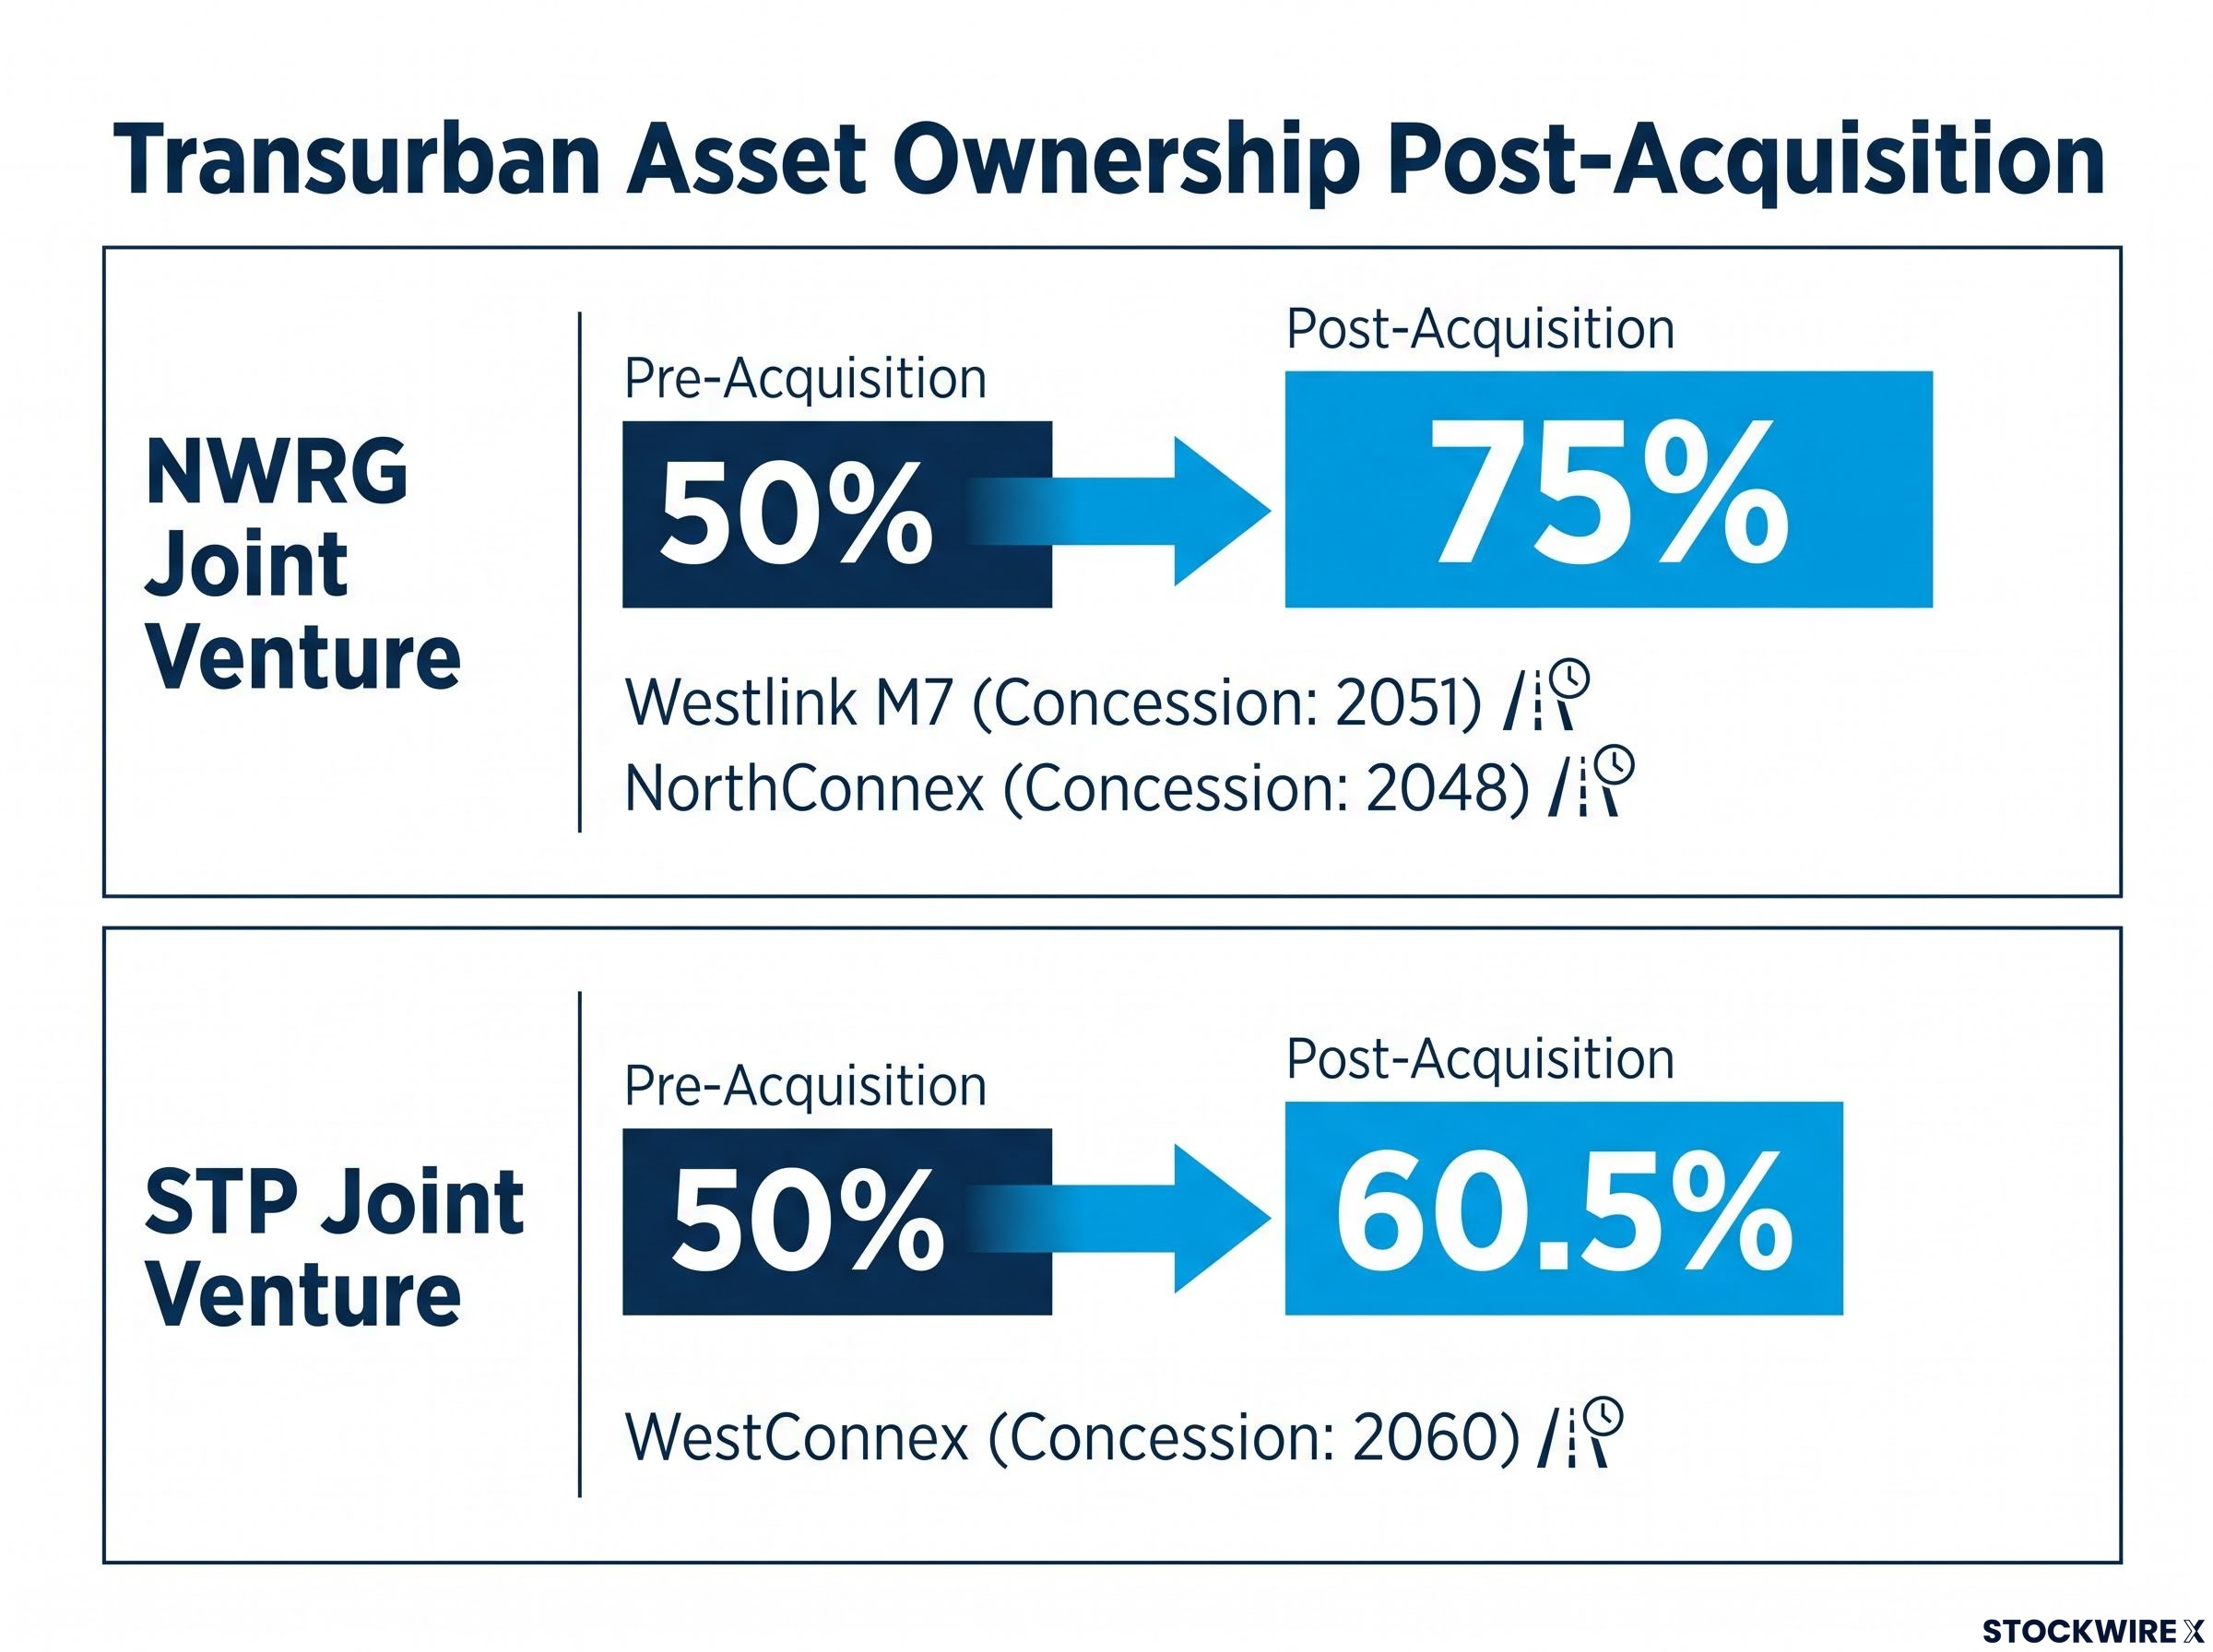
NWRG is the joint venture that owns and operates the Westlink M7 and NorthConnex motorways. STP is the joint venture that owns and operates WestConnex. Upon completion, Transurban’s ownership interests will increase to 75% in NWRG (from 50%) and 60.5% in STP (from 50%).
The three assets carry long-dated concessions, with Westlink M7 running to 2051, NorthConnex to 2048, and WestConnex to 2060. The acquisition is expected to support Transurban’s weighted average concession life across the group. Motorists in New South Wales will see no change to tolls or the on-road experience as a result of the transaction.
The Westlink M7 corridor that forms part of this acquisition has recently added meaningful capacity through the M7-M12 Integration Project, which opened in June 2026 and lifted the motorway’s throughput by up to 30,000 vehicles per day across 26 kilometres.
| Asset | Pre-Acquisition Ownership | Post-Acquisition Ownership | Concession End Date |
|---|---|---|---|
| Westlink M7 (NWRG) | 50% | 75% | 2051 |
| NorthConnex (NWRG) | 50% | 75% | 2048 |
| WestConnex (STP) | 50% | 60.5% | 2060 |
Why Sydney’s toll roads matter to long-term investors
A toll road concession is the right to operate a road and collect tolls from users for a defined period, after which the road reverts to government ownership. For infrastructure investors, long concession lives are valuable because they generate predictable, often inflation-linked revenue streams for decades, making them a reliable source of cash flow.
The three assets in this transaction serve some of Sydney’s most-used freight and commuter corridors. Together, these three roads form a structurally important part of Sydney’s transport network. As the city’s population continues to grow, demand for these corridors is expected to remain resilient over the coming decades.
Financial impact and funding structure
The total consideration of $4.5 billion is an all-cash transaction, inclusive of stamp duty. No equity funding is required. The acquisition will initially be funded with committed debt facilities, which Transurban expects to refinance into longer-term debt over time. The new debt will rank equally with Transurban’s existing corporate senior secured debt.
The all-cash structure draws on committed debt facilities that Transurban expects to refinance into longer-dated instruments over time, a playbook consistent with the group’s recently expanded debt facility, which lifted total committed syndicated bank capacity to A$3.475 billion earlier this year.
Transurban remains committed to its existing Baa1/BBB+ credit ratings, which the company expects will remain unchanged following completion. FY27 Free Cash and distributions are not expected to be impacted by the acquisition.
The acquisition is expected to be value accretive and provide growing accretion to Free Cash per security over the medium and long term. The announcement notes this growth is supported by the addition of the M5 West to the WestConnex concession and the anticipated opening of the Western Harbour Tunnel. In the near term, the announcement states the acquisition is expected to have “an immaterial level of Free Cash per security dilution in the short-term.”
The Valuation Date has been agreed as 31 March 2027, with a roll forward price adjustment payable from that date.
CEO Michelle Jablko
“Sydney is a core market for Transurban. WestConnex, Westlink M7 and NorthConnex provide options for Sydney motorists as they move around the city and will play an important role in supporting Sydney’s growth for decades to come.”
“We remain disciplined with how we allocate capital in our key markets of Australia and North America and we are committed to maintaining strong investment grade credit metrics.”
Conditions and expected timeline
Completion of the NWRG acquisition and the STP acquisition are inter-conditional, meaning both must be satisfied for either to proceed. The transaction remains subject to the following conditions:
- Australian Competition and Consumer Commission (ACCC) clearance
- Compliance with the terms of the relevant project documents
- Other relevant contractual approvals
Subject to these approvals, completion is anticipated during calendar 2027. Transurban has noted it is respectful of these regulatory processes. The transaction represents a change in economic interests between partners and is not expected to have any substantive impact on NWRG or STP governance. Transurban has characterised the acquisition multiples as attractive based on historical transactions, given the concession length and relative maturity of the three assets.
Don’t Miss the Next ASX Infrastructure Deal
Big News Blast delivers FREE breaking ASX news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ investors who stay ahead of the market the moment announcements land. Click the “Free Alerts” button at StockWire X to get started today.