
Suncorp 2026 Investor Update: FY27 outlook guides GWP growth to around 3%
In its 29 October 2026 Investor Update, Suncorp outlined an updated FY27 outlook, with gross written premium (GWP) growth expected to be around 3%, assuming an average FY27 FX rate of AUD 0.81 per NZD. Management said the underlying insurance trading result (UITR) margin is still expected to remain in the top half of the 10-12% range, with no other change to the FY27 outlook previously provided.
The presentation framed the update around leveraging strategic investments in modern platforms, data, artificial intelligence (AI) and resilience as a pure-play Trans-Tasman general insurer.
Steve Johnston, Chief Executive Officer and Managing Director
“Having simplified the business, strengthened our core franchise and invested in modern platforms, data, artificial intelligence and resilience, our focus is now on leveraging those investments to improve customer outcomes, drive operational performance and deliver attractive shareholder returns…”
The lower growth outlook is tied to two identifiable items, while margin guidance is unchanged.
What moved the FY27 GWP outlook
Suncorp highlighted the loss of a single large commercial contract, with an FY27 GWP impact of $125 million. The full impact is expected to be reflected in the first half.
Ongoing weakness in the New Zealand dollar is also expected to reduce growth by approximately 70 basis points in Australian dollar terms. As a result, full year GWP growth is weighted to the second half.
The Investor Scorecard in the presentation set out the FY27 outlook as follows.
| Metric | FY27 outlook |
|---|---|
| GWP growth | Expected to be around 3%, skewed to 2H |
| Total expenses ratio | Broadly in line with FY26 |
| Prior year reserves | Personal Injury releases expected to ~0.4% of Group net insurance revenue |
| UITR margin | Top half of 10-12% range for full year, modestly skewed to 2H |
| Restructuring costs | Expected to be ~$30m |
| Buyback | FY27 buyback of $250m underway |
When big ASX news breaks, our subscribers know first
Strategy: from simplification to leveraging the investments
The transformation path
Management described the transformation in four stages:
- 2019 to 2025: Portfolio simplification, including a multi-year programme of simplification and the exit of non-core businesses.
- 2020 to 2026: Investing in the pure-play, including a new policy administration system, AI-enabled operational transformation and enhanced resilience through reinsurance.
- 2026+: Leveraging the investments, including better products and customer experiences, improved claims and operational outcomes, and new distribution platforms and models.
- Future state: Pursuing growth in insurance value chains and business model evolution.
Strong positions in attractive markets
The presentation set out Suncorp’s market positions and long-term growth drivers across four segments. GWP figures are as at 30 June 2026.
| Segment | Market share | GWP | Growth drivers |
|---|---|---|---|
| Home | 25% | $3.4bn | Growth in housing stock; building cost inflation |
| Motor | 27% | $5.1bn | Growth in the EV pool; vehicle value and repair-cost inflation |
| C&PI | Commercial 9%, PI 27% | $4.5bn | Business formation and wage growth; regulatory and scheme expansion opportunities |
| New Zealand | 25% | NZ$2.8bn | Market recovery from current soft cycle; broader economic recovery; repair cost inflation |
How AI and platform modernisation drive value
A policy administration system is the core software an insurer uses to issue, price and manage policies. Suncorp’s presentation placed a new system of this kind, alongside AI used across the insurance value chain, at the core of its strategy.
Its “Digital Insurer” platform modernisation rests on three differentiating capabilities:
- Digital first: Seamless end-to-end digital sales and service journeys.
- Modern platform: Reusable capabilities across brands, with continuous access to platform, security and AI innovation.
- Intelligent decisioning: Pricing, data, analytics and AI enabling faster, more informed decisions at scale.
Scaled AI adoption is organised around four themes:
- Productivity: AI-enabled workforce, automation and decision support.
- Manufacturing: Personalised product and pricing, underwriting and risk selection.
- Distribution: AI customer journeys, new distribution platforms and models.
- Empowered customers: Customers using AI, and early identification and escalation of customer complaints.
Suncorp tied these to four competitive advantages: customer access, technology leadership, scale and resilience. The stated outcomes include lower acquisition costs, lower cost to serve and reduced volatility, which bear directly on the margin and growth outcomes in the FY27 outlook.
Execution of the AI and distribution agenda is supported by recent executive leadership changes, including a new function combining brand, marketing and digital distribution under one structure.
Shareholder returns and risk-adjusted performance
Management presented a three-part investment proposition: growth in earnings per share, strong risk-adjusted returns with reduced volatility, and disciplined capital management.
On capital, ordinary dividends are ~60-80% of cash earnings, ~20% goes to business needs through the cycle, and excess capital is returned to shareholders.
The $250m buyback sits within a wider capital return programme that followed Suncorp’s FY26 cash earnings of $1.04bn, with the ordinary payout framework supplemented by a special dividend and the on-market repurchase.
The presentation highlighted consistent delivery of UITR margins in the top half of the target range.
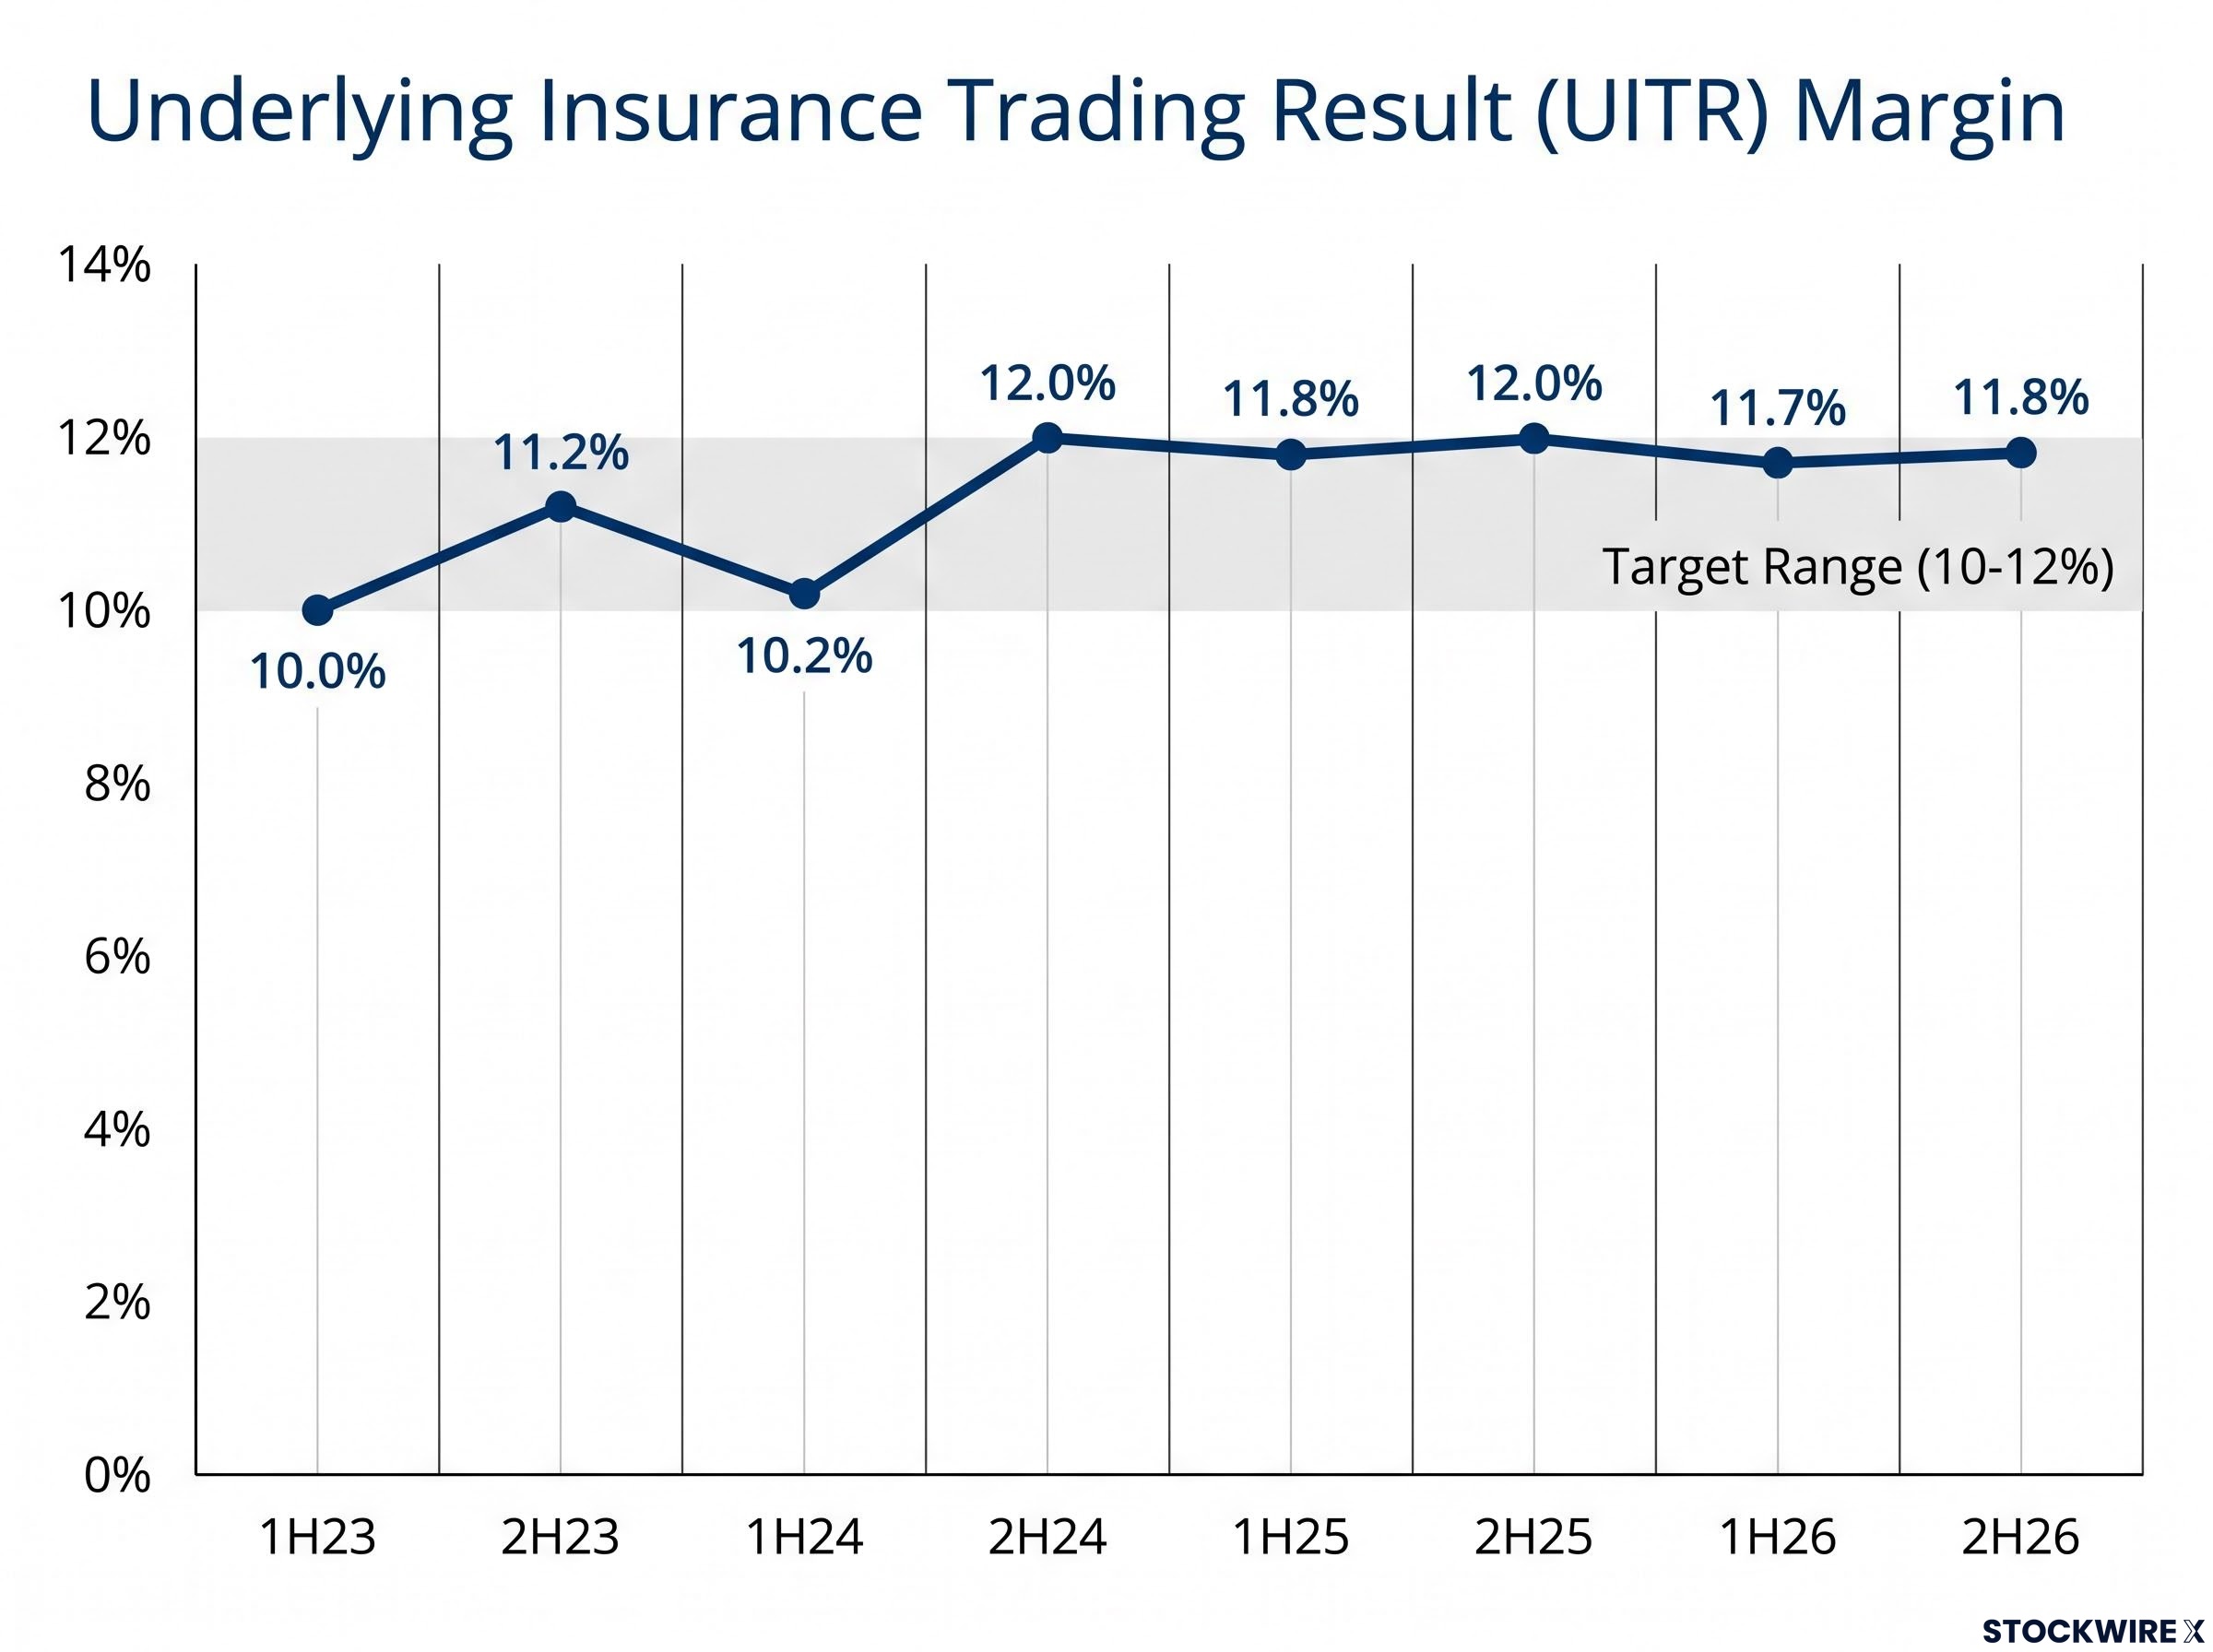
| Period | UITR margin |
|---|---|
| 1H23 | 10.0% |
| 2H23 | 11.2% |
| 1H24 | 10.2% |
| 2H24 | 12.0% |
| 1H25 | 11.8% |
| 2H25 | 12.0% |
| 1H26 | 11.7% |
| 2H26 | 11.8% |
On tangible book value (TBV) per share, the five-year compound annual growth rate (CAGR) was 11.2% for Suncorp, against 1.6% for Aus Banks and 3.9% for Aus Financials (ex Banks). Data is as at 23 October 2026.
Suncorp’s 3-year annualised share price return was 18.8% with a Sharpe ratio of 0.69, compared with 11.4% and 0.62 for the ASX 100. Data is as at 30 September 2026.
What happens next for Suncorp
The presentation and announcement point to the following stated items:
- The FY27 buyback of $250m is described as underway.
- The full impact of the commercial contract loss is expected to be reflected in the first half of FY27.
- FY27 GWP growth and the UITR margin are both weighted to the second half.
- Restructuring costs of ~$30m are expected in FY27.
Get Financials News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX news within minutes of release, complete with in-depth analysis. Big News Blast delivers market-moving financials updates straight to your inbox the moment they break. Click the “Free Alerts” button to stay ahead of the next big announcement.