

EQT Holdings Limited is fielding competing acquisition proposals from two major private equity firms, TPG Global, LLC and BGH Capital Pty Ltd, each seeking to acquire 100% of EQT shares by way of a Scheme of Arrangement. The EQT Board has concluded that the current indicative offer prices from both parties do not adequately reflect the value of Equity Trustees, but has invited each bidder to access substantive non-public information to enable improved proposals to be submitted. Critically, both TPG and BGH have confirmed that EQT’s FY26 final dividend of 20 cents per share, announced on 27 August 2026, will not reduce their respective indicative offer prices.
Board rejects current prices, opens structured engagement
The EQT Board, informed by management and its legal and financial advisers, has formally concluded that the offer prices proposed by TPG and BGH do not adequately reflect the value of Equity Trustees. Rather than closing the door entirely, the Board has offered each party a structured pathway to submit improved proposals.
Under this pathway, each bidder may receive substantive non-public information from Equity Trustees. Access is conditional on each party entering into an appropriate confidentiality deed (including a standstill) with Equity Trustees. Draft confidentiality deeds have already been provided to both TPG and BGH, indicating the process is actively progressing.
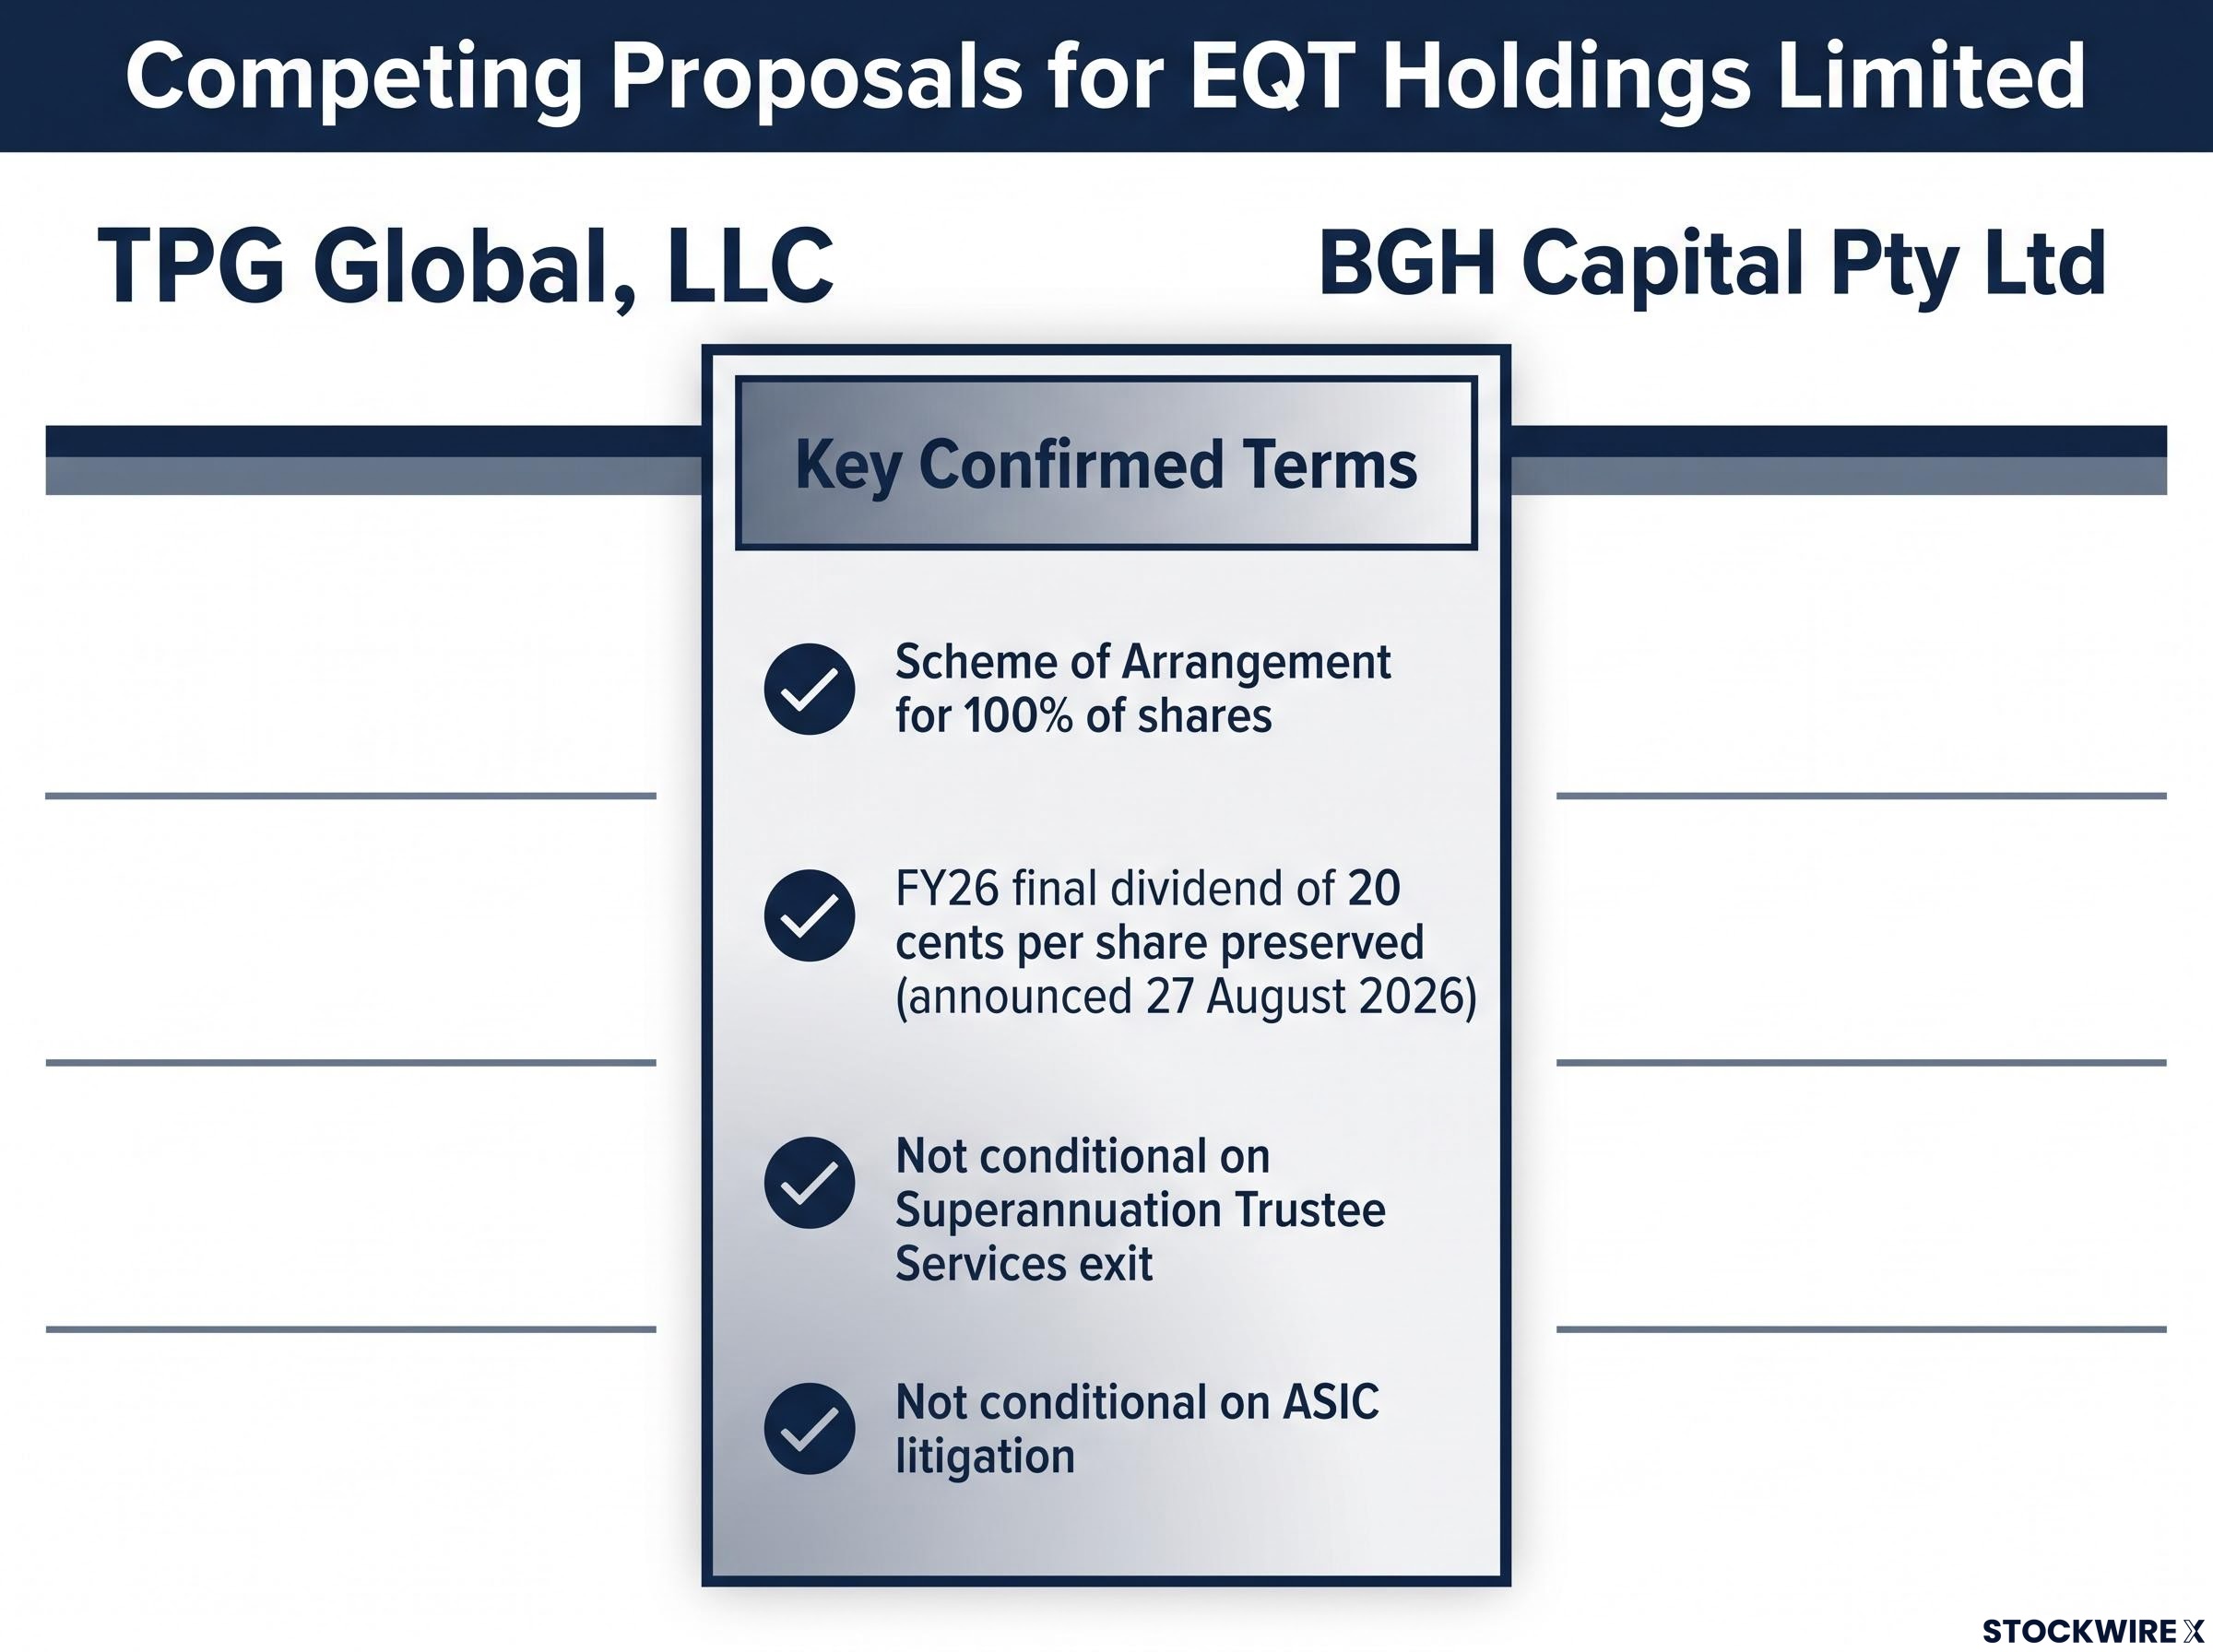
Both parties have made the following key confirmations:
- The FY26 final dividend of 20 cents per share announced on 27 August 2026 will not reduce their respective indicative offer prices
- Their Proposals are not conditional on Equity Trustees implementing an exit of the Superannuation Trustee Services business, or on the conclusion of the ASIC litigation
What the board’s shareholder engagement reveals
The Board explicitly considered feedback from shareholders as part of its deliberations on the Proposals. This inclusion of shareholder sentiment in the formal decision-making process signals a degree of responsiveness to the market and suggests the Board is weighing investor views alongside its own valuation assessment.
When big ASX news breaks, our subscribers know first
Understanding schemes of arrangement — what investors need to know
A Scheme of Arrangement is a court-approved corporate transaction that, if successful, results in an acquirer obtaining 100% of a target company’s shares. The process requires shareholder approval, as well as court approval. Once approved, the scheme is binding on all shareholders, meaning there is no opt-out for minority holders who vote against it.
Private equity acquirers tend to favour this structure because it provides certainty. A successful scheme delivers a clean transfer of the entire issued share capital, eliminating residual minority stakes that can complicate post-acquisition governance.
It is important for investors to understand what “indicative, non-binding and conditional” means in practice. At this stage, neither the TPG nor the BGH proposal constitutes a binding commitment to acquire EQT. These are expressions of interest, and either party may withdraw or revise their proposal before any formal binding offer is made.
The requirement for a confidentiality deed (including a standstill) carries specific legal significance. The standstill provision prevents a bidder from purchasing EQT shares on the open market while negotiations are underway. This protects the Board’s negotiating position by preventing a bidder from accumulating a blocking stake or applying market pressure during the due diligence phase.
Investment implications — competitive tension, premium potential, and uncertainty
The presence of two competing bidders is a structurally positive development for EQT shareholders. Competing proposals create upward price tension, reducing the risk that a single bidder can table a low-ball offer without challenge. When two parties are simultaneously conducting due diligence and preparing revised proposals, each is incentivised to price more aggressively to outcompete the other.
The Board’s decision to reject current prices while simultaneously granting access to non-public information reflects confidence that the intrinsic value of Equity Trustees exceeds what has been tabled to date. Sharing non-public information is a deliberate step that signals the Board believes a higher, justifiable offer is achievable once bidders have a fuller picture of the business.
EQT’s FY26 full year results, released on 27 August 2026, showed continuing operations NPAT rising 32.7% to $33.9 million on revenue of $167 million, providing the financial baseline that both TPG and BGH are now evaluating as they prepare revised proposals.
Two potential deal-break risks that investors may have anticipated have effectively been removed. Neither proposal is conditional on Equity Trustees exiting its Superannuation Trustee Services business, nor on the resolution of the ASIC litigation. This reduces the complexity of any eventual transaction.
EQT’s superannuation trustee exit, announced in June 2026, involved a roughly $13 million non-cash goodwill impairment, a potential $36 million ORFR loan repayment obligation, and the wind-down of a business that managed $95 billion in funds under management, making it one of the more complex structural factors any prospective acquirer must price into a binding offer.
The following table summarises the key confirmed details of each proposal:
| Bidder | Proposal Type | Dividend Treatment | Conditional on Super Exit? | Conditional on ASIC Litigation? |
|---|---|---|---|---|
| TPG Global, LLC | Indicative, non-binding and conditional — Scheme of Arrangement for 100% of EQT shares | FY26 final dividend of 20 cents per share will not reduce indicative offer price | No | No |
| BGH Capital Pty Ltd | Indicative, non-binding and conditional — Scheme of Arrangement for 100% of EQT shares | FY26 final dividend of 20 cents per share will not reduce indicative offer price | No | No |
Investors should note the company’s own caveat: there is no certainty that either Proposal will result in a formal binding offer for EQT, or that any transaction will eventuate. The Board has confirmed that EQT shareholders do not need to take any action in relation to the Proposals at this time.
What happens next
The logical sequence from here involves both TPG and BGH reviewing the non-public information made available under their respective confidentiality deeds, before submitting revised proposals for Board consideration. Should the Board find an improved proposal acceptable, the process would move toward a formal binding offer, followed by shareholder and court approval under the Scheme of Arrangement framework.
The Board has authorised this public release, a procedural step that reflects standard governance transparency in a sensitive takeover context.
Equity Trustees, the brand name of EQT Holdings Limited and its subsidiaries, was established in 1888 and is described as Australia’s leading specialist trustee company. The group offers a range of services spanning asset management, estate planning, philanthropic services, and Responsible Entity services, with offices across Melbourne, Adelaide, Sydney, Brisbane, and Perth.
Stay Ahead on ASX Finance and M&A News
Breaking ASX announcements land in your inbox within minutes, complete with in-depth analysis already done for you. Over 20,000+ investors rely on Big News Blast for FREE real-time coverage across finance, tech, healthcare, and more. Click the “Free Alerts” button to ensure the next market-moving deal reaches you the moment it breaks.