

Perpetual’s Board rejects EQT’s $22.50 acquisition proposal
Perpetual Limited has formally rejected a further revised non-binding proposal from Windflower Pte. Limited, an entity Perpetual understands is indirectly controlled by EQT AB, to acquire 100% of Perpetual shares via a Scheme of Arrangement. The cash scheme consideration offered was $22.50 per Perpetual share, with a permitted dividend of up to $0.60 per share for the half year to 31 December 2026 (1H27) not adjusting the scheme price.
EQT characterised the proposal as a “best and final proposal” in the absence of a competing proposal, formally closing the engagement process. Perpetual shareholders do not need to take any action.
When big ASX news breaks, our subscribers know first
Why the Board said no — valuation and execution risk
The price hasn’t changed since July
The $22.50 scheme consideration under the Further Revised Proposal is identical to the price EQT offered in its earlier proposal dated 27 July 2026, which the Board had already concluded was not in the best interests of Perpetual shareholders.
Following receipt of that earlier proposal, Perpetual provided EQT with access to limited non-public information on a non-exclusive basis to determine whether an improved proposal could be formulated. EQT completed that due diligence process and returned with the same price. Despite having the opportunity to review additional information and revise upward, EQT chose not to.
The due diligence access granted to EQT followed the board’s earlier rejection of the A$22.50 proposal in late July 2026, with Perpetual offering limited non-public information on a non-exclusive basis in the explicit hope that a materially higher revised offer would follow.
Unacceptable transaction execution risk
Beyond the price itself, the Board raised a second and distinct concern. The Further Revised Proposal included further clarification of the conditions and assumptions underpinning EQT’s approach, and in the Board’s view, a number of those assumptions give rise to an unacceptable degree of transaction execution risk for Perpetual and its shareholders.
The announcement does not detail the specific assumptions in question. The Board’s rejection is therefore a dual determination: the proposal both undervalues the company and carries structural concerns that are unacceptable.
Board determination
“After carefully considering all aspects of the Further Revised Proposal, the Board has determined that the Further Revised Proposal undervalues Perpetual and is not in the best interests of Perpetual’s shareholders as a whole.”
It is also worth noting that any future dividend remains subject to Board determination and prevailing financial, regulatory, and market conditions, available franking credits, and other relevant considerations. The Board has stated it is unable to provide any assurance at this time as to whether any dividend will be declared for 1H27 or, if declared, what the quantum of that dividend would be.
What is a Scheme of Arrangement?
A Scheme of Arrangement is a court-approved mechanism by which an acquirer can seek to purchase 100% of a listed company’s shares. Unlike an on-market takeover bid, a Scheme requires both Board recommendation and a shareholder vote — typically approval from at least 75% of votes cast by value and more than 50% by number of shareholders present and voting.
This structure is significant in the current context. Without the Board’s support, a Scheme of Arrangement cannot proceed to a shareholder vote. The Board’s rejection is therefore not merely an advisory opinion; it effectively brings EQT’s current approach to a full stop.
The “best and final” declaration reinforces this. When a bidder states its proposal is best and final in the absence of a competing proposal, it signals it will not raise its offer. Combined with the Board’s refusal to engage further, the EQT process is now concluded on both sides.
Perpetual’s standalone path forward
The conclusion of the EQT process does not alter Perpetual’s strategic priorities. The company has confirmed its planned completion of the Wealth Management business sale remains well progressed and is expected to complete in Q4 of 2026.
The Wealth Management sale to Bain Capital, agreed in March 2026 for $500 million upfront with up to $100 million in performance-linked payments, is the structural transaction underpinning Perpetual’s expected transition to a net cash position and its narrowed focus on Corporate Trust and Asset Management.
Following that sale, Perpetual expects to move to a net cash position, providing enhanced financial flexibility and capacity for additional capital management options alongside dividends. The company’s ongoing focus remains on delivering sustainable long-term value through its Corporate Trust and Asset Management businesses.
Key standalone strategic pillars confirmed by the Board include:
- Completion of the Wealth Management business sale (expected Q4 of 2026)
- Expected transition to a net cash position following the sale
- Capital management optionality alongside dividends
- Continued focus on the Corporate Trust and Asset Management businesses
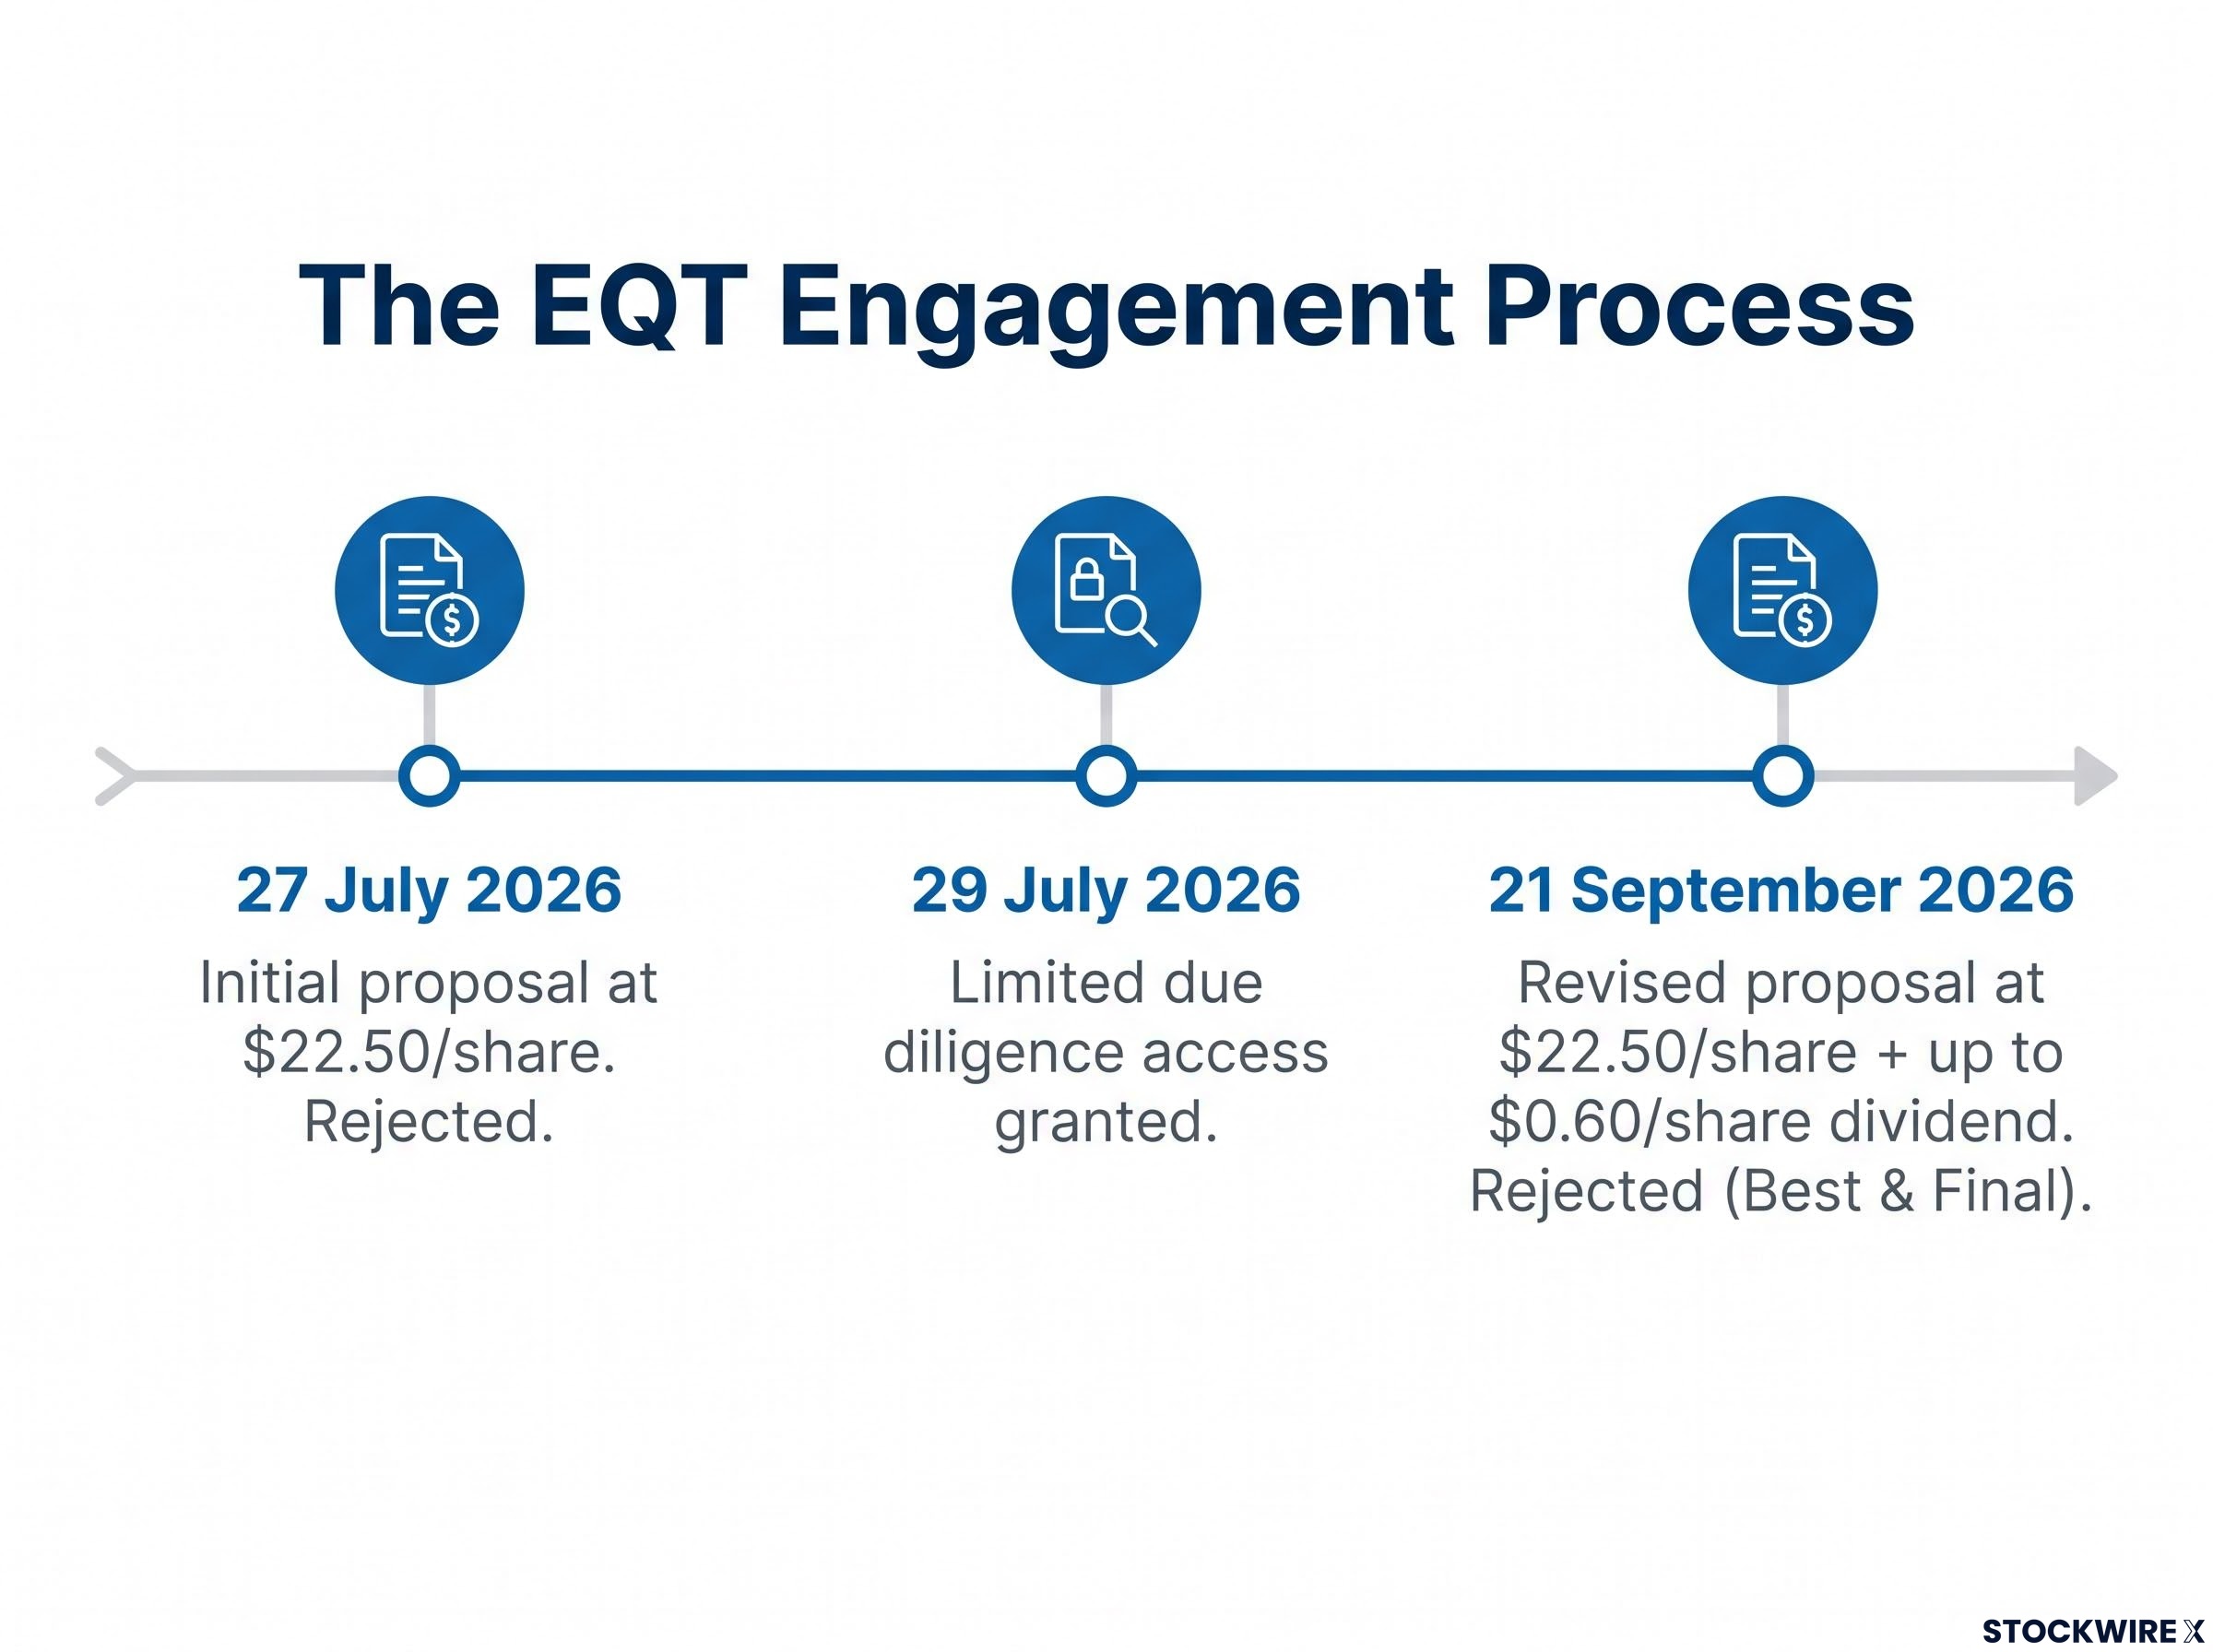
The following table summarises the key events in the EQT engagement process:
| Date | Event | EQT Offer Price | Board Response |
|---|---|---|---|
| 27 July 2026 | Initial EQT proposal received | $22.50/share | Rejected — not in best interests of shareholders |
| 29 July 2026 | Limited due diligence access granted to EQT | — | Provided on non-exclusive basis |
| 21 September 2026 | Further Revised Proposal submitted by EQT | $22.50/share + Permitted Dividend of up to $0.60/share | Rejected — process concluded; best and final proposal, engagement ends |
With the EQT engagement formally concluded, Perpetual’s Board has indicated the company is focused on executing its existing strategy. The Wealth Management sale and anticipated transition to a net cash position represent the near-term priorities, with Corporate Trust and Asset Management forming the foundation of the company’s long-term shareholder value proposition.
Stay Ahead on ASX Financials News
Get FREE breaking ASX financials news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already staying ahead of the market with Big News Blast. Click the “Free Alerts” button to receive real-time coverage the moment market-moving announcements drop.