
Amotiv cuts FY27 outlook after a 5% Q1 revenue decline
Amotiv (ASX:AOV) has revised its FY27 outlook after a challenging first quarter of FY27, with like-for-like Group revenue 5% below the prior corresponding period (pcp). The like-for-like figure excludes the divested ECB business from both periods.
The company attributed the decline largely to subdued new vehicle and pick up sales, combined with supply disruption in Thailand from flooding that affected OEM plant production days. Gross margins improved on the prior year.
Alongside the update, the Group announced an on-market buyback of up to 5% of shares on issue, maintaining its commitment to improving shareholder returns.
When big ASX news breaks, our subscribers know first
Q1 FY27 trading by division
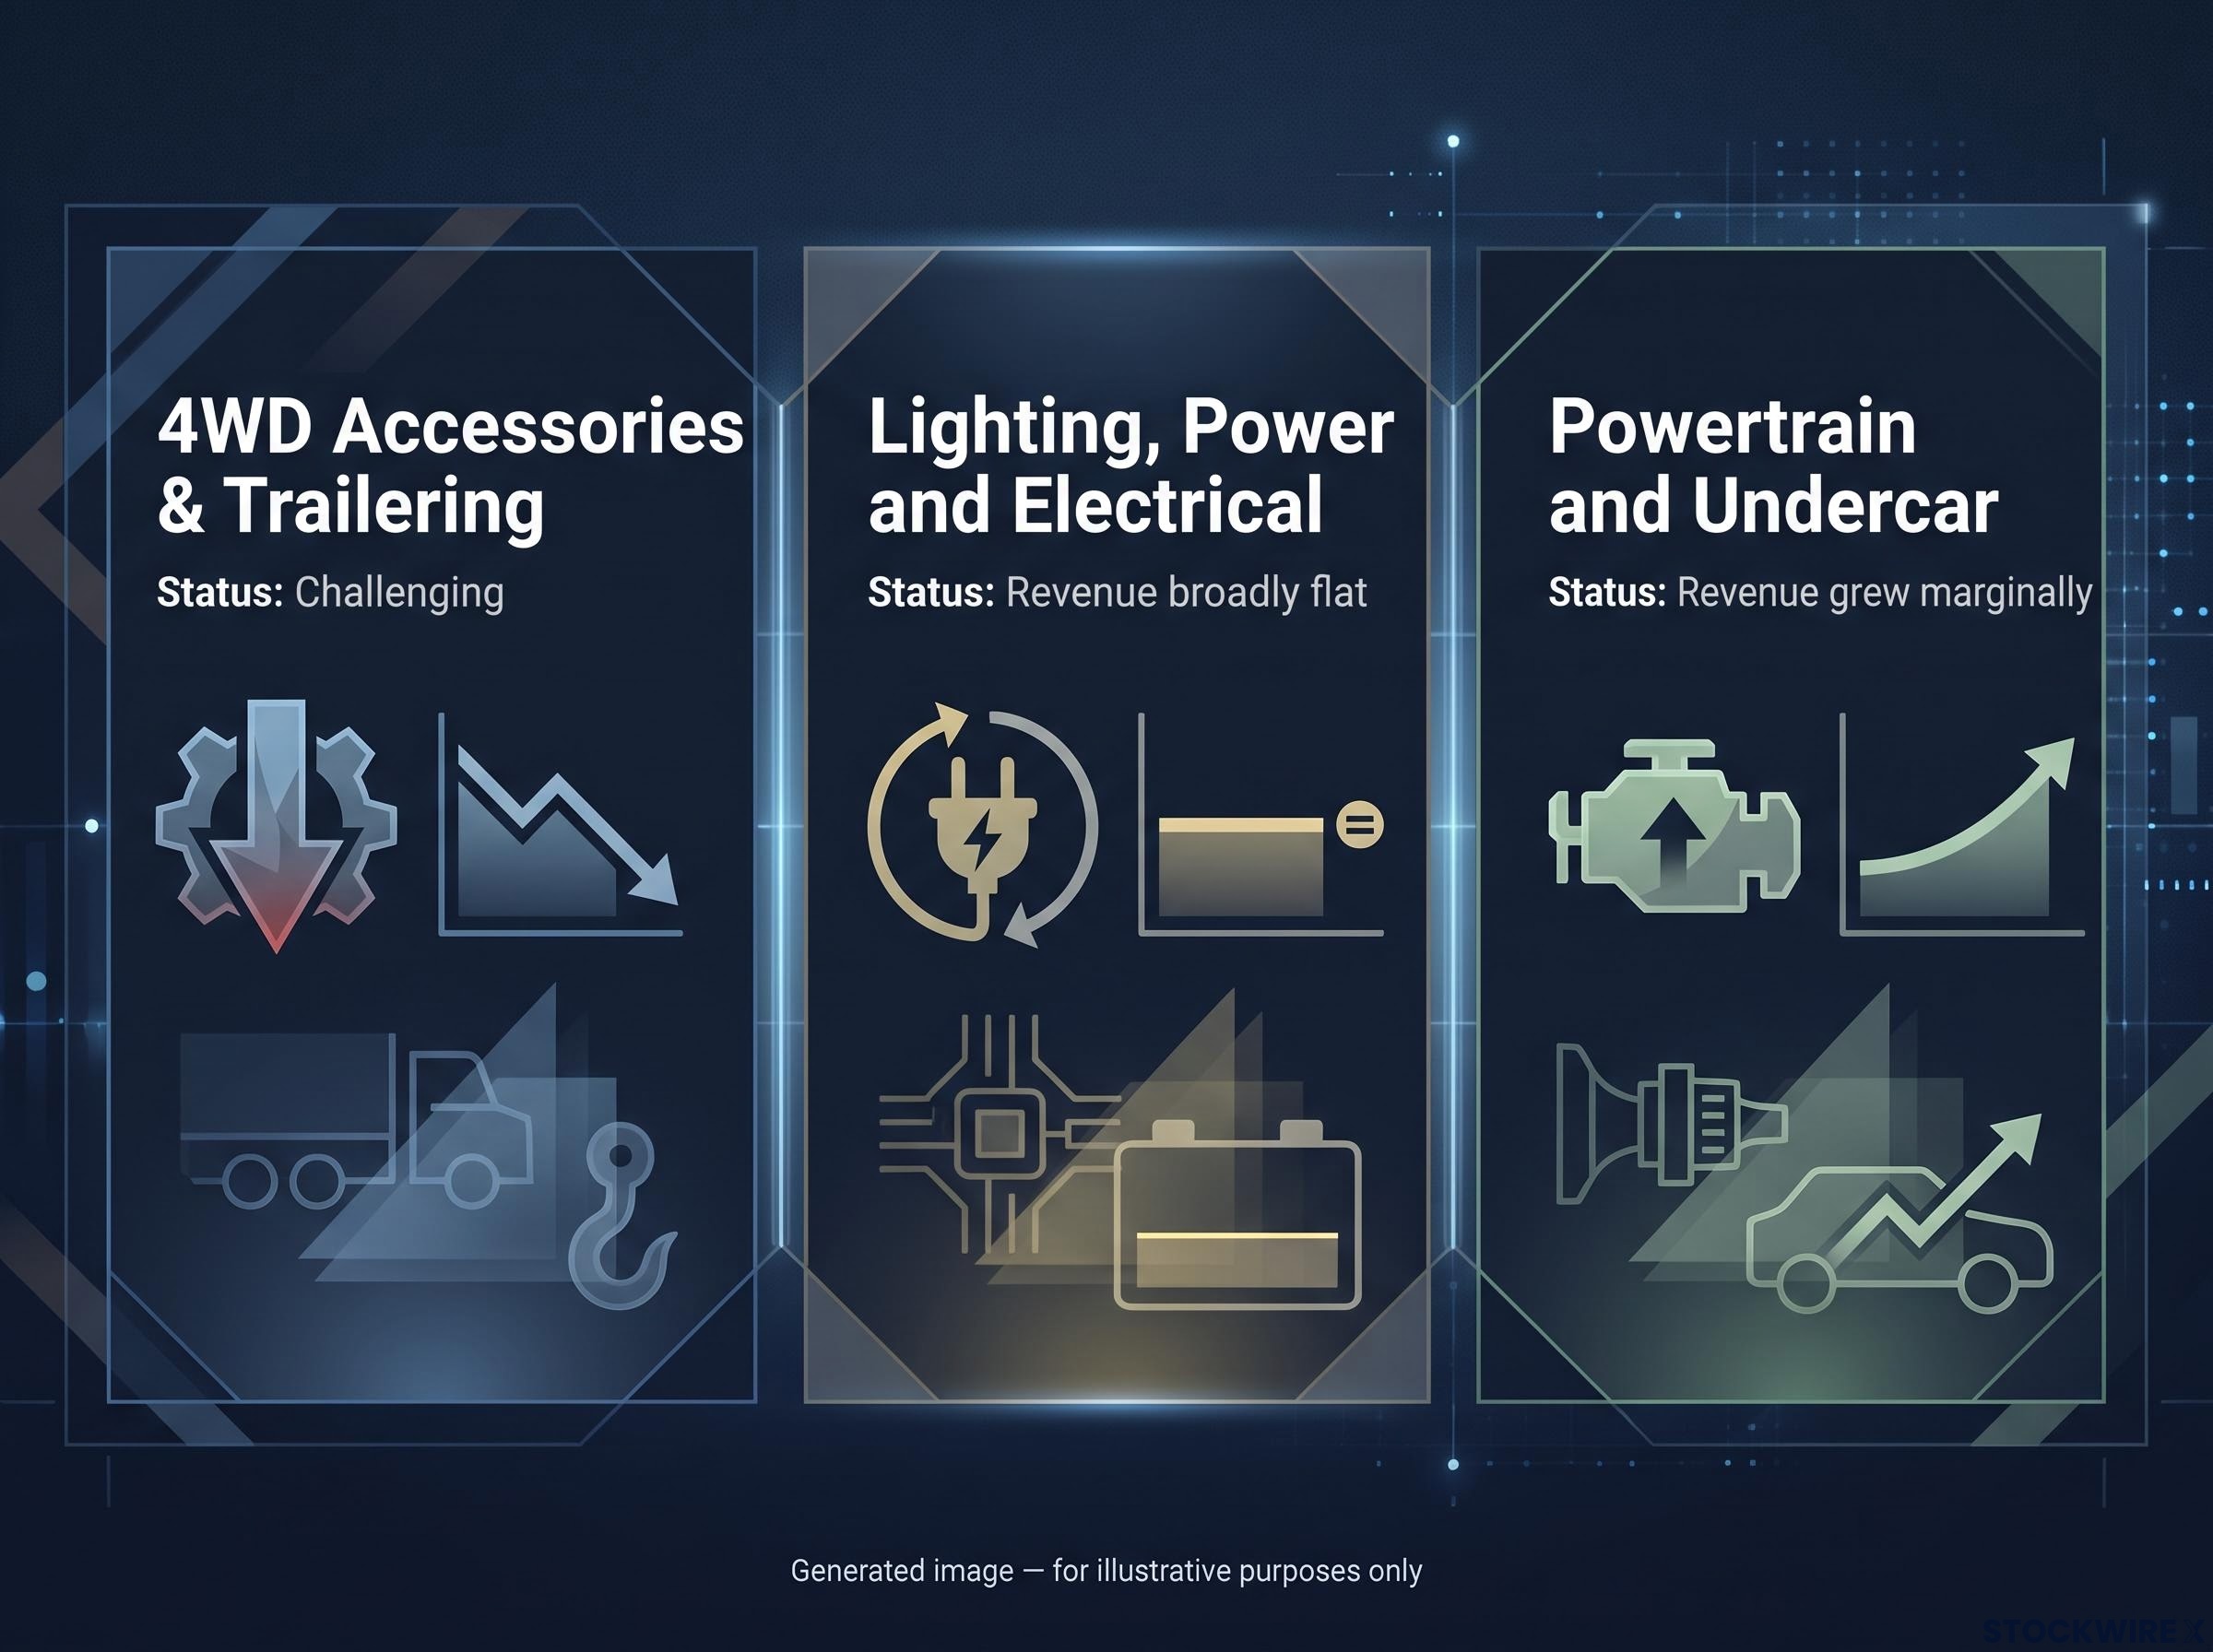
Trading was challenging mostly in the 4WD Accessories & Trailering Division. The other two divisions were steadier.
| Division | Q1 FY27 trading | Key driver |
|---|---|---|
| 4WD Accessories & Trailering | Challenging | Subdued new vehicle and pick up sales; Thailand flooding disruption to OEM plant production days |
| Lighting, Power and Electrical | Revenue broadly flat | n/a |
| Powertrain and Undercar | Revenue grew marginally | n/a |
Costs under pressure
Operating costs were affected by one-offs and inflationary increases. The one-off costs related to:
- A legal dispute with a US customer
- Hi Viz lighting
- Heightened Caravan/RV sector risks
- Warehousing and logistics costs
Hi Viz revenue contribution is not considered material to the Group. Operating costs remain a key area of focus through the balance of the year, through targeted efforts as part of Amotiv Unified initiatives.
Revised FY27 outlook: what changed
In August, Amotiv expected modest revenue and underlying EBITA growth in FY27, assuming a continuation of prevailing economic and trading conditions and no material adverse events. Conditions have since worsened:
- Conflict in the Middle East has persisted, keeping fuel prices elevated
- Interest rates have risen further
- Consumer sentiment has weakened
- Cost of living pressures have increased
Management expects these conditions to persist for the balance of FY27. The outlook has been revised as follows.
| Scenario | Revenue | Underlying EBITA |
|---|---|---|
| Excluding VAFI consolidation | Now expected to be up to 5% lower than FY26 continuing operations | Now expected to be up to 5% lower than FY26 continuing operations |
| Including VAFI consolidation | Expected to be broadly in line with FY26 continuing operations | Expected to be broadly in line with FY26 continuing operations |
FY26 continuing operations revenue was $986.2m and underlying EBITA was $191.6m. These figures exclude the ECB and Fully Equipped businesses, both divested in FY27. FY26 reported revenue was $1,023.9m and underlying EBITA was $195.1m.
That reported EBITA base comes from the FY26 full year results, where underlying EBITA of $195.1m landed in line with guidance and cash conversion reached 93.1%, before trading conditions weakened.
The outlook assumes a continuation of prevailing economic, geopolitical and trading conditions, no material adverse events and delivery of further Amotiv Unified benefits. It is qualified by the Disclaimer on page 13 of the 2026 AGM presentation.
Divisional outlook
- 4WD: Growing Chinese OEM presence in ANZ is expected to remain a source of new business. Thailand flooding impact is expected to normalise into H2, while new vehicle sales (pick-up and SUV Medium+) are expected to remain subdued.
- LPE: US and Europe growth is expected to continue. EBITA margins are expected to moderate versus FY26, reflecting the absence of a prior-year one-off and ongoing US investment, and ANZ headwinds are expected to persist.
- PTU: Wear and repair categories are expected to remain resilient. Further US growth is expected in H2 from the Holley alliance, and VAFI consolidation is weighted to H2.
What is VAFI consolidation and why it matters
Amotiv holds 50.1% of VAFI. Under accounting standards, VAFI is 100% consolidated from 1 October 2026 at EBITA, meaning all of its earnings at that level are counted in the Group’s result.
The 49.9% minority share is eliminated at NPAT attributable to AOV shareholders. Because the outlook is shown both with and without VAFI consolidation, investors can compare like with like against FY26 continuing operations.
Levers supporting the second half
Amotiv said its business fundamentals remain strong, with the outlook supported by the following levers:
- Pricing actions undertaken across all divisions, with benefits weighted towards H2
- A further $10m net annualised benefits targeted in FY27 from Amotiv Unified, largely weighted to H2, moderating inflationary increases
- International expansion, including VAFI consolidation from 1 October 2026 (50.1%), a strategic alliance announced with Holley Performance Brands (NYSE: HLLY) providing US growth opportunities from H2 onwards, and continued expansion of US e-commerce through Amazon Prime enablement
- FX management tailwinds, including USD hedging to end of Q3 at favourable rates versus pcp, with a THB tailwind partly offsetting steel cost increases
The Group also announced an on-market buyback of up to 5% of shares on issue, maintaining the commitment to improving shareholder returns. Combined with strong brands and market positions, resilient wear and repair exposure and a strong balance sheet and cashflows, the Board and management have confidence in Amotiv’s future.
What happens next for Amotiv
VAFI consolidation took effect from 1 October 2026, with the benefit weighted to H2 FY27. The following items are flagged in the update:
- Thailand flooding: impact expected to normalise into H2.
- Amotiv Unified: a further $10m net annualised benefits targeted in FY27, largely weighted to H2.
- Pricing actions: benefits weighted towards H2.
- Holley alliance: US growth opportunities from H2 onwards.
- USD hedging: in place to the end of Q3 at favourable rates versus pcp.
Further details are provided in the AGM addresses and presentation released on 27 October 2026.
Stay Ahead on Consumer News Before the Market Moves
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already receiving real-time alerts from Big News Blast. Click the “Free Alerts” button to see market-moving consumer announcements the moment they break.