
Memphasys identifies expedited FDA clearance pathway for Felix™
Memphasys (ASX: MEM) has identified a potentially faster and more cost-effective route to FDA clearance for its Felix™ Sperm Separation System, potentially shifting from the De Novo classification pathway to the more established 510(k) pathway after identifying a device it believes may be a suitable predicate. The development follows a Board-level reassessment of the Company’s US regulatory strategy, prompted by the strategic importance and scale of the US fertility market. This is a strategic upgrade to the Company’s regulatory approach, not a change to its near-term commercial priorities.
When big ASX news breaks, our subscribers know first
What changed and why it matters
Memphasys had previously anticipated that Felix™ would need to progress through the FDA’s De Novo classification pathway because no suitable predicate device had been identified. Working with specialist regulatory advisers, the Company has now identified a legally marketed device it believes may provide an appropriate predicate for Felix™.
This creates the potential for Felix™ to pursue the FDA’s established 510(k) pathway, based on demonstrating substantial equivalence, rather than the De Novo pathway previously contemplated. The Board believes this represents a potentially more efficient route towards accessing one of the world’s largest fertility markets.
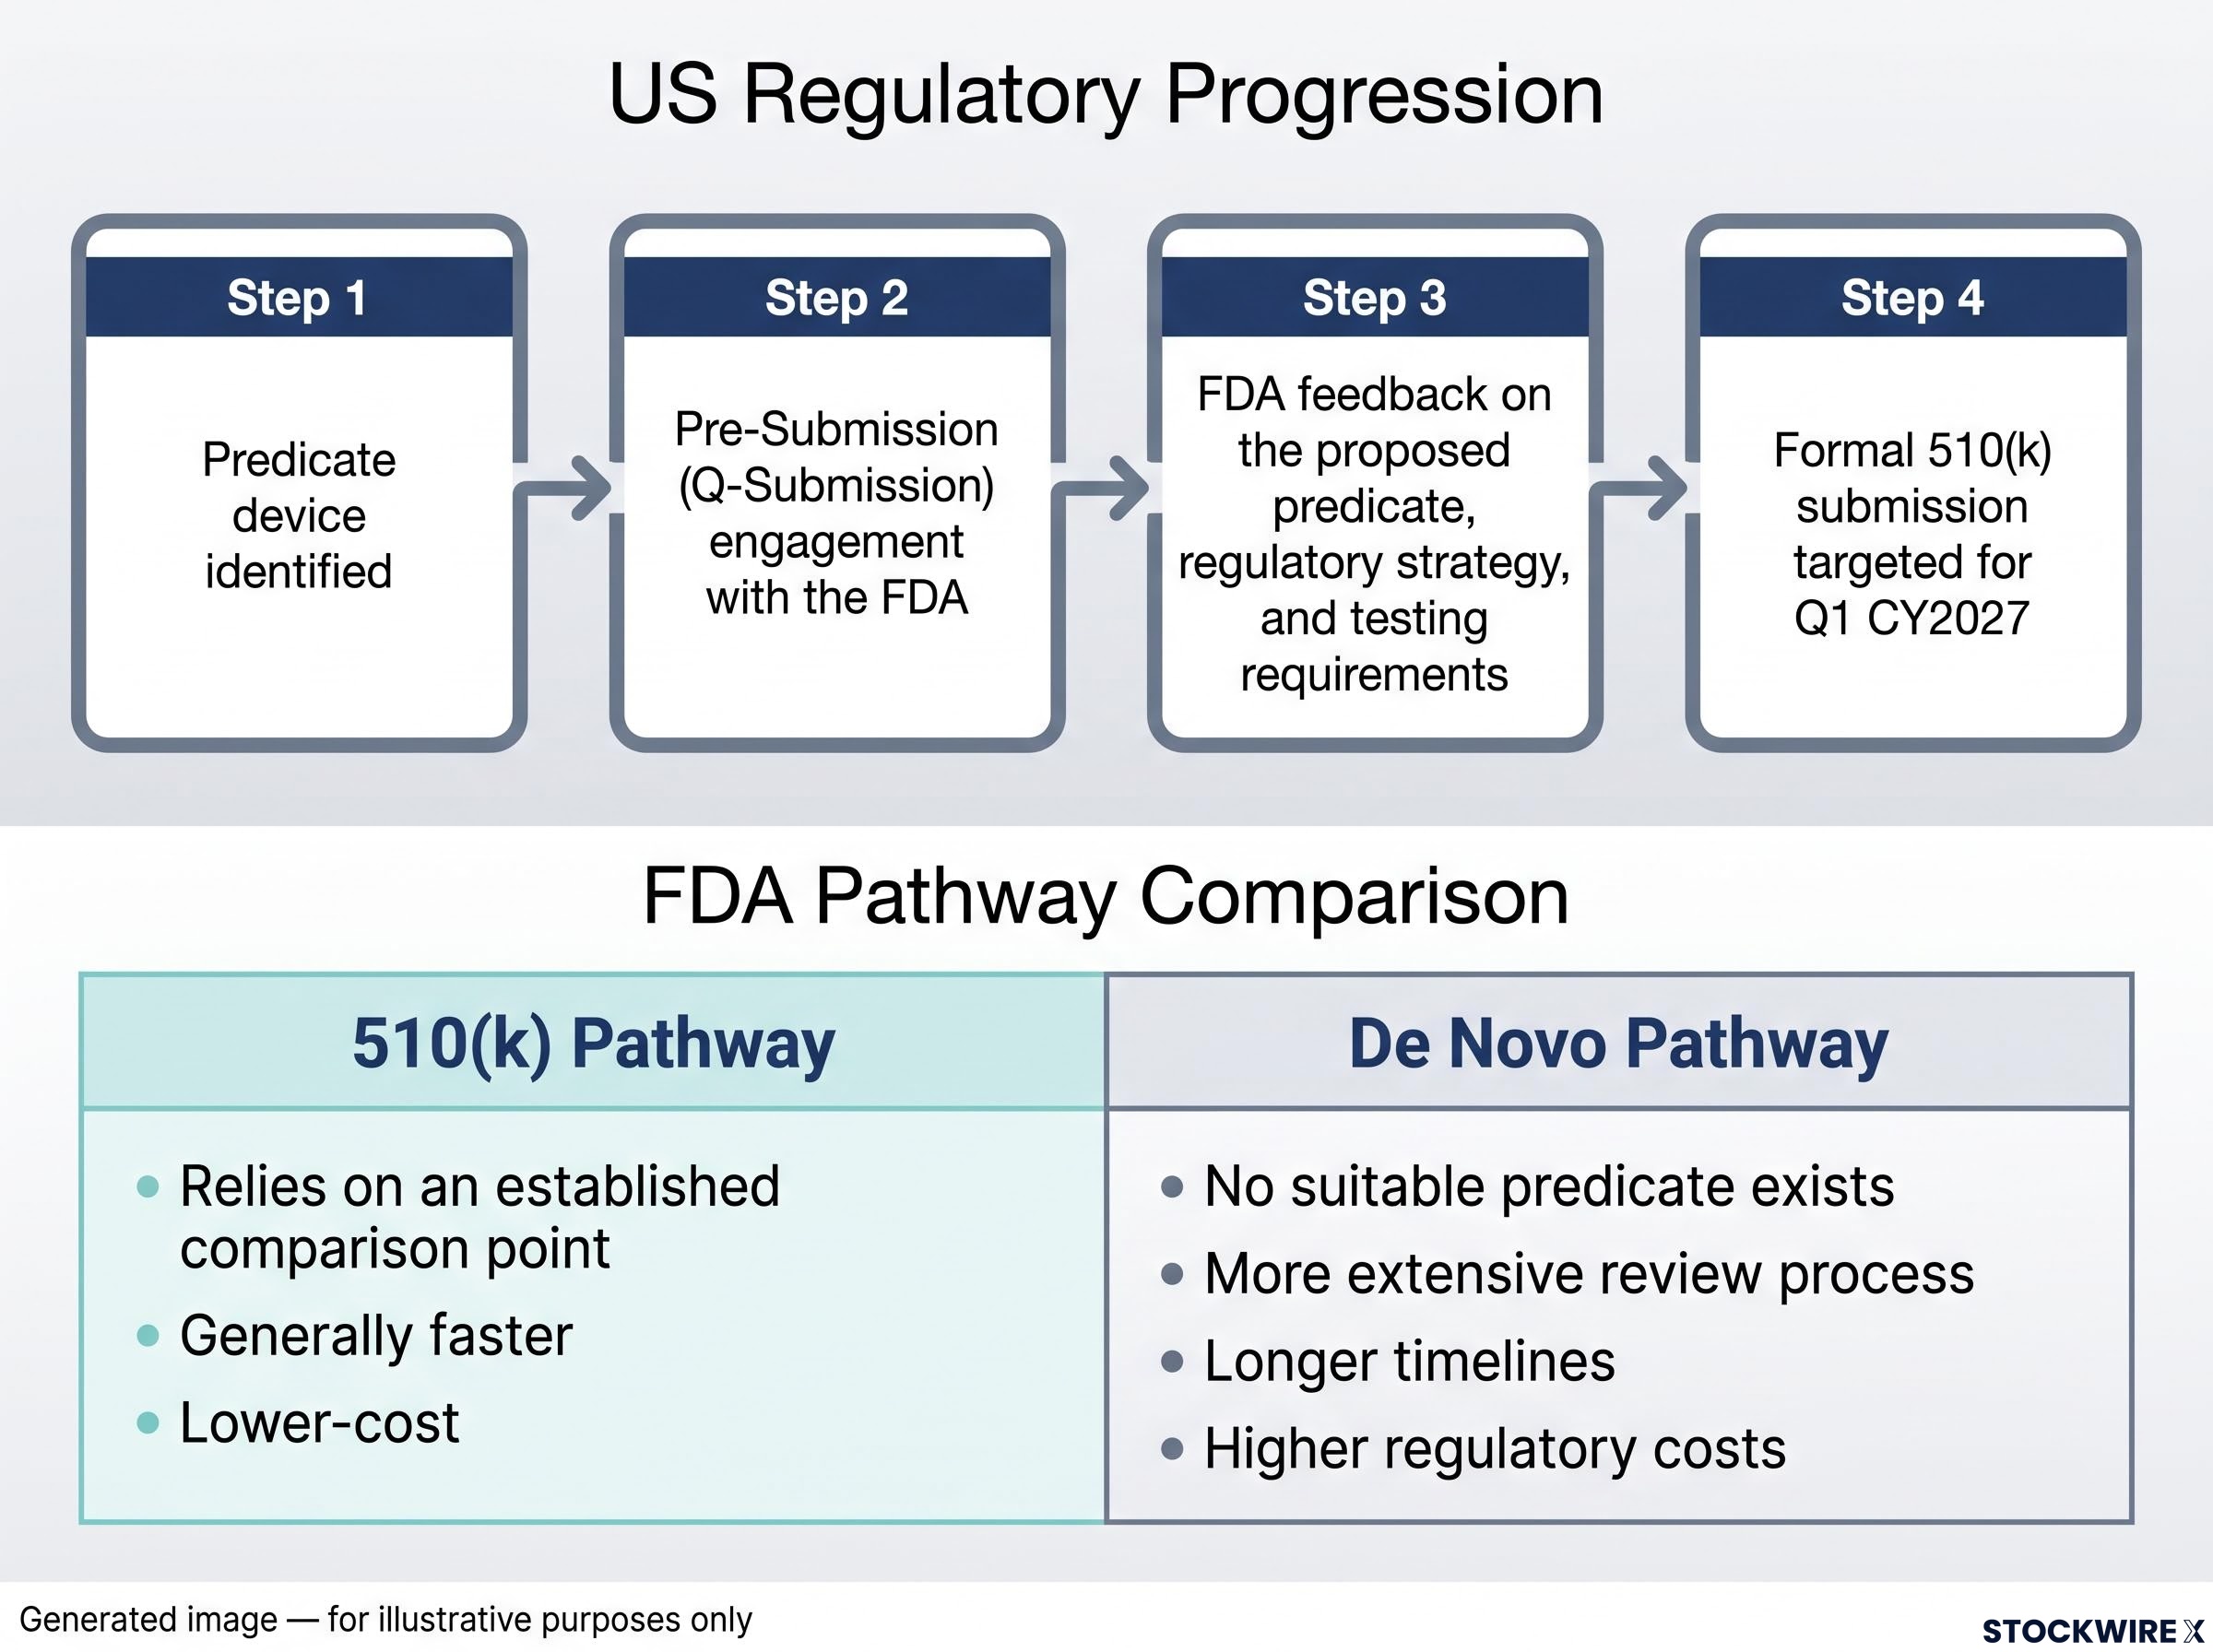
The regulatory progression is expected to follow these steps:
- Predicate device identified
- Pre-Submission (Q-Submission) engagement with the FDA
- FDA feedback on the proposed predicate, regulatory strategy, and testing requirements
- Formal 510(k) submission targeted for Q1 CY2027
Understanding the 510(k) vs De Novo pathways
For investors unfamiliar with US medical device regulation, the distinction between these two pathways is material to understanding the significance of this update.
The 510(k) pathway allows a company to seek FDA clearance by demonstrating that its device is “substantially equivalent” to a legally marketed predicate device already cleared by the FDA. Because the pathway relies on an established comparison point, it is generally faster and lower-cost than alternative routes. The De Novo pathway, by contrast, is used when no suitable predicate exists. It requires a more extensive clinical and technical review process, resulting in longer timelines and higher regulatory costs.
For investors, the shift matters because the 510(k) pathway is capital-efficient and reduces the timeline risk associated with US market entry. A faster, lower-cost regulatory process preserves cash and brings the potential US revenue opportunity closer within reach.
The US IVF market opportunity
The United States represents a significant long-term commercial opportunity for Felix™, with the Board’s reassessment reinforcing the strategic case for establishing a credible pathway to market entry.
| Metric | Figure | Source | Context |
|---|---|---|---|
| US IVF market size (2025 estimate) | US$5.9 billion | Company announcement | Approximately 20% of global IVF market by revenue |
| US clinics providing ART services | Approximately 500 | Company announcement | Broad addressable clinic base for Felix™ |
| ART cycles reported (2022) | 435,426 | CDC national data | Reported across 457 reporting clinics |
Memphasys has framed the US as an additional long-term growth opportunity, layered on top of its existing commercialisation efforts, not a pivot away from current markets.
Commercial momentum in existing markets
The US regulatory programme is strategically ringfenced and progresses in parallel with the Company’s existing commercialisation activities, meaning it is not expected to redirect management focus or significantly impact near-term cashflow.
Memphasys’ immediate commercial priority remains accelerating Felix™ adoption and generating recurring cartridge revenue across its established markets. The Company continues to build its commercial footprint across Europe, Australia and New Zealand, Asia and MENA.
The Monash IVF supply agreement, covering a 22-clinic network that performed over 12,000 stimulated IVF cycles in FY2025, represents the largest individual Felix commercial deal executed to date and sits alongside the repeat orders from Europe and MENA as a concrete indicator of accelerating adoption.
Supporting that momentum, the Company has received additional repeat orders from existing partners and clinics across several markets:
- Repeat orders from Italy
- Repeat orders from the UK
- Repeat orders from MENA
These repeat orders provide further validation of Felix™ in clinical practice and reflect growing customer adoption and confidence in the technology.
Investment case: a capital-efficient pathway to one of the world’s largest IVF markets
The identification of a potential 510(k) predicate device represents a meaningful development in Memphasys’ US strategy, offering a potentially more efficient regulatory route into a US$5.9 billion market that accounts for approximately 20% of global IVF revenue by value. The disciplined, ringfenced approach reflects Board-level strategic judgement, preserving near-term commercial execution while establishing a longer-term pathway into the United States.
The next measurable milestone is the Pre-Submission (Q-Submission) engagement with the FDA, with a formal 510(k) submission targeted for Q1 CY2027, subject to the outcome of that engagement and completion of any additional work required.
David Tasker, Executive Chairman
“The Board’s reassessment of our US regulatory strategy has identified a potentially faster and more direct pathway for Felix™ into a US$5.9 billion IVF market representing around 20% of the global market. We will pursue this opportunity in a disciplined and ringfenced manner, while maintaining our immediate focus on driving Felix™ adoption and revenue across Europe, ANZ, Asia and MENA.”
The dual-track strategy positions Memphasys to continue converting its expanding global footprint into recurring Felix™ cartridge revenue in the near term, while progressing a potentially capital-efficient pathway into the US market over the longer term.
The Felix commercial rollout delivered A$111,600 in revenue across four regions during the March 2026 quarter, establishing a measurable baseline from which the US regulatory programme is being layered as an incremental longer-term opportunity rather than a near-term distraction.
Don’t Miss the Next Healthcare Breakthrough on ASX
Big News Blast delivers FREE breaking ASX healthcare and biotech news directly to your inbox within minutes of release, with in-depth analysis already done. Join 20,000+ investors who stay ahead of market-moving announcements the moment they drop. Click the “Free Alerts” button at StockWire X to start receiving alerts today.