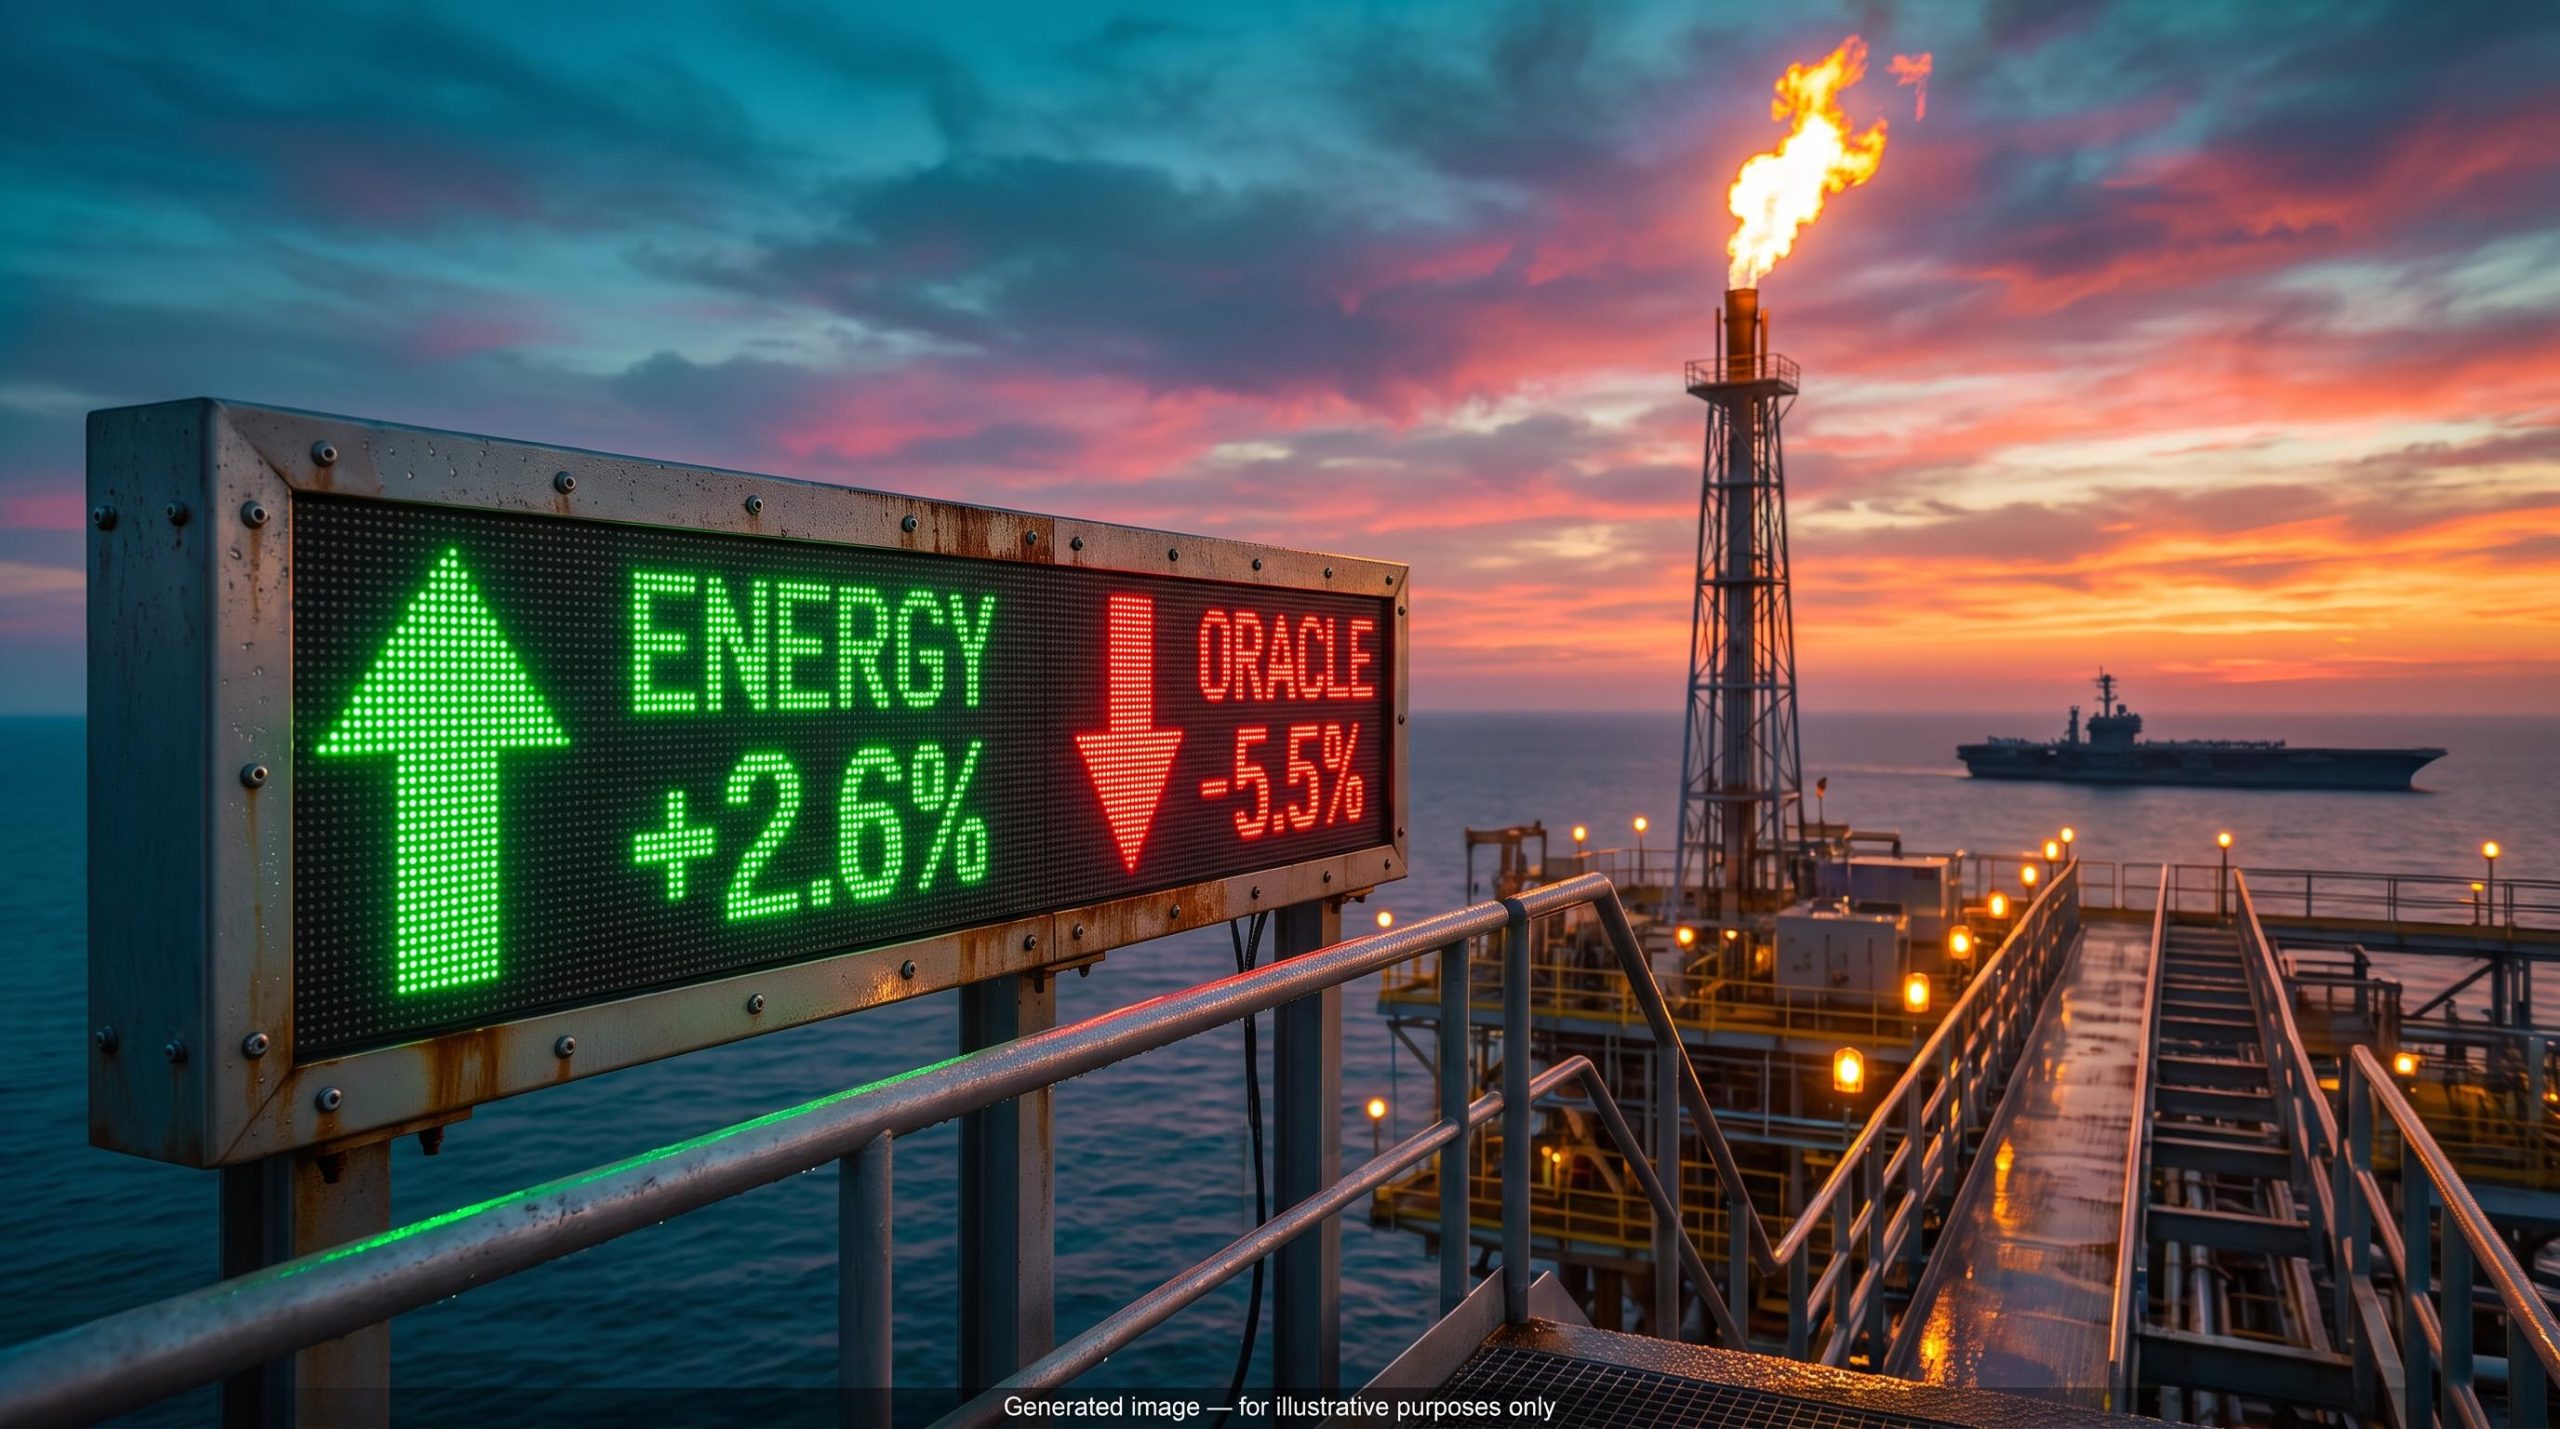
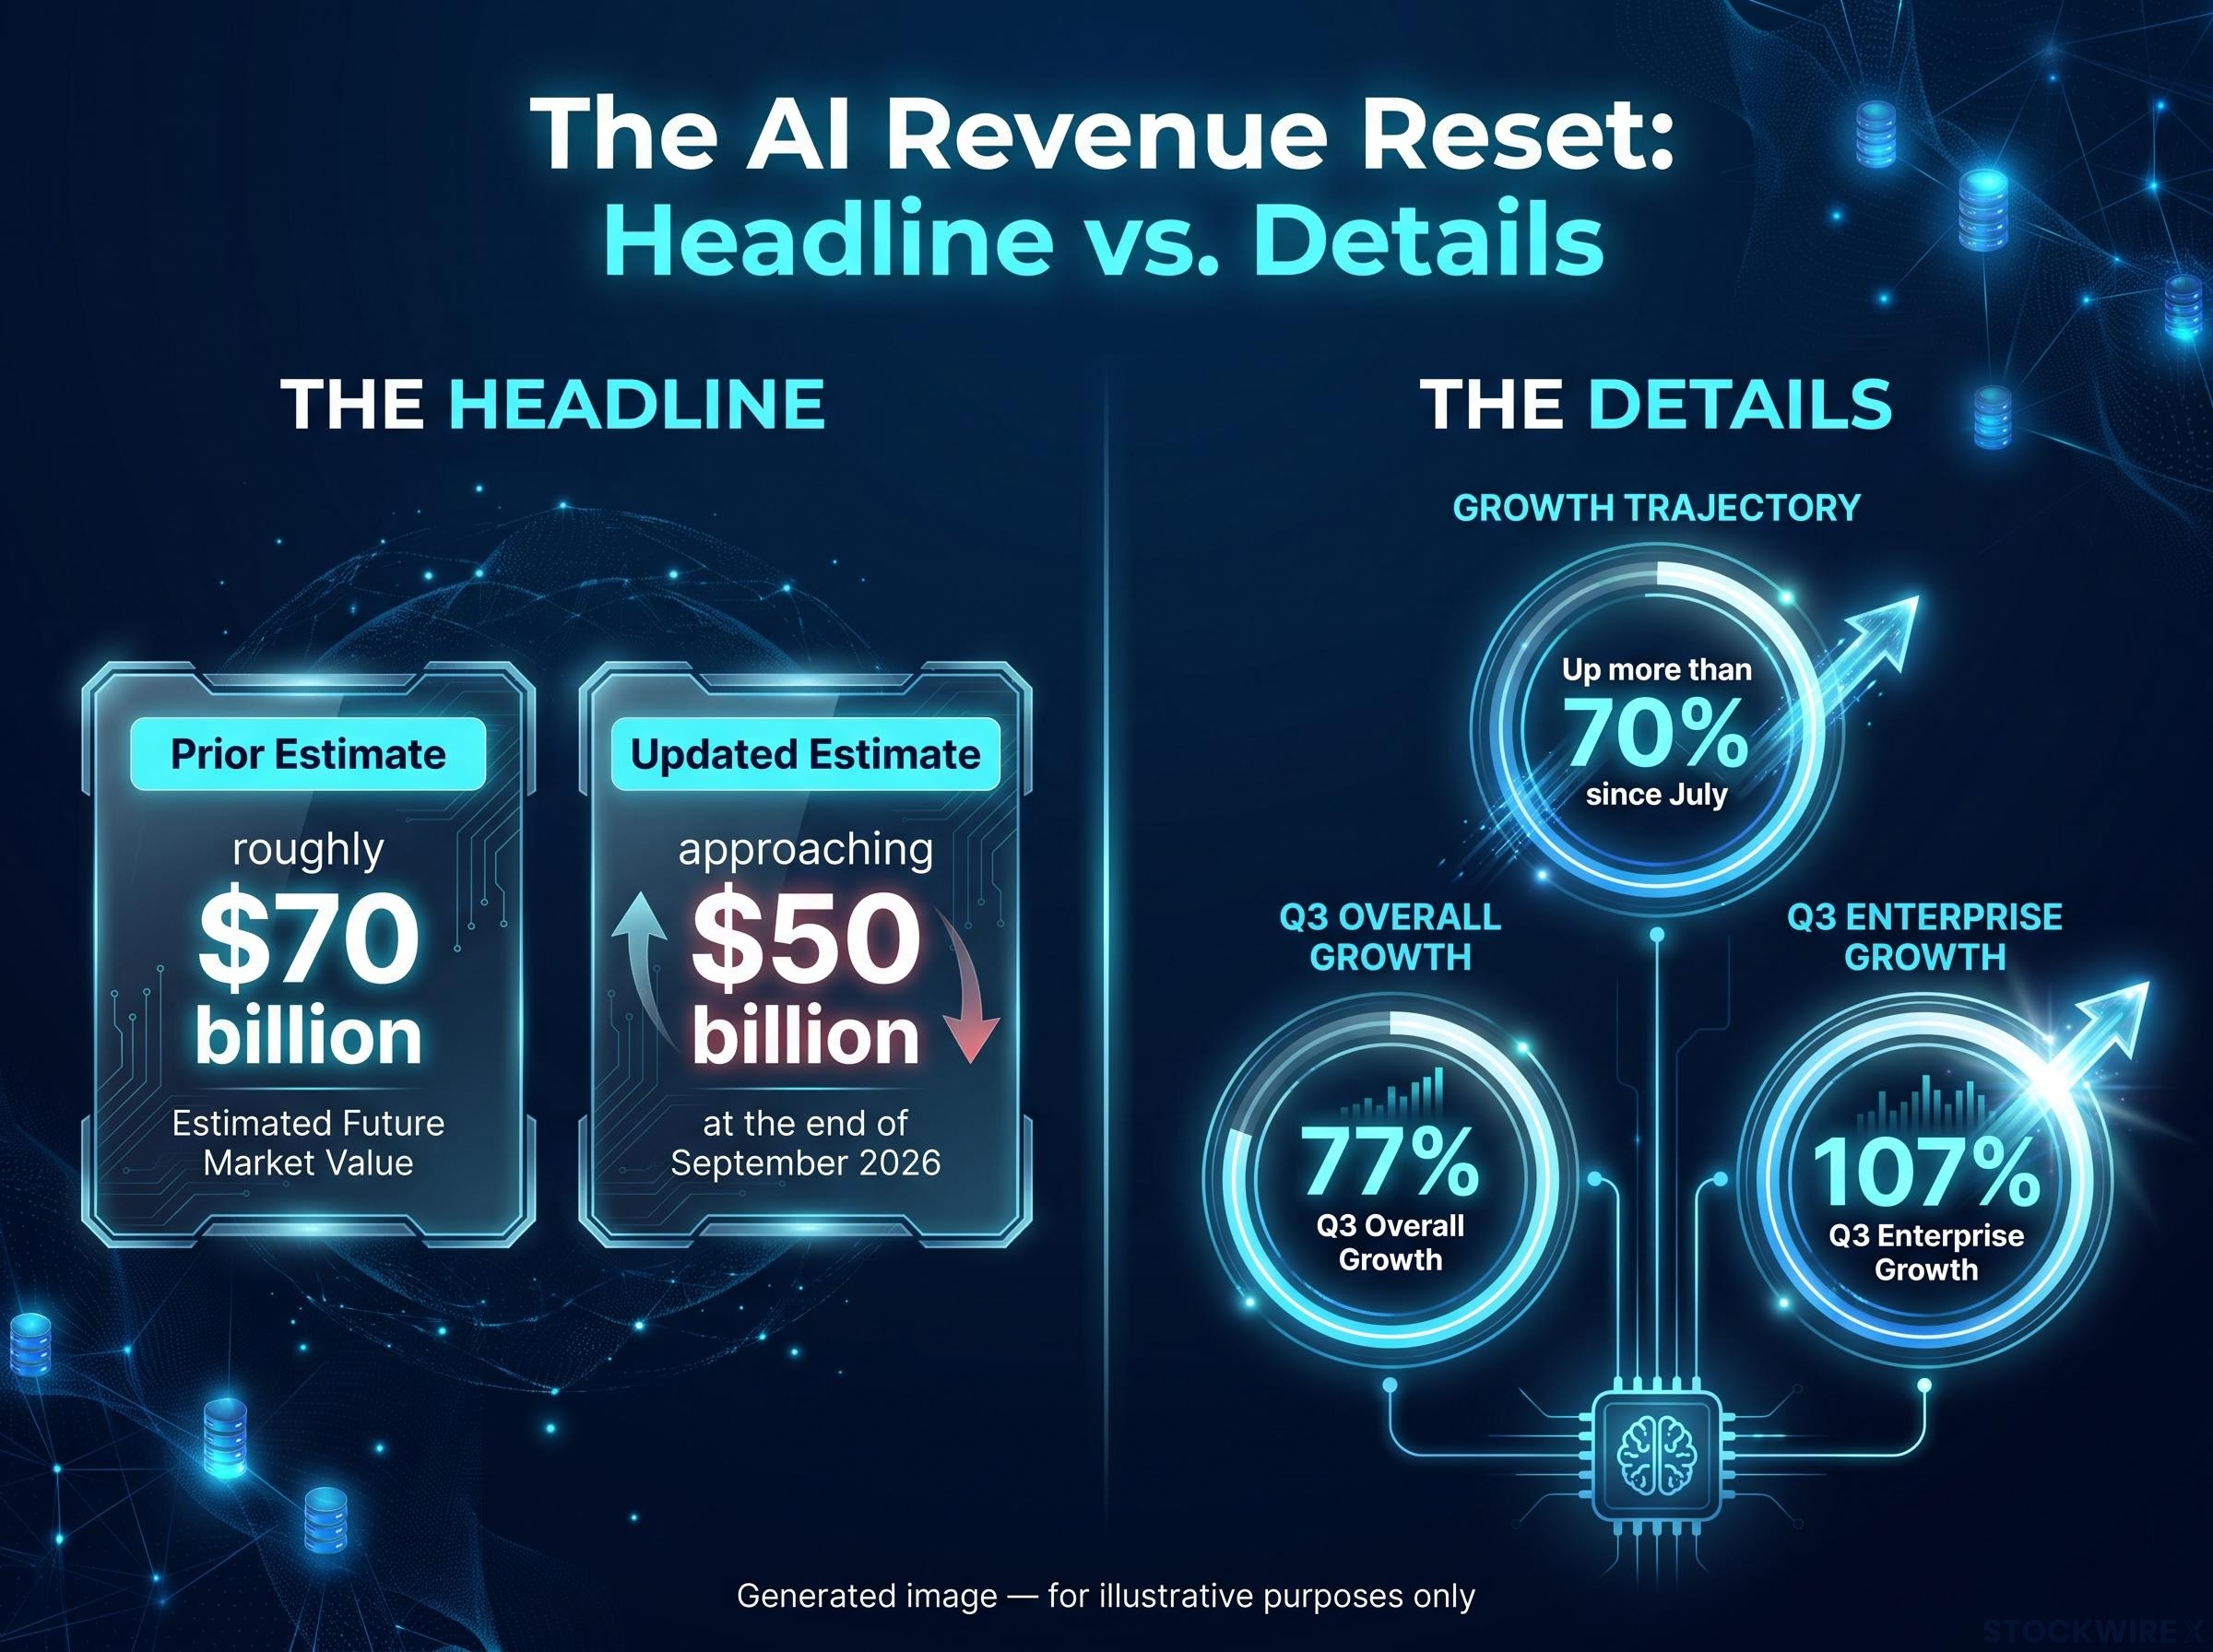
Investors woke up to a $20 billion hole in the AI story. A single Financial Times report put OpenAI’s annualised revenue near $50 billion, against the roughly $70 billion markets had been working with. Oracle fell 5.5% in a session where energy stocks rose 2.6%, the sharpest snapshot yet of a market rotation from tech to energy.
The question the tape could not answer was whether AI demand had collapsed, or whether the way that demand is counted had simply changed.
The same session carried Brent crude near $103 a barrel, a US 10-year Treasury yield of 5.23% and gold around $4,158. With US-Iran tensions still escalating in early October 2026, two forces were moving money at once, and reading either one alone gives you a distorted picture.
Here is how to separate the AI-sentiment signal from the geopolitical one, and how to judge whether this rotation is a rest stop or a regime change.
What did the OpenAI revenue reset actually change, and what did it not?
The numbers
The headline looks brutal. According to the FT, OpenAI told investors its annualised revenue was approaching $50 billion at the end of September 2026. Earlier investor materials and media reports had implied a run-rate of about $68-70 billion.
The reset in one line Prior figure: roughly $70 billion annualised. Updated figure: “approaching $50 billion“, per the Financial Times.
Then the detail arrives, and the picture softens. Revenue is still reported as up more than 70% since July. Third-quarter growth ran at 77% overall and 107% for enterprise customers, hardly the profile of a business losing its footing.
Two ways to read the gap
Benzinga’s summary of the FT piece explains how the higher figure was built: earlier estimates took a short burst of strong growth and annualised it, meaning they projected that pace across a full year. Rollingout and StartupFortune report the revision largely aligns OpenAI’s method with Anthropic’s more conservative approach.
The cautionary reading carries real weight too. CNBC and MarketWatch framed the episode as proof of how stretched AI valuation assumptions had become, and Ramp Economics Lab data suggests OpenAI has been ceding ground to Anthropic. That turns an accounting story into a competition story.
| View | Core Argument | Source | Implication for chips |
|---|---|---|---|
| Benign | Gap is methodological; growth remains above 70% since July | Benzinga, Mitrade | Infrastructure demand stays strong |
| Cautionary | Valuations assumed too much; Anthropic gaining share | CNBC, MarketWatch framing | Leadership fragments; multiples compress |
What this tells you is that a revised run-rate changes how much growth was priced in, not whether the demand exists. That is why a methodology change can still knock 5% off a stock. No confirmed IPO timing has emerged, so any valuation debate tied to a listing remains open.
Investors exploring what the missing listing timeline means can read our detailed coverage of OpenAI’s IPO delay, including the Foundation’s governance rights that would limit public shareholders.
When big ASX news breaks, our subscribers know first
How did one report move tech, energy and defensives in a single session?
The broad indices barely flinched. The S&P 500 slipped about 0.5%, while the Nasdaq fell about 1.2%. The Dow rose 0.2%.
That divergence widens at stock level:
- Nvidia fell 2.9%
- AMD dropped 3.9%
- Oracle lost 5.5%
Invezz reported slightly smaller moves (Nvidia about 2%, AMD about 3%), though the original session-close figures are the more precise. Meanwhile, the Moomoo sector heat map showed money landing elsewhere.
| Asset or Sector | Move | Role in the rotation |
|---|---|---|
| Nasdaq | -1.2% | Source of outflows |
| Energy | +2.6% | Primary destination |
| Defensives | +2.2% | Safety bid |
| Financials | +0.5% | Modest beneficiary |
| Copper | -1.2% | Traded with tech |
Losses on one side, gains on the other, roughly matched in size. That mirror image is what separates a rotation from a selloff: pressure concentrated in tech and semiconductors while the wider market held.
The Dow’s gain alongside the Nasdaq’s loss tells you capital moved within the market rather than out of it. Your exposure that mattered was concentration, not market direction, which points towards rebalancing rather than de-risking. Benzinga and Mitrade argue the reaction may prove overstated, a reminder that one session sets a direction, not a trend.
Capital moving within the market rather than out of it is the defining feature of a sector rotation strategy, where institutional money repositions across cyclical and defensive groups ahead of confirming economic data.
Why do oil, Treasury yields and gold matter to a tech selloff?
How the mechanism works
A tech stock’s price rests largely on profits expected years from now. To value those future profits today, investors apply a discount rate, which is the return they demand for waiting. When that rate rises, distant earnings are worth less in today’s money.
Oil reaches that discount rate through a chain:
- Oil prices rise, lifting fuel and transport costs.
- Inflation expectations climb as those costs spread through the economy.
- Long-term Treasury yields rise as bond buyers demand compensation for inflation.
- Higher yields lower the present value of long-duration growth stocks, those whose earnings sit furthest in the future.
The same chain supports energy producers, whose cash flows arrive now and rise with the oil price, and real assets such as gold. Saxo Bank has warned that prolonged disruption around the Strait of Hormuz keeps energy costs elevated and pushes long-term yields higher.
The escalation timeline
The session ran that mechanism live. Reports of Iranian attacks on ships, including a strike near Qatar, and Houthi attacks on Saudi airports sent Brent to about $106. It eased to near $103 after President Trump posted that he would not attack Iran before the US midterms.
The 10-year yield touched 5.35% before settling at 5.23%, helped by lower oil and a solid 30-year auction. Gold rose 0.4%, and the US has moved a third carrier into the Persian Gulf.
The 10-year’s climb toward 5.35% fits a wider structural repricing of long-dated Treasuries, driven by a rising term premium and persistent fiscal deficits rather than oil alone.
| Date | Brent | 10-year yield | Source |
|---|---|---|---|
| 13 July 2026 | ~$78.8 | ~4.6% | UBS Global Wealth Management |
| 1 September 2026 | Above $91 | ~4.78% | Saxo Bank |
| Early October 2026 | ~$103 | 5.23% | Original source |
These snapshots do not conflict; they trace a steady escalation. The pre-midterm pledge leaves post-election risk open, and UBS frames energy and gold as hedges for exactly this backdrop.
For you, the takeaway is that tech is being hit twice: once by a company-specific AI reset, and again by a rate environment that shrinks what future earnings are worth. The two effects compound.
Is this a lasting shift, or can semiconductors still lead again?
The chip data argues against the selloff. TSMC reported September revenue of NT$511.86 billion (about $16 billion), up 54.6% year on year and down just 0.6% from August. Q3 revenue reached NT$1.49 trillion (about $46.7 billion), and Proactive Investors says the result beat expectations by about 3%.
Strong print, weaker share price TSMC September revenue: up 54.6% year on year. TSMC’s US-listed ADR: down about 1.4%.
Coinpaper reads that fall as profit-taking and valuation concern, not disappointment with fundamentals. CNBC stresses that the demand behind the record month comes from a wide customer base, not OpenAI alone: hyperscalers, enterprises and model builders including Anthropic. The FT also reports China accelerating data centre build-out with open-weight models, though independent commentary on its effect on global chip demand was not found.
That breadth matters. If OpenAI’s lead narrows, the spending shifts between buyers rather than disappearing, which can keep chips and memory supported.
That breadth supports a structural demand floor under chip stocks, with the larger threat coming from hyperscaler capex cuts rather than shifts in who captures AI revenue.
The verdict is layered. The selloff looks like a cyclical de-rating of expensive AI names sitting on a more structural tilt toward real assets and defensives, which UBS describes as portfolio resilience in a higher-for-longer rate world. Energy is no one-way bet either: further escalation could hit broad risk appetite, energy included.
The evidence supports adjusting your weighting rather than abandoning the AI supply chain. Signals that would change the view:
- TSMC monthly sales turning lower
- The 10-year yield breaking higher, or falling back below 5%
- Brent reversing sharply in either direction
- Fresh Anthropic versus OpenAI share data from Ramp Economics Lab
Past performance does not guarantee future results, and these assessments are speculative and subject to change with market developments.
What the rotation changes, and what it leaves intact
The AI infrastructure cycle still looks intact, with TSMC’s numbers as the clearest evidence. What changed is the debate over who captures AI revenue and at what multiple. Layered on top, oil-driven yields and US-Iran risk are shifting marginal preference toward energy, gold and defensives.
Three variables will tell you which force is winning:
- Brent and the 10-year yield, moving together or apart
- TSMC’s next monthly revenue print
- Any post-midterm shift in US-Iran posture
If chip orders hold while yields ease, semiconductors have room to lead again. If oil and rates keep climbing, the tilt toward real assets is likely to deepen.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.