Malaysia’s exports jumped 54.5% year on year in September to a record monthly value. Over the same stretch, the ringgit barely moved, trading sideways around 4.08 per US dollar. That disconnect is the signal many readers miss when they form a view on the Malaysian ringgit outlook: spectacular trade numbers do not automatically produce a stronger currency.
The timing matters. Bank Negara Malaysia (BNM), the country’s central bank, holds its next policy meeting on Thursday, 5 November 2026. Meanwhile, Christopher Wong at OCBC notes that the ringgit held up well last week even as volatility returned to regional currency markets.
The useful skill here is reading trade, inflation, central bank and US dollar signals together rather than one at a time. Here is a framework for judging why the ringgit is steady, what BNM is likely to do, and where the real risk sits.
Why the ringgit is holding firm: trade strength and mild inflation
What the September trade data shows
The size of September’s surge is hard to overstate. According to the Department of Statistics Malaysia (DOSM), exports reached RM215.1 billion, up 54.5% year on year. Imports climbed 52.7% to RM181.4 billion, leaving a trade surplus of RM33.7 billion, up 64.9%.
77 months and counting September marked Malaysia’s 77th consecutive monthly trade surplus, a run that began in May 2020.
The nine-month picture is even larger. MATRADE puts the January-September cumulative surplus at RM232.38 billion, up 115.7%. Electrical and electronics (E&E) products, meaning semiconductors and related components, accounted for about 69.2% of total exports, according to Trading Economics citing DOSM, with manufactured goods up about 50.4%.
Why mild inflation matters for the currency
The second pillar is quiet prices. Headline inflation, measured by the consumer price index (CPI), eased to 1.8% in September from 1.9% in August. Core CPI, which strips out volatile items such as fresh food and fuel, held at 1.7%, below its 2021-25 average of 2.1%.
| Indicator | Latest reading | Comparison | Source |
|---|---|---|---|
| Exports (Sep 2026) | RM215.1bn | +54.5% year on year | DOSM |
| Trade surplus (Sep 2026) | RM33.7bn | +64.9% year on year | DOSM |
| Headline CPI (Sep 2026) | 1.8% | 1.9% in August | DOSM |
| Core CPI (Sep 2026) | 1.7% | 2.1% 2021-25 average | DOSM via The Star |
| International reserves | US$132.1bn | As at 15 October 2026 | BNM |
Together, these figures show a country earning more foreign currency than it spends and leaning less on foreign portfolio money to fund itself. What this tells you is that the ringgit has a solid external cushion. Treat it as a foundation for stability, though, not a guarantee of appreciation.
For readers wanting to test the reserves argument, our deep-dive into Asian reserve limits shows why large buffers have not stopped regional currency pressure in 2026.
When big ASX news breaks, our subscribers know first
How currencies respond: trade, rates, policy and the US dollar
So why does a record surplus sit alongside a flat currency? Because trade is only one of several forces acting on an exchange rate at once.
The four forces behind USD/MYR
USD/MYR is quoted as ringgit per US dollar, so a lower number means a stronger ringgit. Four drivers do most of the work:
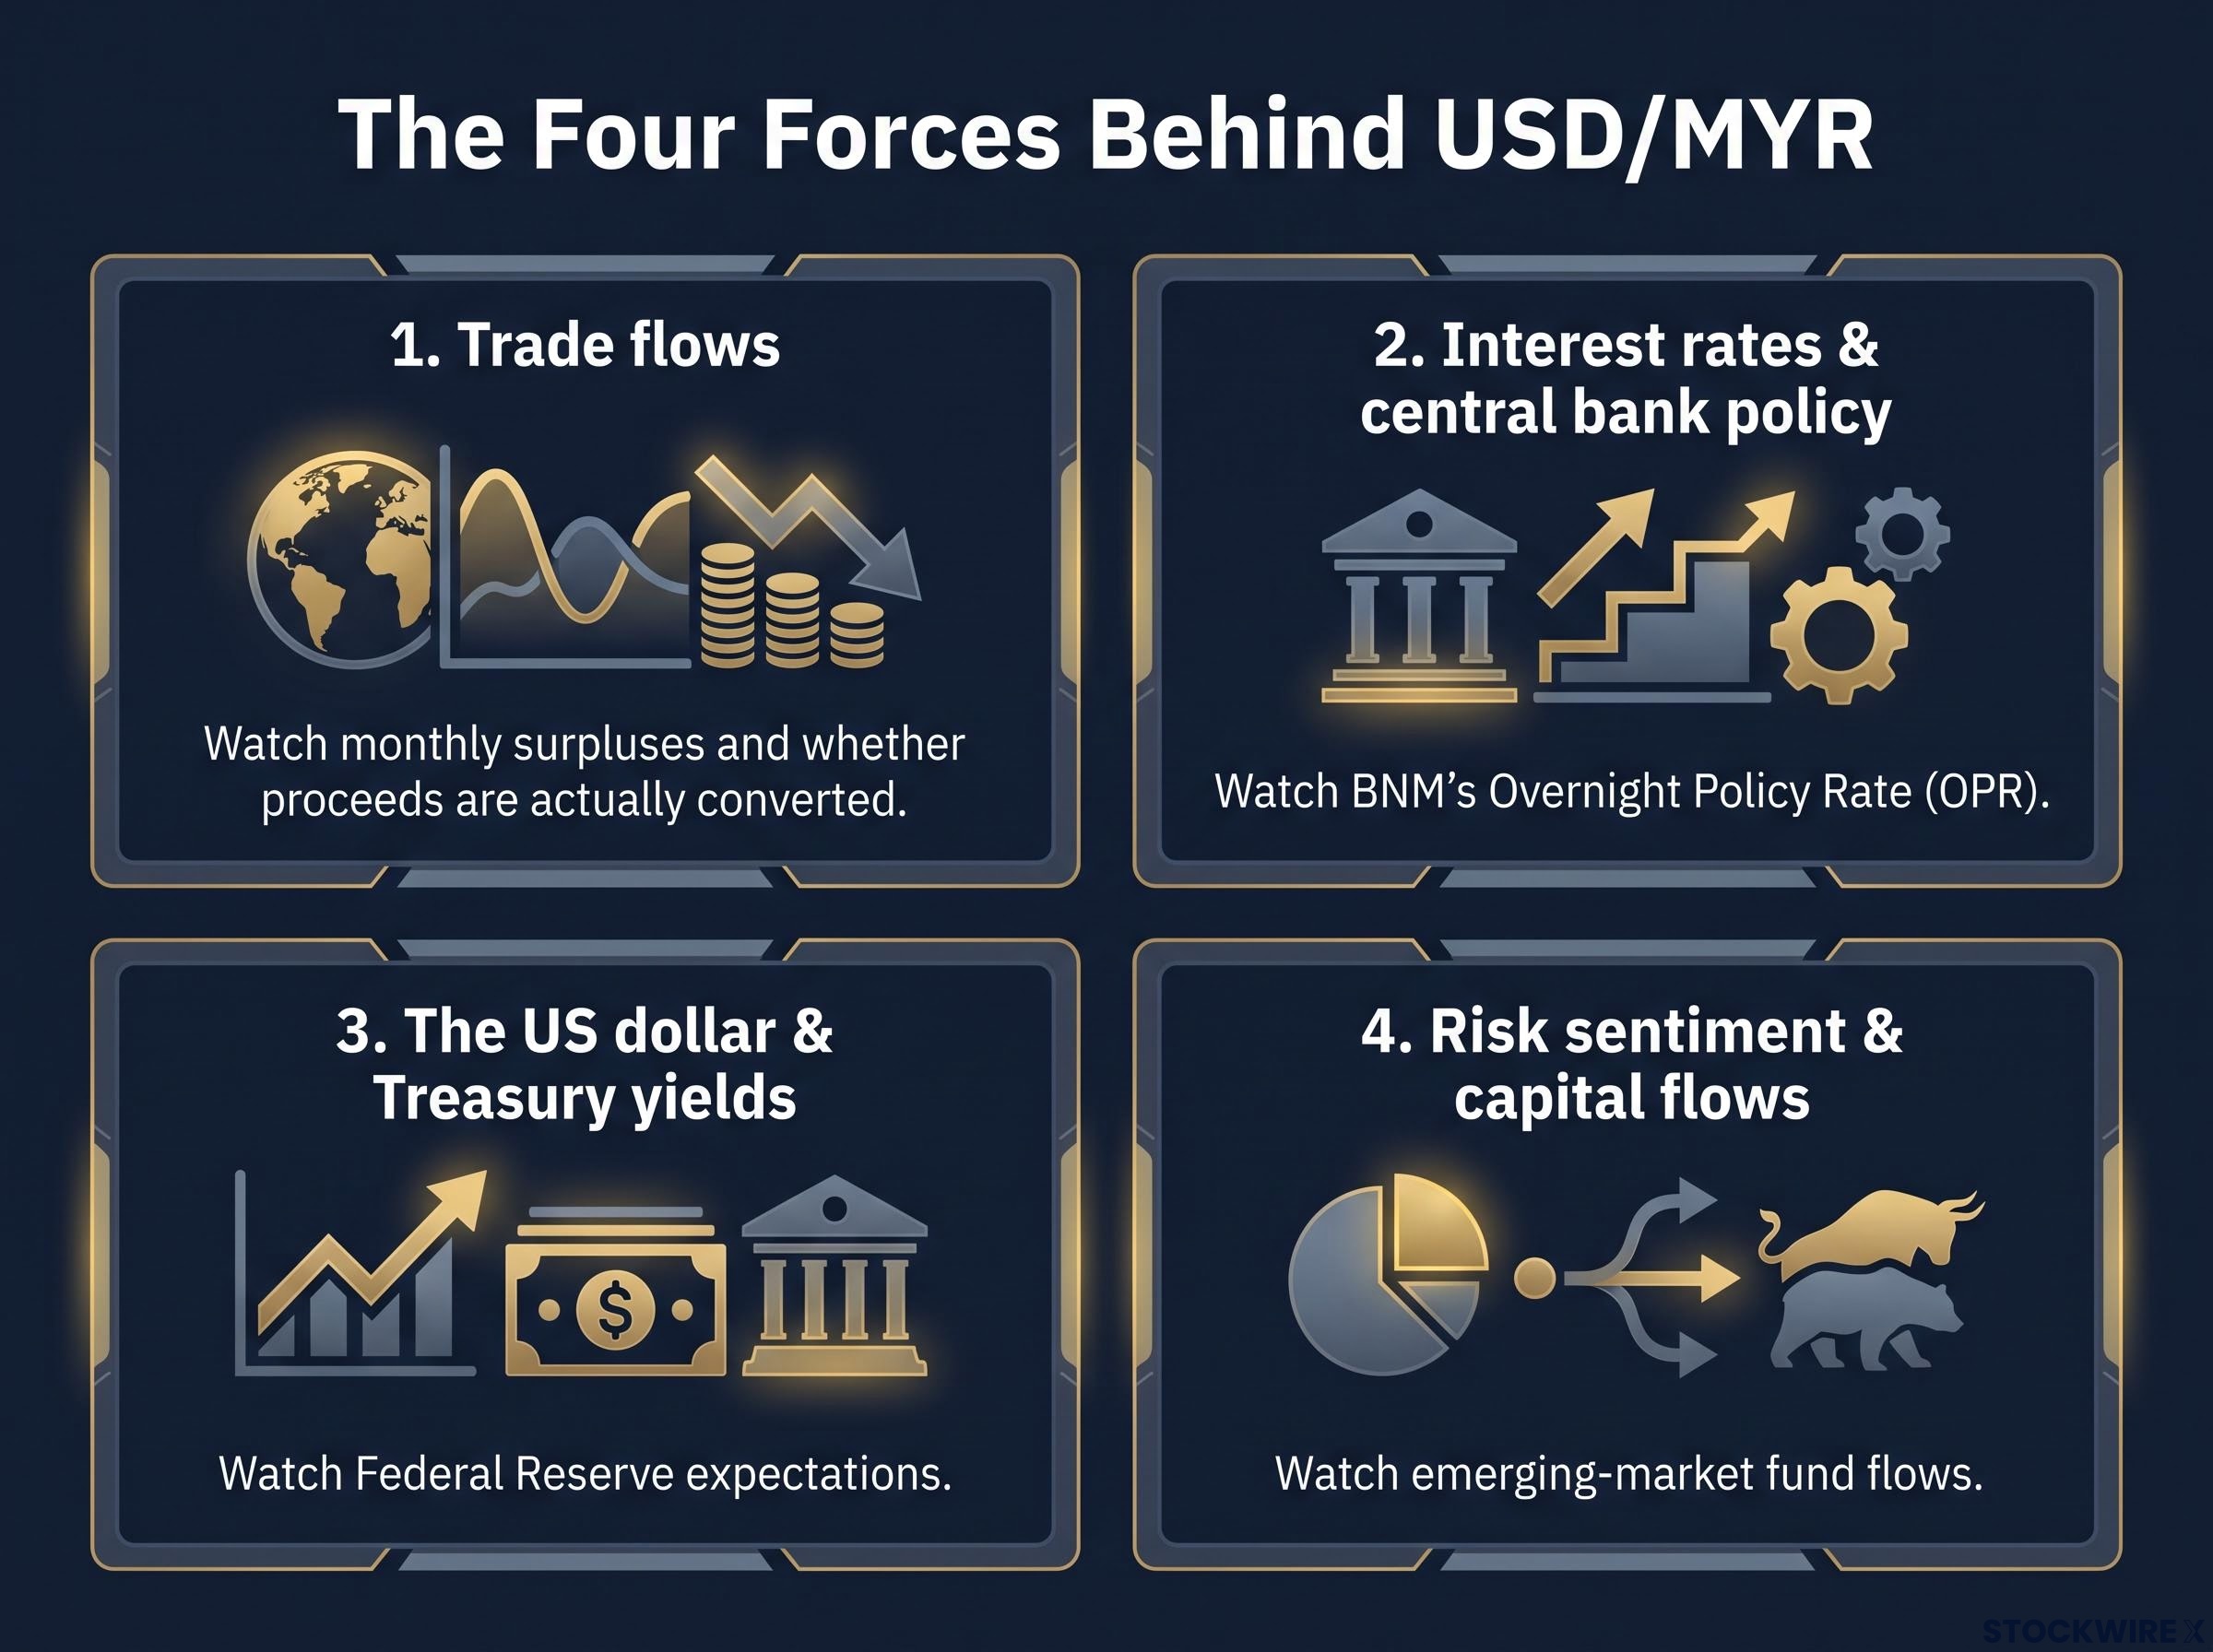
- Trade flows. Exporters selling foreign currency for ringgit add demand. Watch monthly surpluses, but also whether proceeds are actually converted.
- Interest rates and central bank policy. Higher local rates relative to the US can attract capital. Watch BNM’s Overnight Policy Rate (OPR), the benchmark rate it sets for overnight lending between banks.
- The US dollar and Treasury yields. A broadly stronger dollar or higher US government bond yields pressure Asian currencies. Watch Federal Reserve expectations.
- Risk sentiment and capital flows. Global appetite for risk shapes foreign buying of Malaysian stocks and bonds. Watch emerging-market fund flows.
BNM itself treats the ringgit as market-determined and uses the OPR, not the exchange rate, as its policy tool. That leaves the currency exposed to all four forces simultaneously.
Where the ringgit has felt each force in 2026
The dollar side has already shown its weight. In September, OCBC’s Wong observed that firmer US yields and a stronger dollar briefly pushed USD/MYR above 4.10, with nothing in Malaysia’s own data driving the move.
Wong’s current view is that near-term direction depends mostly on broader dollar moves and risk sentiment. UOB describes emerging-market flows as volatile and uneven, which explains why steadiness in the ringgit is itself a modest achievement right now.
Firmer yields and elevated oil prices have been putting pressure on Asian currencies through several reinforcing channels at once, which helps explain why a steady ringgit is a more modest achievement than it first appears.
The lesson for you is practical. When a strong trade print lands, count it as one input among four, and check the dollar and yield backdrop before assuming the ringgit will follow.
Why BNM has little reason to move on 5 November
The policy side of the equation points firmly towards patience.
The case for holding at 2.75%
The OPR stands at 2.75% after a 25 basis point cut on 3 September 2026 (a basis point is one-hundredth of a percentage point). Reversing that cut within two months would be an abrupt change of course. Inflation at 1.8%, moderating domestic demand and a trade surplus that creates no urgent pressure all argue against it.
The BNM Monetary Policy Statement of 3 September confirms the Monetary Policy Committee’s decision on the Overnight Policy Rate, which is the baseline any November change would have to depart from, and it gives you the official wording to compare against.
Most institutions agree. OCBC sees little pressing need to alter policy, while CIMB points to softer seasonally adjusted momentum in manufacturing and services.
| Institution | OPR call | USD/MYR view | Key reasoning |
|---|---|---|---|
| RHB | Unchanged at final 2026 meeting | 4.05 end-2026; 3.98 end-2027 | Contained inflation, growth and current-account surplus |
| CIMB | No change until 2027 | Not specified | Contained inflation, softer momentum |
| MUFG | Held through Q3 2027 | 4.03 end-2026; 3.98 Q3 2027 | Electronics exports, external accounts, valuations |
| ANZ Research | 25 bp hike in November | Not specified | Growth momentum extending into 2027 |
The dissent: ANZ’s hike call
ANZ Research expects a 25 basis point hike, arguing that growth momentum could carry into 2027 and justify tightening before inflation builds. The split is less about the data than about weighting: low inflation favours a hold, strong growth favours a pre-emptive move.
For you, a hold is the base case, so it would confirm expectations rather than act as a catalyst. A surprise hike is the outcome that could genuinely shift USD/MYR, likely in the ringgit’s favour.
The catch: record exports do not guarantee ringgit buying, and the range to watch
Here the comfortable story starts to crack.
Why export earnings may not become ringgit demand
Under BNM’s foreign exchange rules, exporters must bring proceeds home within six months of shipment, with extensions of up to 24 months in specified cases. They no longer have to convert them. The earlier 75% conversion requirement has gone, and up to 100% can sit in an onshore Trade Foreign Currency Account (Trade FCA), a local bank account held in foreign currency.
Repatriation is not conversion Bringing dollars into Malaysia strengthens the external balance. Only selling those dollars for ringgit creates direct demand for the currency.
Export earnings support the ringgit only when exporters:
- convert repatriated foreign currency into ringgit;
- pay local wages, suppliers, taxes or dividends in ringgit; or
- place proceeds domestically in a way that generates ringgit demand.
From today, 26 October, exporters can also sweep proceeds automatically into Trade FCAs to cover up to six months of foreign-currency obligations established with their onshore bank. RHB cautions that a current-account surplus does not guarantee appreciation for exactly this reason. OCBC commentary points to Taiwan, where strong September export orders came without enough foreign inflows to lift the currency.
The range to watch and what could break it
BNM’s reference rate was 4.0841 on 23 October. OCBC expects USD/MYR to hold 4.08-4.09 within broader limits of 4.0760-4.0950, with flat daily momentum and a rising relative strength index (RSI), a gauge of recent price momentum. UOB’s wider range runs from about 4.00 to 4.10.
- A dollar and yield rebound pushing USD/MYR back above 4.10.
- An electronics downcycle weakening the E&E engine.
- Base effects, as a 54.5% rise makes future annual growth likely to slow.
- Higher oil prices, which MUFG flags as a risk.
- Fiscal and fuel-subsidy concerns weighing on sentiment.
What this means for you is that the ringgit may react less to trade headlines than the numbers suggest. Range levels and dollar moves are better guides than export growth rates.
These views are forward-looking and subject to change. Past performance does not guarantee future results, and forecasts depend on market conditions and other risk factors.
What the data supports, and what to watch before 5 November
The most defensible read is sideways-to-firm trading near 4.08-4.09, with BNM holding at 2.75% as the base case. Strong exports, mild inflation and deep reserves explain why the ringgit is stable. The conversion gap and the US dollar will decide how far it actually moves.
Before the meeting, three signals deserve your attention:
- The tone of BNM’s statement, especially any hint that growth is shifting its bias towards tightening.
- US yields and the dollar, the force most likely to break the range in either direction.
- Evidence of exporters converting proceeds, which would finally turn trade strength into ringgit demand.
If all three line up, the ringgit has room to firm. If they diverge, expect the range to hold.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.