The Indonesian rupiah swung from 17,990 to 17,760 per dollar in the space of three weeks. The catalyst was not a rate decision. It was a resignation, an acting governor’s first public pledge, and a presidential nomination, all landing within days of each other at Bank Indonesia (BI).
That sequence sits on top of a monetary policy story that moved just as fast. BI compressed 100 basis points of tightening into roughly two months between May and June 2026, then stopped. The August 19 rate decision is expected to confirm a second consecutive hold at 5.75%, the first meeting formally presided over by acting governor Destry Damayanti after Perry Warjiyo’s unexpected departure in late July.
Here is a clear investor read on what the rate hold and leadership change actually mean for the rupiah, Indonesian bonds, and equities, stripped of the headline noise. By the end, you will know whether these developments change your thesis on Indonesian assets or simply confirm what the market has already priced.
A 100 bps sprint, then a deliberate pause
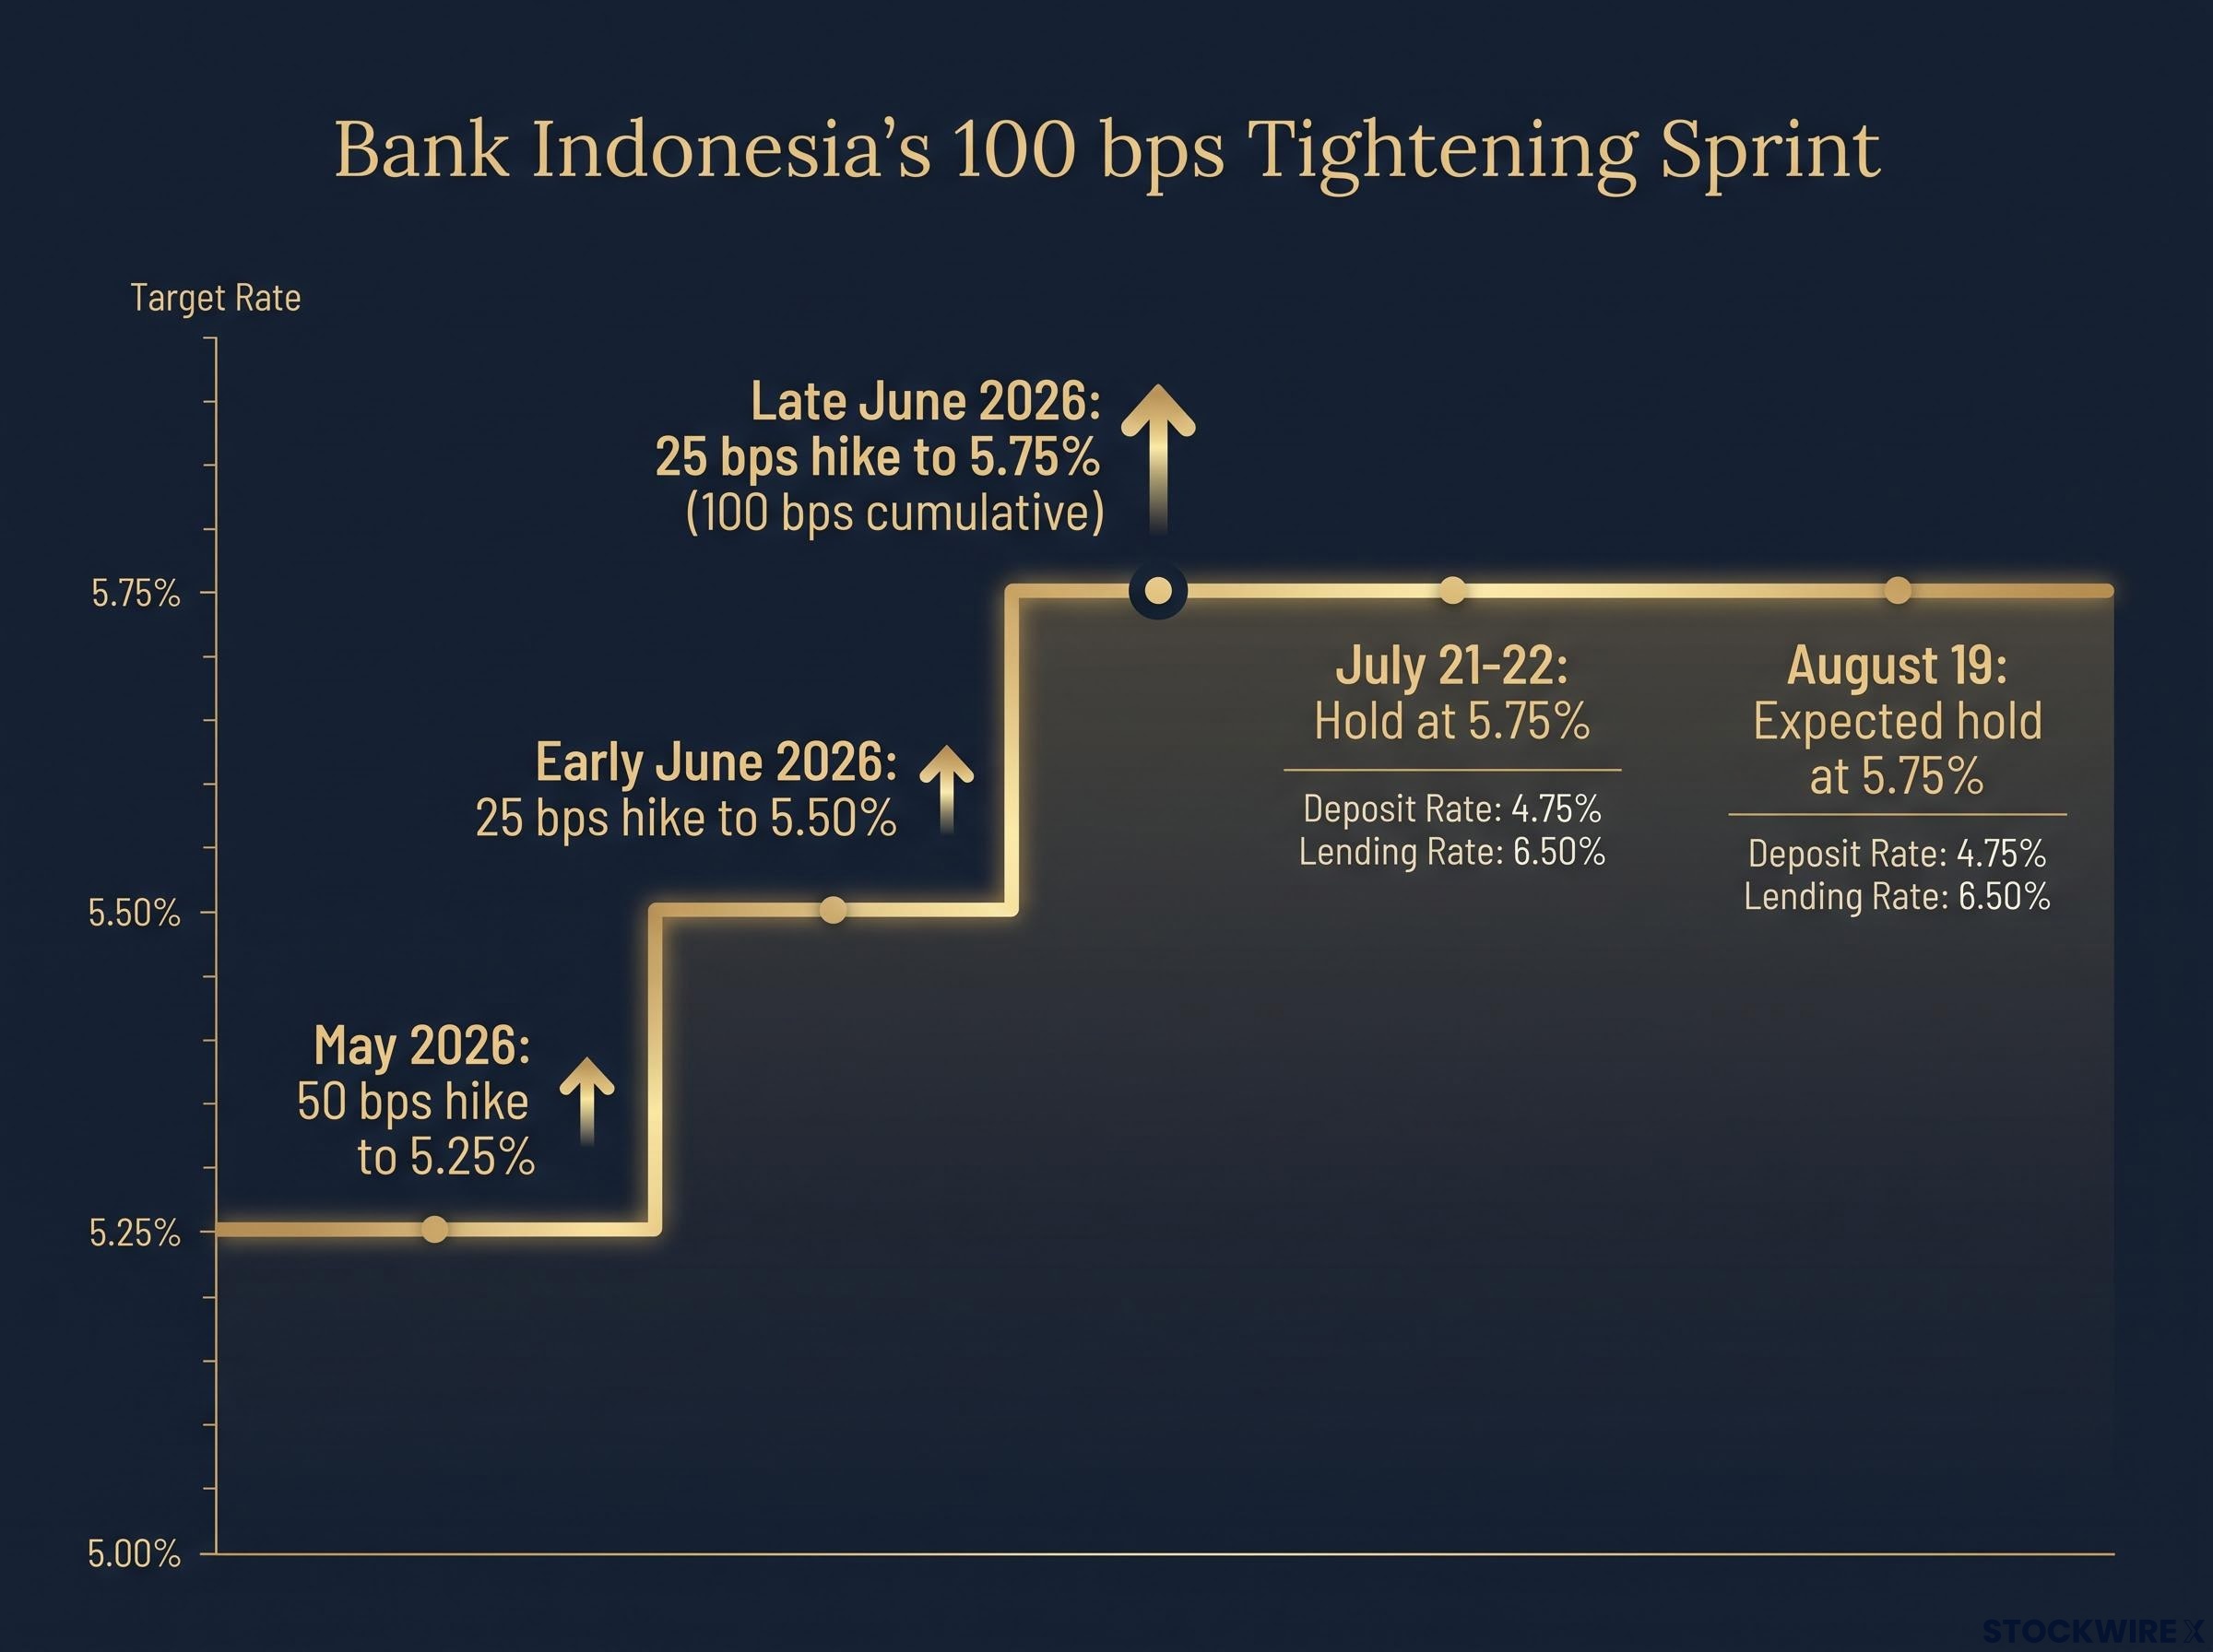
The tightening cycle that brought BI to 5.75% was compressed, front-loaded, and unmistakably urgent. The sequence unfolded in three steps:
- May 2026: BI raised the BI-Rate by 50 bps to 5.25%, the first move in the cycle and the clearest signal that rupiah weakness had reached a threshold the central bank was no longer willing to tolerate.
- Early June 2026: A second hike of 25 bps brought the rate to 5.50%, maintaining the pressure.
- Late June 2026: A third hike of 25 bps completed the sprint at 5.75%, delivering a cumulative 100 bps of tightening in approximately two months.
That pace tells you something about how seriously BI viewed the rupiah’s slide. Central banks do not front-load like this unless the currency pressure warrants an emergency-pace response.
The May 2026 hike that opened the cycle was not designed primarily as an inflation response; it was a rupiah defence move that simultaneously triggered an Asian tightening cycle, with Goldman Sachs projecting South Korea, India, and Taiwan to follow in H2 2026 as dollar strength and Hormuz-linked energy costs compressed emerging market buffers across the region.
Bank Indonesia’s May 2026 rate decision confirmed the 50 bps lift to 5.25% alongside an explicit rupiah stability mandate, establishing the policy logic that carried through the subsequent two hikes and the eventual hold.
Then came the pivot. At the 21-22 July Board of Governors Meeting, BI held at 5.75%, maintaining the Deposit Facility Rate at 4.75% and the Lending Facility Rate at 6.50%. The hold was not indecision. It was a deliberate shift in mode.
Analysis from Elias Haddad of Brown Brothers Harriman frames the current stance as a watchful, data-dependent pause, with the tightening work largely complete and further moves contingent on incoming data rather than pre-committed.
The August 19 meeting is expected to confirm a second consecutive hold, reinforcing that the tightening phase is closed. For investors pricing the forward path, the implication is straightforward: BI has exhausted its near-term tightening case, which means the next policy surprise is more likely to be an easing than an additional hike.
When big ASX news breaks, our subscribers know first
What Bank Indonesia’s rate hold actually signals about rupiah stability
The hold at 5.75% is not inaction. It is a substitution: BI is replacing further rate hikes with a suite of non-rate tools designed to stabilise the rupiah while keeping monetary conditions from tightening further into the real economy.
The toolkit BI is actively deploying includes:
- FX intervention channels: BI operates across spot, Domestic Non-Deliverable Forward (DNDF), and Non-Deliverable Forward (NDF) markets. These are the instruments BI uses to buy or sell rupiah directly, smoothing volatility without moving the policy rate.
- SRBI (Sekuritas Rupiah Bank Indonesia): A central bank security used to manage liquidity in the banking system, attract foreign portfolio inflows, and discourage banks from simply parking excess funds at the central bank rather than lending.
- Macroprudential incentives: Regulatory tools that direct bank lending toward productive sectors, using BI’s supervisory role to shape credit conditions without rate changes.
For anyone watching the rupiah, the hold only holds up as credible if these tools are doing real work. The mid-August USD/IDR level near 17,800 suggests they are; the currency has stabilised well inside the 18,000 zone that triggered intervention rhetoric earlier this year.
Inflation below target gives BI room to stay put
The domestic permission structure for holding is straightforward. Consumer price inflation is running comfortably within BI’s 1.5%-3.5% target band. That removes the one scenario that would force BI’s hand regardless of currency dynamics: if inflation were breaching the ceiling, a hold would be untenable.
BI’s own communication frames the current stance as a balance between price stability, FX stability, and growth support. With all three in acceptable range, the central bank has earned the space to pause.
Destry Damayanti and what a continuity governor means in practice
Destry Damayanti brings a CV that markets read as institutionally embedded rather than politically installed:
- Senior Deputy Governor at BI since 2019, reappointed in 2024
- Former Chief Economist at Bank Mandiri, Indonesia’s largest state-owned bank
- Prior roles at Citibank and the Indonesia Deposit Insurance Corporation
- Present inside the room for every rate decision during the 2026 tightening cycle
The transition itself moved quickly. Perry Warjiyo stepped down in late July 2026, with roughly two years still remaining on his second five-year term. His exit came without warning. The Board of Governors immediately appointed Destry as acting governor under BI’s governing law, and President Prabowo Subianto nominated her as the sole candidate for the permanent role, sending the nomination to parliament with the backing of his legislative majority.
If confirmed, she would become the first woman to permanently lead BI.
Destry has consistently stressed that BI will maintain its existing policy mix: prioritising rupiah stability, keeping inflation within target, and supporting growth through macroprudential tools and money-market instruments.
The “continuity candidate” framing is not just reassuring language. Destry was the principal deputy throughout the tightening cycle, co-designing the framework that produced the 100 bps sprint and the subsequent hold. Investors are not dealing with an unknown quantity. They are dealing with the person who helped build the current architecture. That said, accepting the market’s positive verdict at face value without understanding the credentials behind it would be a mistake in any emerging market leadership transition.
How Indonesian assets moved, and what the sequence reveals
The rupiah’s three-act response to the leadership transition reveals what markets were actually pricing at each stage, not just what happened.
| Stage | Event trigger | USD/IDR level | Market interpretation |
|---|---|---|---|
| 1. Initial shock | Warjiyo’s resignation | ~17,990-18,000 | Institutional risk premium; concern over policy continuity and central bank independence |
| 2. Stabilisation | Destry’s acting governor pledge, FX intervention commitment | Capped near 18,000 | Immediate reassurance that the policy mix would not shift; intervention tools deployed |
| 3. Relief rally | Sole governor candidate nomination by Prabowo | ~17,760 (seven-week high) | Leadership continuity confirmed; rupiah outperformed most Asian currencies |
As of mid-August, USD/IDR is trading near 17,800, supported by the combination of policy continuity, BI’s active toolkit, and global dollar softness. The sequence tells you that the market’s primary concern was not the rate level but institutional continuity. Destry’s nomination resolved that concern faster than the rate policy itself could.
The USD/IDR technical setup heading into the August 19 meeting reflects the dual catalyst that drove the pair from 18,279 to the 17,760-17,803 range: a U.S. payroll miss that weakened the dollar broadly, combined with the leadership clarity that removed the institutional risk premium markets had priced into the rupiah over the preceding weeks.
What the bond market is pricing beyond the rate hold
Fixed-income dynamics are responding to the broader policy mix rather than the headline rate alone. BI’s use of SRBI and macroprudential incentives shapes bank demand for government securities directly, discouraging banks from passively holding central bank instruments and nudging them toward government paper and lending.
For bond investors, the duration trade depends on how quickly global yields move relative to BI’s cautious hold. Foreign inflow incentives are explicitly designed to deepen local market demand for Indonesian government bonds, which means supply-demand technicals could tighten even without a rate cut.
Investor implications across rupiah, bonds, and equities
Each asset class carries a distinct read under the current policy configuration.
| Asset class | Policy rate impact | Primary risk driver | Investor implication |
|---|---|---|---|
| Rupiah (IDR) | Hold supports carry but does not drive direction | Global dollar strength, risk sentiment, commodity prices | BI will lean against moves toward 18,000 but cannot insulate from external shocks |
| Bonds | 5.75% nominal carry attractive versus developed markets | Global yield trajectory and BI liquidity operations | Carry plus duration trade; watch SRBI issuance and bank demand shifts |
| Equities | Stable rates support rate-sensitive sectors | Sector-specific: domestic policy for banks/property; global cycles for exporters | Differentiate between domestically anchored names and commodity-exposed exporters |
Within equities, the sector-level implications diverge:
- Banks: Benefit from BI’s explicit encouragement to lend more, predictable funding costs, and reduced FX volatility risk
- Property: Benefits from rate and FX predictability, which supports mortgage demand and construction financing
- Exporters and commodity names: Remain primarily exposed to global commodity cycles; a stable rupiah reduces translation risk but does not drive earnings
The common thread across all three asset classes is that domestic policy risk has been substantially reduced for now. That shifts the analytical weight toward external variables: U.S. rate expectations, commodity prices, and global risk appetite are the primary drivers to model, not BI’s next rate decision.
U.S. trade policy uncertainty has also shifted structurally in 2026, with federal courts dismantling the broadest pillars of executive tariff authority in ways that reduce the binary executive-shock risk that periodically drives dollar strength and emerging market capital flight, though the migration toward a slower legislative model creates a different category of prolonged uncertainty for Asian exporters and their currencies.
Regional central bank divergence sharpened through mid-2026 as the Bank of Japan raised its overnight rate to a 31-year high in June while BI was simultaneously completing its own tightening sprint, creating a differentiated policy landscape across Asia that reshapes carry trade dynamics and cross-border capital flows for investors positioned across multiple Asian markets.
Three risks that could break the hold narrative
None of these risks are imminent, but each has a visible trigger and a clear BI response pattern. That makes them monitorable rather than unknowable.
- Sharp rupiah weakness. A return toward 18,000 driven by renewed dollar strength or a geopolitical shock could revive BI’s tightening bias. BI has already demonstrated willingness to intervene aggressively at prior record lows, and if intervention alone proves insufficient, a rate response becomes the backstop.
- Growth disappointment. A sharper-than-expected domestic slowdown is the plausible pathway to an eventual easing pivot, but only once BI is confident that FX and inflation risks are sufficiently contained. The preconditions for a cut are clear: stable currency, inflation within target, and evidence that growth needs support the rate hikes cannot provide.
- Institutional friction. BI-government relations and central bank autonomy remain a structural risk to monitor. Destry’s nomination has reassured markets so far, but recent reporting has flagged scrutiny of BI policies under new leadership. The parliamentary confirmation process and any early signals on the government-central bank dynamic will shape whether this risk stays dormant or becomes live.
What the stability narrative means for investors watching the next cycle
BI’s tightening cycle is effectively complete, and the hold is durable in the near term. Destry Damayanti’s continuity profile has resolved the leadership uncertainty faster than the market feared, with rupiah stability locked in as the primary policy objective. Indonesian assets now compete on yield and institutional stability rather than rate policy volatility, repositioning them within the emerging market universe as a relative safe harbour from central bank risk.
The three variables that would signal a shift in that positioning are specific enough to track:
- USD/IDR trajectory relative to the 18,000 threshold, the level at which BI’s intervention rhetoric has historically escalated
- Global yield movements relative to BI’s 5.75% hold, which determine whether Indonesian carry remains attractive or compresses
- Destry’s parliamentary confirmation and any early signals on BI-government relations, which shape the institutional risk premium markets are currently discounting
The argument is not simply that a hold is expected. It is that the hold, combined with the leadership resolution, repositions Indonesian assets in the emerging market risk spectrum. The question now is whether that positioning holds through the next phase of the global cycle.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Forward-looking statements regarding Bank Indonesia’s policy path are subject to change based on economic conditions, currency dynamics, and institutional developments.