Dallas Fed President Lorie Logan said on Tuesday that the Federal Reserve still has work to do, calling for further Fed rate hikes at a quicker tempo than markets had assumed. “It remains clear to me, given the current outlook, that the FOMC needs to implement at least two more 25-basis-point rate increases,” she said.
The dollar gained against every major currency on the same day. With the federal-funds target range at 3.75%-4.00% and October consumer prices coming in hotter than expected, Logan’s remarks landed in a market already leaning hawkish. Hawkish means favouring higher interest rates to control inflation.
She was not the only driver. Governor Christopher Waller’s comments and the October Consumer Price Index (CPI) report also pushed rates and currencies around.
Here is what her case means for the path of rates, for the dollar and for your portfolio in the weeks before the December meeting.
Why Logan says the Fed funds rate is still at least 50 basis points too low
Logan made her case at the 11th joint energy conference hosted by the Dallas and Kansas City Fed banks in Houston, in a speech titled Economic and monetary policy outlook. Her call was blunt.
Lorie Logan, President, Federal Reserve Bank of Dallas “It remains clear to me, given the current outlook, that the FOMC needs to implement at least two more 25-basis-point rate increases.”
She went further on timing: “It may be possible to move more rapidly this winter than the FOMC has moved so far this fall.” The argument behind that line rests on a diagnosis built in four steps:
- Inflation: “trending meaningfully higher than the 2% goal,” and broad rather than confined to war-related energy disruption or tariffs. September PCE inflation ran at 3.6%, with core at 3.1%.
- Growth: strong, carried by solid consumer spending and firm business investment.
- Labour market: “balanced and perhaps tightening a bit.”
- Policy stance: the target range sits at least 50 basis points below the level that would be modestly restrictive.
She put the real Fed funds rate, the policy rate after subtracting inflation, at about 78 basis points. In her reading, that is not tight enough to pull inflation back to target.
That tells you one FOMC voice sees today’s range as still accommodative. In her view, a December hike may be a floor, not a ceiling.
What she wants after the hikes
Logan is not arguing for an open-ended campaign. “After two more increases are in place, it would make sense in my view to pause and examine economic and financial developments to determine what further action may be appropriate,” she said.
Gradual steps, she argued, can lower the risk of an abrupt slide in activity. The aim is policy that is “modestly restrictive so we can sustainably deliver both maximum employment and stable prices.”
When big ASX news breaks, our subscribers know first
How the dollar and Treasury yields reacted
The breadth of the dollar’s move stood out. FXStreet’s daily heat map showed the US dollar higher against all seven major currencies, with the biggest gain against the Australian dollar.
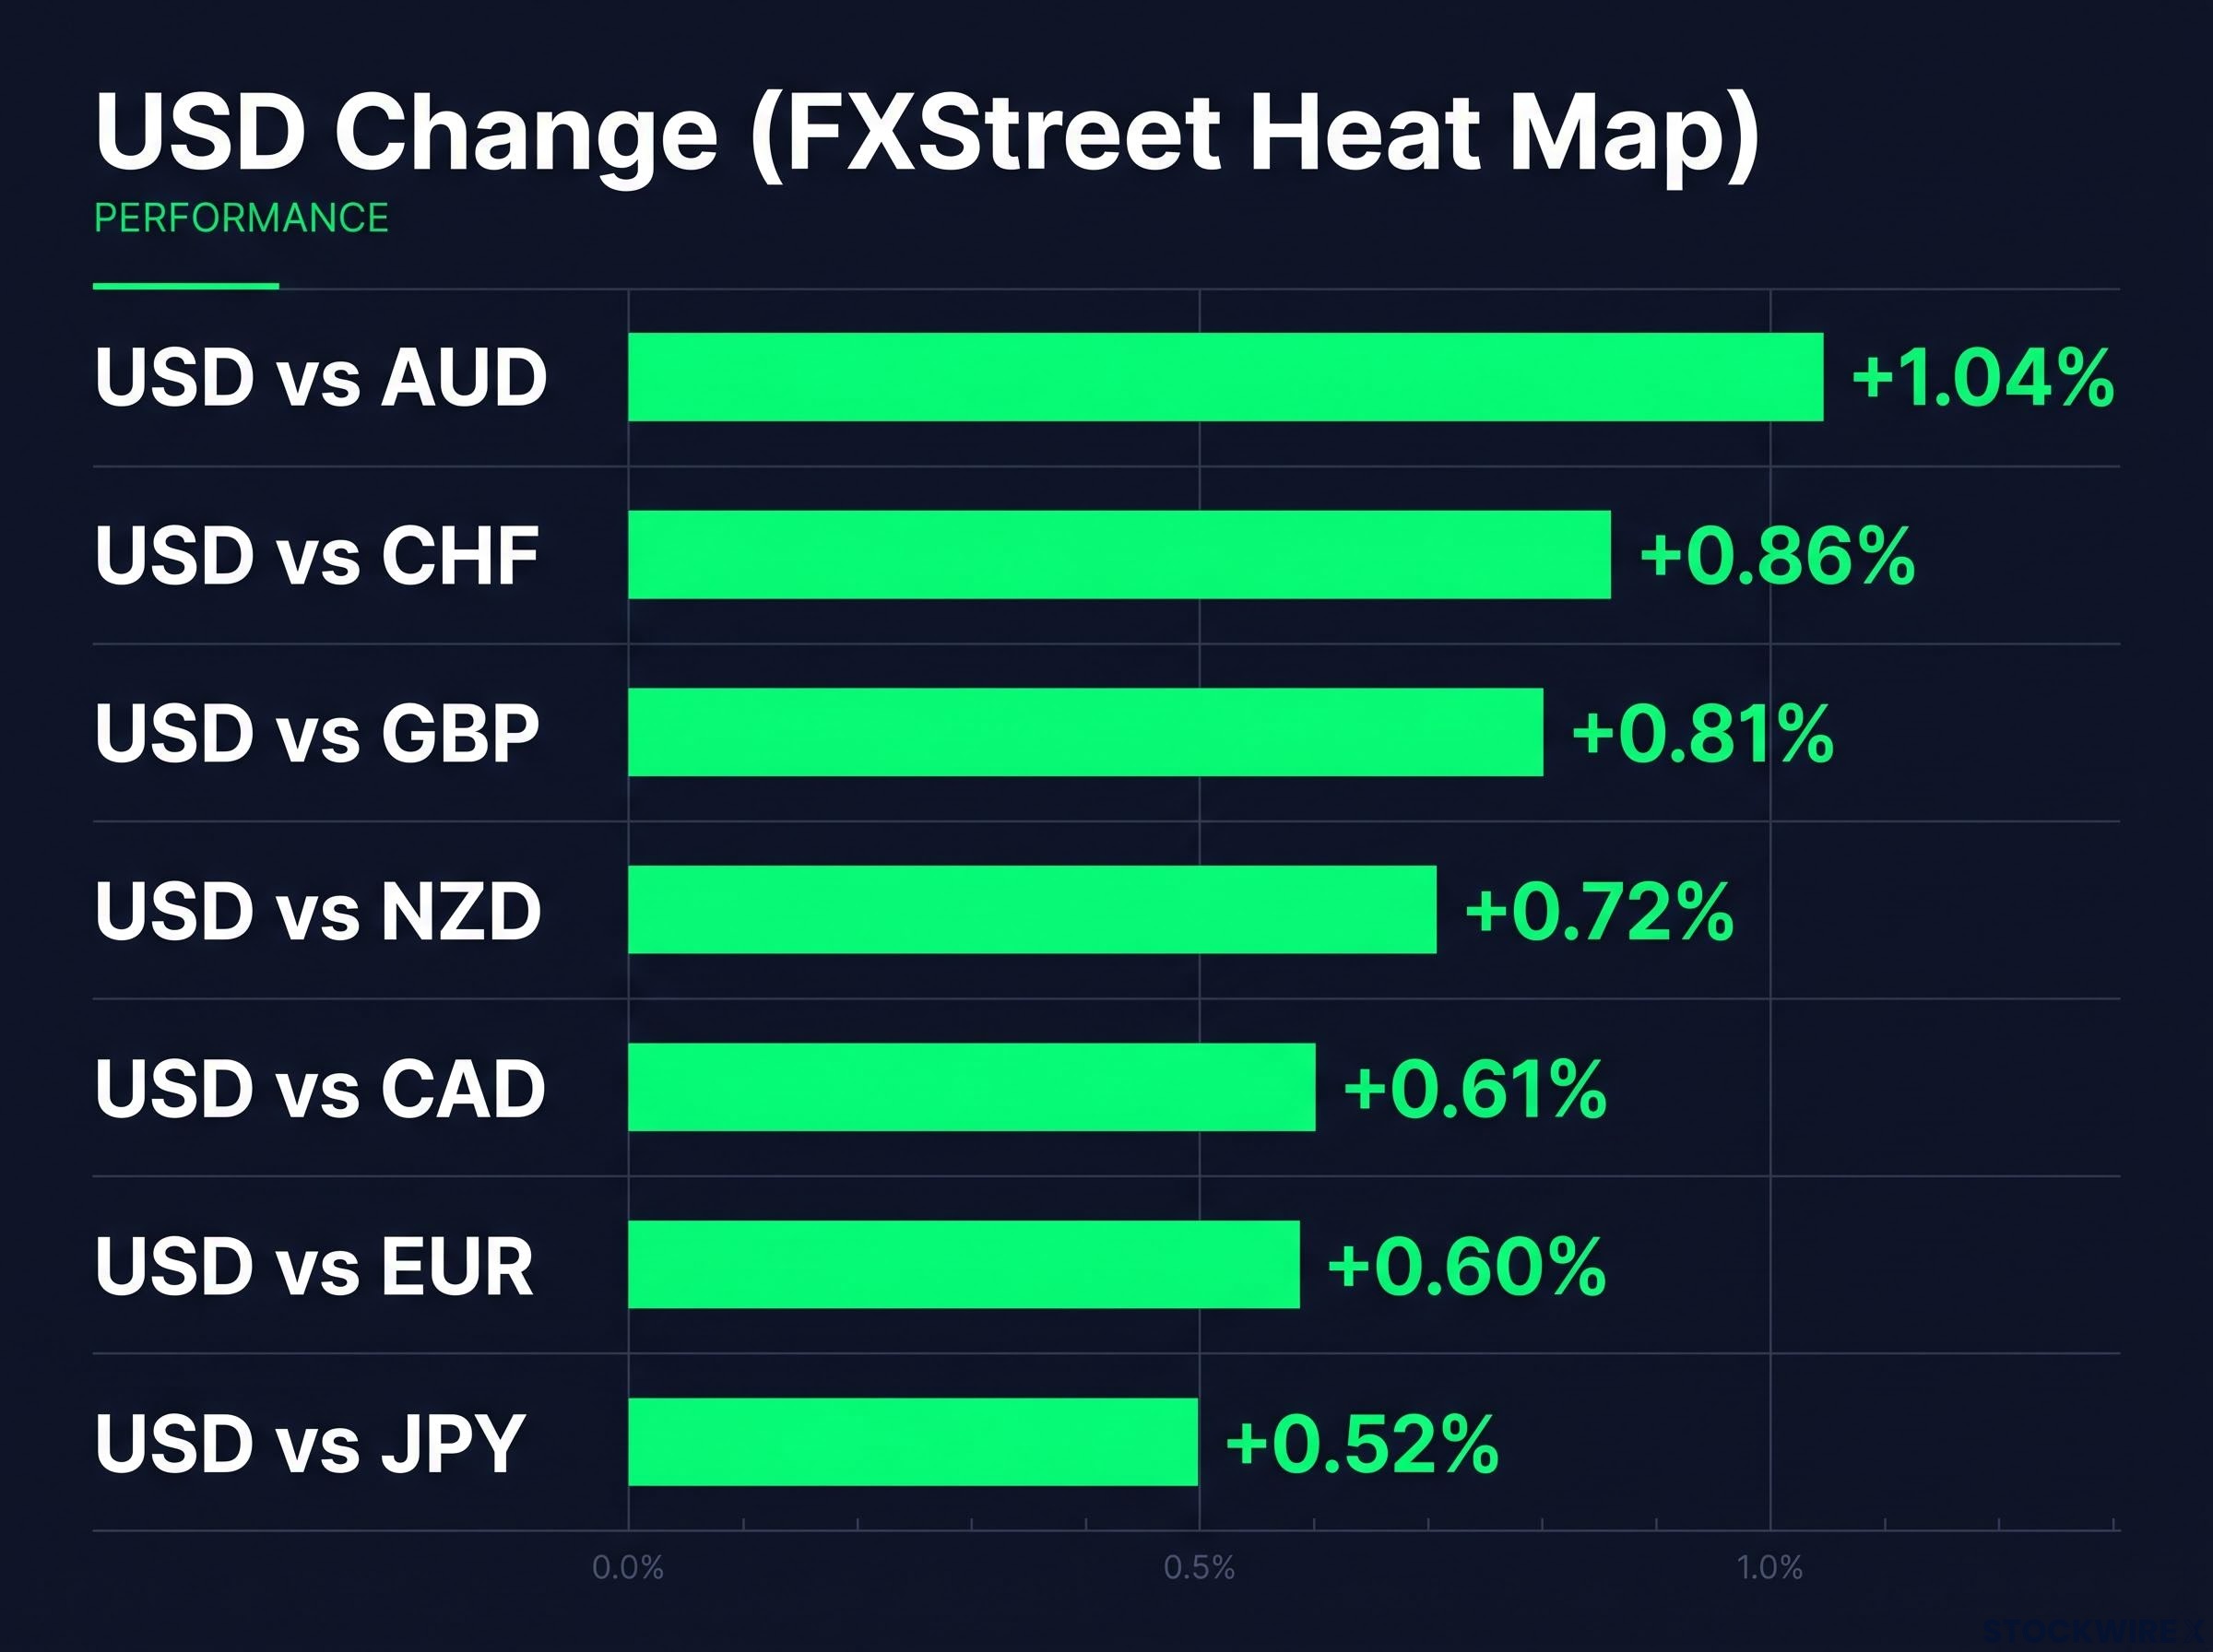
The US dollar gained broadly against all seven major peers, led by a +1.04% rise against the Australian dollar.
| Pair | USD change (FXStreet heat map) |
|---|---|
| USD vs EUR | +0.60% |
| USD vs GBP | +0.81% |
| USD vs JPY | +0.52% |
| USD vs CAD | +0.61% |
| USD vs AUD | +1.04% |
| USD vs NZD | +0.72% |
| USD vs CHF | +0.86% |
Attribution is messier than the table suggests. October CPI rose 0.4% month on month, with core up 0.3%, and Reuters reported that Waller’s comments alongside that data supported the dollar.
The sources also disagree on size. Reuters quoted the euro down just 0.1% at $1.1215 and sterling down 0.15% at $1.3423, far smaller than FXStreet’s figures, likely because the two used different measurement windows. No move in the DXY dollar index specifically was found.
Rate pricing shifted with the data:
- A 25 basis point December hike moved towards near certainty after the CPI release.
- One Reuters-based report put the chance of a 50 basis point move at nearly 10%.
- The 10-year Treasury yield sat around 4.9%, with one report at 4.99% after CPI and Schwab at about 4.94% during the session.
Higher policy rates also feed through to bond duration risk and equity discount rates, so a 10-year yield near 4.9% reprices both fixed income and growth stocks.
A rally across every major pair tells you the market is repricing US rates against the rest of the world. That matters if you hold unhedged foreign assets or businesses sensitive to import costs.
Why Fed rate hikes tend to lift the dollar, and when they do not
The simple version holds most of the time. Higher US rates and yields raise the expected return on dollar assets, draw in foreign capital and widen the gap with central banks that move more slowly.
The transmission runs through yield differentials, balance-sheet policy and market pricing, which is why Fed rate hikes tend to lift the dollar only when they widen the return gap beyond what futures markets had already discounted.
History adds conditions. Currencies trade on expected policy, so a hike the market already priced does far less than a surprise.
| Episode | What happened to the dollar | Lesson |
|---|---|---|
| 2022-2023 tightening | Strengthened while the Fed looked more hawkish than peers, then gains faded as the end of hikes was priced | Relative hawkishness drives the move |
| 2004-2006 “measured pace” | Did not rise steadily despite repeated hikes | Anticipated hikes carry little punch |
| 2013 taper episode | Signalling alone lifted US yields and reversed emerging-market flows | Expectations move markets before actions do |
Four factors decide whether hikes actually lift the dollar:
- Other central banks: if the ECB, Bank of England, RBA or Bank of Japan also tighten, the rate gap narrows.
- Recession fears: hikes read as growth-killing can push investors out of the dollar.
- Fiscal worries: doubts over US finances can blunt the yield advantage.
- Safe-haven flows: geopolitical stress can send capital to other havens.
On that basis, Logan’s two-hikes-then-pause path would likely be most dollar-positive if markets saw it as credible inflation control without a serious recession.
Fed tools in brief
The Fed’s dual mandate is price stability and full employment, pursued mainly by setting short-term interest rates. Quantitative easing (QE) means the central bank buys high-grade bonds to push down long-term rates, as it did in 2008, and it usually weakens the dollar. Quantitative tightening (QT) reverses that by ending purchases and reinvestment, and usually supports the currency.
The lesson for you: watch the surprise against expectations, not the hike itself.
Where Logan sits among Fed officials, and what to watch before December
Logan sits at the hawkish edge of a live debate, though not alone. The October 28 decision to hold rates passed on a 10-2 vote.
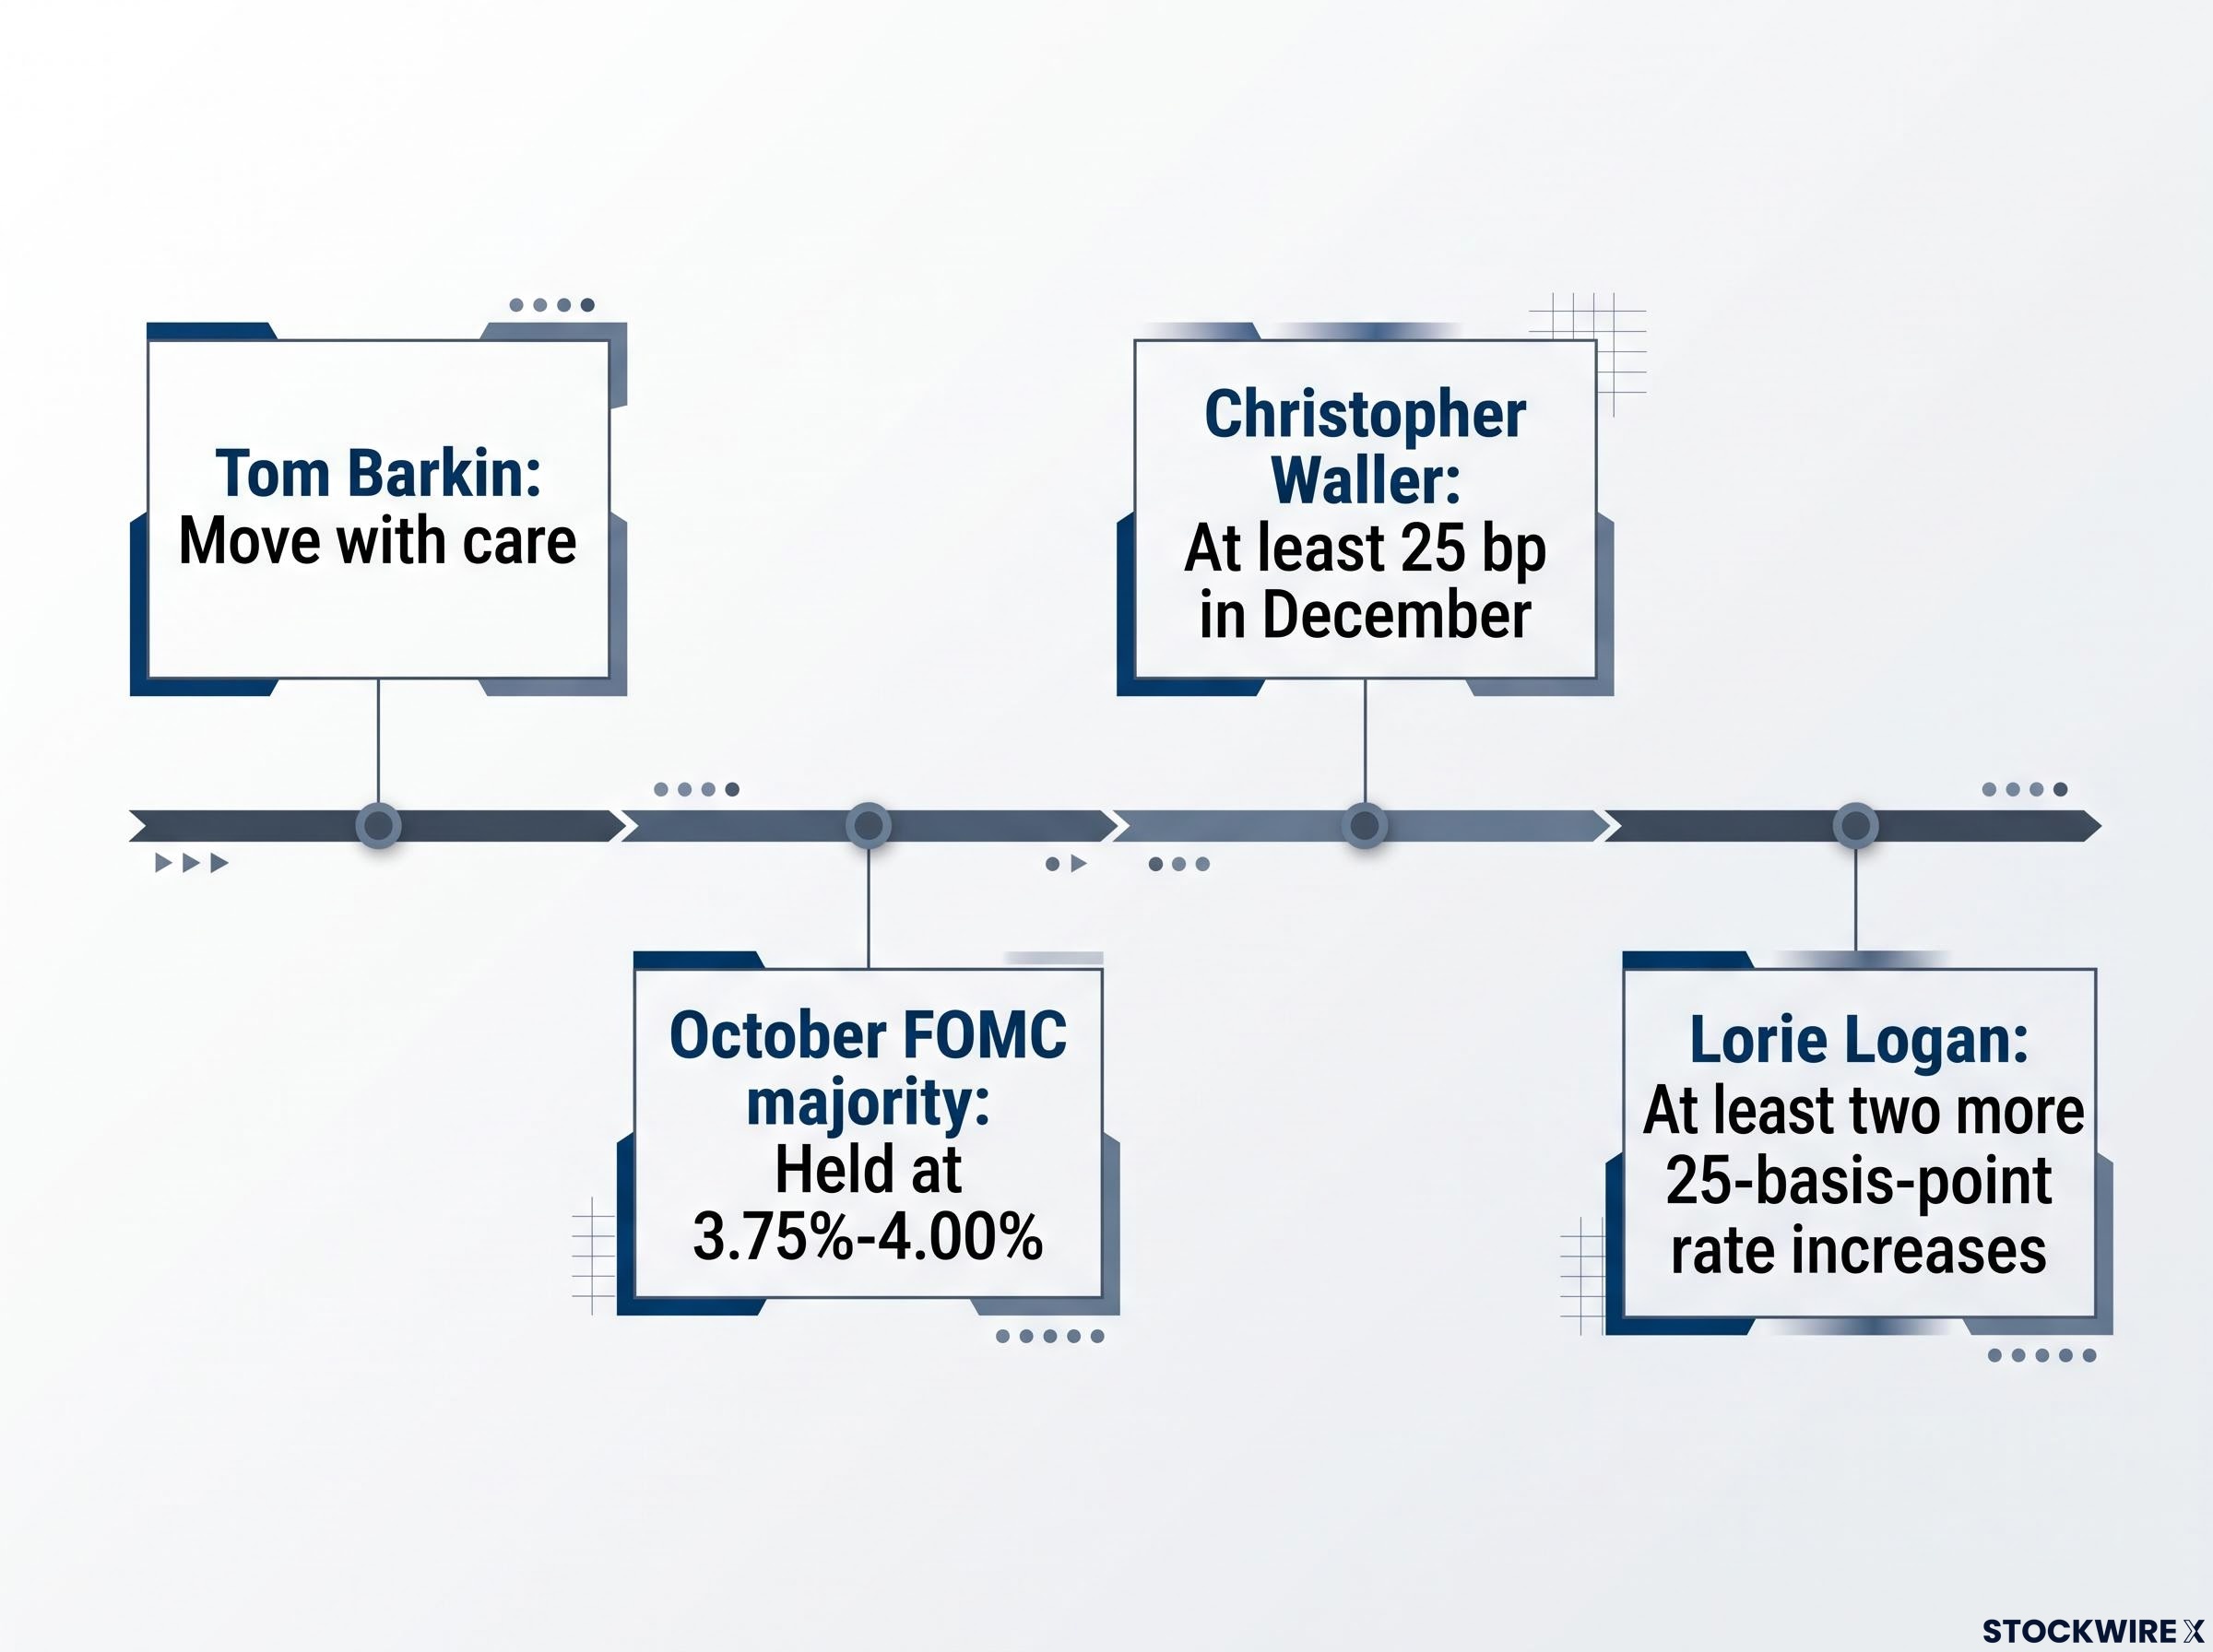
Lorie Logan sits at the hawkish end of the Federal Reserve spectrum, calling for at least two more 25-basis-point rate increases.
| Official or group | Position | Versus Logan |
|---|---|---|
| Governor Christopher Waller | At least 25 bp in December; 50 bp should be considered if core CPI rose 0.3% or more | More aggressive on the next move |
| Richmond Fed’s Tom Barkin | Move policy “with care” | More cautious on pace |
| Reuters poll of 101 economists | December hike to 4.00%-4.25%, most see it as the last | Less hawkish |
| October FOMC majority | Held at 3.75%-4.00% | Waiting on data |
Two more hikes from today’s range imply an endpoint of at least 4.25%-4.50%, an inference from her stated number of moves, against roughly 4.00%-4.25% in the consensus.
The counter-arguments carry weight. Tightening too fast could tip a balanced labour market into decline, rate effects arrive with lags, and hikes cannot fix supply shocks from energy disruption or tariffs.
The dates that will settle the argument:
- 25 November 2026: the BEA releases October PCE inflation.
- 8-9 December 2026: the FOMC meets and publishes fresh projections.
The gap between Logan and the consensus is about how many hikes remain. That makes the December statement and projections more important to you than the near-certain quarter-point move.
What Logan’s call changes for December, and what it leaves open
The debate has moved on from whether the Fed hikes to how many more times and how quickly. Logan has put a number on that, and the dollar’s gains across every major pair show markets have started to take the hawkish case seriously.
What remains open is whether her colleagues follow. The October PCE figures on 25 November will test her claim that inflation is broad and persistent, and the 8-9 December projections will show whether the committee sees one more hike or several.
If you hold dollar-sensitive positions, those two dates are your decision points. A hawkish surprise would favour Logan’s view; a statement signalling one-and-done would hand the argument to the consensus.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.