EUR/USD took a hawkish surprise on the chin on Tuesday and still did not leave its range. US core inflation rose 0.3% in October against a 0.2% forecast, yet the pair only slipped toward the lower half of the band it has held since late October.
The reason sits in what the market is pricing. Traders are not trading today’s interest rates. They are trading where the Federal Reserve and the European Central Bank (ECB) are expected to take rates over the coming months, and Tuesday’s print simply confirmed a view that was already in place.
That view faces a real test over the coming days. Christine Lagarde speaks twice, two more central bankers take the stage, and Friday brings both Eurozone GDP and US producer prices.
With the pair near 1.1160 after the CPI release on 10 November 2026, the useful question for the EUR/USD week ahead is narrow. Will any of this week’s events push the pair out of its 1.1130-1.1270 range, or shift the gap between Fed and ECB rate expectations? After this, you will be able to judge each event against both.
Why did a hot core CPI print leave EUR/USD stuck in its range?
A beat on core inflation usually hits the euro hard. This one produced a slide, not a break.
The October numbers from the Bureau of Labor Statistics looked like this:
- Headline CPI: up 0.4% month on month, after 0.6% in September
- Core CPI (which strips out food and energy): up 0.3%, against a 0.2% consensus
- Annual rate: not published, because the comparison month from a year earlier lacked usable data after the disruption to CPI collection
Two different prices are in circulation, and they measure different things. Reuters put the market price at about 1.1160, down roughly 0.55% after the release. The ECB’s official reference rate for the day was 1.1214, a fixing set once a day rather than a live trading price.
The range itself is clear. The pair found lows just above 1.1130 on 29 October and highs near 1.1267 on 4 November. Technical levels from StoneX and TMGM sharpen the picture, although the two firms draw the boundaries slightly differently.
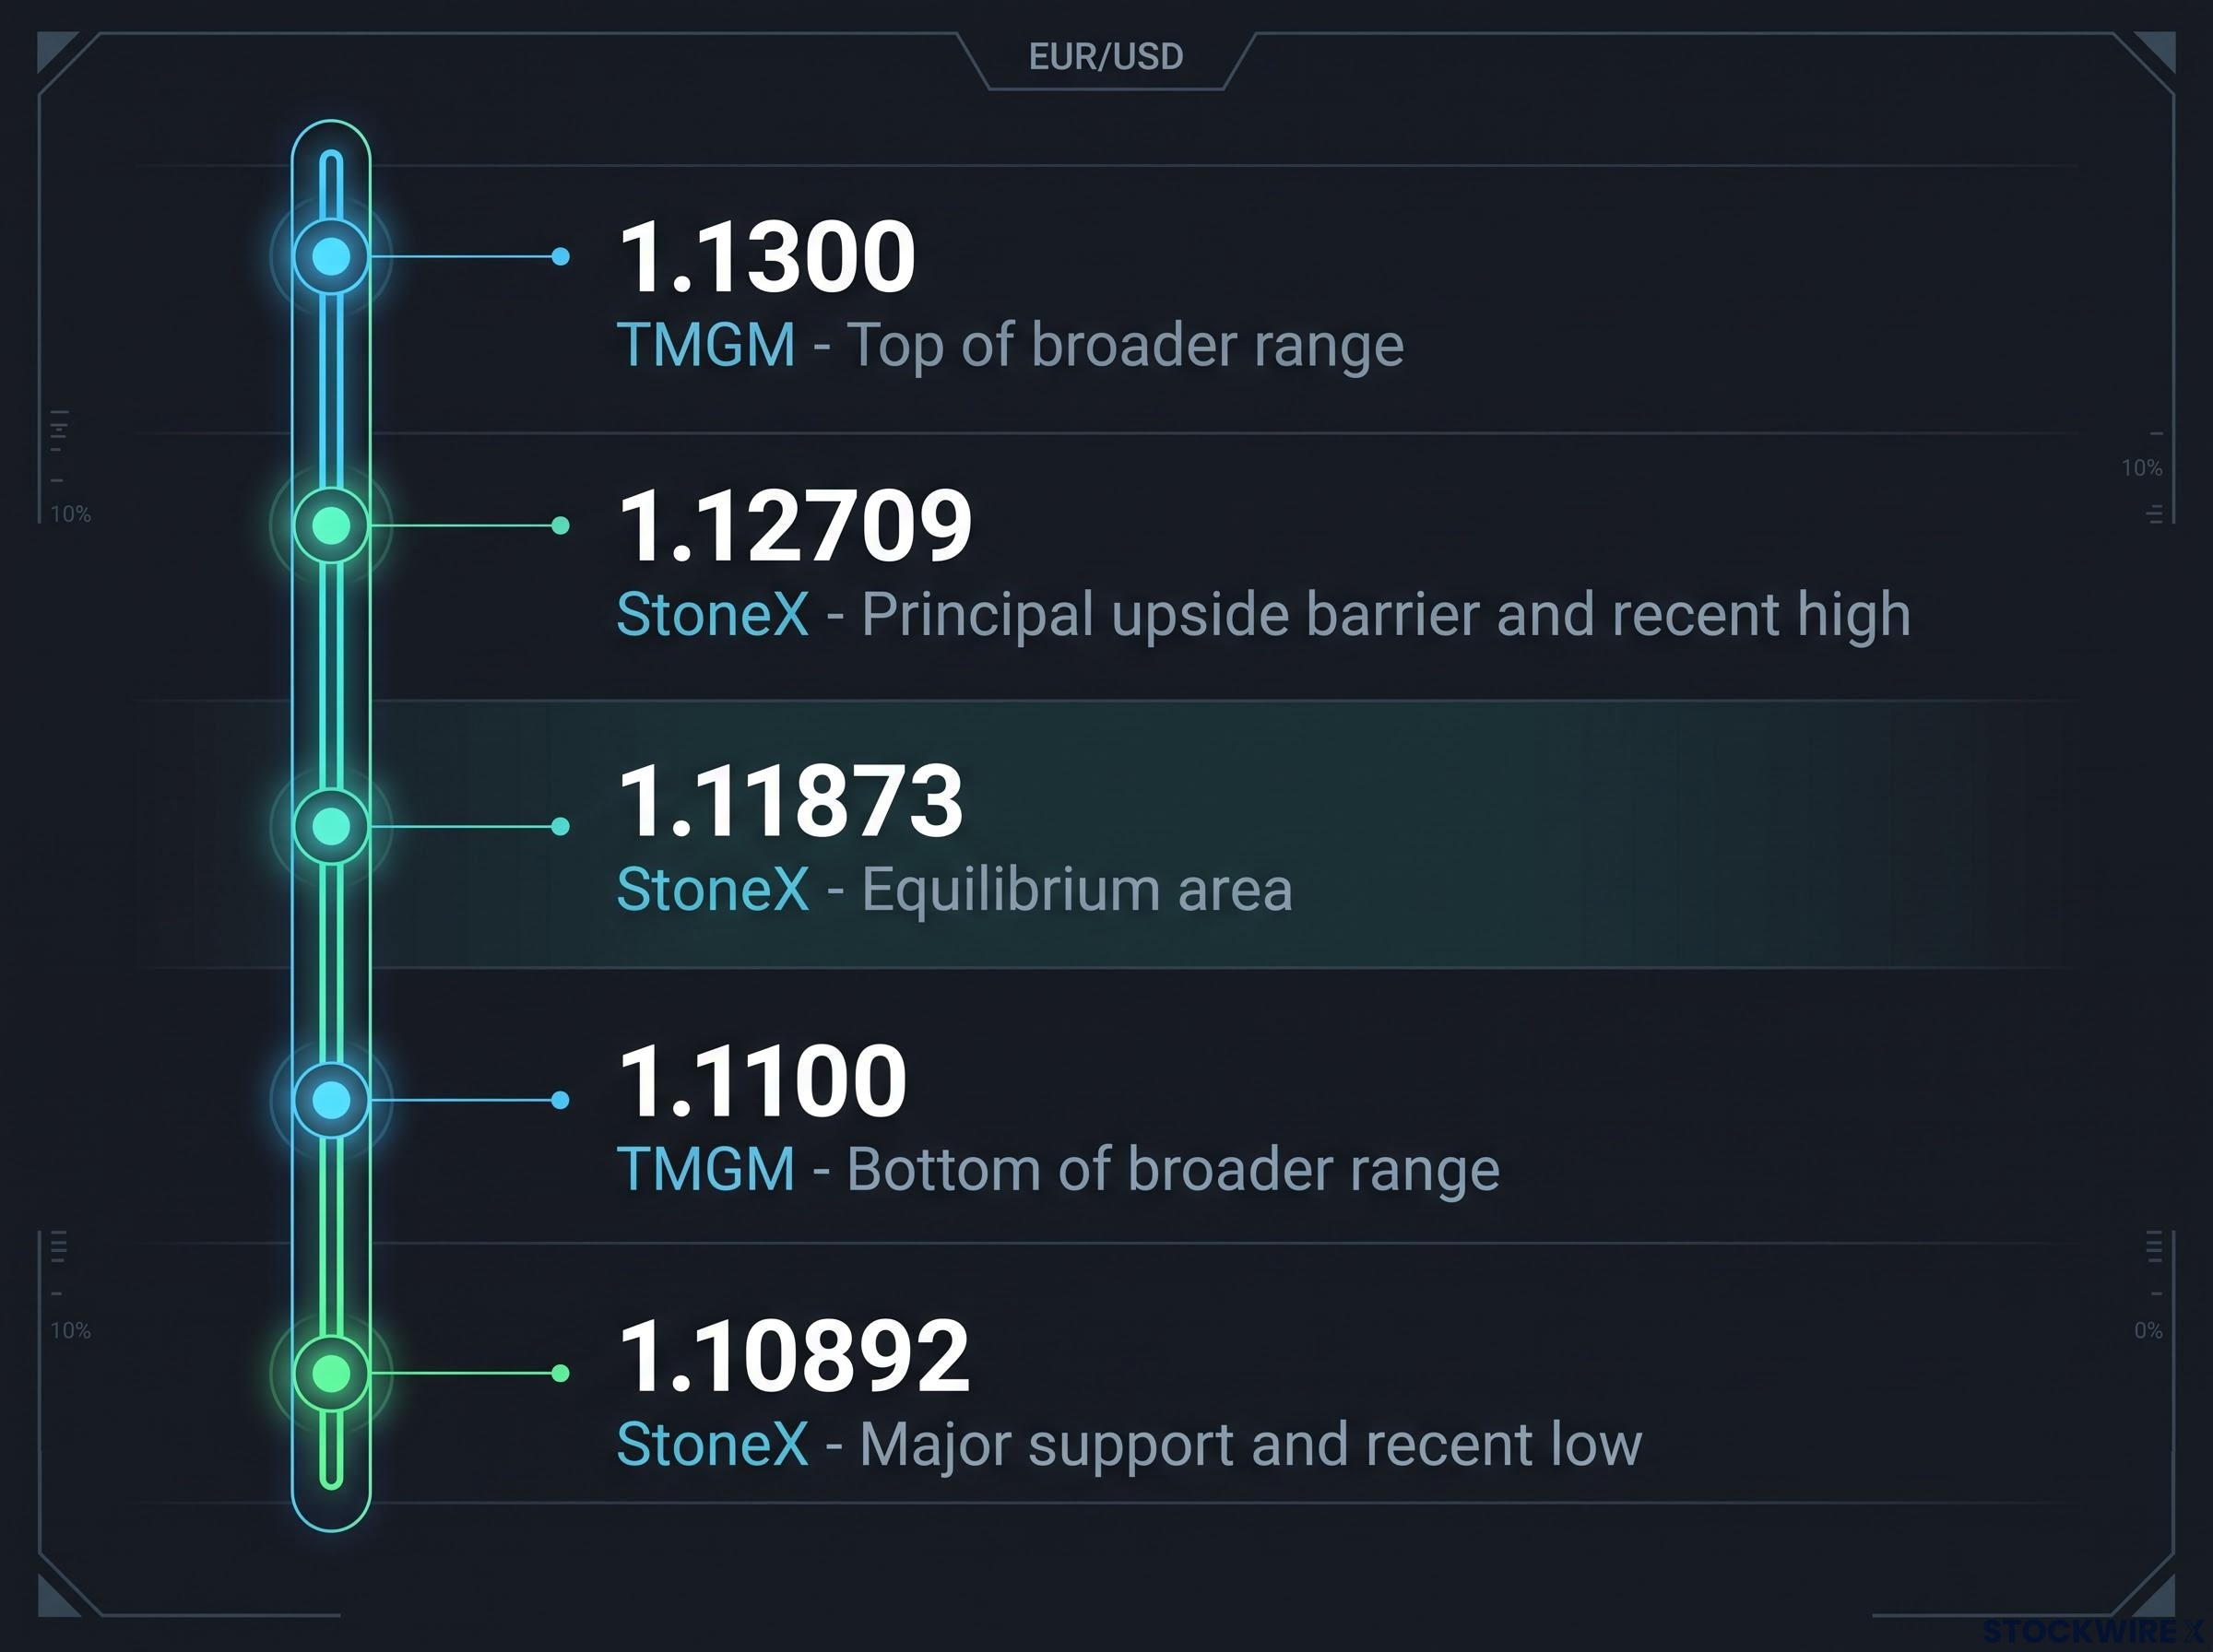
Technical levels from StoneX and TMGM highlight a narrow trading range, bounded by 1.1300 at the top and 1.10892 at the bottom.
| Level | Source | Role |
|---|---|---|
| 1.1300 | TMGM | Top of broader range |
| 1.12709 | StoneX | Principal upside barrier and recent high |
| 1.11873 | StoneX | Equilibrium area |
| 1.1100 | TMGM | Bottom of broader range |
| 1.10892 | StoneX | Major support and recent low |
StoneX read the CPI print as reinforcing the case that the Fed may stay more aggressive than the ECB, which caps how far the euro can climb. That is the key point. The pair drifted lower without touching support, which tells you the market treated the data as confirmation of an existing view rather than a new regime, so range trading remains the base case.
When big ASX news breaks, our subscribers know first
How wide is the Fed-ECB policy gap, and why does it move the euro?
The difference between the two central banks’ rates is the engine behind that range. The Fed’s target range sits at 3.75%-4.00% after a 25 basis point hike in September 2026 and a pause in October. The ECB’s deposit rate is 2.50%, set on 29 October 2026. (A basis point is one hundredth of a percentage point.)
That leaves a gap of about 1.25-1.50 percentage points in favour of the dollar. If the Fed adds two more 25 basis point hikes while the ECB holds, the gap widens to roughly 1.75-2.00 points.
The Fed-ECB rate gap has become the single figure most closely tied to global currency pricing, which is why a spread of roughly 125 basis points shapes how international portfolios are positioned across the euro and the dollar.
The gap moves the currency through a simple chain:
- Higher expected US rates lift Treasury yields and money-market returns.
- Global investors gain a stronger reason to hold dollar assets.
- Demand for dollars rises relative to euros, pushing EUR/USD lower.
- All of this happens on expectations, so priced-in future hikes can lift the dollar before the Fed actually moves.
2022 showed the limits of reading the gap as a single number. The Fed tightened faster and harder, the ECB responded later, and the dollar surged. The lesson was that the expected path and credibility of policy mattered more than the level of the differential on any given day.
On Tuesday, Dallas Fed President Lorie Logan set out a clear path: at least two more 25 basis point hikes, possibly faster over the winter, then a pause. Across the Atlantic, ECB chief economist Philip Lane sounded hawkish but conditional.
Philip Lane on December Lane said a December ECB hike would be prudent if the data do not change, with the decision hinging on whether the energy shock spreads into wages and other prices.
So the divergence is not tightening versus easing. It is an explicit US tightening bias against a conditional ECB one. That explains why Eurozone inflation of 4.0% in October, a three-year high, has not lifted the euro further.
| Measure | Federal Reserve | ECB |
|---|---|---|
| Policy rate | 3.75%-4.00% | 2.50% deposit rate |
| Latest action | 25 bp hike in September, paused in October | Decision on 29 October |
| Latest inflation | Core CPI +0.3% m/m (October) | Headline 4.0% y/y, core 2.5% (October) |
| Market pricing | December hike about 91-99%; 50 bp odds about 11% | About two hikes by mid-2027 |
ING’s Chris Turner expects the pair to stay offered in a 1.10-1.15 range over the next four to five months, citing the US rate advantage and a euro risk premium tied to French fiscal and political uncertainty. With a December Fed hike already heavily priced, a matching decision may add little for the dollar. What you should watch is guidance and the pace of hikes, not the headline call.
What drives the euro? A short primer for reading this week’s data
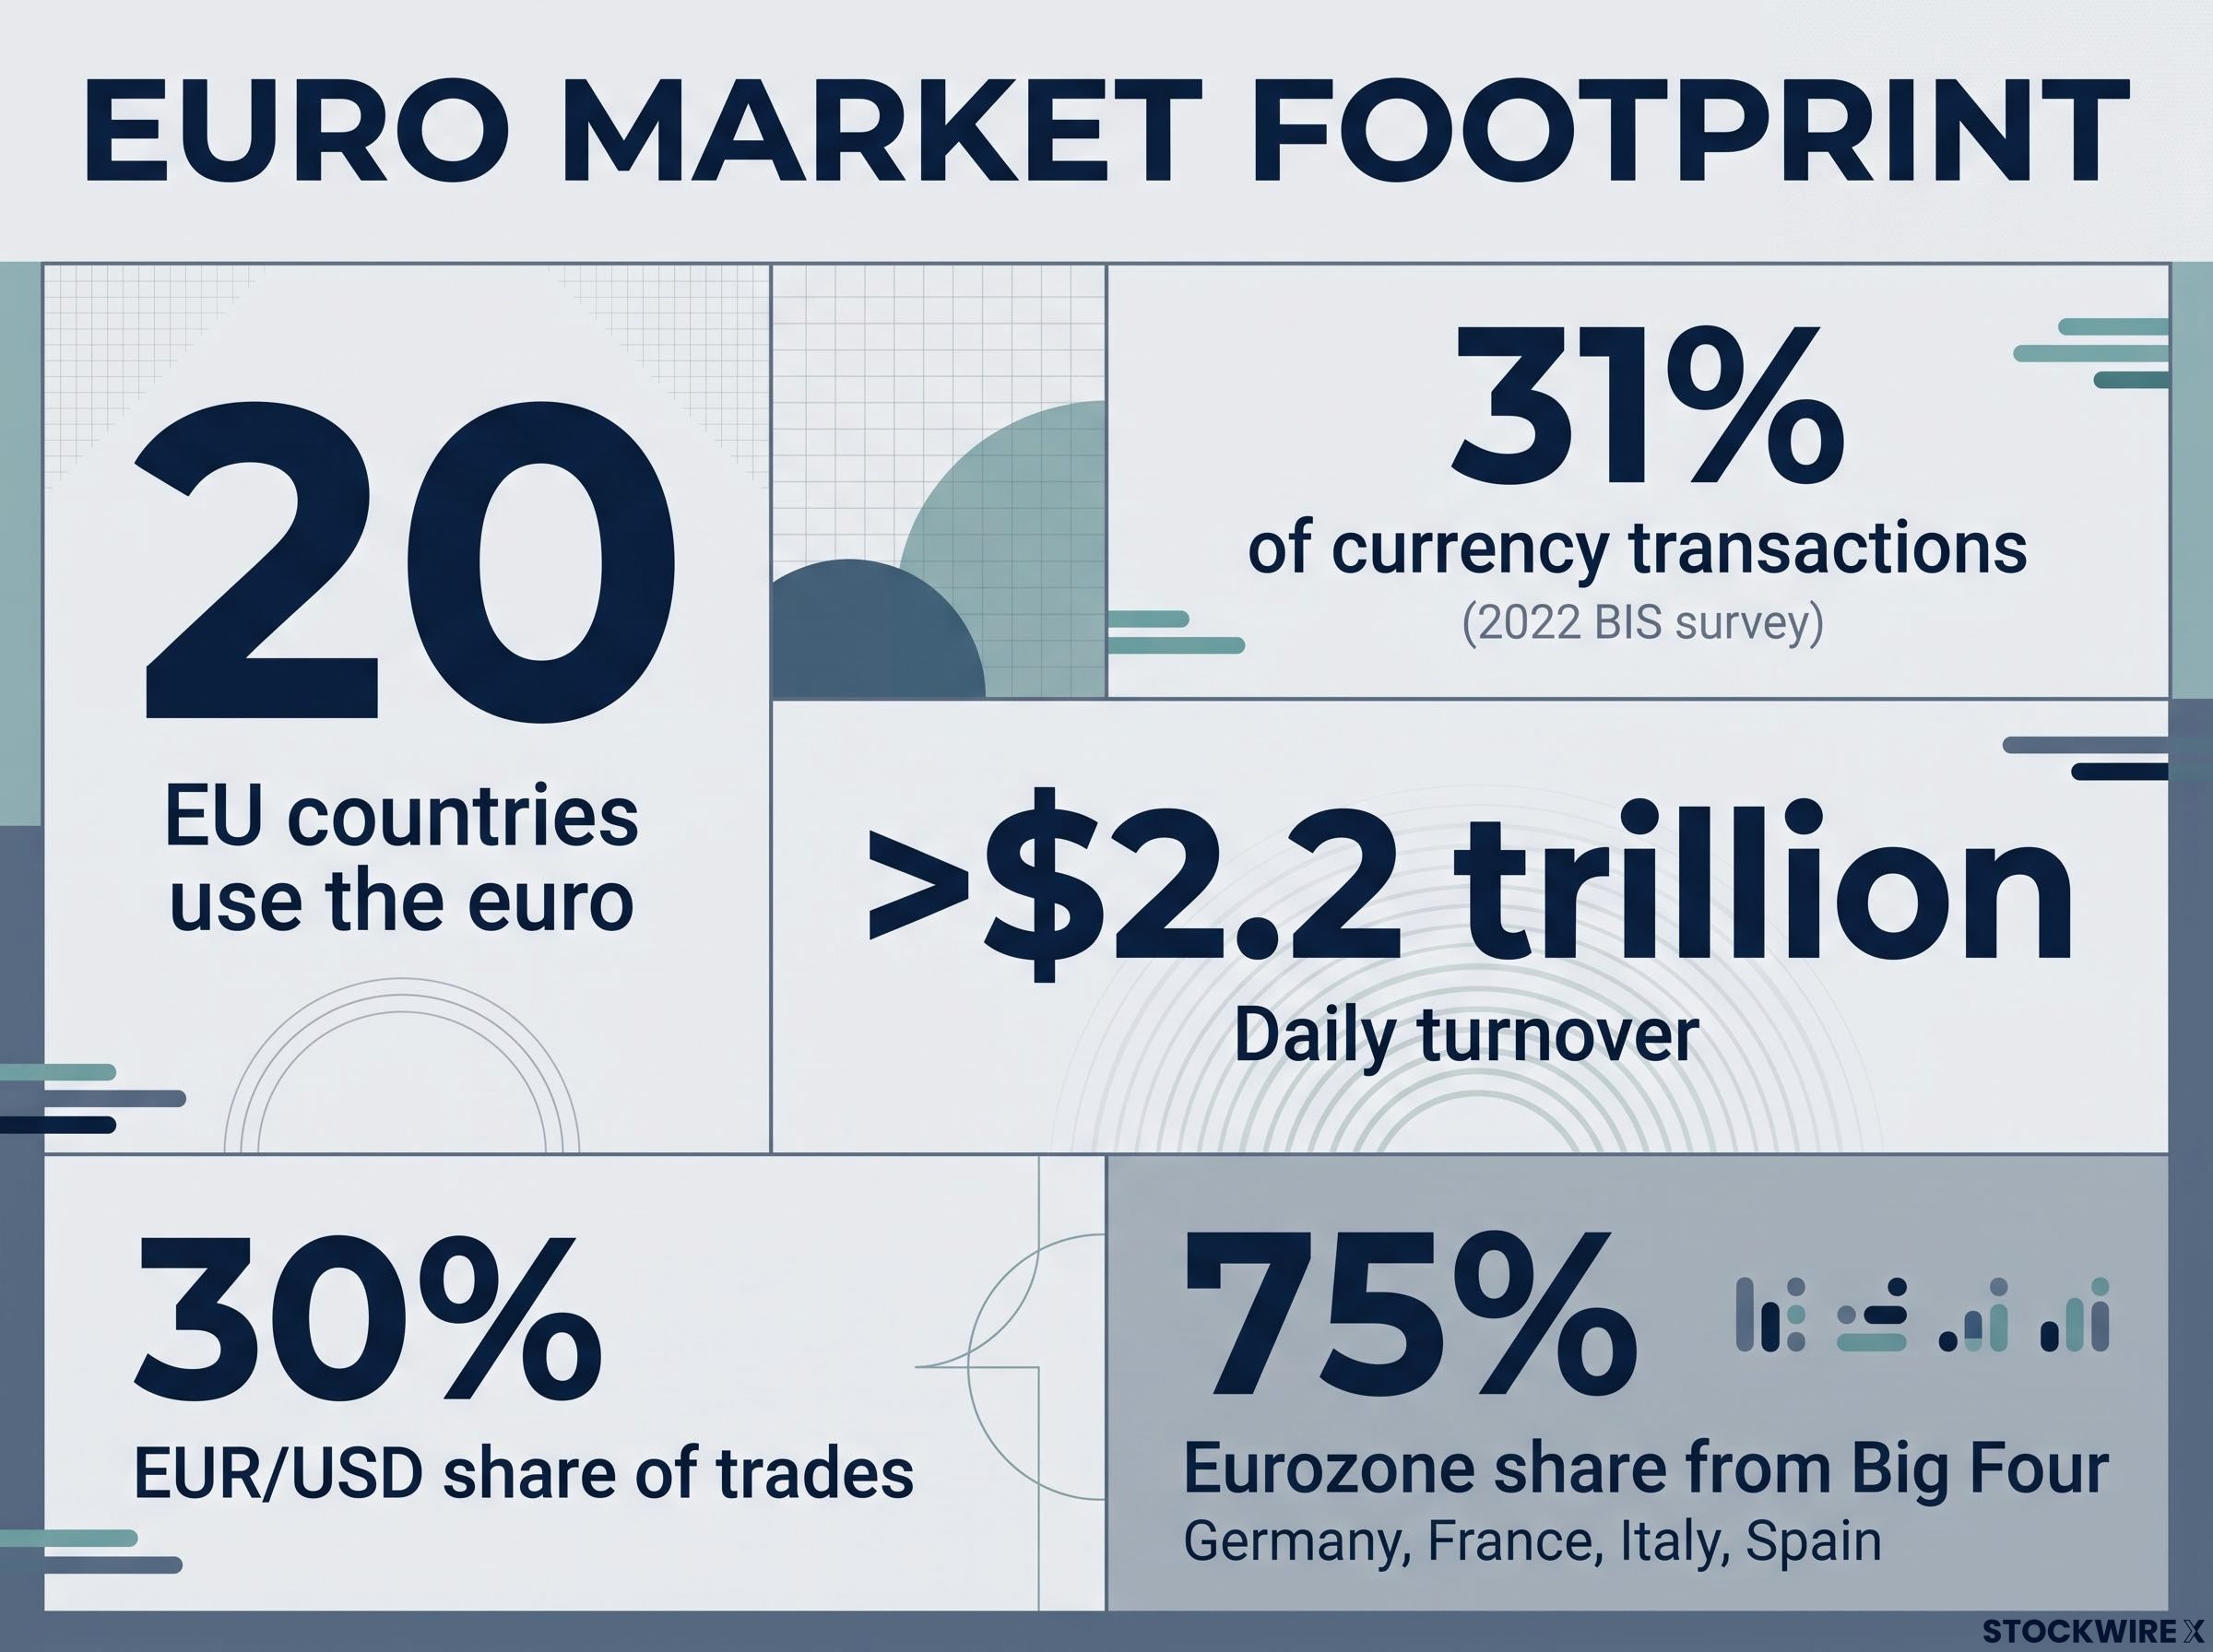
Before the calendar, it helps to know what actually moves the euro. The euro is used by 20 EU countries and is the second most traded currency after the dollar. In the 2022 BIS survey, the most recent cited here, the euro featured in 31% of currency transactions, with daily turnover above $2.2 trillion. EUR/USD alone made up about 30% of trades.
 ECB tightening cycle began in earnest with two 25 basis point hikes in three months, and Eurosystem staff projections keep inflation above target through 2027, context that explains why hawkish speakers carry weight.
Growth, trade and politics
Rates are not the only lever. These are the other drivers you will see referenced this week:
- Growth and sentiment data (GDP, PMIs, employment): strong readings tend to help the euro, weak ones hurt it
- The big four economies: Germany, France, Italy and Spain make up 75% of the Eurozone, so their data moves the currency most
- Trade balance: a surplus tends to strengthen a currency
- Energy prices: higher prices feed inflation and pressure the ECB, but also strain growth
- French fiscal and political risk: fresh uncertainty adds a risk premium that weighs on the euro
- Global risk sentiment: risk-off moves tend to favour the dollar
Here is the filter to keep. Strong data and hawkish ECB signals help the euro only to the extent that they shift rate expectations relative to the Fed. Apply that test to every release this week.
This week’s calendar: what each event could do to EUR/USD
The week builds steadily toward a crowded Friday.
| Event | Time (GMT) | Consensus | Why it matters |
|---|---|---|---|
| Christine Lagarde speaks | Wed 11 Nov 09:45; Thu 12 Nov 19:30 | No numerical forecast | Any shift in ECB signalling on December |
| Beth Hammack (Cleveland Fed) | Thu 12 Nov 14:00 | No numerical forecast | A voter this year; tests support for Logan’s path |
| Isabel Schnabel (ECB) | Fri 13 Nov 07:10 | No numerical forecast | Hawkish tone could lift ECB pricing |
| Eurozone Q3 GDP, second estimate | Fri 13 Nov 10:00 | +0.4% q/q, +1.3% y/y | Confirms whether growth can absorb an ECB hike |
| US October core PPI | Fri 13 Nov 13:30 | +0.3% m/m; headline +0.4% | Producer prices feed the Fed pace debate |
The three speeches carry no forecasts, so tone is the variable. Lagarde opens Wednesday, and a firmer line on second-round effects would echo Lane and give the euro some support. Hammack’s Thursday remarks matter because she votes this year.
Friday stacks the risk. The Q3 flash on 30 October already showed 0.4% growth, so a matching second estimate is the baseline. A print in line leaves the ECB debate where it is, which means the real surprise risk sits with Lagarde, Schnabel and core PPI, and you should size your expectations around those three.
If the range breaks higher
- Softer US data, including a cooler PPI print
- A less hawkish Fed tone, weakening the case for faster hikes
- Stronger ECB repricing, if Lagarde or Schnabel back Lane’s December case
- Weaker US growth or employment, trimming Fed-hike pricing
A sustained move above 1.13 would need some combination of these.
If the range breaks lower
- A hot PPI print that reinforces Logan’s case
- ECB speakers who avoid committing to December
- A French fiscal or political shock adding to the euro’s risk premium
A decisive break of 1.11-1.109 would signal a wider bearish move. Two considerations cut across both lists. Falling energy prices could ease headline inflation, although Lane warned core could still rise with a lag. And because a December Fed hike is heavily priced, the dollar may struggle to extend gains without more hawkish guidance. TMGM and StoneX both read the current setup as range trading rather than a confirmed reversal.
These scenarios are speculative and subject to change based on market developments and incoming data.
Reading the week through the rate gap, not the headlines
EUR/USD is trading rate expectations inside a defined band, and this week decides whether the Fed-ECB gap narrative strengthens or stalls. Tuesday’s CPI showed how the market filters data: it rewarded the dollar for confirming a view, not for surprising anyone.
Keep 1.11 and 1.13 as your decision points. A move through either, held rather than briefly touched, would tell you the market has changed its read on policy paths.
Beyond Friday, three variables carry forward. Watch the pace of Fed hikes against the December move already priced in, the ECB’s signalling on second-round effects, and any fresh French fiscal news. Those will shape whether the range survives into year-end.
Investors weighing other ways to express policy divergence will find our deep-dive into ECB and BoE divergence, which explains why EUR/GBP can be a cleaner pair than EUR/USD.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.