
Third quarter 2026 results: net income up 17% to $133 million
Light & Wonder (ASX: LNW) reported in its third quarter 2026 results (quarter ended 30 September 2026) that net income rose 17% to $133 million, with diluted earnings per share up 28% to $1.72. All figures are in US dollars.
Consolidated AEBITDA grew 2% to $383 million, while Adjusted NPATA increased 7% to $163 million. EPSa (Adjusted NPATA per diluted share) rose 17% to $2.12.
Earnings grew even though revenue slipped. Third quarter revenue was $824 million, down 2%, while year-to-date revenue grew 1% to $2,440 million.
The company attributed the net income increase primarily to margin strength on a favourable revenue mix and ongoing operational efficiencies. Consolidated AEBITDA margin rose 1 percentage point to 46%.
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $824M | $841M | -2% |
| Net income | $133M | $114M | +17% |
| Diluted EPS | $1.72 | $1.34 | +28% |
| Consolidated AEBITDA | $383M | $375M | +2% |
| Adjusted NPATA | $163M | $153M | +7% |
| EPSa | $2.12 | $1.81 | +17% |
Matt Wilson, President and Chief Executive Officer
“Our content-centric operating model is enhancing our recurring revenue business, as evidenced in the results… Gaming momentum continues, evidenced by our North American premium installed base growing for the 25th consecutive quarter.”
When big ASX news breaks, our subscribers know first
Recurring revenue and segment performance
Gaming operations and iGaming were the primary growth drivers, partially offset by softness in Gaming systems and SciPlay.
Gaming
Gaming revenue was $554 million, down 1% from $558 million. Gaming AEBITDA rose 2% to $312 million, and margin expanded 1 percentage point to 56%.
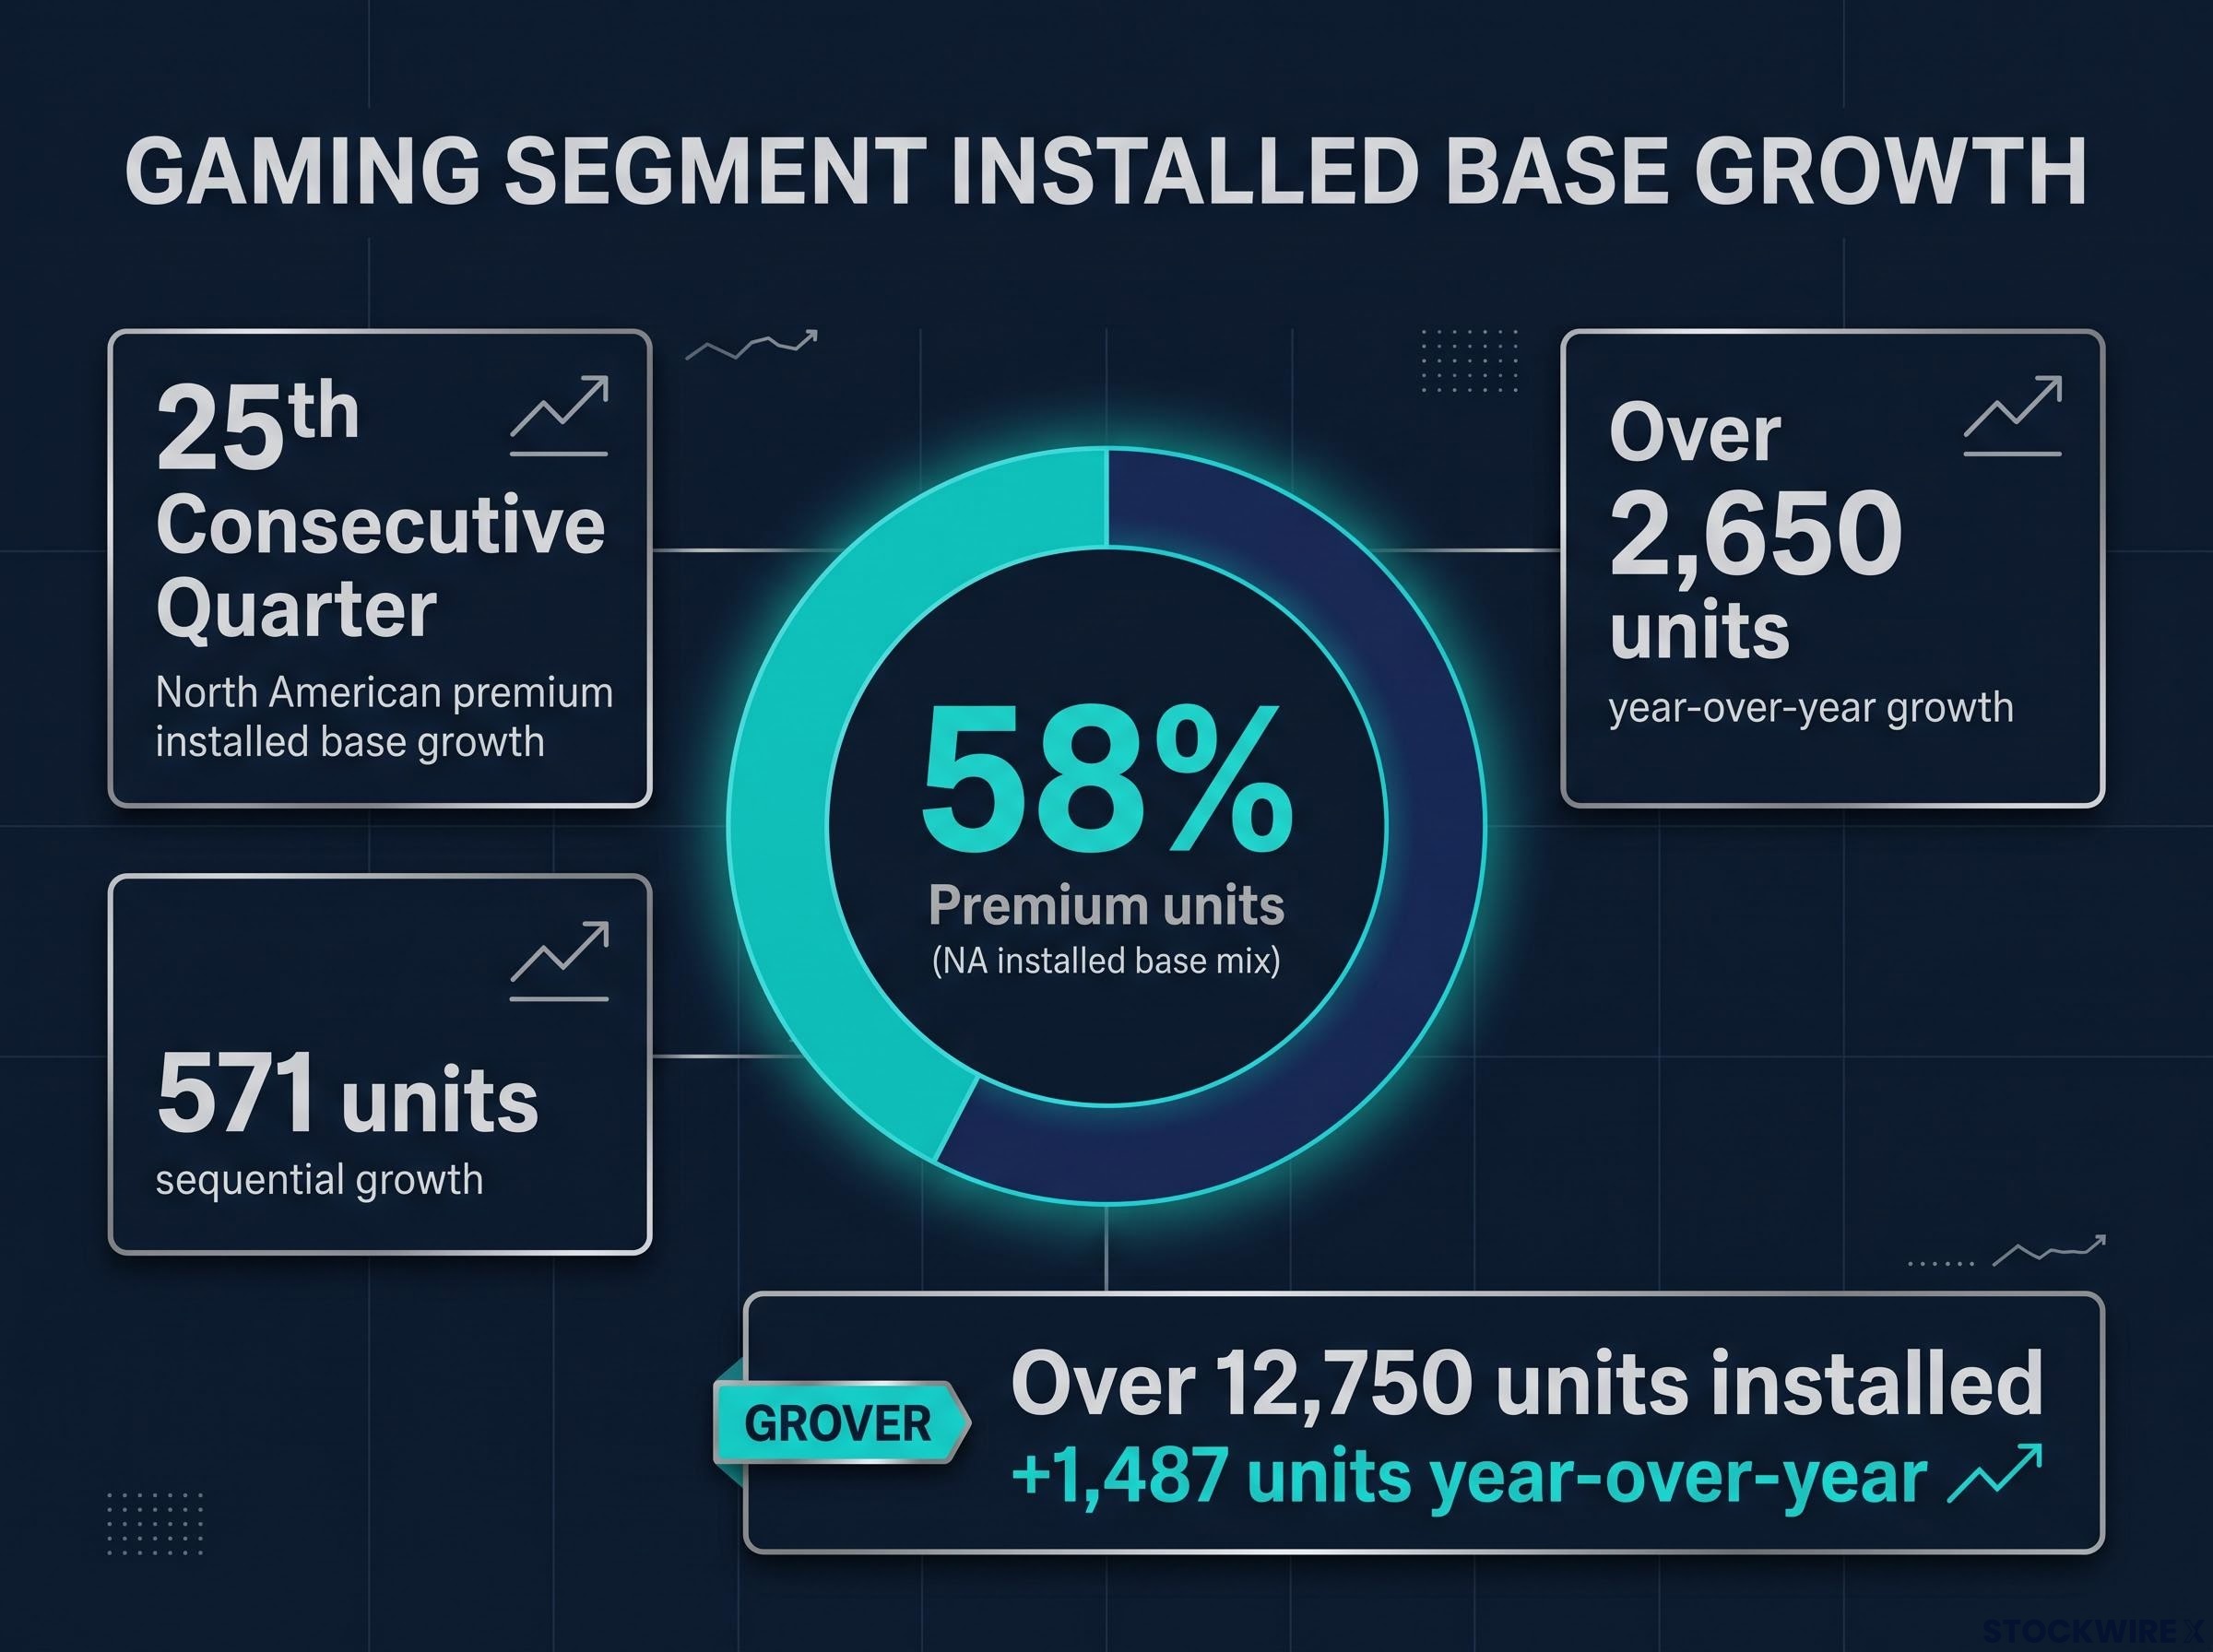
The North American premium installed base grew for a 25th consecutive quarter, up over 2,650 units year-over-year and 571 units sequentially. Premium units now represent 58% of the total North American installed base mix. Grover added 1,487 units year-over-year and had over 12,750 units installed at period end.
Gaming operations revenue increased 3% to $248 million, and machine sales rose 5% to $199 million on 8,906 new units shipped globally. Gaming systems revenue fell 24% to $55 million on lower hardware sales, and Table products revenue fell 7% to $52 million.
iGaming and SciPlay
iGaming revenue increased 13% to $97 million, with AEBITDA of $37 million. Wagers processed through the platform reached a quarterly record of $31.7 billion.
SciPlay revenue decreased 12% to $173 million, reflecting softness in the broader social casino free-to-play market. Direct-to-consumer revenue was $53 million, or 31% of SciPlay revenue, and AMRPPU grew 5% to $132.80.
| Segment | Revenue | Revenue change | AEBITDA | Margin |
|---|---|---|---|---|
| Gaming | $554M | -1% | $312M | 56% |
| SciPlay | $173M | -12% | $67M | 39% |
| iGaming | $97M | +13% | $37M | 38% |
Recurring revenue explained
Recurring revenue is income that repeats from ongoing arrangements rather than from one-off sales. The company defines it as including:
- Gaming operations (inclusive of Grover)
- Ongoing Gaming systems maintenance
- Table service/rental agreements
- SciPlay revenue
- iGaming revenue
Management said the strategy of scaling recurring revenue is leading to enhanced cash flow, and Chief Financial Officer Oliver Chow linked the recurring revenue base and margin discipline to strong cash generation.
The second quarter results showed the recurring share of sales reaching roughly 70%, up from 63% in 2022, which frames how far the revenue mix has shifted ahead of this latest period.
Cash generation and balance sheet deleveraging
Net cash provided by operating activities rose 28% to $236 million. Adjusted free cash flow was $181 million, up 21%, and year-to-date Adjusted free cash flow reached $545 million, up 49%.
The principal face value of debt outstanding fell by $153 million during the quarter to $5.0 billion. The net debt leverage ratio eased to 3.3x from 3.4x at 30 June 2026, and available liquidity was $1,059 million.
No shares or CDIs were repurchased under the share repurchase program in the quarter. With approximately 88% of the current authorised program utilised, remaining capacity is approximately $180 million.
Independent of that program, the company purchased 0.4 million CDIs on-market for approximately $30 million, held in trust for future settlement of equity-based awards.
Oliver Chow, Chief Financial Officer
“As signaled last quarter, we prioritized deleveraging over share repurchases, reducing our net debt leverage ratio by approximately 0.1x sequentially, keeping us on track to fall below 3.0x during the first half of 2027…”
Outlook and what happens next
For FY 2026, Consolidated AEBITDA growth is expected to be toward the lower end of the previously announced range of mid-to-high single digits. Adjusted NPATA is expected to grow faster than Consolidated AEBITDA, and EPSa faster than Adjusted NPATA.
The outlook reflects weakness in the social casino market and some delayed timing of investments and capital expenditures by customers. These are partially offset by the growing recurring revenue base and an expected seasonally strong fourth quarter.
Events and targets stated in the announcement:
- Earnings call: Executive leadership hosts a call on Wednesday 4 November 2026 at 5:00 p.m. EST (Thursday 5 November 2026 at 9:00 a.m. AEDT) to review the third quarter results. A webcast replay will be archived on the investor site.
- Net debt leverage ratio: The company remains on track to continue reducing the ratio toward 3.0x by the end of FY 2026 and below 3.0x during 1H FY 2027. This is a forward-looking non-GAAP measure presented on a supplemental basis and does not reflect company guidance.
- Fourth quarter: Further acceleration in Gaming machine sales is expected.
Don’t Miss the Next Consumer Discretionary Winner
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ investors who stay ahead of the market. Click the “Free Alerts” button at Big News Blast to receive alerts the moment market-moving announcements break.