
City Chic expects positive first-half EBIT as full-price stores surge 19.6%
City Chic Collective (ASX: CCX) has provided a trading update for the 18 weeks to 1 November 2026, based on preliminary and unaudited results. The company is expecting to generate positive EBIT in 1H FY27, subject to continuing sales momentum into the busy Black Friday and Christmas trading period.
Group revenue, excluding wholesale, was down 1.7% on the prior corresponding period (PCP), while gross margin dollars increased 2.2%. Group trading gross margin rose 240bps, so the earnings story is being driven by margin quality rather than sales volume.
Key highlights from the update:
- Group comparable sales up 1.2%, with comparable trading gross margin dollars up 5.1%
- ANZ comparable store sales up 15.4%, with full price stores up 19.6%
- City Chic remains on track to end 1H FY27 with a positive cash balance and no drawn debt
Phil Ryan, Chief Executive Officer and Managing Director
“The sales momentum we have built through the Spring season in ANZ, together with expanded gross margins from a stronger full-price sales mix, demonstrates that our strategy is delivering improved trading performance, despite a challenging retail environment.”
When big ASX news breaks, our subscribers know first
Strategic reset delivers margin expansion
Why City Chic cut promotions in August
In August, the company made a planned step change to materially reduce promotional activity, particularly online. It also reshaped the price point mix to deliver value in the current retail environment.
Mr Ryan said the reduction “initially affected sales, particularly online where we comped higher promotional activity last year.” Sales momentum has since improved in response to the new season range, with materially healthier margins, according to the company.
For investors, the trade-off is a short-term hit to sales in exchange for stronger gross margins. The company said the Spring/Summer range has been well received.
Performance by channel
The source table for the 18 weeks of FY27 is reproduced below as presented.
| FY27 (weeks 1-18) | Comp Sales Growth | Comp Margin Growth | Sales Growth | GM$ Growth |
|---|---|---|---|---|
| ANZ | 2.6% | 5.0% | 0.2% | 3.8% |
| USA | -12.0% | 7.1% | -34.2% | -32.3% |
| USA (ex WHS) | n/a | n/a | -13.0% | -8.7% |
| Total | 1.2% | 5.1% | -6.1% | -2.4% |
| Total (ex WHS) | n/a | n/a | -1.7% | 2.2% |
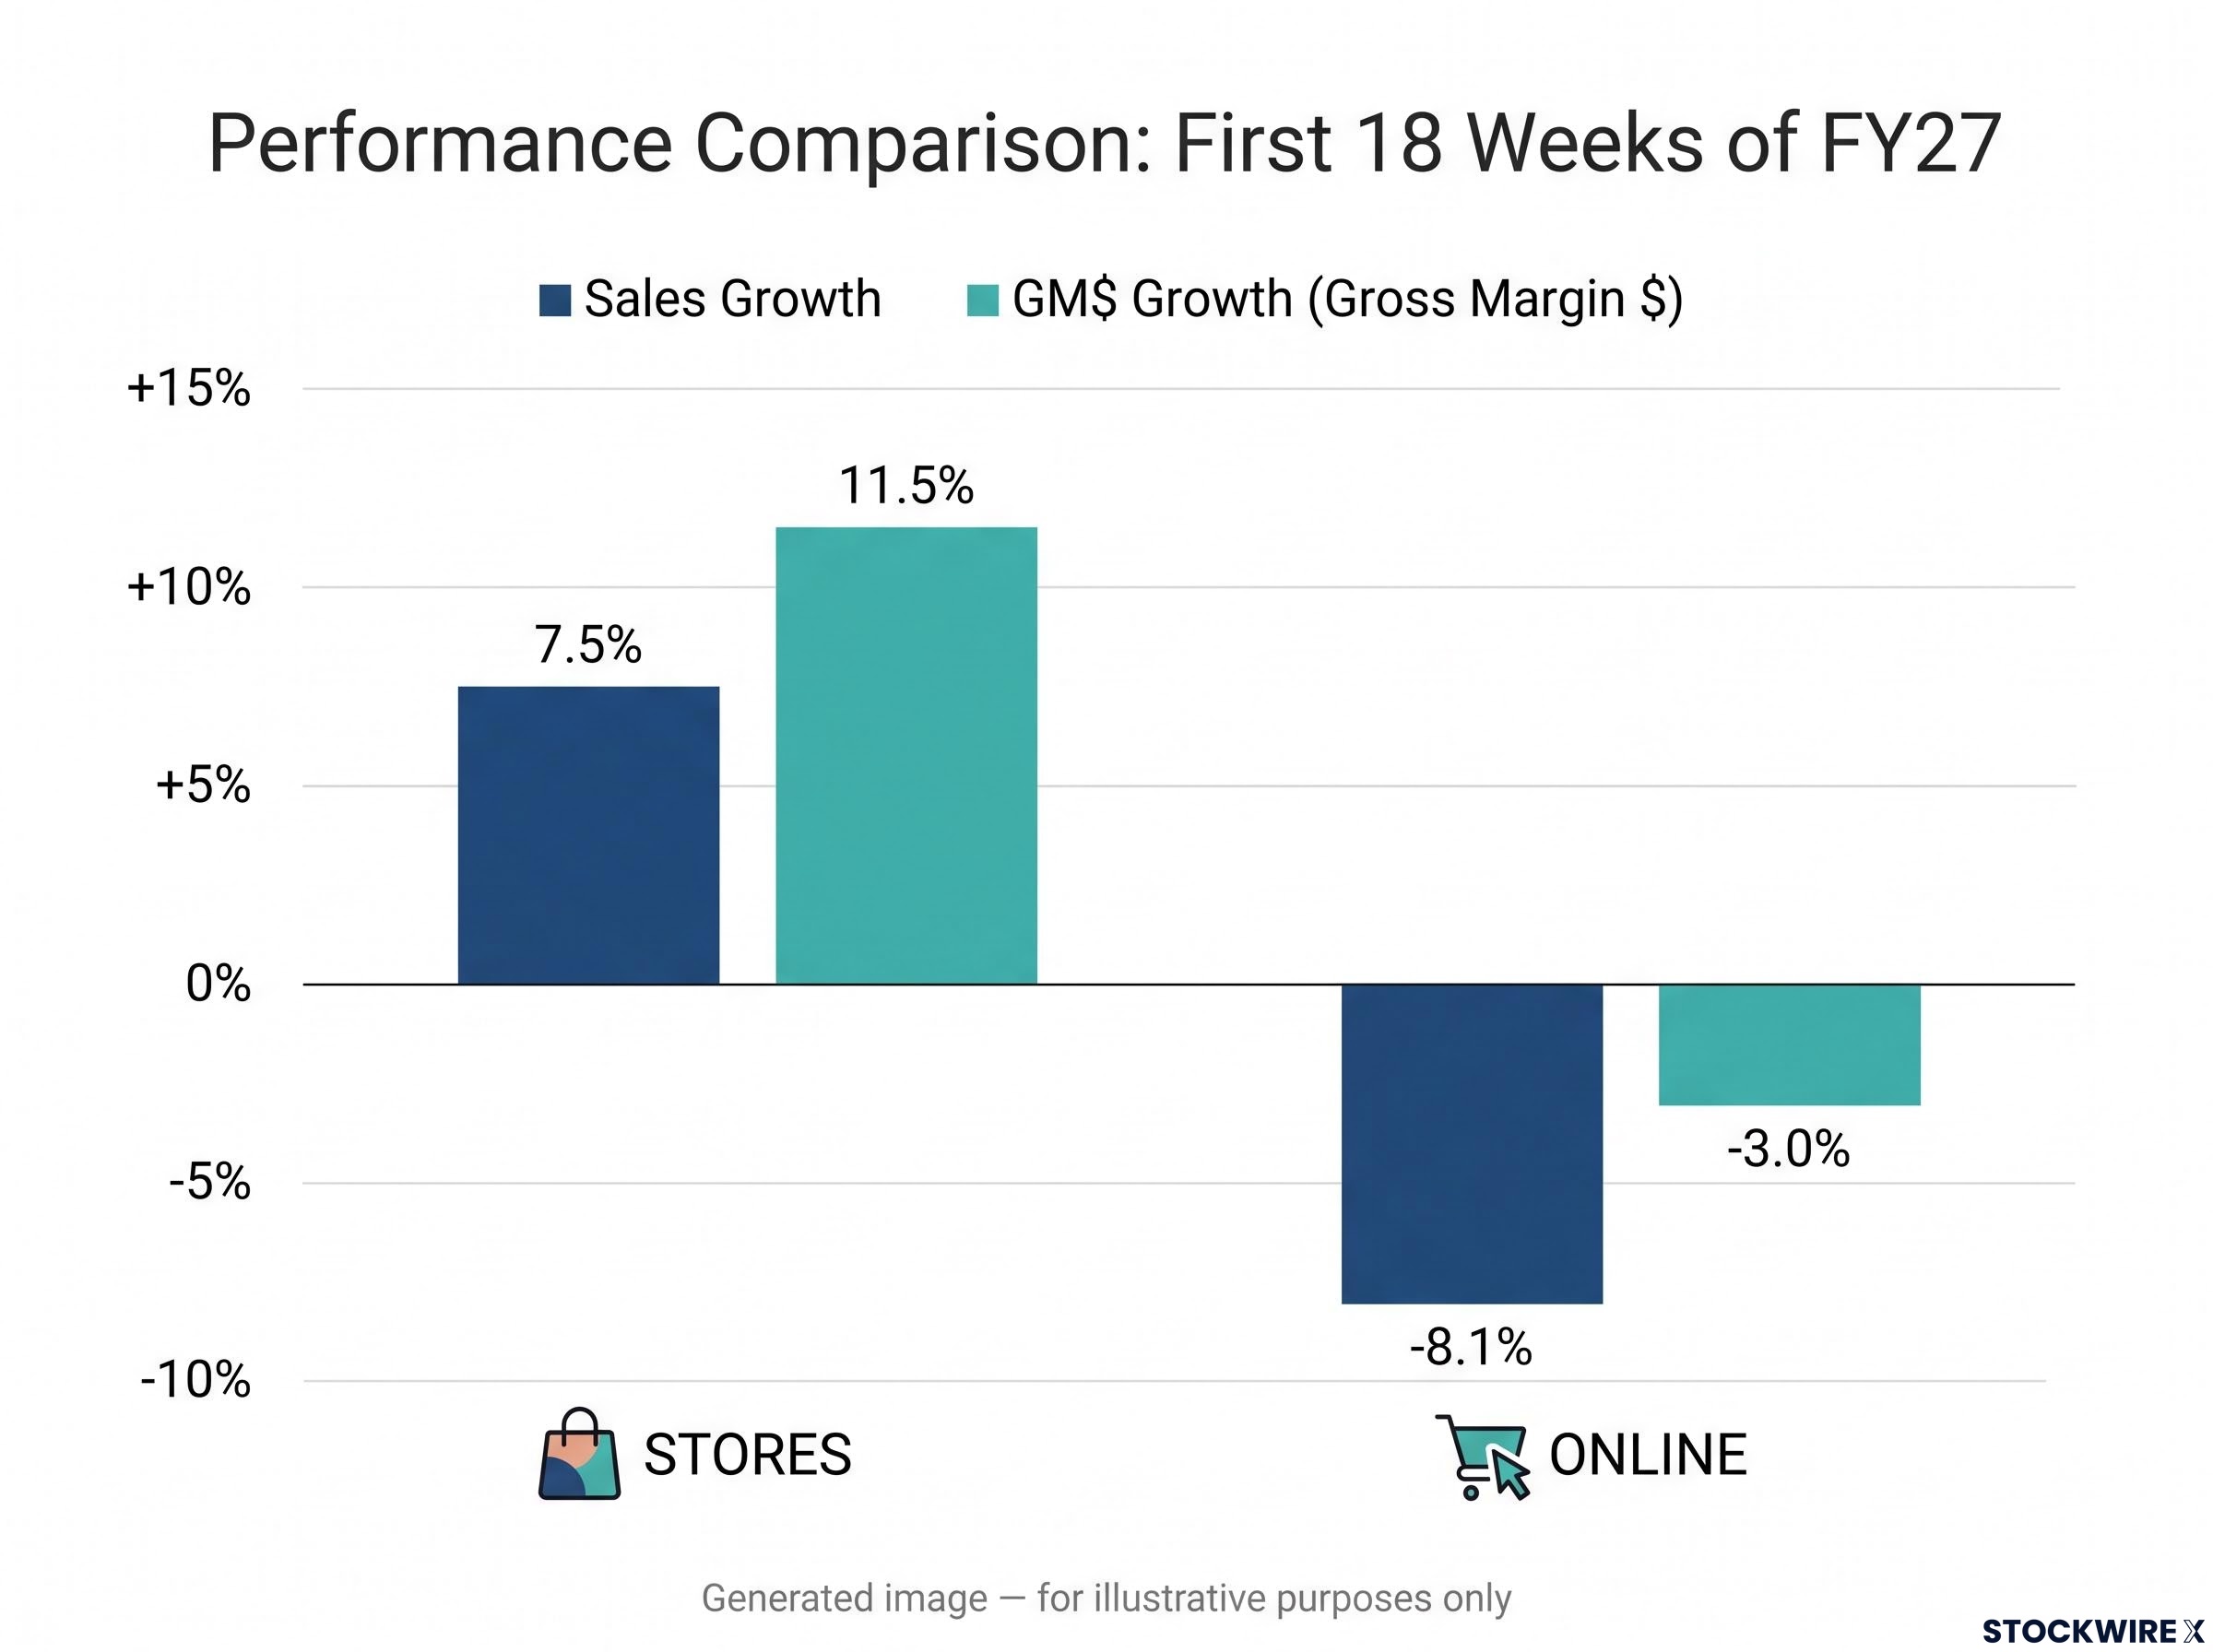
| Stores | 15.4% | 15.5% | 7.5% | 11.5% |
| Online | -8.1% | -3.0% | -8.1% | -3.0% |
| Marketplace | 14.9% | 14.1% | -8.5% | -14.6% |
| Discontinued – WHS | n/a | n/a | -100% | -100% |
The body of the announcement adds further detail on online and the USA:
- ANZ online trading gross margin was up 200bps, with comparable sales down 7.4% and trading gross margin dollars down 4.5% as a result of the strategic reset
- USA comparable sales were down 12.0%, while comparable trading gross margin dollars rose 7.1%
- USA online trading gross margin was 1,060bps above the PCP, and the USA business remains profitable
City Chic said it continues to focus on rebuilding sales momentum in the USA.
The weakness in the US traces back to a tariff-driven inventory pullback last financial year, when management deliberately cut purchasing during tariff volatility before normalising buying.
Stores lead the profit story
ANZ stores delivered comparable sales growth in each of the first 18 weeks of FY27, with full-price stores delivering comparable sales growth of 19.6%. Total store sales increased 7.5%, reflecting comparable store sales growth of 15.4%.
Clearance stores also recorded improved profitability as the DFO strategy continued to gain traction. The total store network was seven stores smaller than in the PCP, four stores have closed since June, and Rouse Hill Town Centre opened in October. City Chic operates a network of 72 stores across Australia and New Zealand.
Why full-price mix matters more than headline revenue
Gross margin is the share of each sale left after the direct cost of the product. Selling more items at full price lifts that share, so a retailer can earn more from fewer sales when it discounts less.
That dynamic is visible in the group result, where revenue excluding wholesale fell 1.7% while gross margin dollars rose 2.2%. The company also pointed to a more profitable ANZ online sales mix with lower associated fulfilment costs, which it said is strengthening performance.
The FY26 earnings recovery was built on a 209bps gross margin expansion and a $7.1m cut to the cost of doing business, which is why the current quarter’s margin gains read as a continuation of a pattern rather than a one-off.
Balance sheet and what happens next for City Chic
The Group’s $10 million debt facility remains in place until 31 March 2028. City Chic does not expect to have any drawn debt at the end of 1H FY27, and operating costs remain tightly managed and aligned with trading activity.
The company stated the following forward events:
- The second of the two required FY27 clean downs is expected to be completed in December 2026. The first has been completed.
- The busy Black Friday and Christmas trading period is the stated condition for the expected positive first-half EBIT, which is subject to continuing sales momentum.
- City Chic will provide a further update with its 1H FY27 results in February 2027.
Retail conditions remain challenging and the peak trading period is still ahead. Even so, the company said the trading performance to date reinforces its confidence in its strategy.
Don’t Miss the Next Consumer Retail Winner
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors who stay ahead of the market with Big News Blast. Click the “Free Alerts” button now to receive consumer sector alerts the moment market-moving news breaks.