
Schoolblazer outlines A$5.325m placement to cut parent-level debt
In its equity raising investor presentation, management at Schoolblazer Limited (ASX:SBZ) outlined a two-tranche institutional placement of approximately 53.25 million new fully paid ordinary shares at A$0.10, to raise A$5.325 million. The company stated it has received binding commitments for the placement.
The offer price represents a 13.0% discount to the last close on 29 October 2026. Proceeds are to be used to partially repay the IFM facility at the SBZ parent level, reducing SBZ’s debt and interest costs, and to fund working capital and the costs of the offer.
Blue Ocean Equities Pty Limited and E&P Capital Pty Limited have been appointed as Joint Lead Managers and Joint Bookrunners. New shares will rank equally with existing fully paid ordinary shares.
How the placement is structured
The presentation split the placement into two tranches:
- Tranche 1: approx. 14.4 million new shares to raise approx. A$1.44 million, issued using the company’s existing placement capacity under ASX Listing Rule 7.1.
- Tranche 2: approx. 38.8 million new shares to raise approx. A$3.88 million. This comprises 17.5 million shares (A$1.75 million) relating to Director participation, conditional on shareholder approval under ASX Listing Rule 10.11, plus approx. 21.3 million shares (approx. A$2.13 million) issued under Listing Rule 7.1.
Pro-forma fully paid ordinary shares after the placement, including employee shares, total 594,931,955.
When big ASX news breaks, our subscribers know first
Balance sheet and debt reduction
Management presented a pro-forma position based on 31 August 2026 unaudited management accounts, as if the raise and the September debt repayments had occurred on that date. It is not a forecast.
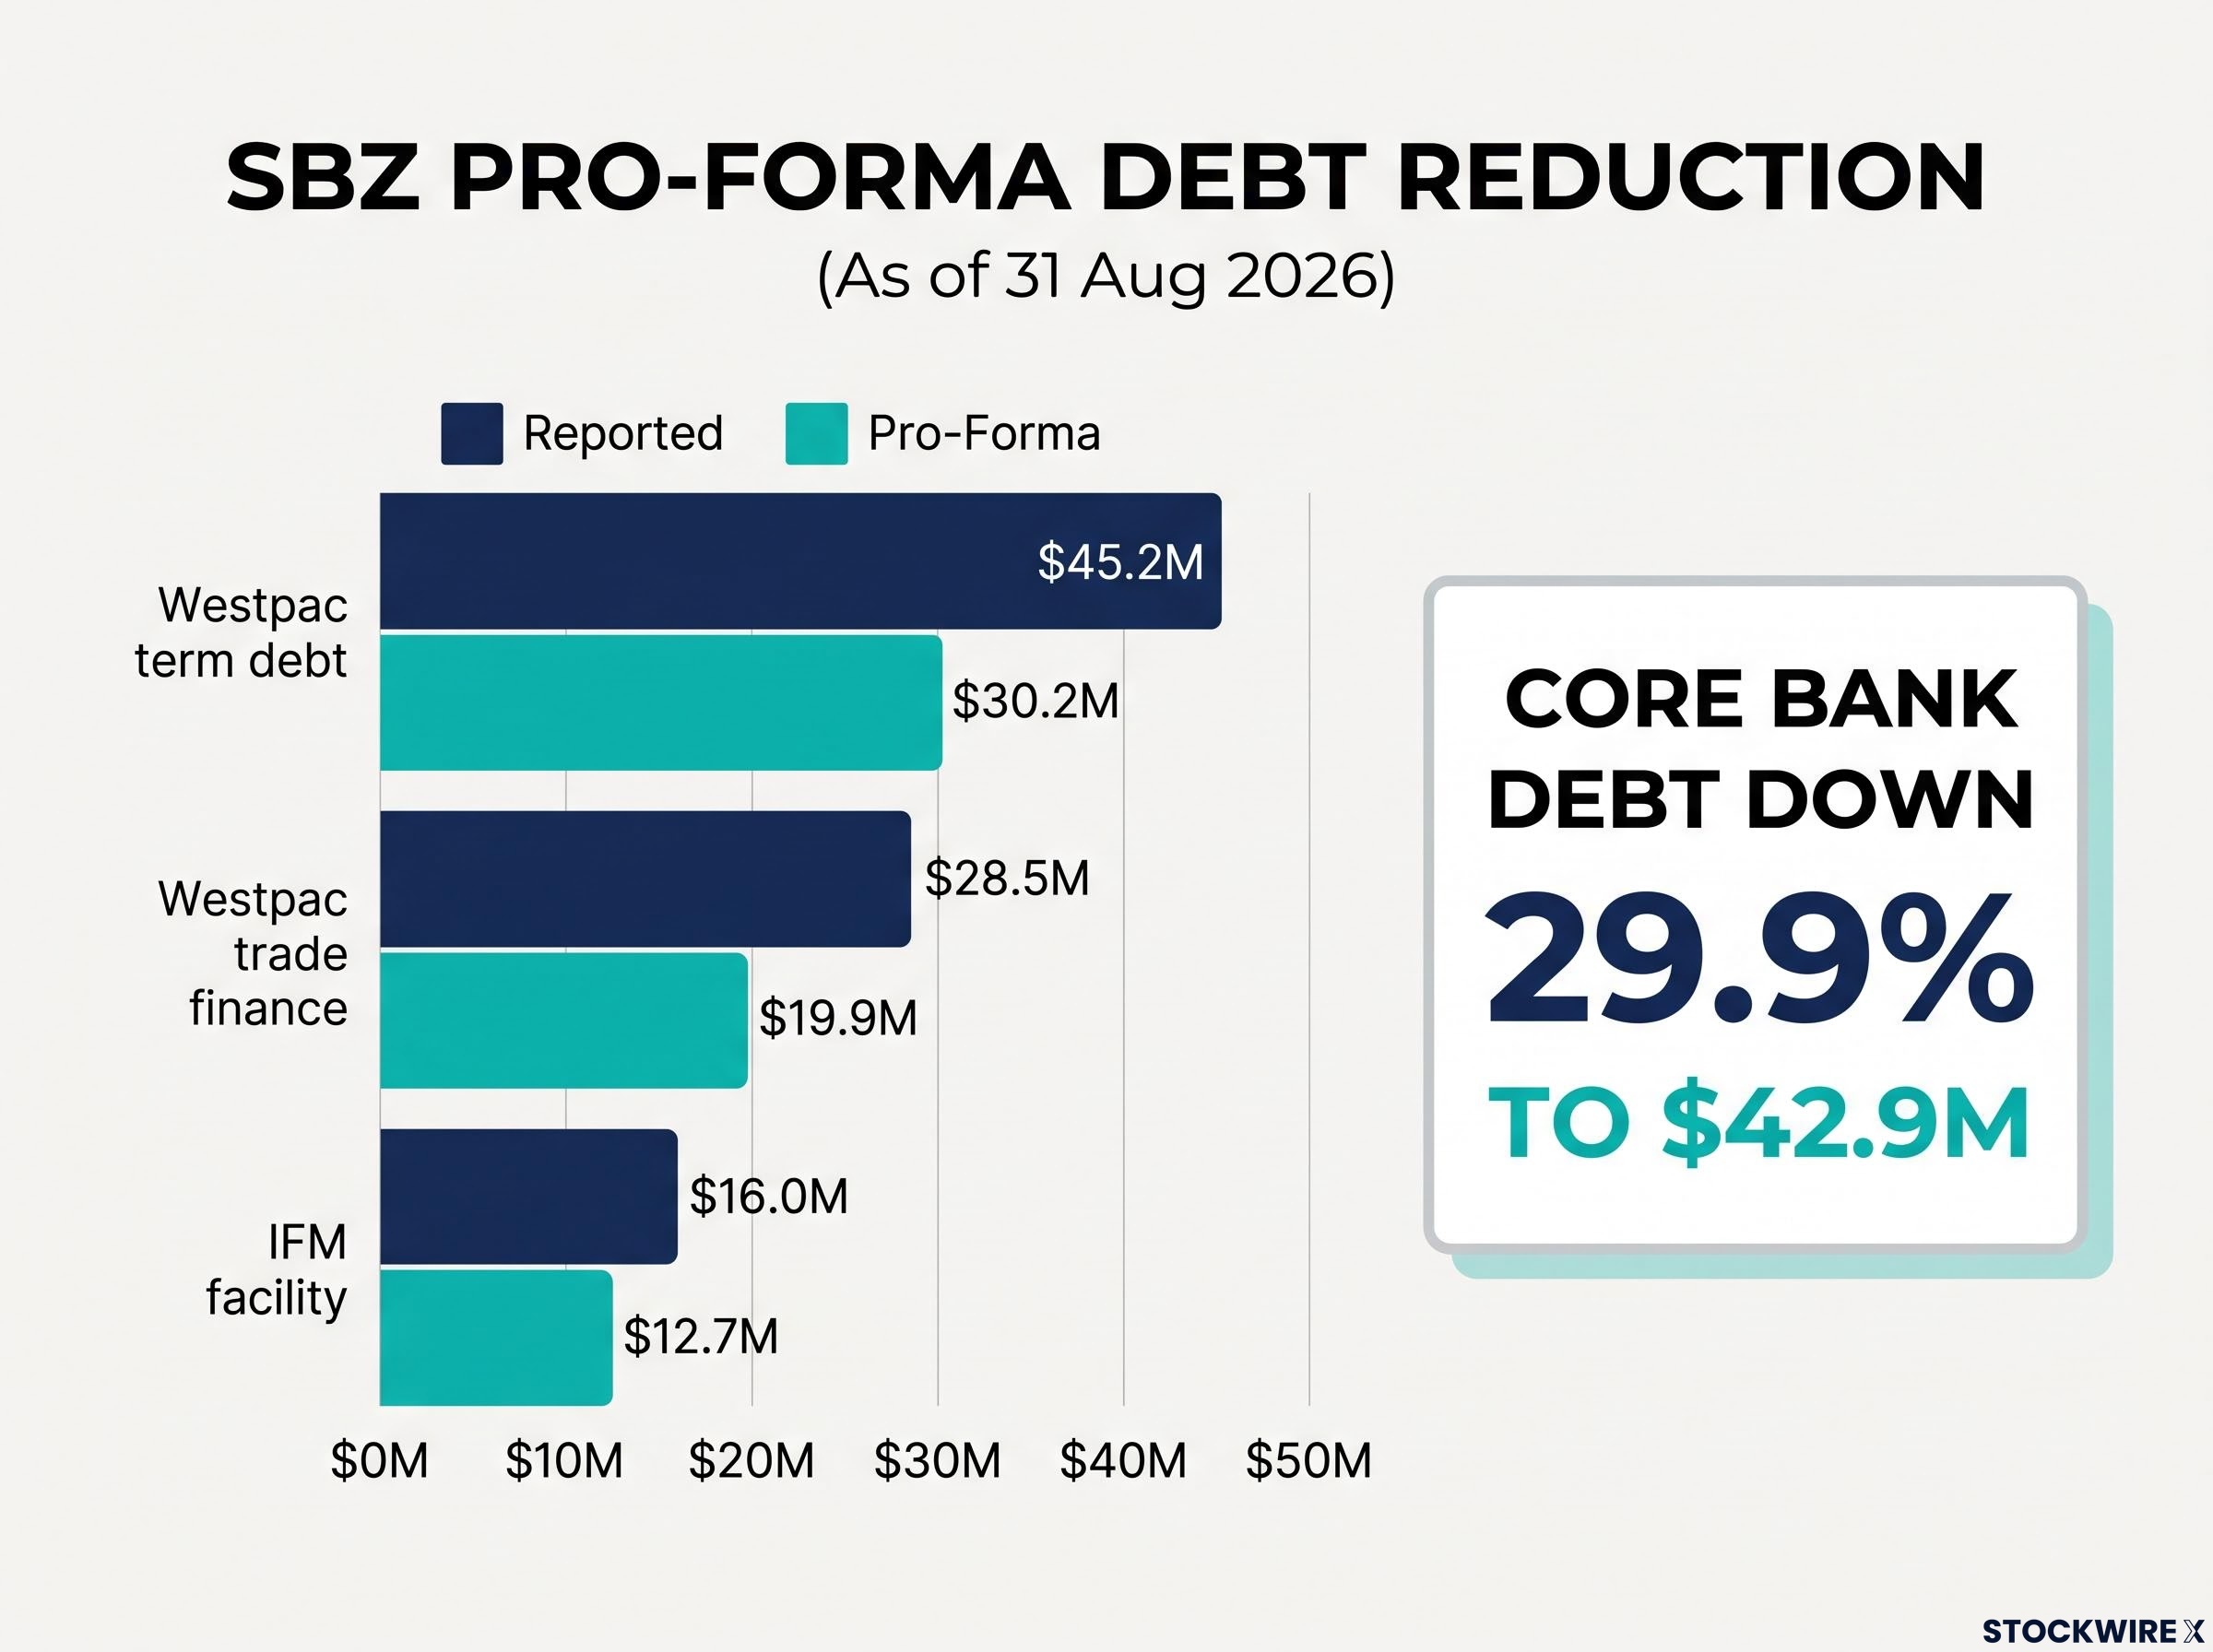
Of the A$5.3M raise, $3.3M repays a portion of the IFM facility (from $16.0M to $12.7M), leaving $1.7M for working capital and interest post fees. Key pro-forma points included:
- Westpac term debt reduced by $15.0M, from $45.2M to $30.2M
- Westpac trade finance reduced by $8.5M, from $28.5M to $19.9M
- Core bank debt (Westpac term plus IFM) down 29.9% to $42.9M
- Pro-forma cash of $8.0M, down from $29.8M
- Annual interest expenses reduced by approximately $1 million from $18 million of core debt repayments, based on current interest rates
- Net working capital cover of trade finance rising from 2.49x to 3.55x
| A$m, Consolidated SBZ | Reported 31 Aug 26 | Sep 26 debt repayment | Equity Raise | Pro-forma 31 Aug 26 |
|---|---|---|---|---|
| Cash | 29.8 | (23.5) | 1.7 | 8.0 |
| Westpac term debt (SBG) | 45.2 | (15.0) | n/a | 30.2 |
| Westpac trade finance (SBG) | 28.5 | (8.5) | n/a | 19.9 |
| IFM facility (head company) | 16.0 | n/a | (3.3) | 12.7 |
| Net assets | 139.3 | n/a | 5.0 | 144.3 |
Lender position and non-cash items
The IFM facility has a single net leverage covenant at SBZ level, which has been amended to provide waivers and headroom during certain quarters of FY26 and FY27. Management stated IFM is supportive, the planned repayments are being made early, and maturity remains in November 2027.
SBG covenants commence testing on 30 September 2027, with key covenants being Term Debt/EBITDA and Interest Cover. Management expects headroom on the FY27 guidance range.
On statutory accounts, a material FY26 loss is expected from non-cash acquisition accounting adjustments. Estimated impacts to NPAT, subject to audit, include a one-off FY26 charge of $12-13m for inventory revaluation and ongoing $2-3m amortisation of intangible customer relationships.
SBZ’s market capitalisation is below its net assets, which is an impairment indicator under AASB136 and may result in an impairment subject to the final audit.
What a school uniform platform actually earns from
Schoolblazer Group describes itself as a global school uniform and sportswear supplier to over 1,000 contracted schools. The presentation set out a four-step model:
- Schools appoint the company on multi-year contracts.
- An in-house team designs uniforms incorporating each school’s themes and identity.
- Group-wide sourcing teams and international offices source the product.
- Families buy online for home delivery, or in stores, while wholesale channels also sell to schools and retailers.
Management said multi-year contracts are sticky, describing the revenue book as defensive. At FY26 close the group had 1,066 contracted schools with 98% retention. In the UK, Schoolblazer has exclusive 3-5 year contracts that allow for inflation protection.
On FY26 unaudited, constant currency figures, revenue by geography was UK 57%, Australia 25%, Rest of World 12% and New Zealand 7%. Direct Digital accounted for 39% of revenue by channel.
The group operates four brands: Schoolblazer (premium uniform), Trutex (value uniform), Limitless (premium sportswear) and Akoa (value sportswear).
Management described direct-to-parent channels as the higher-margin contracted channels the group is deliberately shifting toward. Its stated ambition is to target 75%+ for both direct digital and contracted schools.
FY26 trading update and FY27 outlook
The presentation restated the trading update dated 21 September 2026. FY26 revenue is expected at A$165-170m on a constant currency basis, against prior guidance of A$190m. SBG Underlying FY26 EBITDA is expected at A$11-13m, with gross margins remaining strong at c. 52%.
The FY26 earnings guidance miss reflected several external headwinds landing in the final quarter, with a largely fixed cost base amplifying the revenue shortfall against the A$190m target.
Management cited several pressures:
- UK private school VAT: 20% VAT imposed in 2025, with enrolments down an estimated 8-10% year on year
- China: Trutex sales fell c. 61%, taking c. A$5.7m off group revenue
- UK wholesale de-stocking: retailers reduced inventory ahead of new limits on compulsory branded uniform items
Positives included direct-to-parent channels up 0.5%, 29 net new schools in FY26 and 22 already contracted for FY27. SBG also reported $20m of operating cash flow before interest in 2H FY26.
| Constant currency, A$000s | FY26 Unaudited | FY25 Pro Forma | Variance % |
|---|---|---|---|
| Direct Retail | 21,169 | 19,626 | 7.86% |
| Direct Digital | 66,203 | 67,309 | (1.64%) |
| Wholesale to Retailer | 43,350 | 53,155 | (18.45%) |
| Wholesale to School | 37,255 | 39,355 | (5.34%) |
| Total Revenue | 167,977 | 179,444 | (6.39%) |
For FY27, SBG guidance is $170-180m revenue and $18-20m EBITDA. The indicative bridge starts from the $12m FY26 guidance midpoint, adding $4.0m of cost savings, 1.0-2.0 from gross margin improvement and 1.0-2.0 from new contracts.
The bridge excludes approximately $2.6m of SBZ head company costs, which would reduce consolidated Underlying EBITDA. Management said the A$25m EBITDA target remains achievable but is deferred, subject to achieving FY27 guidance and progressing the global sourcing initiative.
On cost savings, management described approximately A$4m of FY27 savings, over half of which is already confirmed or in execution.
What happens next for Schoolblazer
The presentation’s indicative timetable and related milestones are below. Dates are indicative and subject to change, and the company reserves the right to vary them without notice.
- Trading halt: Friday, 30 October 2026 (completed).
- Recommencement of trading: Tuesday, 3 November 2026.
- Tranche 1 settlement: Monday, 9 November 2026.
- Tranche 1 allotment: Tuesday, 10 November 2026.
- General Meeting to approve Director participation in Tranche 2: expected in December 2026.
- Tranche 2 settlement and allotment: expected in December 2026.
- SBG covenant testing begins 30 September 2027.
- IFM facility maturity: November 2027.
- 90.67M SBZ shares remain escrowed until October 2027.
Don’t Miss the Next Consumer Sector Mover
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving news breaks, and stay ahead of the market.