West Texas Intermediate (WTI) crude fell about 9% on Wednesday, 4 November 2026, to a four-week low near $88 a barrel, a day after the US midterm elections. The slide arrived on the same morning that official US inventory data came in bullish, the kind of report that normally pushes the WTI crude oil price higher, not lower.
At first, no single headline explained the fall. The weight of the evidence now points to traders cutting the odds of a near-term US-Iran escalation, which drained the war premium built into the price.
The numbers themselves are messy. Prices swung sharply during the session, sources quote different levels, and no official 4 November settlement had been identified at the time of writing (all prices in US dollars).
Here is a clear read on which explanation the evidence best supports, why the good inventory news failed to help, and how to interpret a move like this the next time it happens.
What actually moved the WTI crude oil price on the day after the midterms?
The price action
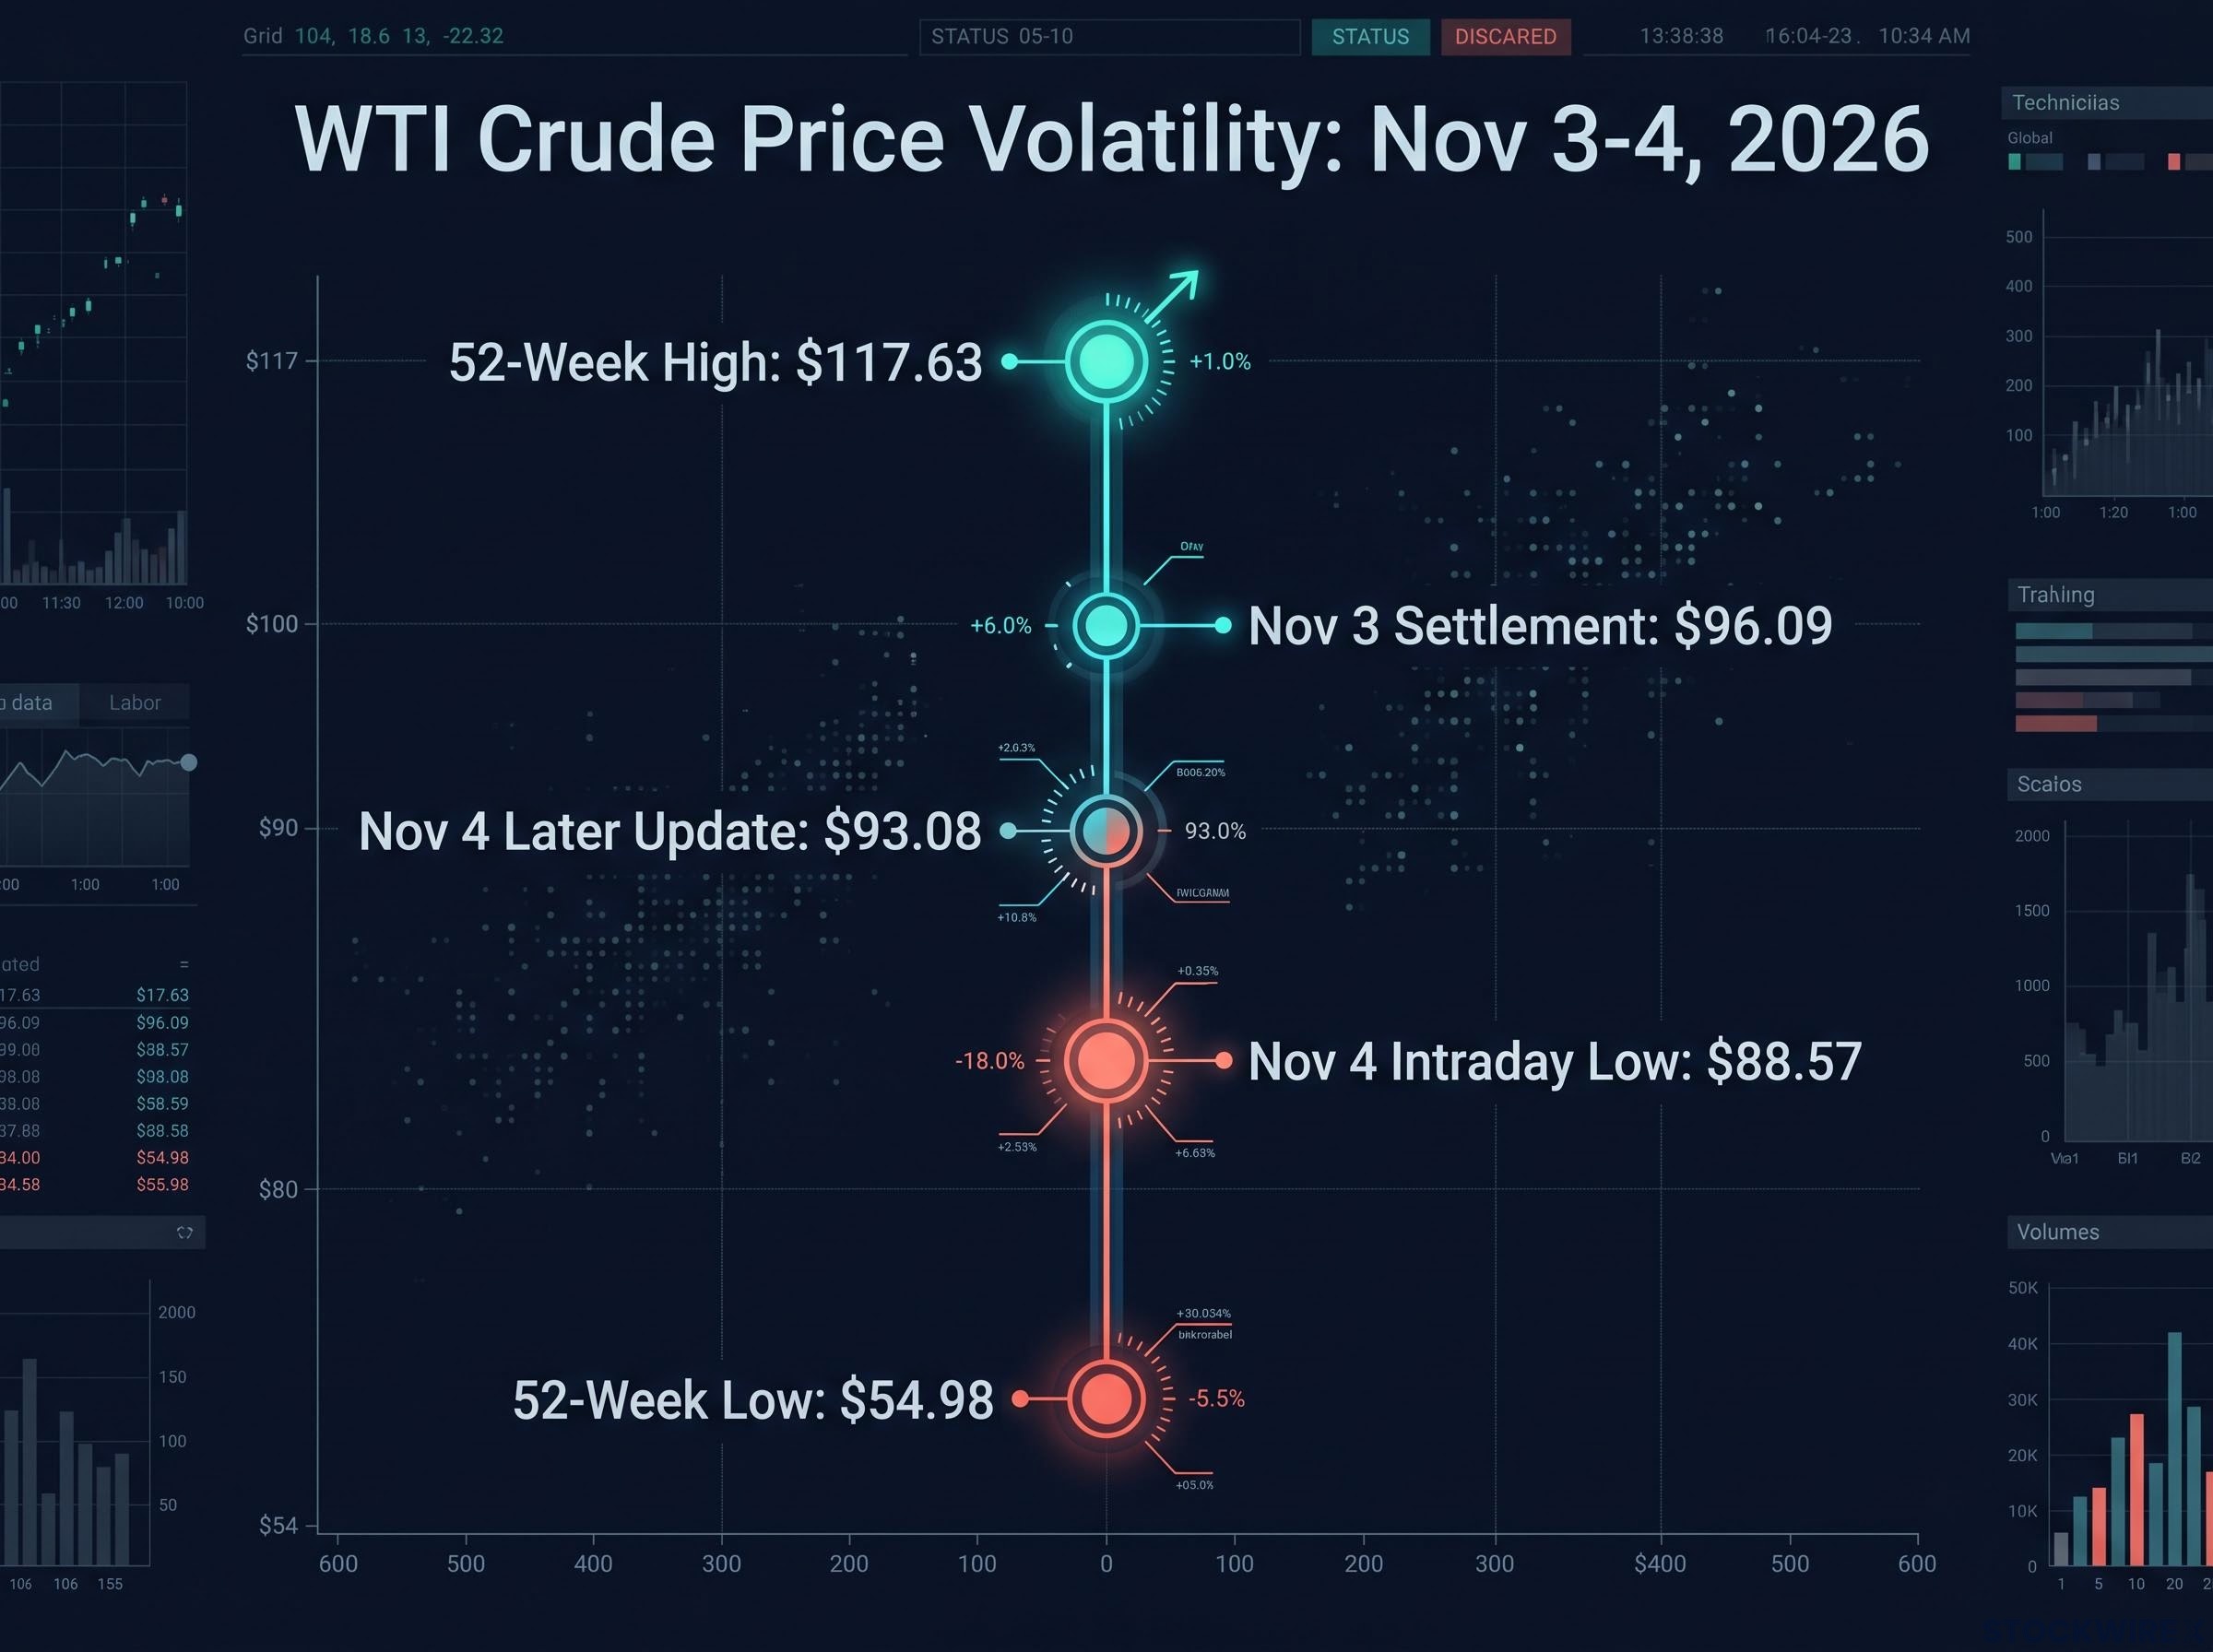
The December WTI contract settled at $96.09 on 3 November, the prior session. On Wednesday it broke lower, with intraday reports placing the low between $87.74 and $89.36.
That gap explains the conflicting figures. The $96.09 is yesterday’s official close; the roughly $88 figure is today’s intraday trough, and a later Reuters quote shows prices had already recovered part of the ground.
| Source | Level quoted | Change | Timing |
|---|---|---|---|
| CME settlement (via Yahoo Finance, MarketWatch) | $96.09 | Down $0.37 | Prior session, 3 November |
| Economic Times | $88.57 | Down $7.52 | Intraday, 4 November |
| Reuters (later update) | $93.08 | Down $3.01 | Later session, 4 November |
For scale, the 52-week range runs from a high of $117.63 to a low of $54.98.
The political and diplomatic backdrop
The pieces started arriving on Monday. Qatari mediators flew to Tehran on 2 November to meet Iranian Foreign Minister Abbas Araghchi, expecting feedback from both sides within about 36 hours, although a senior Iranian official told Reuters the two sides remained far apart.
Then came Donald Trump’s interview with the Financial Times.
Trump said the US had “no immediate plans” to strike Iran, adding: “We seem to be getting everything we want.” He also said the US was “locked and loaded” if needed.
Tim Waterer of KCM Trade told Reuters that diplomatic hopes, plus a weekend without meaningful military escalation, took some immediate heat out of prices. The midterms added a further layer: Democratic gains could increase pressure to limit war funding, and Senate Democratic Leader Chuck Schumer vowed to end the war, a pledge in the original reporting that later research could not independently confirm. CBS News also reported that Trump was weighing whether Defense Secretary Pete Hegseth should stay.
Reuters described the market as waiting for Washington’s next move. For you, that is the point: traders cut the probability of a supply shock, and the price fell with it, even though not a single barrel changed hands differently.
A similar paradox appeared in August, when Brent fell after a sweeping Treasury announcement because traders were pricing sanction credibility rather than the threat itself.
When big ASX news breaks, our subscribers know first
Why did a bullish inventory report fail to hold the market up?
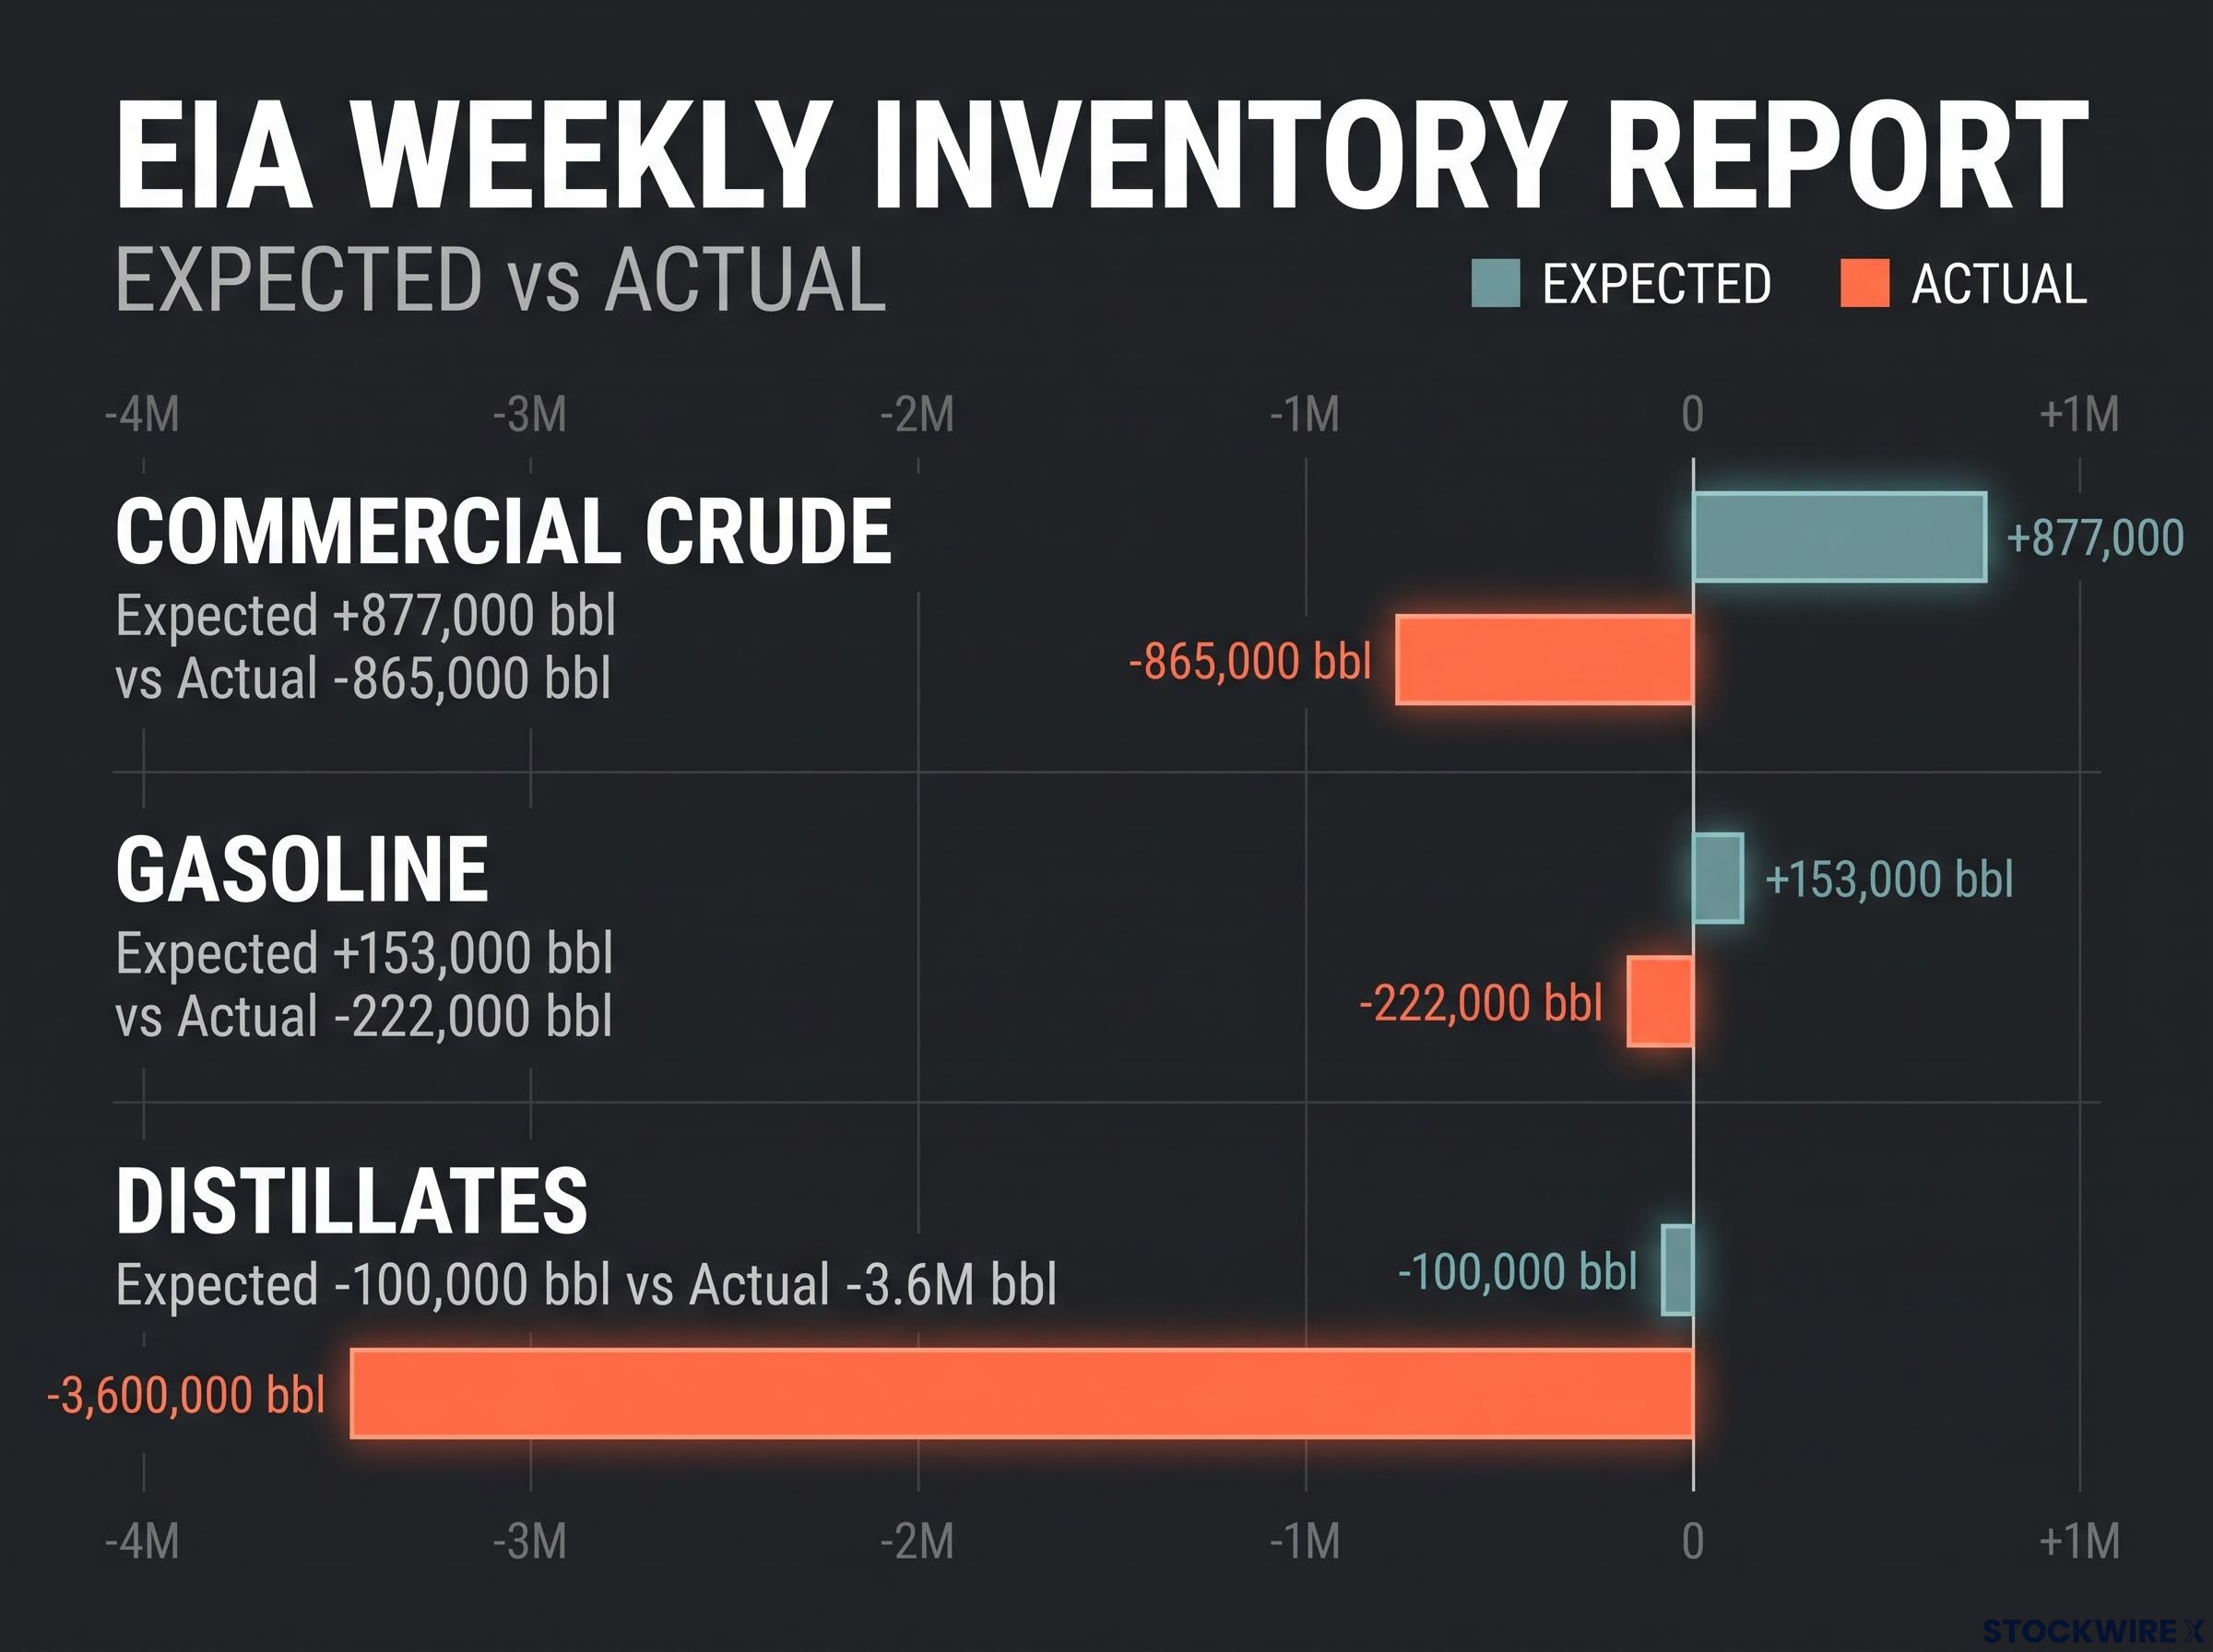
The Energy Information Administration (EIA) report should have been a lift. A Reuters poll expected US commercial crude stocks to build by 877,000 barrels; instead they fell 865,000 barrels to 409.8 million, although other surveys ranged widely.
| Category | EIA result | Expectation |
|---|---|---|
| Commercial crude | Down 865,000 bbl to 409.8M bbl | Build of 877,000 bbl (Reuters poll) |
| Cushing crude | Up 280,000 bbl | No comparable poll figure |
| Gasoline | Down 222,000 bbl to about 209.0M bbl | Build of 153,000 bbl |
| Distillates | Down 3.6M bbl to 99.3M bbl | Draw of 100,000 bbl |
Distillate stocks now sit about 13% below their five-year average. The American Petroleum Institute (API) had flagged an even larger crude draw of 5.267 million barrels the day before, and API and EIA figures land within 1% of each other about 75% of the time, with the EIA viewed as the more reliable.
None of it mattered for long.
Inventories describe what has already happened to supply and demand. Futures, contracts to buy or sell oil at a set price on a future date, react instantly to any change in the odds of disruption. When those odds fell, the backward-looking stock data simply lost the argument.
The wider backdrop also leans bearish once the premium fades:
- OPEC+ raised output targets during 2026 and completed the rollback of a 1.65 million barrel per day cut agreed in 2023.
- The EIA forecasts global demand to fall 1.1 million barrels per day in 2026, before rising 2.5 million barrels per day in 2027.
The final OPEC+ production increase of 188,000 barrels per day, approved in August, completed the unwinding of the 2023 voluntary cuts, and compliance gaps now matter more than the quota headline.
If you trade around the Wednesday EIA release, treat a good number as support, not a trigger. A geopolitical repricing will override it.
How do the dollar, OPEC+ and the war risk premium set the price of WTI?
The risk premium
What you saw on screen was a premium collapsing. A war risk premium is the extra amount traders pay above normal value because conflict threatens oil fields, terminals, pipelines or tankers. It builds before any supply is lost, and it can vanish just as fast when the threat recedes, even with tight stocks.
The Strait of Hormuz sits at the centre of it. Disruption to that transit route would lift freight and insurance costs and push buyers toward other supplies, and the EIA reports that Middle Eastern producers had already cut output by more than 11 million barrels per day.
There is precedent. After the US attack on Iran in June 2025, analysts quoted by CNBC expected an initial $3-$5 rise, with more only if Iran caused real disruption.
Goldman Sachs estimate: The Brent geopolitical premium fell from about $15 a barrel to $1 after the June 2025 ceasefire, with only a 4% estimated probability of a Hormuz interruption.
Dollar, OPEC+ and inventories
WTI is a light, sweet US crude, meaning low density and low sulphur, priced through the Cushing, Oklahoma hub and benchmarked alongside Brent and Dubai. Four drivers move it:
- Risk premium: rising threat lifts prices; easing threat removes the premium quickly.
- US dollar: a stronger dollar generally weighs on oil, though no 4 November source quantified its role today.
- OPEC+: the 12 OPEC members plus ten partners, including Russia, lift prices by cutting quotas and pressure them by raising output.
- Inventories: draws usually support prices, builds usually weigh, but both lag.
Market commentary placed support near $93 and resistance near $97, and selling through those levels likely added momentum, though that is inference from price action. Use the list as a checklist: when oil moves sharply without a stock-data cause, ask first whether the risk premium changed.
Could the slide reverse, and what would keep it going?
The drop is real, but it rests on odds that can flip within a single headline. The EIA’s own outlook still retains a risk premium, a reminder that the underlying war and Hormuz risks have not gone away.
Earlier in the year, record inventory draws of 8.5 million barrels per day failed to be offset by emergency reserve releases, which shows how stretched the physical balance had become before the premium faded.
| Reversal triggers | Extension conditions |
|---|---|
| Talks break down | Diplomacy produces a ceasefire |
| Renewed strikes or tanker attacks | Hormuz traffic normalises |
| Damage to oil infrastructure | Shut-in production returns |
| Renewed Strait of Hormuz threats | OPEC+ output keeps rising |
Under normalisation, the EIA expects most shut-in production to return by Q1 2027 and Brent to average $65 a barrel in 2027. Past performance does not guarantee future results; projections are subject to market conditions and various risk factors.
Even at $88, WTI sits nearly $30 below its 52-week high, and Reuters noted the market is waiting on Washington. Watch for:
- Iranian and US responses to the Qatari mediators
- Any congressional move on war funding
- Strike or tanker headlines from the Gulf
- OPEC+ output signals
Treat $88 as a snapshot of shifting odds, not a new floor, and expect swings in both directions.
What to watch next as the WTI crude oil price tests $93 and $97
The evidence points to a war premium unwinding, not a collapse in physical demand, with tight inventories acting as a counterweight rather than a cause.
The next signals are already lined up: feedback from Tehran and Washington to Qatari mediators, Congress’s stance on war funding, the decision on Hegseth, the next EIA release and any shift in OPEC+ output. Whether WTI holds below $93 or reclaims $97 will likely depend on those headlines more than on barrels.
Your filter for each one is simple. Ask whether it raises or lowers the odds of a supply shock, because that is what the market priced today.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.