An investment-grade label sounds like a public verdict that anyone can check. For a loan sitting inside a life insurer owned by a private credit giant, the rating may be one you will never see, and it can decide how much capital that insurer must hold. That gap is why private credit insurer ratings now draw scrutiny from regulators.
The scale is large. The National Association of Insurance Commissioners (NAIC) estimates U.S. insurers held about $1.2 trillion of private credit at year-end 2025, roughly 13% of their cash and invested assets.
The timing matters too. The NAIC’s new review process took effect on 1 January 2026. Commentator Chris Whalen argues the body has since backed off and that a federal insurance regulator is coming, while a Baltimore rental-loan fraud case shows how losses might spread.
Here is how the risk is supposed to work, where oversight actually stands, and how a loss in one corner could reach banks and the policyholders behind them.
How do private ratings lower an insurer’s capital requirements?
On paper, the process looks almost dull. A private-letter rating is a credit rating that an issuer or investor pays for and that is shared only with selected parties, not published. Insurers then use that rating to work out their regulatory capital.
The five-step chain
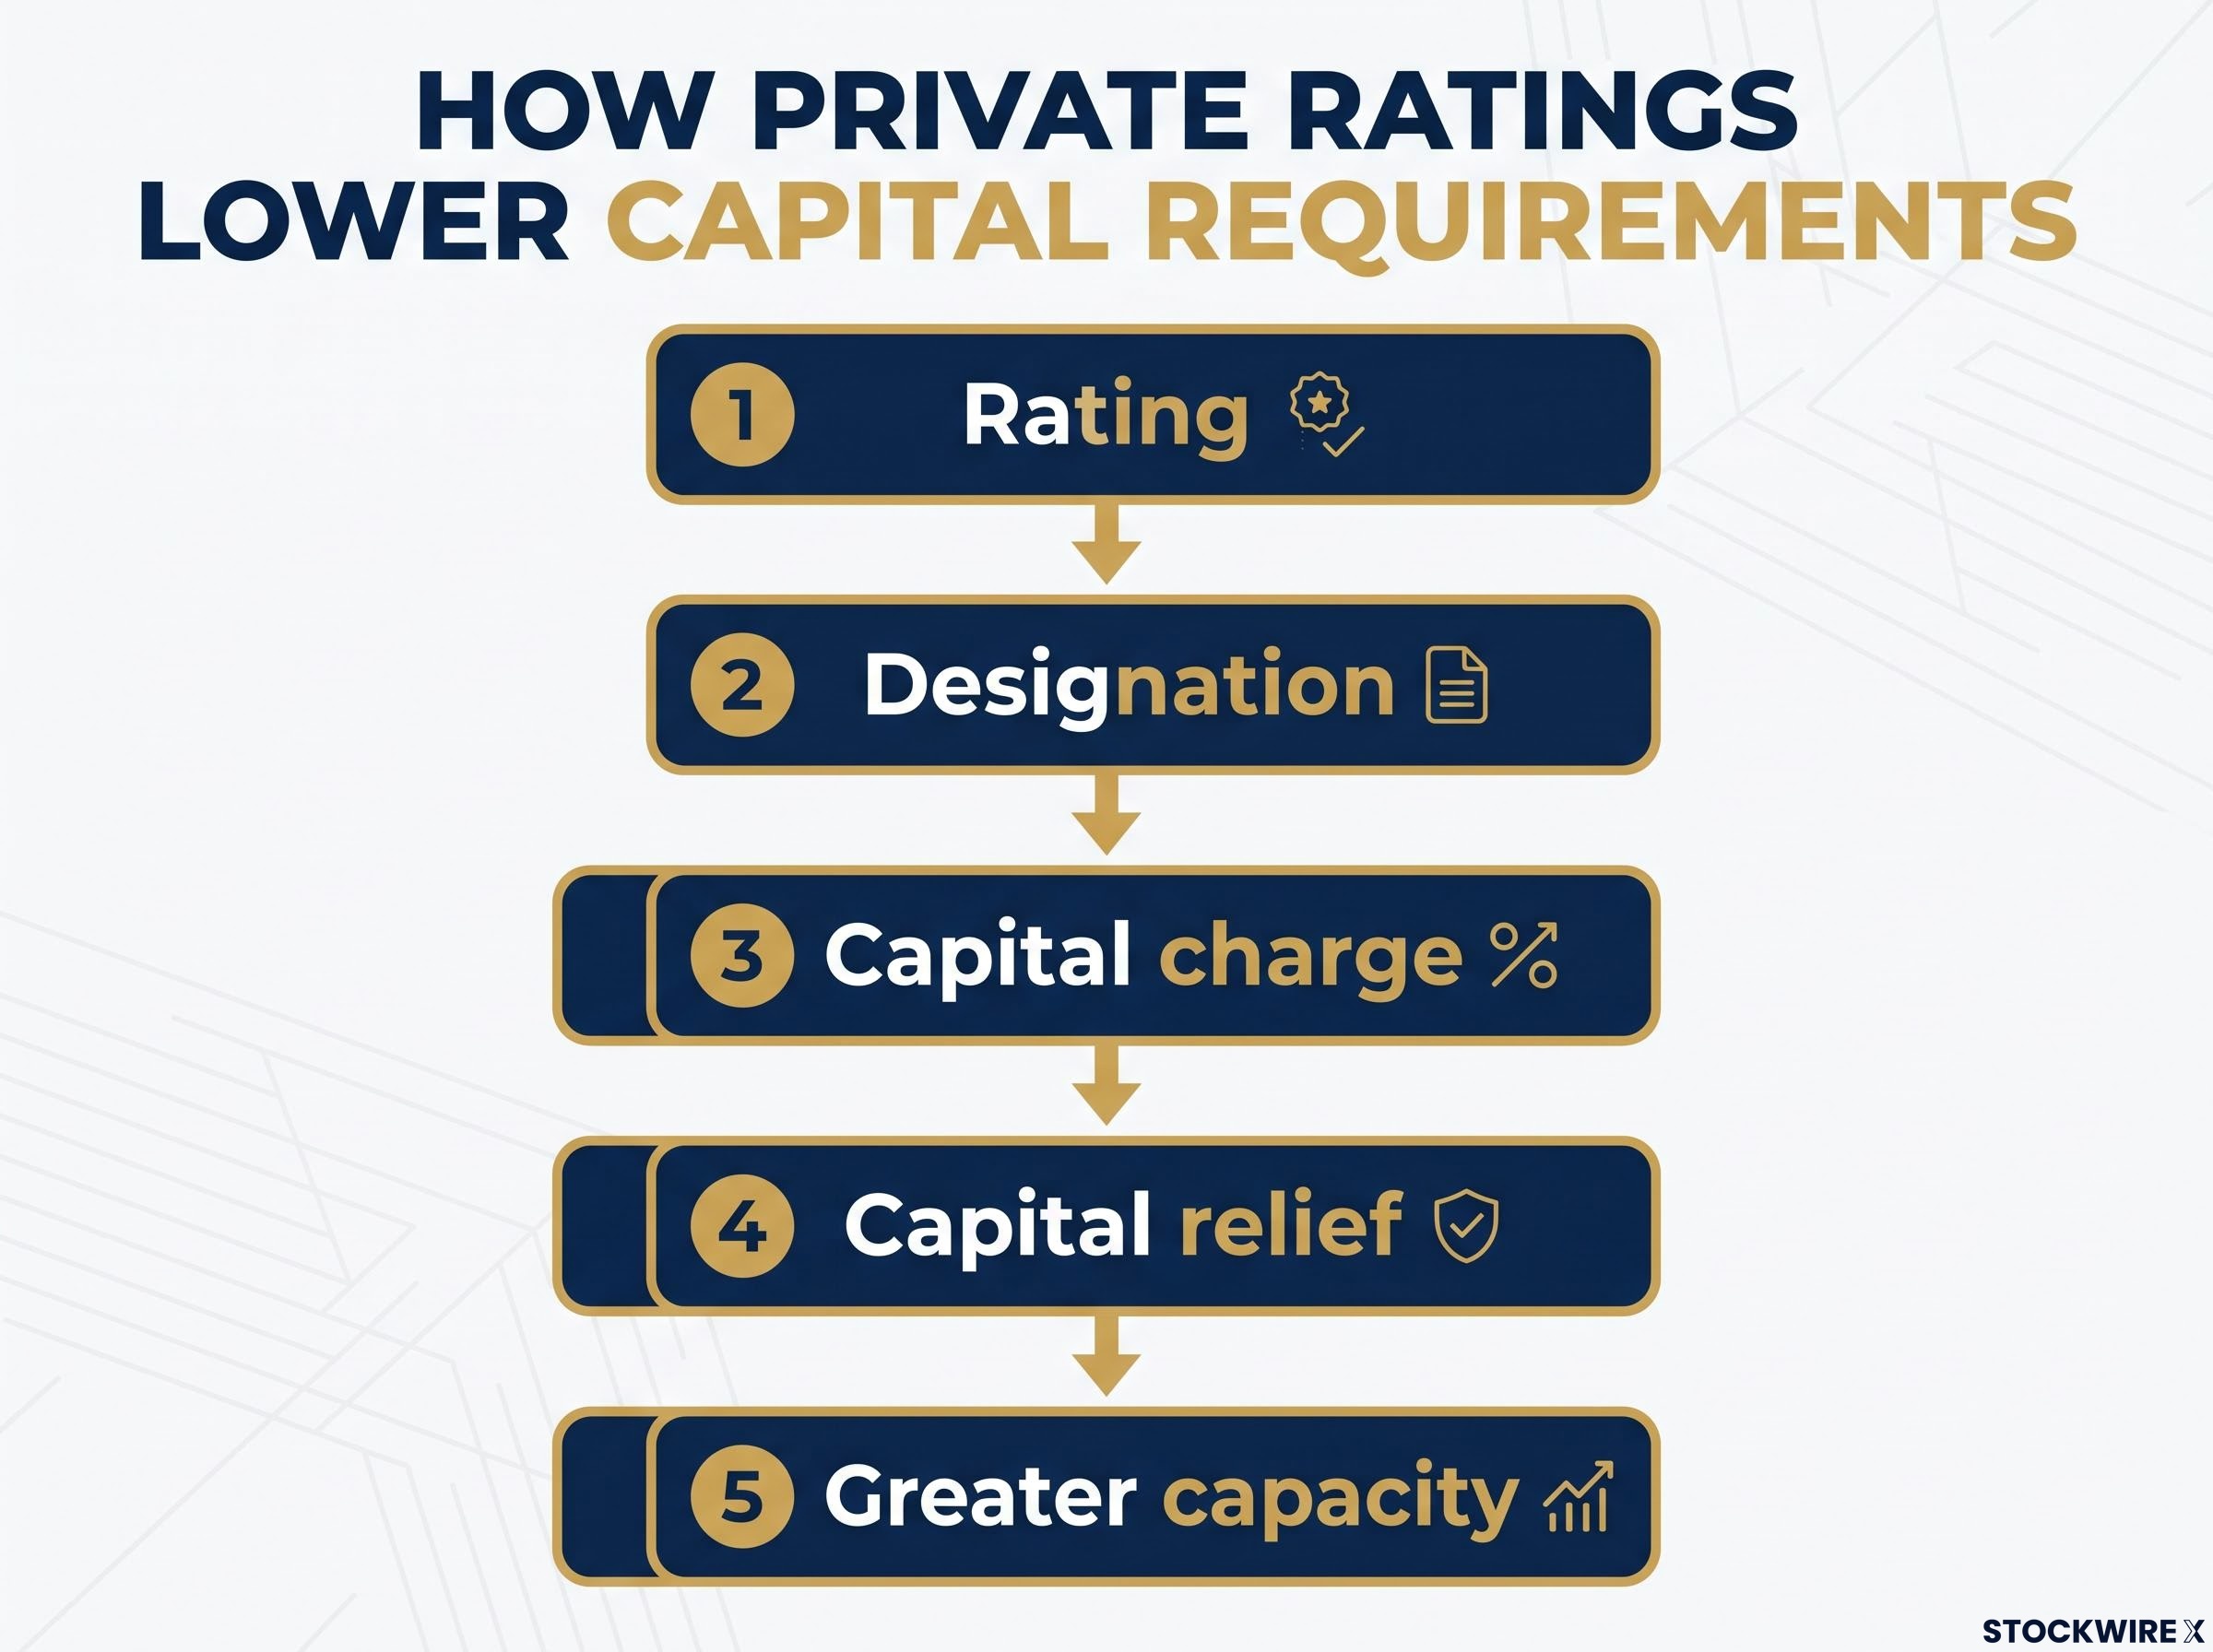
- Rating: An insurer obtains a private rating on an illiquid loan, private placement or structured asset.
- Designation: The rating is mapped to an NAIC designation, a regulatory score from strongest to weakest credit quality.
- Capital charge: That designation sets the risk-based capital charge, the amount of capital the insurer must hold against the asset.
- Capital relief: A higher rating lowers the required capital, even if the asset’s economic risk has not changed.
- Greater capacity: Insurers affiliated with private equity (PE) can then hold more private-credit assets with less statutory capital than a stricter assessment would demand.
Everything rests on step one. If that first rating is too generous, every step below it inherits the error.
Who issues these ratings? Increasingly, smaller agencies such as Egan-Jones, Kroll Bond Rating Agency and Morningstar DBRS. Private ratings are a major revenue source for agencies, which raises an obvious question about incentives when the client paying for the rating benefits from a higher one.
| Figure | Source and date | Why it matters |
|---|---|---|
| $1.2 trillion exposure; 13% of cash and invested assets; 21% of bonds | NAIC Capital Markets Bureau, year-end 2025 | Broadest recent official estimate |
| Private ratings 23% of investments at PE-affiliated insurers vs 8% elsewhere | Commentary on BIS analysis, November 2025 | PE-linked insurers lean on them more |
| Smaller agencies 86% of private-rating exposure, up from about 70% in 2019 | NAIC report, June 2024 | Concentration among smaller raters |
| About one-ninth of life insurers’ fixed income; over 50% of Level 3 | Moody’s, cited 2026 | Private ratings dominate the hardest-to-value assets |
| About 70% of Athene assets had two or more ratings, or NAIC/SVO-based ratings | Apollo, 24 November 2025 | Not the same as 70% carrying private ratings |
Level 3 assets are those valued with internal models because no observable market price exists. They are the least liquid holdings an insurer owns. Keep in mind that “private credit”, “private ratings”, “private placements” and “two or more ratings” describe different groups of assets, so the figures above cannot be swapped for one another.
How big the problem looks depends on who is counting, and the debate over private credit systemic risk turns on whether you measure insurer exposure narrowly from regulator data or broadly across all investments.
What critics and defenders each say
The International Monetary Fund’s October 2025 Global Financial Stability Report warned that misclassified below-investment-grade assets could produce defaults beyond expected losses in a shock. The Bank for International Settlements (BIS) has flagged transparency and incentive concerns, and UBS Chairman Colm Kelleher compared insurer rating-shopping with the arbitrage that preceded subprime.
Defenders counter that private loans often come with deep lender diligence, negotiated covenants and ongoing borrower information, and that they suit long-duration liabilities. This is a conditional channel, not proof that PE-owned insurers are insolvent or that every private rating is inflated.
If you hold or are weighing an annuity from a PE-affiliated insurer, those ratings affect how much capital stands behind your policy. Asking who rated the assets is a fair question.
When big ASX news breaks, our subscribers know first
Did the NAIC back away from scrutiny, or is the picture more mixed?
Whalen’s claim is pointed. In his view, the NAIC is a trade association of state commissioners rather than a true regulator, and it retreated after the industry pushed back.
The record tells a more complicated story. The Securities Valuation Office (SVO) discretion process became effective on 1 January 2026. Insurers must file private-letter ratings and rationale reports, and the SVO can challenge a rating on a filing-exempt security if it may not reasonably reflect the investment risk.
The SVO discretion process lets the Securities Valuation Office challenge a private-letter rating on a filing-exempt security, but only when the gap with its own view reaches three notches, so you should expect challenges to be rare and targeted.
The threshold Removal from filing-exempt treatment generally requires at least a three-notch gap between the private rating and the SVO Credit Committee’s own view, followed by review. State regulators make the final call.
| Issue | Whalen’s framing | Documented NAIC position |
|---|---|---|
| Authority | A trade body, not a regulator | SVO can challenge; states decide; NAIC cannot override ratings alone |
| Threshold | Scrutiny watered down | Three-notch gap generally required |
| Status | Backed off after pushback | Effective 1 January 2026; enhanced reporting from 2026 |
Research found no web-reported evidence of industry lawsuit threats and no formal reversal. It did find friction: required systems and information-sharing agreements were not yet operational in December 2025. The NAIC’s letter to Senator Elizabeth Warren, updated on 30 October 2026, describes continued oversight.
Two readings remain possible. One sees a compromise shaped by resistance; the other sees modernisation. The evidence supports modernisation as the more defensible description, though the delays and the high threshold blunt the reform.
There is also a confidentiality trade-off. Supervisors may see more, but you, the public, may not. A power on paper is not the same as a power used, so the safeguard’s real strength will only show when a contested rating is actually challenged.
Why does one commentator expect a federal insurance regulator?
Whalen goes further than criticising the NAIC. He argues state supervision is too fragmented for a national, interconnected system, and that problems will not be fixed until an insurer fails. Treat that as one structural question, not a settled forecast.
The system in question is big. The Federal Reserve’s May 2026 Financial Stability Report put U.S. private-credit loans at about $1.4 trillion, roughly 10% of nonfinancial corporate debt and about one-third of below-investment-grade debt excluding bank loans. Barclays analysis, reported in May 2026, found private-credit assets at U.S. life insurers grew more than 20% in 2025 to about 10% of assets, and above 15% at PE-affiliated insurers such as Athene and Global Atlantic.
The case for a national regulator
- Large insurers and asset managers operate nationally, while supervision is state-based.
- Private-credit risk crosses insurance, banking, securities and derivatives markets.
- States may compete to attract insurers to their domicile.
- A federal body could standardise capital rules, data and enforcement.
- Monitoring links between banks, insurers and reinsurers would be easier.
The case for keeping states in charge
- Insurance liabilities and claims are largely local and state-specific.
- State regulators have specialised expertise.
- State guaranty associations, funded by insurers, already provide a policyholder backstop.
- A single federal regulator could become a single point of failure.
- The current system can be strengthened through NAIC coordination, better data and stronger SVO powers.
Fed research establishes that these sectors are interconnected, with banks still key lenders to nonbanks. It does not establish that a federal regulator is necessary. Whichever model prevails decides who stands behind your policy and how quickly trouble is spotted, so watch the debate rather than bank on an outcome. These views are speculative and subject to change as policy develops.
The interconnection is not only a U.S. story: the ECB has mapped about €425 billion of private credit exposure across European institutions, warning that second-round losses could exceed the direct hits in a severe shock.
How could a Baltimore rental-loan fraud move losses through insurers and banks?
The abstract risk becomes easier to see in one concrete case.
What the Baltimore case alleges
According to the Baltimore Banner in March 2026, New York-area investors acquired roughly 700 Baltimore homes using debt service coverage ratio (DSCR) loans. A DSCR loan qualifies a borrower on the property’s expected rental income rather than on pay stubs or personal income. Financing reportedly included more than $100 million in private credit and roughly $100 million in DSCR debt, and federal investigators were examining the deals as of March 2026.
Properties were allegedly transferred among related entities or refinanced at inflated values. Civil claims allege more than $24 million in losses, with AmeriTrust alleging about $14.1 million across more than 90 loans, per reports on 16 September and 20 October 2026. These cases are civil and unadjudicated.
No loan-by-loan list tying these loans to named life insurers or warehouse banks has been found. Whalen’s claim that life insurers bought them is his view; reported links are to the broader private-credit ecosystem.
How warehouse lines connect lenders to banks
A warehouse line is a short-term bank credit facility that lets a lender fund loans before selling or securitising them. A Federal Reserve note from 23 May 2025 expected banks to raise private-credit exposure this way, and the Richmond Fed described in August 2025 how nonbank mortgage firms rely on these lines.
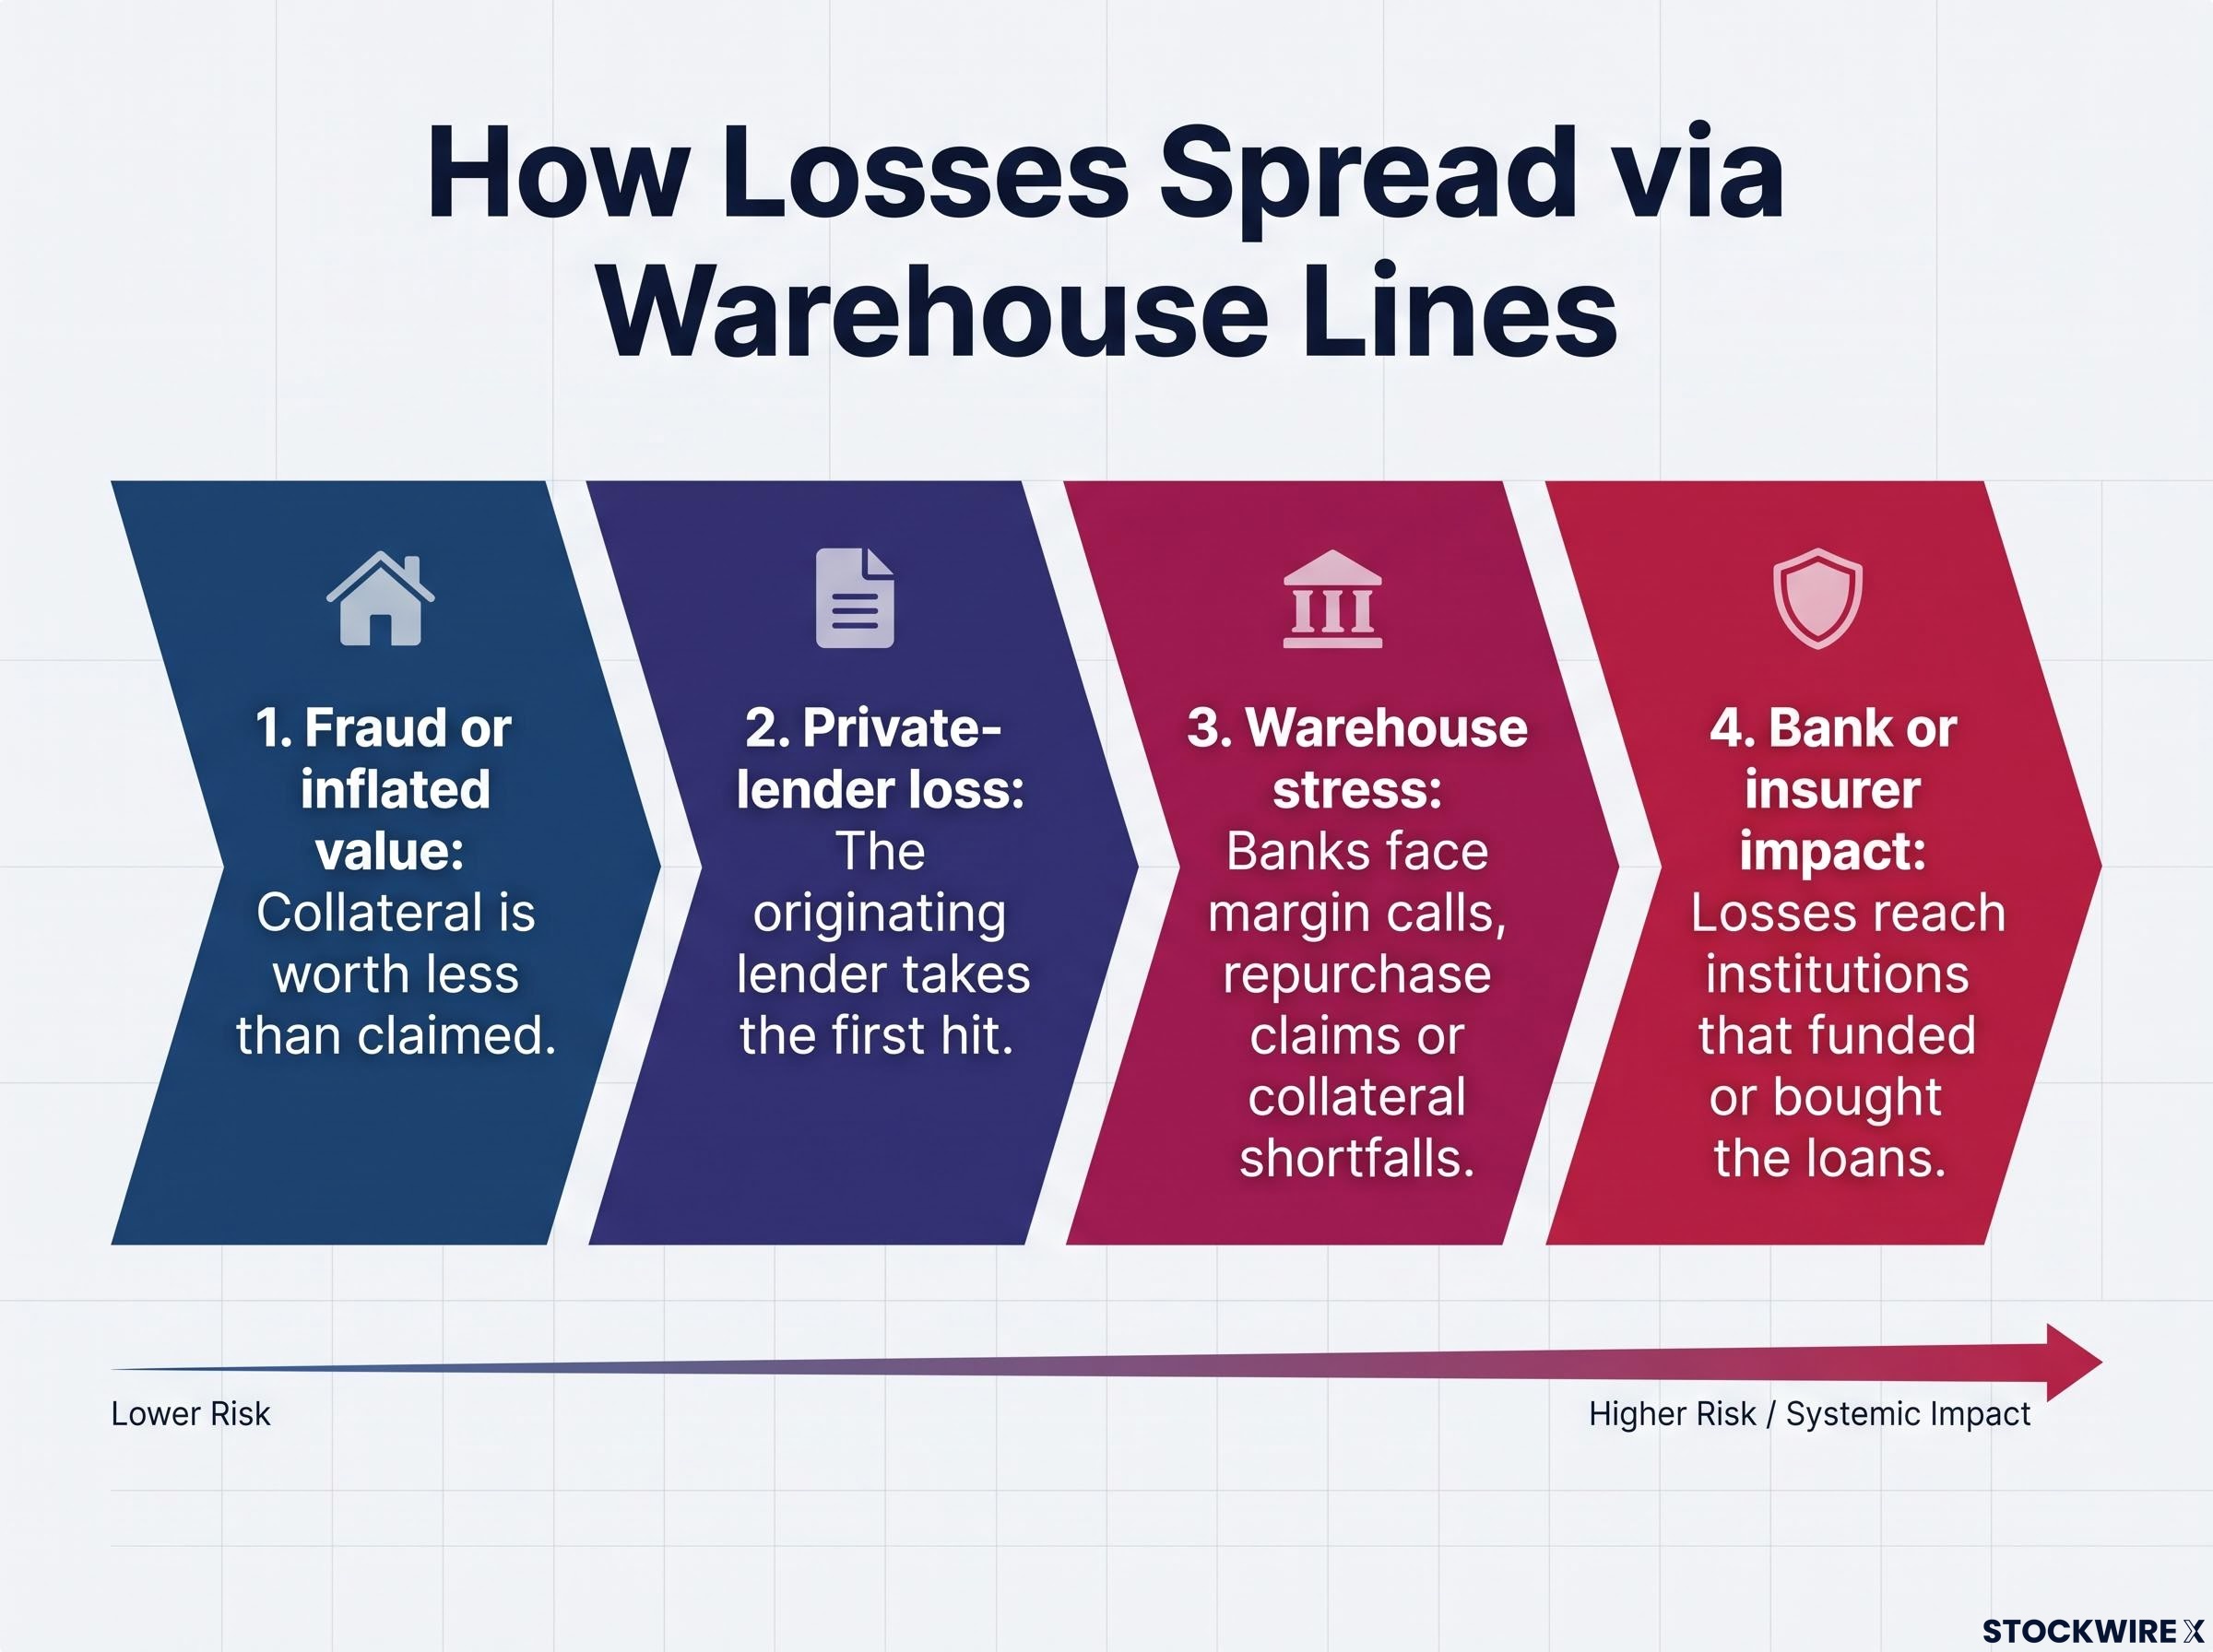
- Fraud or inflated value: Collateral is worth less than claimed.
- Private-lender loss: The originating lender takes the first hit.
- Warehouse stress: Banks face margin calls, repurchase claims or collateral shortfalls.
- Bank or insurer impact: Losses reach institutions that funded or bought the loans.
What precedents do and do not show
| Case | How losses spread | Caveat |
|---|---|---|
| Baltimore DSCR loans | Alleged inflated values hit private lenders | Unadjudicated; insurer exposure unproven |
| Tricolor, 2025 | Alleged double-pledged collateral; JPMorgan about $170M | Nonbank auto lender, not an insurer |
| First Brands, 2025 | UBS over $500M; Jefferies about $715M questionable receivables | Corporate case; no proven material insurer losses |
| Executive Life, early 1990s | Guaranty association assessments on other insurers | Older, imperfect analogue |
| AIG, 2008 | Collateral calls across counterparties | Derivatives-driven, not private ratings |
There are counterweights. Insurers hold reserves against long-dated liabilities, bank exposures may be collateralised and diversified, and a credit loss is not automatically insolvency. Still, the pattern shows losses in loosely verified lending can reach institutions you never dealt with directly, which is why collateral quality and double-pledging risk matter more than headline ratings.
What to watch as oversight and the evidence develop
The evidence supports a real but conditional channel: a generous private rating lowers capital, expands room for private assets and could leave an insurer undercapitalised if the rating proves wrong. Bank warehouse lines form a second, separate path. Neither amounts to proof of insolvency.
Three signals will tell you more than any commentator’s forecast:
- First public SVO challenges under the 2026 process, showing whether the power gets used.
- Resolution of the Baltimore matters, both civil and federal.
- Movement on federal insurance proposals in Congress.
Weight primary sources such as NAIC filings, court records and Fed reports above confident predictions in either direction.
For readers weighing where annuities fit against other safe holdings, our dedicated guide to fixed income alternatives compares after-tax real returns across Treasury bills, bank deposits and annuities.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.