A currency preview on Fed day usually starts and ends with the Fed. This one starts in Seoul, where a record chip-memory earnings report has helped reset the US dollar’s backdrop hours before the Federal Open Market Committee (FOMC) decision.
ING‘s Chris Turner argues that easing stress in the artificial intelligence (AI) sector has freed currency markets to look again at resilient US growth, high inflation, rising energy costs and the Fed’s response. The US Dollar Index (DXY), which measures the dollar against a basket of six major currencies, sits near 102.36 and is pressing back toward its 2026 highs. The FOMC decision lands today, 28 October 2026.
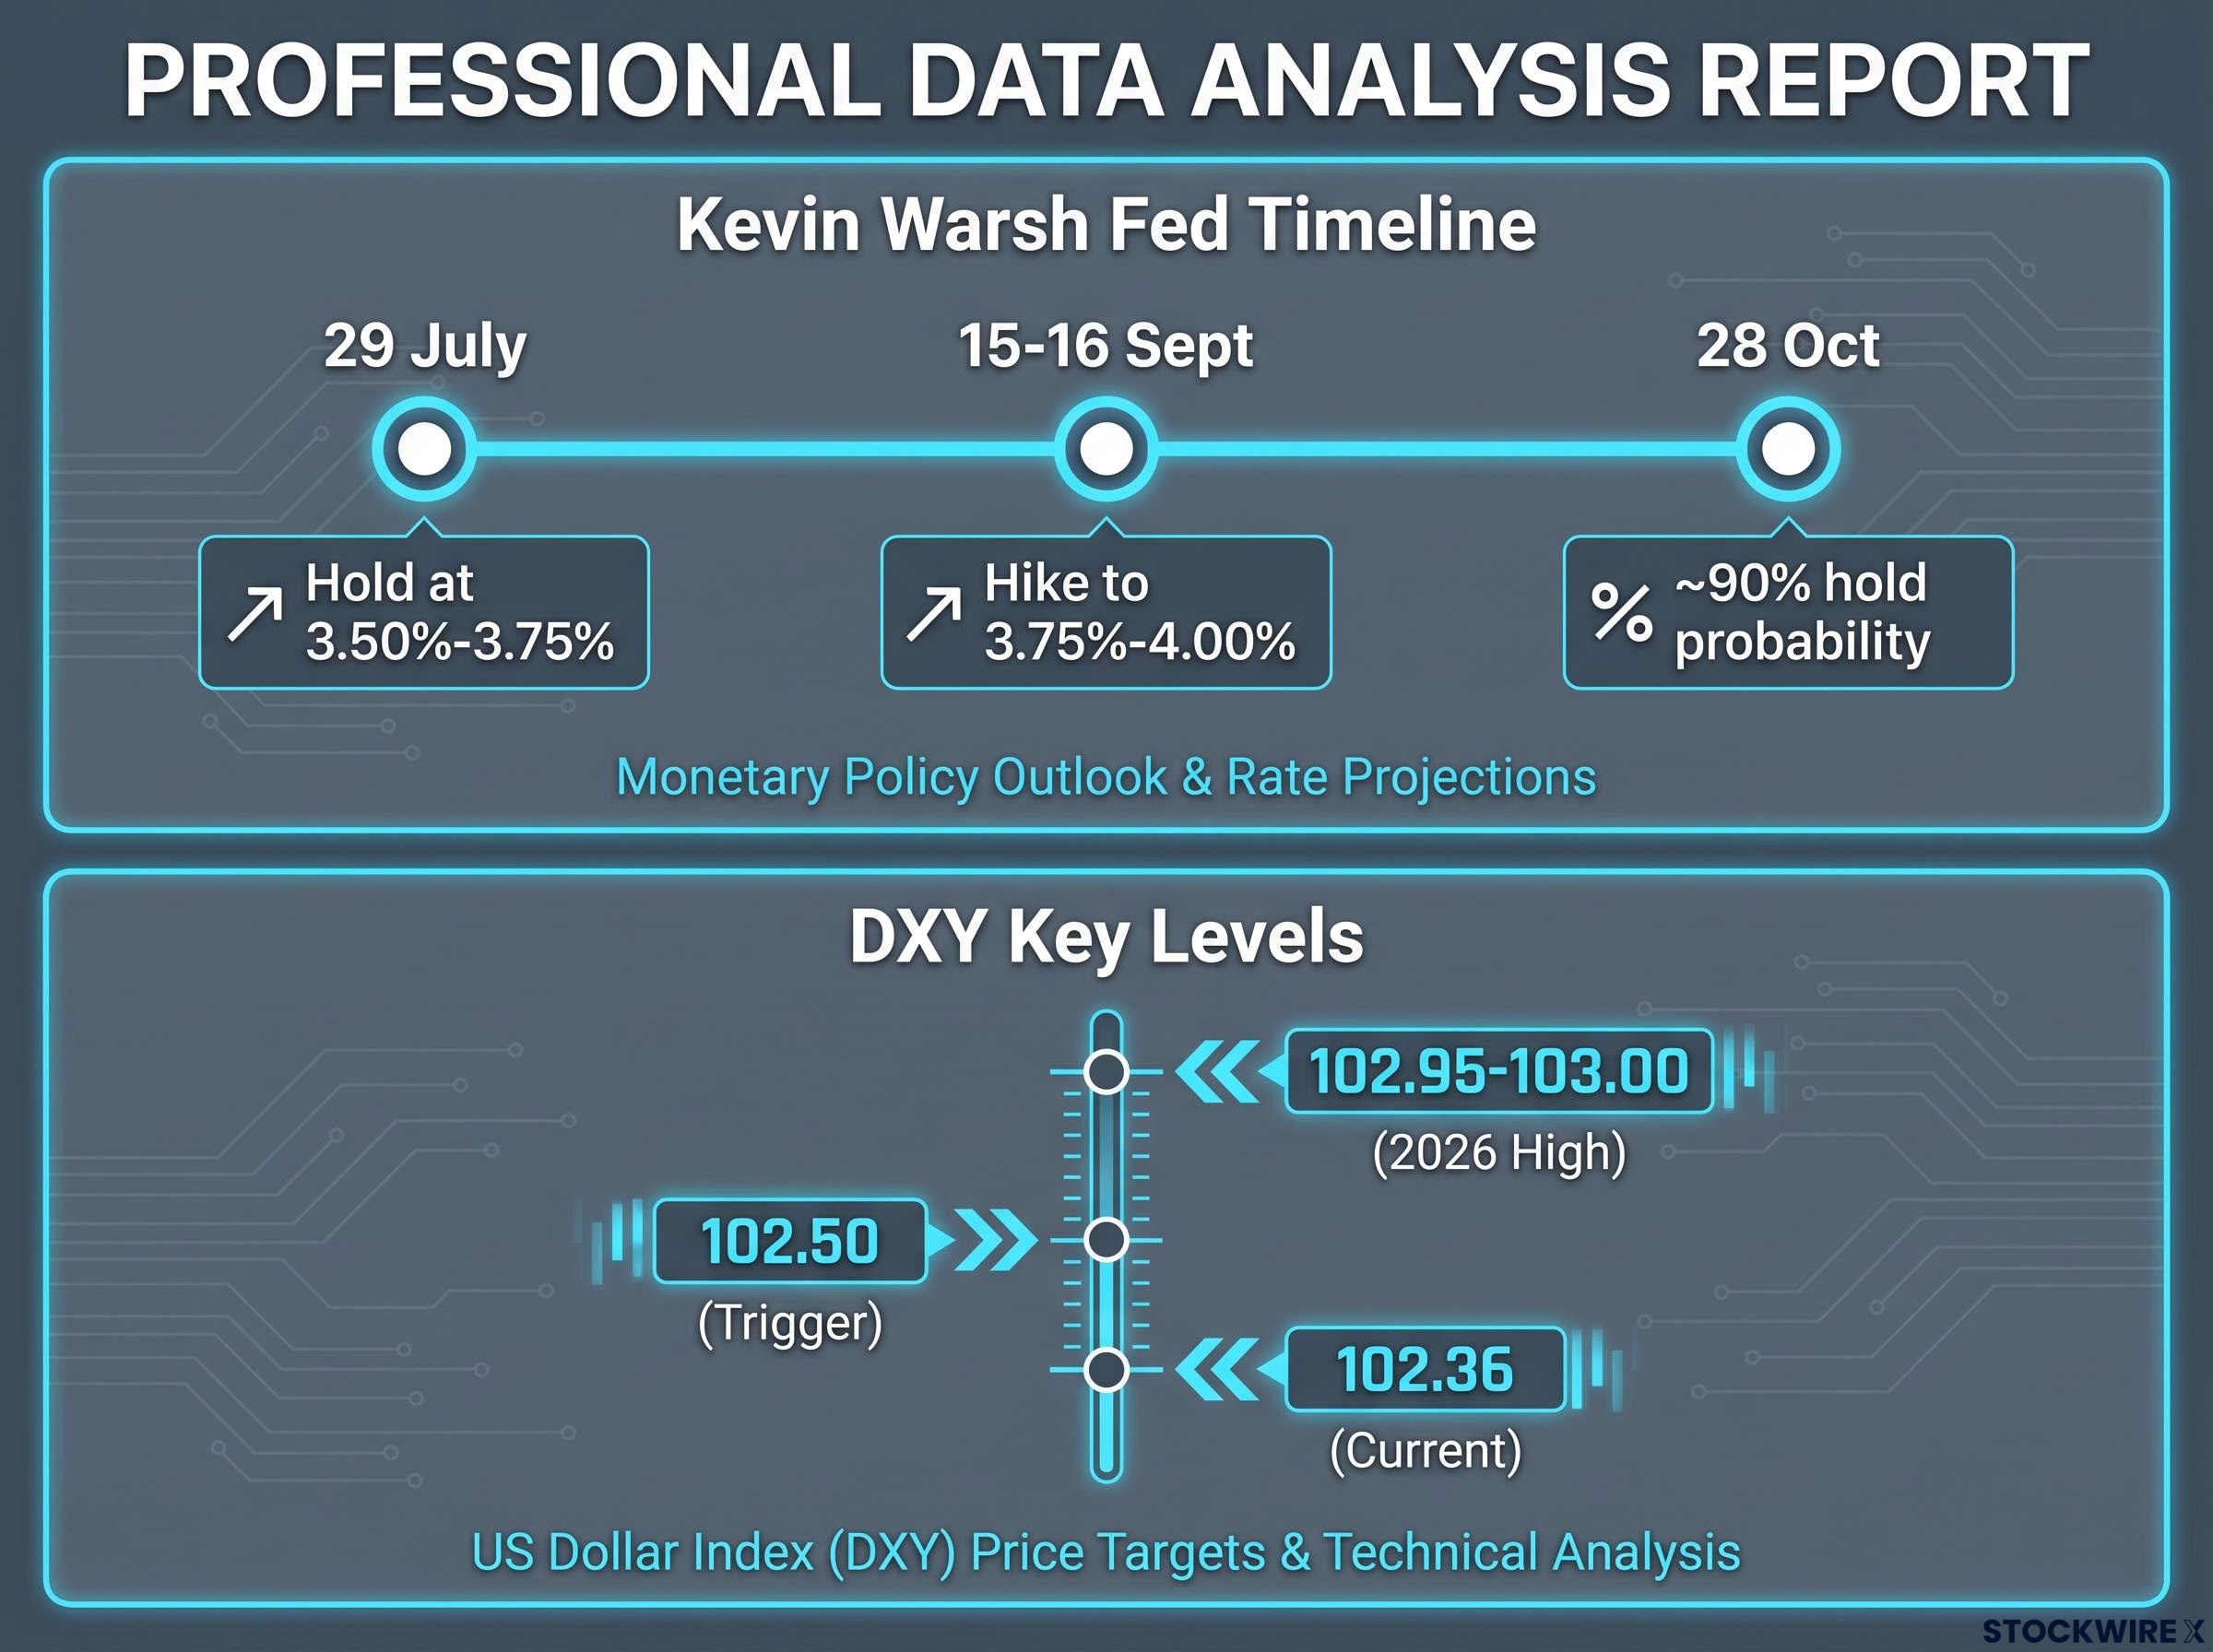
Here is the framework for reading how equity risk sentiment feeds currency direction around a central bank meeting. You will also see the two DXY levels that matter, 102.50 and 103.00, and the communication risks that decide whether they hold.
Why did calmer AI sentiment hand the dollar back to the Fed?
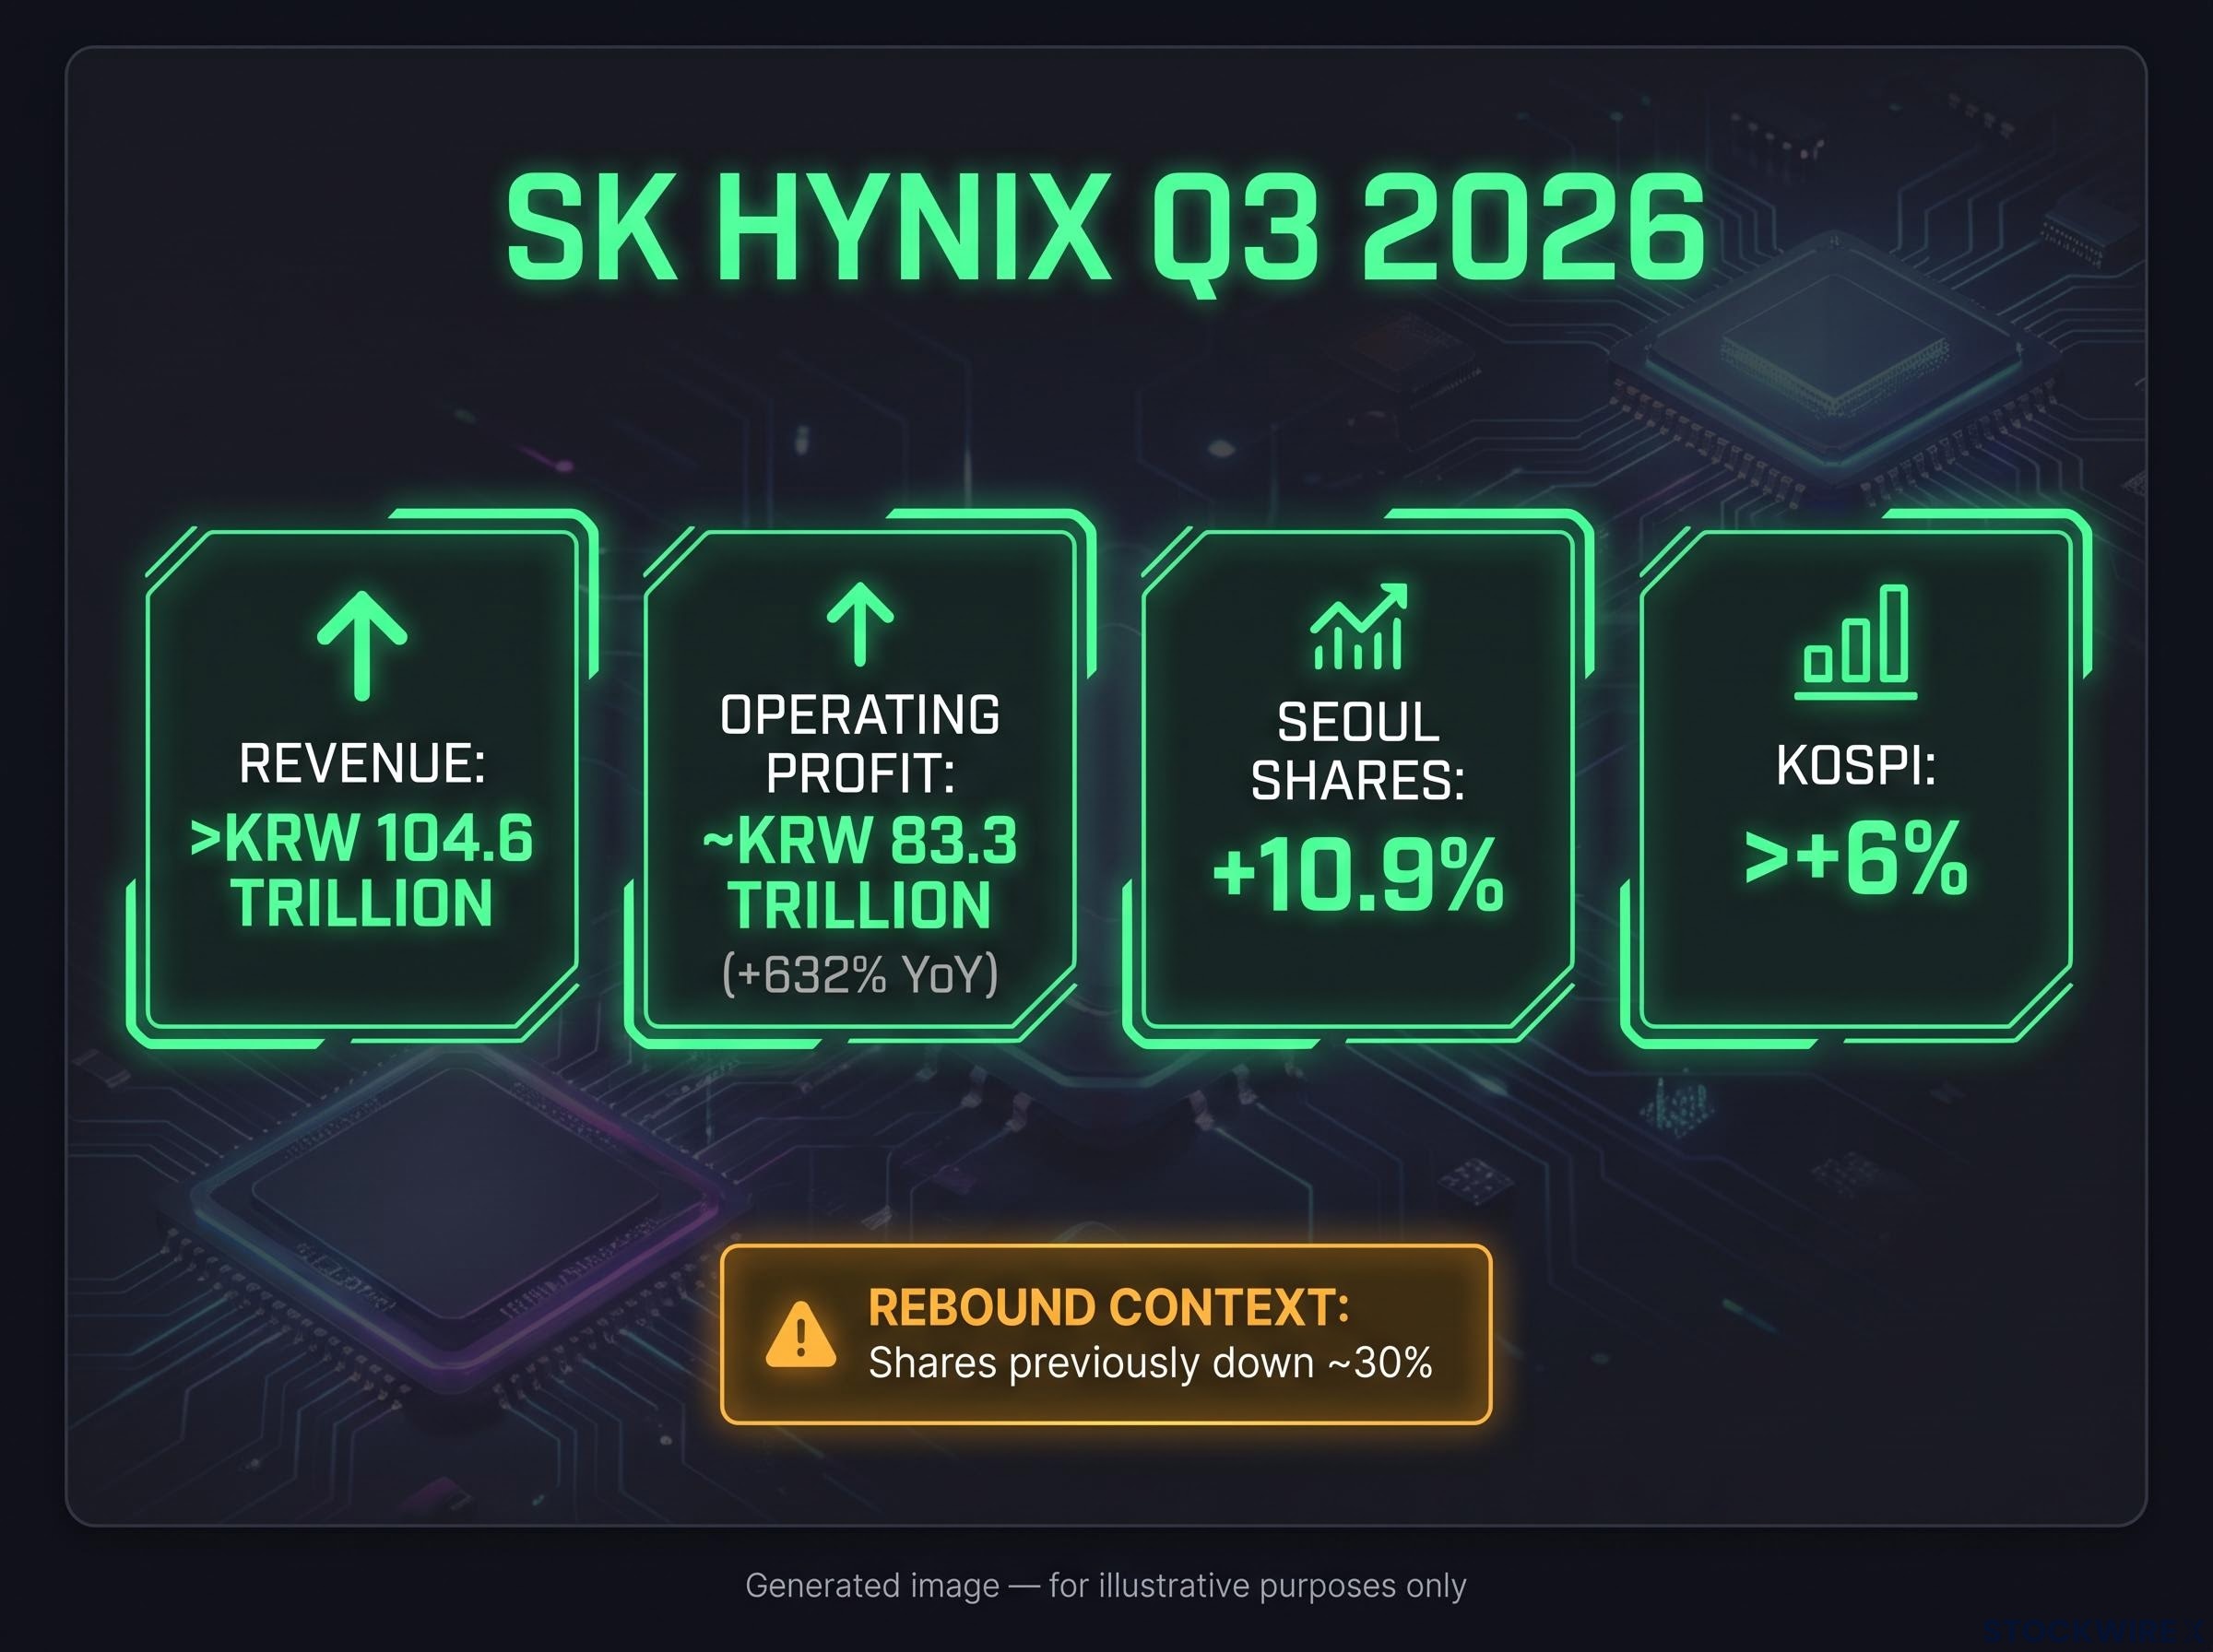
SK Hynix reported record third-quarter results on 28 October 2026, and Seoul reacted fast. The numbers were large enough to shift sentiment well beyond Korea:
- Q3 2026 revenue above KRW 104.6 trillion
- Operating profit of about KRW 83.3 trillion, up roughly 632% year-on-year
- Shares up 10.9% in Seoul, with the Kospi rising more than 6%
- US ADRs up 1.92% in regular trading and about 5.8%-6.1% after hours
Context makes the rally sharper. Investors had earlier pushed Samsung and SK Hynix shares down roughly 30% on fears that AI spending and memory prices could soften.
A blowout result from the world’s leading AI-memory supplier undercut that fear directly. It also eased a second worry, flagged by Turner: that higher borrowing costs were damaging business models, particularly for high-yield issuers. As the biggest AI names keep delivering, that concern is fading.
The memory supply shortage underpinning SK Hynix’s result is also the reason AI spending looks durable to many analysts, with demand expected to exceed supply through 2027 and 2028 and new fab capacity arriving late.
ING’s read With AI-sector stress easing, Turner argues currency markets can turn back to Fed policy, energy prices and inflation, a mix he sees as supportive for the dollar.
What the AI sell-off had already done to hike pricing
ING estimates the dollar gained about 4% from September to early October. It then stalled, and the tech sell-off was part of the reason: falling equities trimmed expectations that the Fed would keep tightening.
Stabilisation removes that drag. What this tells you is that the AI scare had been quietly working against the dollar through Fed pricing, so its fading matters for your currency exposure even if you never touch a chip stock. Before any Fed meeting, Asian equity headlines are worth checking alongside the rates calendar.
When big ASX news breaks, our subscribers know first
How does equity risk sentiment actually move a currency?
The common intuition is simple: stocks fall, investors get nervous, the dollar rises. Sometimes that holds. Often it does not, because an equity shock travels through several channels at once, and they can pull the dollar in opposite directions.
The 2026 AI episode shows all four at work.
| Channel | Mechanism | Typical dollar effect | 2026 example |
|---|---|---|---|
| Risk appetite and safe haven | Sharp sell-offs push investors toward the dollar for safety | Supportive during panic | A steep AI-equity sell-off can lift demand for dollars; calm shifts focus back to rate gaps |
| Rate expectations | Weaker growth outlook lowers expected Fed hikes and yields | Negative | ING says the recent sell-off already pared tightening expectations |
| Credit and financial conditions | Falling tech stocks can widen high-yield spreads, tightening conditions | Negative if the Fed treats this as a substitute for hikes | Borrowing-cost worries for high-yield issuers |
| Capital flows | Investment in chips, data centres and cloud draws money across borders | Supportive when AI investment looks durable | Strong SK Hynix results reinforce confidence in AI spending |
Two terms need a plain definition. A rate differential is the gap between interest rates in two countries, and a wider gap in favour of the US tends to attract money into dollars. A high-yield spread is the extra interest that riskier companies pay to borrow compared with the government.
The key point is that the rate channel can override the safe-haven channel. If a sell-off threatens US growth and widens spreads, markets price fewer hikes, and that can outweigh any rush for safety.
Whenever equities wobble before a Fed meeting, ask which channel is likely to dominate. Your answer tells you more about the dollar’s direction than the size of the stock move.
What could Warsh say today, and why does the wording matter more than the decision?
The decision itself carries little suspense. Reuters reported on 26 October that futures implied about a 90% probability of no change, leaving the target range at 3.75%-4.00% after September’s 25 basis point hike.
That makes the language the swing factor. The 2026 record shows how much Fed Chair Kevin Warsh’s tone has mattered.
The September meeting showed the same pattern: with the hike nearly fully priced, DXY direction depended on Warsh’s forward guidance on later meetings rather than the rate move itself, a dynamic that repeats ahead of today’s decision.
| Episode | Communication | Market consequence |
|---|---|---|
| June | Characterised by ING as hawkish | Set a multi-week dollar trend |
| 29 July | 9-3 vote to hold at 3.50%-3.75%; remarks read as bond yields doing part of the Fed’s tightening | Lower near-term hike expectations, higher long-term yields, weaker dollar and stocks |
| 15-16 September | Hike to 3.75%-4.00%, with further tightening possibly needed | Hawkish read; dollar rallied about 4% into early October |
| After September CPI | Jefferson, Bowman and Waller signalled no rush | October hike odds fell from above 50%; hold became consensus |
That last row matters. September’s consumer price index (CPI) ran hot, with headline prices up 0.6% month-on-month and 3.7% year-on-year, and core up 0.3% and 2.6%. Yet comments from Vice Chairs Philip Jefferson and Michelle Bowman and Governor Chris Waller were enough to shift the market toward a pause.
Guidance sets the trend ING observes that each Warsh-led meeting has set the dollar’s direction for the following four to six weeks.
ING expects Warsh to stress monetary stability and credibility. Franklin Templeton is more cautious, warning on 16 October that he may again sound non-committal.
Two scenarios for today’s press conference
A credibility-first message would support pricing for a December hike and, with it, the dollar. A repeat of July’s argument that tighter financial conditions are doing the Fed’s work would risk removing December pricing and weakening the dollar.
What this tells you is that a hold is neither bullish nor bearish by itself. Watch the press conference framing, not just the headline decision.
Where do 102.50 and 103.00 sit, and what could stop DXY?
DXY closed at 102.3644 on 27 October, according to Trading Economics. Its 2026 high was about 102.95 on 14 October, with some coverage placing it near 102.96-103.00.
| Level or risk | What it represents | What would trigger it |
|---|---|---|
| 102.36 | Current position | Pre-meeting consolidation |
| 102.50 | Immediate upside trigger | Credibility-first message from Warsh |
| 102.95-103.00 | 2026 high and round-number resistance | Sustained December-hike pricing |
| Failure in the zone | Profit-taking after repeated rejections | A pause without reinforced December guidance |
ING’s base case is a pause, continued dollar support and a possible December hike. Interestingly, its main correction catalyst is a renewed tech-led risk-off move, not a dovish Fed.
DXY has tested the 102.50-103.00 area several times without breaking through. A failure near 103.00 would not be a surprise, and a break above 102.50 is best read as a conditional signal tied to what Warsh says, not a forecast in its own right.
Event-driven DXY levels have mattered before: ahead of Jackson Hole in August, the index broke below 98.80 and prior supports flipped to resistance, showing how quickly Fed tone can reshape a chart ahead of a catalyst.
The risks that could cap the rally
- Communication risk: a dovish or non-committal Warsh repeating July’s financial-conditions argument
- AI re-rating: another sell-off that hurts growth, widens spreads and cuts hike pricing
- Energy and growth: high energy prices support the dollar through inflation but may damage growth over time
- Data weakness: ING acknowledges softer jobs figures and stress in housing
- Fiscal credibility: deficits lift long-term yields, but deterioration poses a longer-term valuation problem
Inflation alone does not settle the question either. A hot CPI print still produced roughly 90% hold odds. No attributable October 2026 views from MUFG, Goldman Sachs or Morgan Stanley were found, so the bullish call rests largely on ING’s reading.
These statements are speculative and subject to change based on market developments.
What today’s FOMC changes for the dollar, and what it does not
Calmer AI sentiment has returned the dollar to a rate-differential story, but Warsh’s tone decides whether 102.50 and 103.00 come into reach. If he reaffirms credibility, the near-term bias leans constructive; a communication-driven shift toward a December pause is the clearest downside.
After the meeting, watch three things: how Warsh frames financial conditions, whether AI equities hold their rebound, and where energy prices settle. Together they will tell you whether the next four to six weeks favour the dollar. This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.