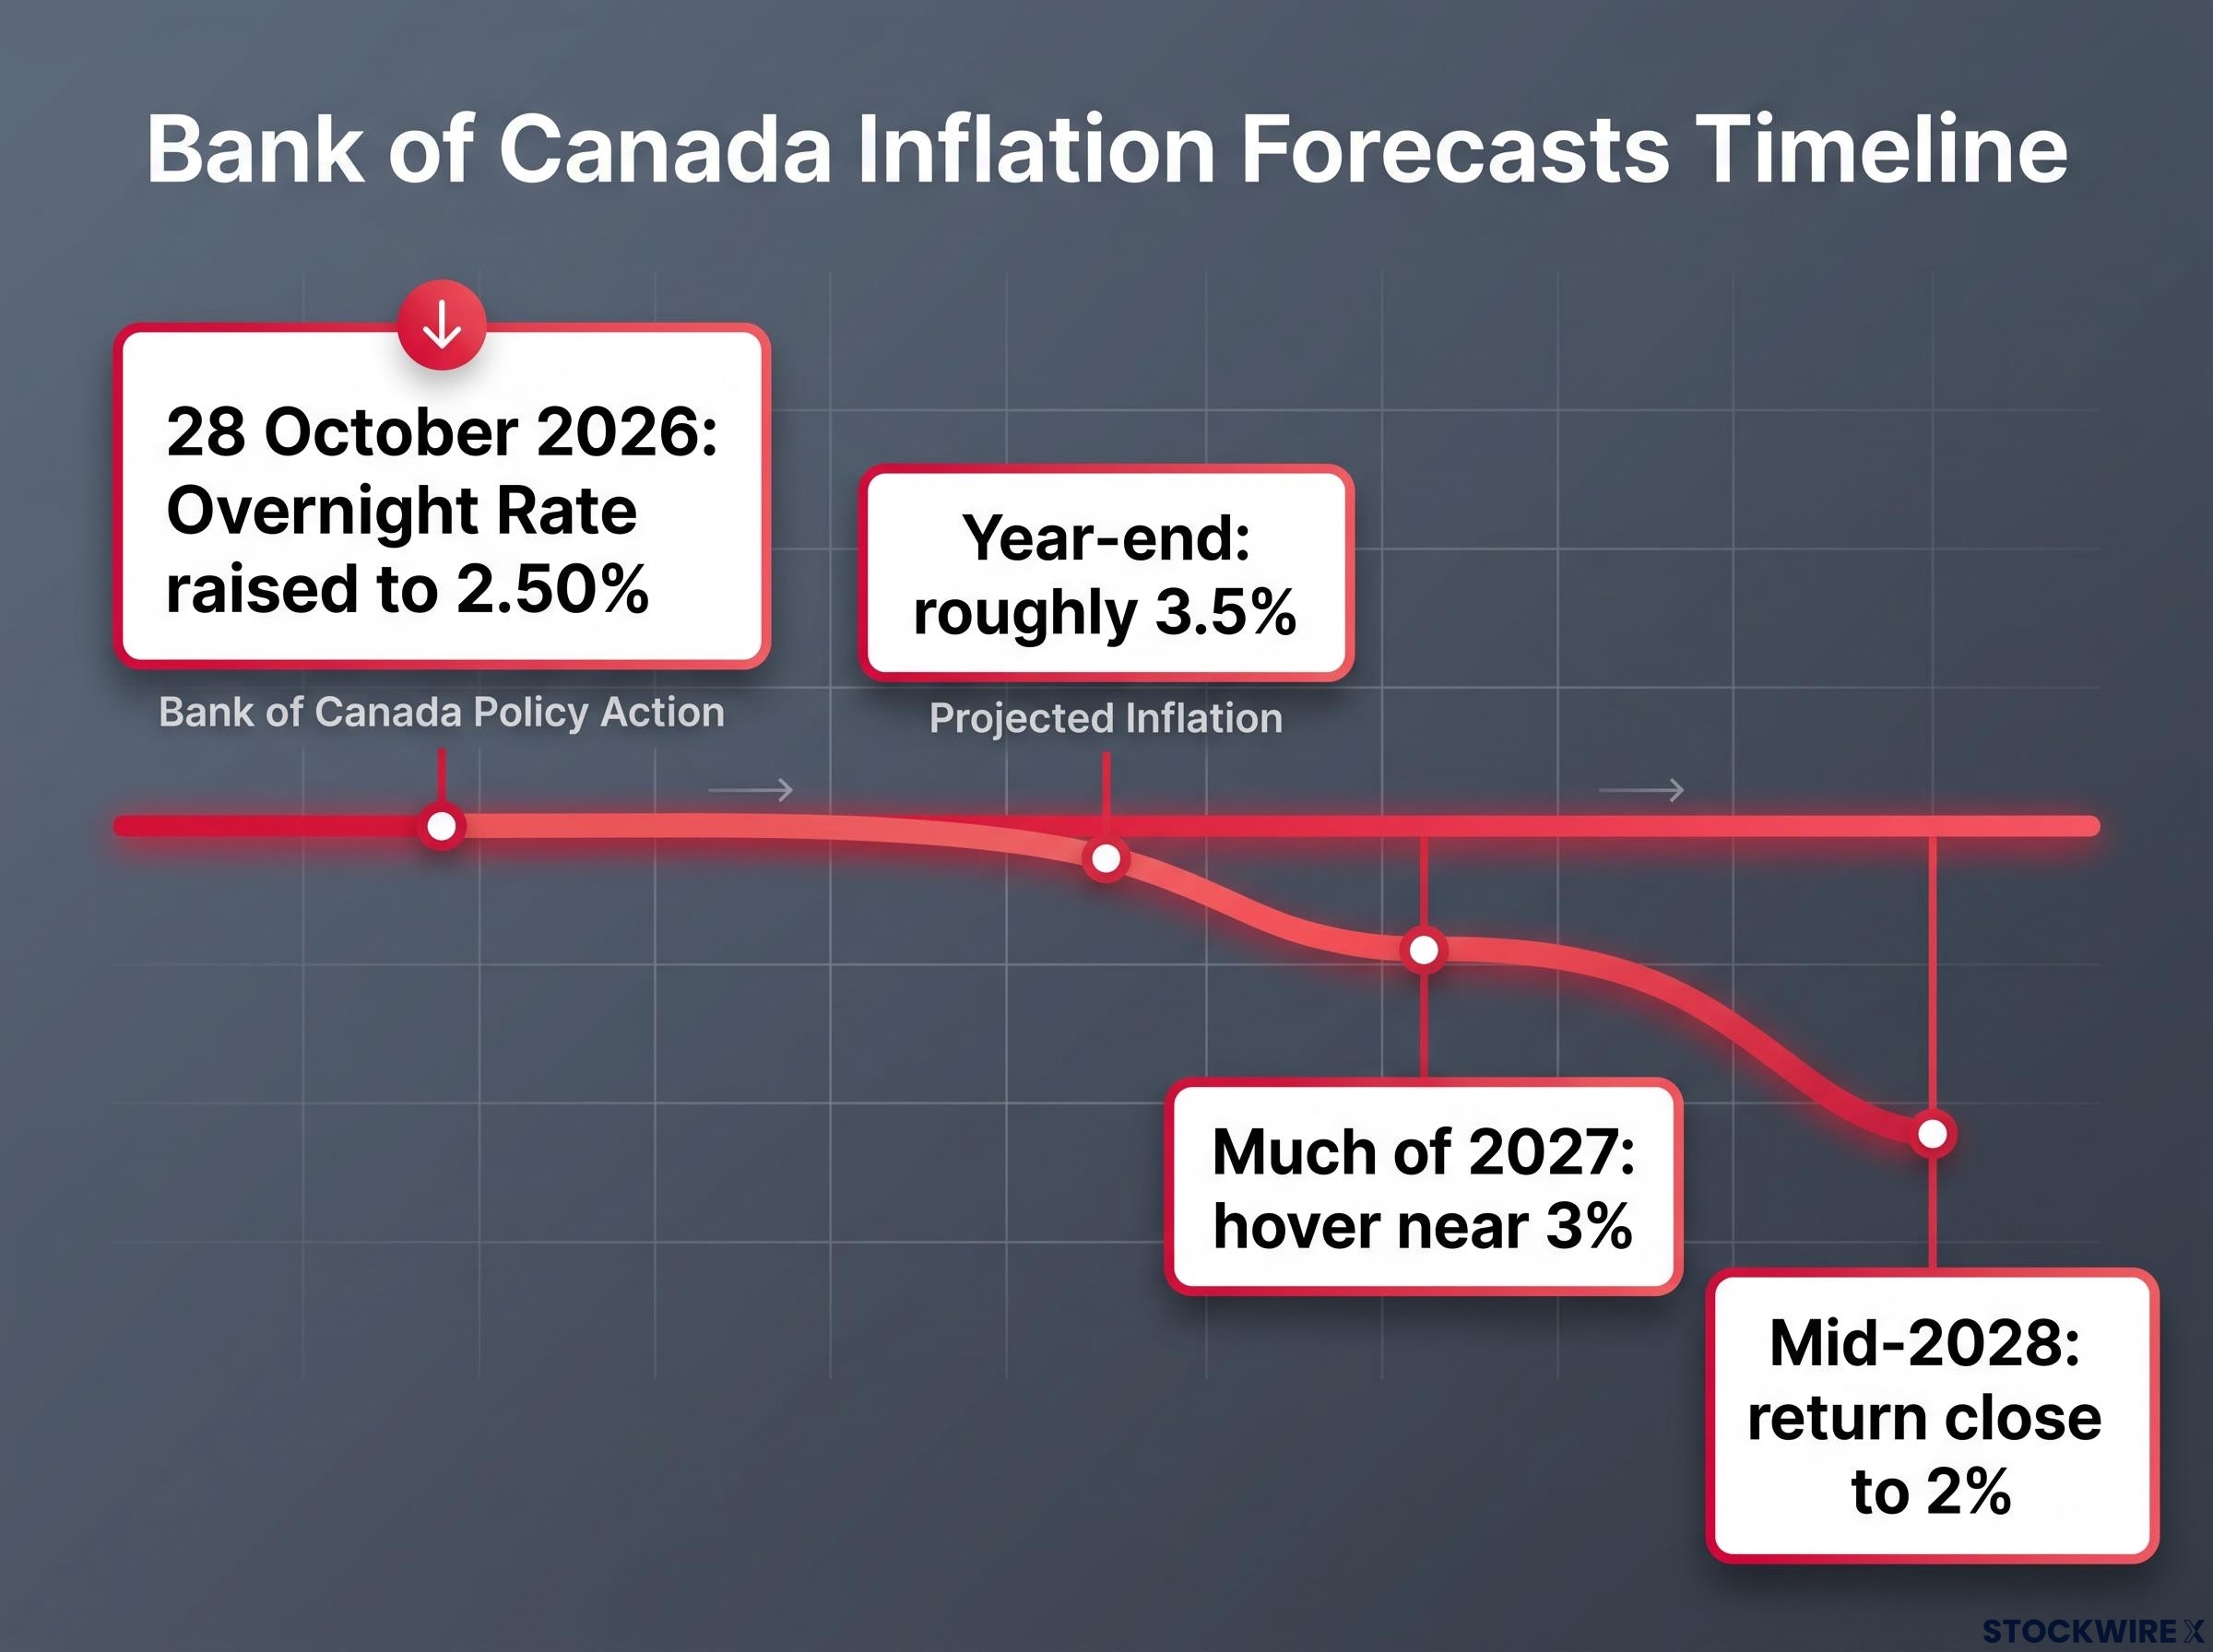
The Bank of Canada raised its overnight rate by 25 basis points to 2.50% on Wednesday, 28 October 2026. It is the central bank’s first increase since July 2023, and it comes while core inflation is still running below 2%.
Headline inflation sits at 3.1%, but energy is doing almost all of the work. The Bank is tightening ahead of evidence that higher prices are spreading, not in response to it.
That distinction matters for anyone with a variable-rate mortgage, a line of credit or exposure to the Canadian dollar. A pre-emptive hike can be followed by more, or it can be a one-off insurance policy.
Here is why the Bank moved now, why the loonie barely flinched, and which signals would point toward a second Bank of Canada rate hike.
Why did the Bank hike when core inflation is still below 2%?
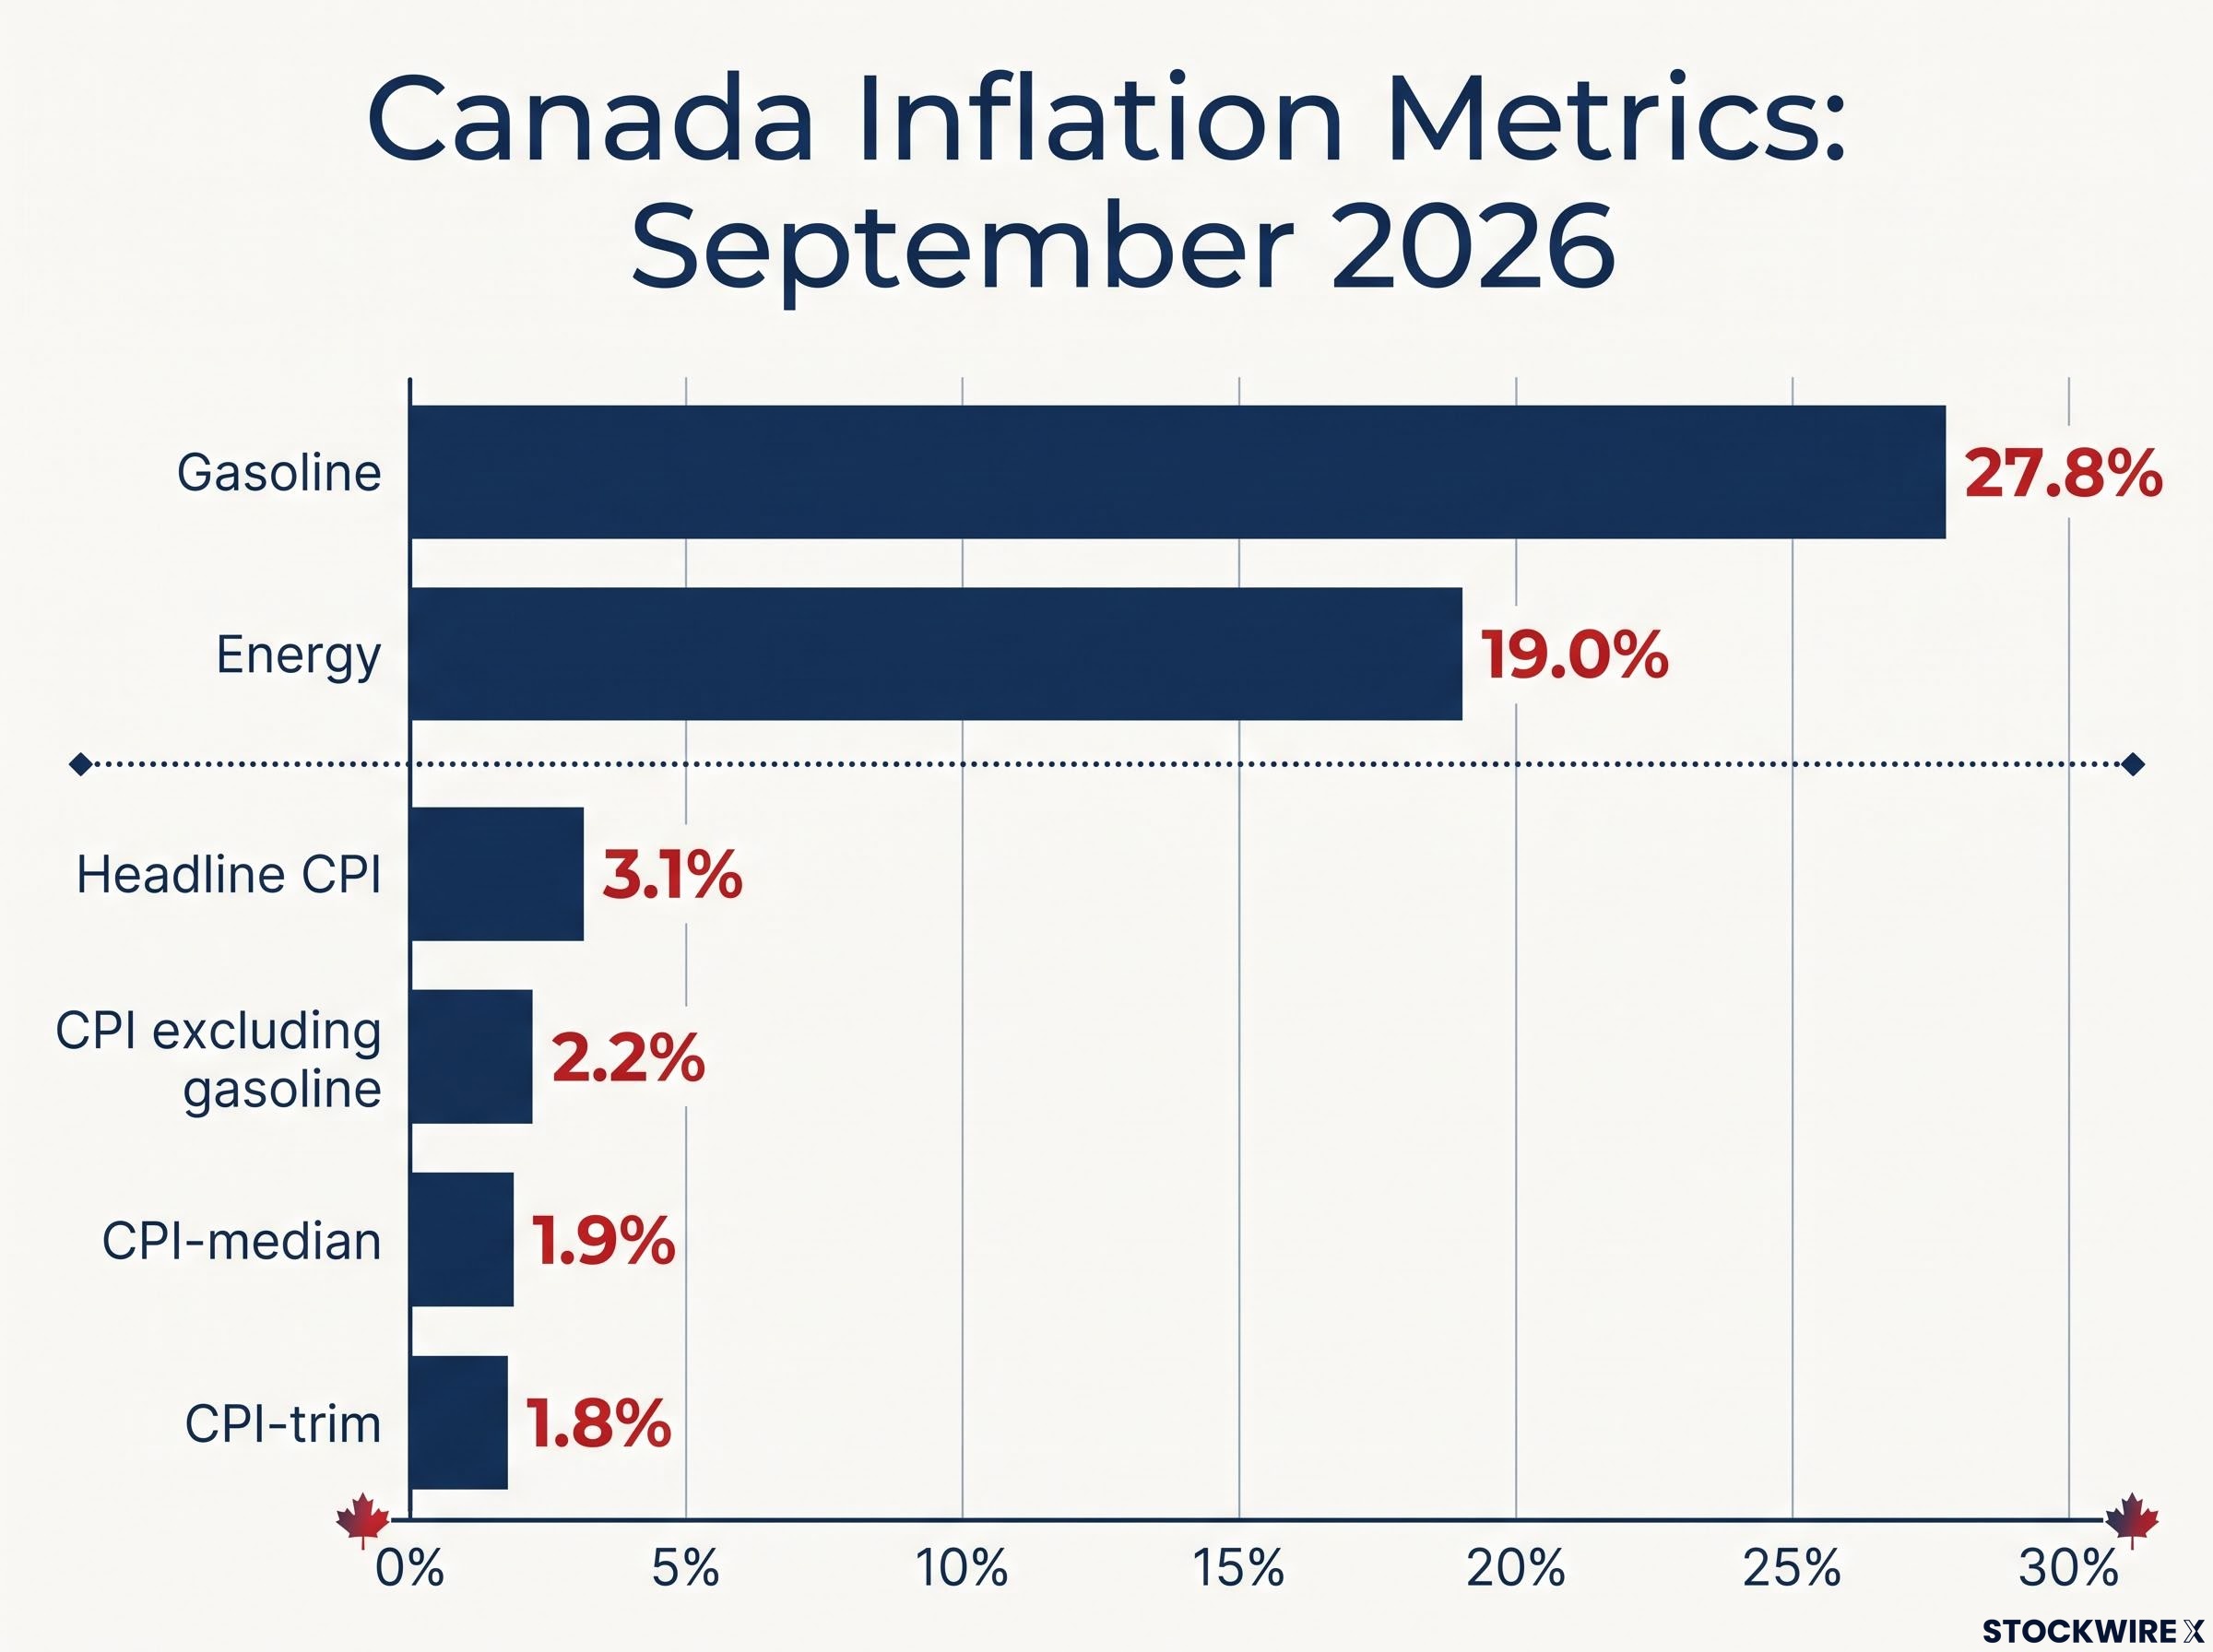
On the surface, the numbers argue against each other. Statistics Canada put September headline inflation at 3.1%, up from 3.0% in August. The Bank’s preferred core gauges were lower, with CPI-trim at 1.8% and CPI-median at 1.9%.
CPI-trim and CPI-median are core inflation measures. They strip out the most extreme price moves each month to show the underlying trend.
| Measure | Latest figure | Date |
|---|---|---|
| Headline CPI (y/y) | 3.1% | September 2026 |
| CPI-trim | 1.8% | September 2026 |
| CPI-median | 1.9% | September 2026 |
| CPI excluding gasoline | 2.2% | September 2026 |
| Gasoline (y/y) | 27.8% | September 2026 |
| Energy (y/y) | 19.0% (August: 15.4%) | September 2026 |
The gap resolves once you separate first-round from second-round effects. First-round effects are the direct price jumps in gasoline, diesel and heating oil. Second-round effects come later, when firms raise unrelated prices and workers push for higher wages to compensate.
The September CPI gap between headline and core readings had been flagged beforehand as energy-led rather than broad-based, with weakening employment also limiting the Bank’s appetite to respond to the fuel price shock.
The Bank is betting on stopping the second round before it starts. Governor Tiff Macklem said the move aims to keep persistently high energy costs from spreading into other goods and services, with the Bank Rate now 2.75% and the deposit rate 2.45%.
Governor Tiff Macklem “There could be a need to increase the policy rate further, but given uncertainties, we will proceed carefully.”
The Bank expects inflation to reach roughly 3.5% by year-end, hover near 3% through much of 2027, and return close to 2% by mid-2028. The core gap tells you the Bank is acting on risk rather than damage already done. That makes this a judgment call, and it could age well or badly.
When big ASX news breaks, our subscribers know first
What the Bank’s own surveys said about pass-through and expectations
The Bank did not make that call on energy prices alone. Its own surveys showed businesses and households growing less comfortable.
What the surveys showed
The Q3 Business Outlook Survey and Survey of Consumer Expectations pointed in the same direction:
- Firms have mostly absorbed higher input costs so far, but plan to pass more on over the next 12 months
- Roughly half of firms intend to pass some or all cost increases to customers, according to RBC Economics
- One-year business inflation expectations rose to 3.7%, with two-year expectations at 3.1%
- Consumers’ long-term expectations have climbed to match their short-term ones, with energy and Canada-US trade tensions cited as drivers
That last point carries the most weight. When long-term expectations drift up, the Bank’s 2% target starts to lose its grip on how people set prices and wages.
Where economists disagreed
Not everyone accepted the logic. CIBC chief economist Avery Shenfeld argued that waiting until December or January would allow more time to assess energy and trade, and he called an immediate hike a potential policy error.
| Institution | Position | Core reasoning |
|---|---|---|
| Bank of Canada | Hike now | Second-round risks rising as energy stays high |
| CIBC | Wait | Core inflation does not yet require tightening |
| RBC Economics | Expected hike, saw strong case for patience | Weak housing, near-target core, slowing growth |
| Capital Economics | Backed hike | Rising long-term expectations |
A Reuters poll majority sided with the Bank, warning that delay could embed energy inflation in wages and expectations. The wait camp pointed to weak housing, slowing GDP and mortgage renewal pressure that has eased but not disappeared.
The disagreement reflected a wider divide in which traders and economists split over whether soft core readings or rising business expectations deserved more weight, with market pricing running well ahead of most published forecasts.
If you carry a variable-rate mortgage or line of credit, that split matters. The hike was contested, so further increases are not a foregone conclusion.
Why the Canadian dollar barely moved, and how BoC tools usually affect it
For a policy shift of this size, the currency response was almost silent. TradingKey reported USD/CAD little changed during US trading hours.
Why the market shrugged
Markets saw this coming. A Reuters poll found 19 of 34 economists expected the hike, and Bloomberg-derived pricing put the implied probability at 87%, up from 70% earlier in the week.
Capital Economics said investors had priced roughly 100 basis points of further hikes by end-2027, a path it considers excessive. The loonie had already firmed slightly beforehand, largely on broad US dollar weakness.
The loonie’s muted reaction fits a broader pattern in which Canada-US rate differentials and expected policy paths, rather than the headline decision itself, drive the currency, with forward guidance usually mattering more than the move on the day.
How BoC tools typically move CAD
Three channels drive the Canadian dollar:
- Rate differentials. Higher Canadian rates support CAD when they widen the yield gap with the US or shift the expected policy path.
- Oil prices. Canada exports energy, so higher oil usually helps CAD, though this time oil is also the inflation problem.
- Trade risk. Tariffs and Canada-US uncertainty can drag on exports and investment, offsetting rate support.
The Bank’s balance-sheet tools work through similar channels:
- Quantitative easing (QE), where the Bank creates money to buy bonds, typically weakens CAD and was used in 2020-21
- Quantitative tightening (QT), which reverses QE by stopping purchases and reinvestment, is generally supportive
No quantified comparison of CAD moves in those episodes was found. The practical lesson is that a hike only moves the loonie when it changes the expected path, so watch guidance and the US-Canada yield gap rather than the decision itself.
What to watch before another Bank of Canada rate hike
The question now is whether this is a single hike or the start of a cycle. These indicators will decide it.
| Indicator | Current reading | Why it matters |
|---|---|---|
| CPI-trim / CPI-median | 1.8% / 1.9% | Sustained rises show inflation broadening |
| Business expectations | 3.7% one-year | Signals whether price-setting is shifting |
| Fuel and heating oil | Persistently high (no per-barrel figure available) | Duration drives pass-through |
| Wages, GDP, housing | Growth slowing, housing weak | Act as brakes on further hikes |
In order of importance, the triggers are:
- Core measures moving higher alongside non-energy price increases
- Further rises in long-term consumer and business expectations
- Energy prices staying elevated long enough to reach wages and services
Each faces a brake in housing weakness, mortgage renewals, slowing GDP and US trade uncertainty. CIBC expects the period after November’s US midterms to clarify energy and trade, and the Bank holds eight scheduled meetings a year, with December next. No post-decision probability for a December hike was available.
If core measures stay below 2% while energy eases, you can reasonably plan for a pause. If they climb toward 2.5% or higher, budget for higher borrowing costs.
Past performance does not guarantee future results. Forecasts cited here are subject to market conditions and may change.
What this hike settles, and what it leaves open
The Bank has made its choice: prevention over patience. Core inflation remains below 2%, and the flat currency reaction confirms the move was expected rather than a shock.
What stays unsettled is the path from here. Further tightening depends on whether energy inflation broadens into core and non-energy prices. Weak housing, mortgage renewals and US trade uncertainty all argue for restraint.
December’s meeting will be the first real test of whether this bet holds, and the core inflation prints before it will carry more weight than any headline number.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.