Railroads changed how nations traded. Electricity changed how people worked. The internet changed almost everything. Yet many people who invested in building all three lost money, which is the uncomfortable pattern behind today’s AI bubble debate.
By October, 2026 capital spending guidance from the largest cloud and platform companies (the “hyperscalers”) had reached roughly $720-745 billion, according to reported figures. Some estimates put it near $800 billion. Over the same period, free cash flow at several of these companies has weakened sharply or turned negative.
Kevin Muir, author of The Macro Tourist and co-host of Market Huddle, has become one of the clearest voices on this tension. He accepts that AI could change the world. His concern is that the broad agreement on this point is itself the risk.
This piece gives you a way to test AI valuations yourself, using three lenses: earnings quality, pricing, and share supply.
Why great technologies make poor investments
The intuition feels sound. If a technology reshapes the economy, owning the companies behind it should pay. History keeps disagreeing.
- Railroads: National markets opened and transport costs fell, but overbuilding, heavy fixed costs and price wars hurt many investors.
- Electricity: Productivity improved across the economy, but much of the value flowed to users and downstream industries rather than to every builder of generation capacity.
- Dot-com and telecom: The internet became foundational, yet the late 1990s funded excess fibre, servers and network capacity, and many companies failed.
The common thread is that technological success and investor success are separate outcomes. Adoption can exceed every forecast while the companies that paid for the build-out earn poor returns.
The Nasdaq 1997-2000 parallel holds on the charts, yet forward multiples near 25x against roughly 58x at the dot-com peak show the mechanics of any correction could differ sharply from the original collapse.
Michael Burry has reportedly drawn a sharper version of the dot-com lesson: share prices can peak before spending on the underlying technology does. In other words, the market can turn while the construction cranes are still working.
Muir’s core thesis The more firmly investors believe AI will change the world, the more capital pours into it, and the weaker the returns on that capital become.
The firms that tend to win in these cycles are the ones with pricing power, scarce intellectual property or control of distribution. Not every chip buyer or data centre builder qualifies.
That leaves you with two separate questions. Is AI important? And will the specific company you own get paid for it? Being right about the first does not make you right about the second, so answer them separately before you buy.
When big ASX news breaks, our subscribers know first
How accounting can make AI earnings look cheaper than they are
If the issue is who gets paid, the next question is how payment shows up in the accounts. Here the timing matters more than most headline figures suggest.
Depreciation and useful lives
When a company buys servers, it does not record the full cost as an expense straight away. It capitalises the purchase, meaning it records it as an asset, then depreciates it, spreading the cost across the years the equipment is expected to be useful.
The cash leaves immediately. The expense arrives slowly. If the assumed life is longer than the equipment’s real usefulness, reported profit runs ahead of economic reality.
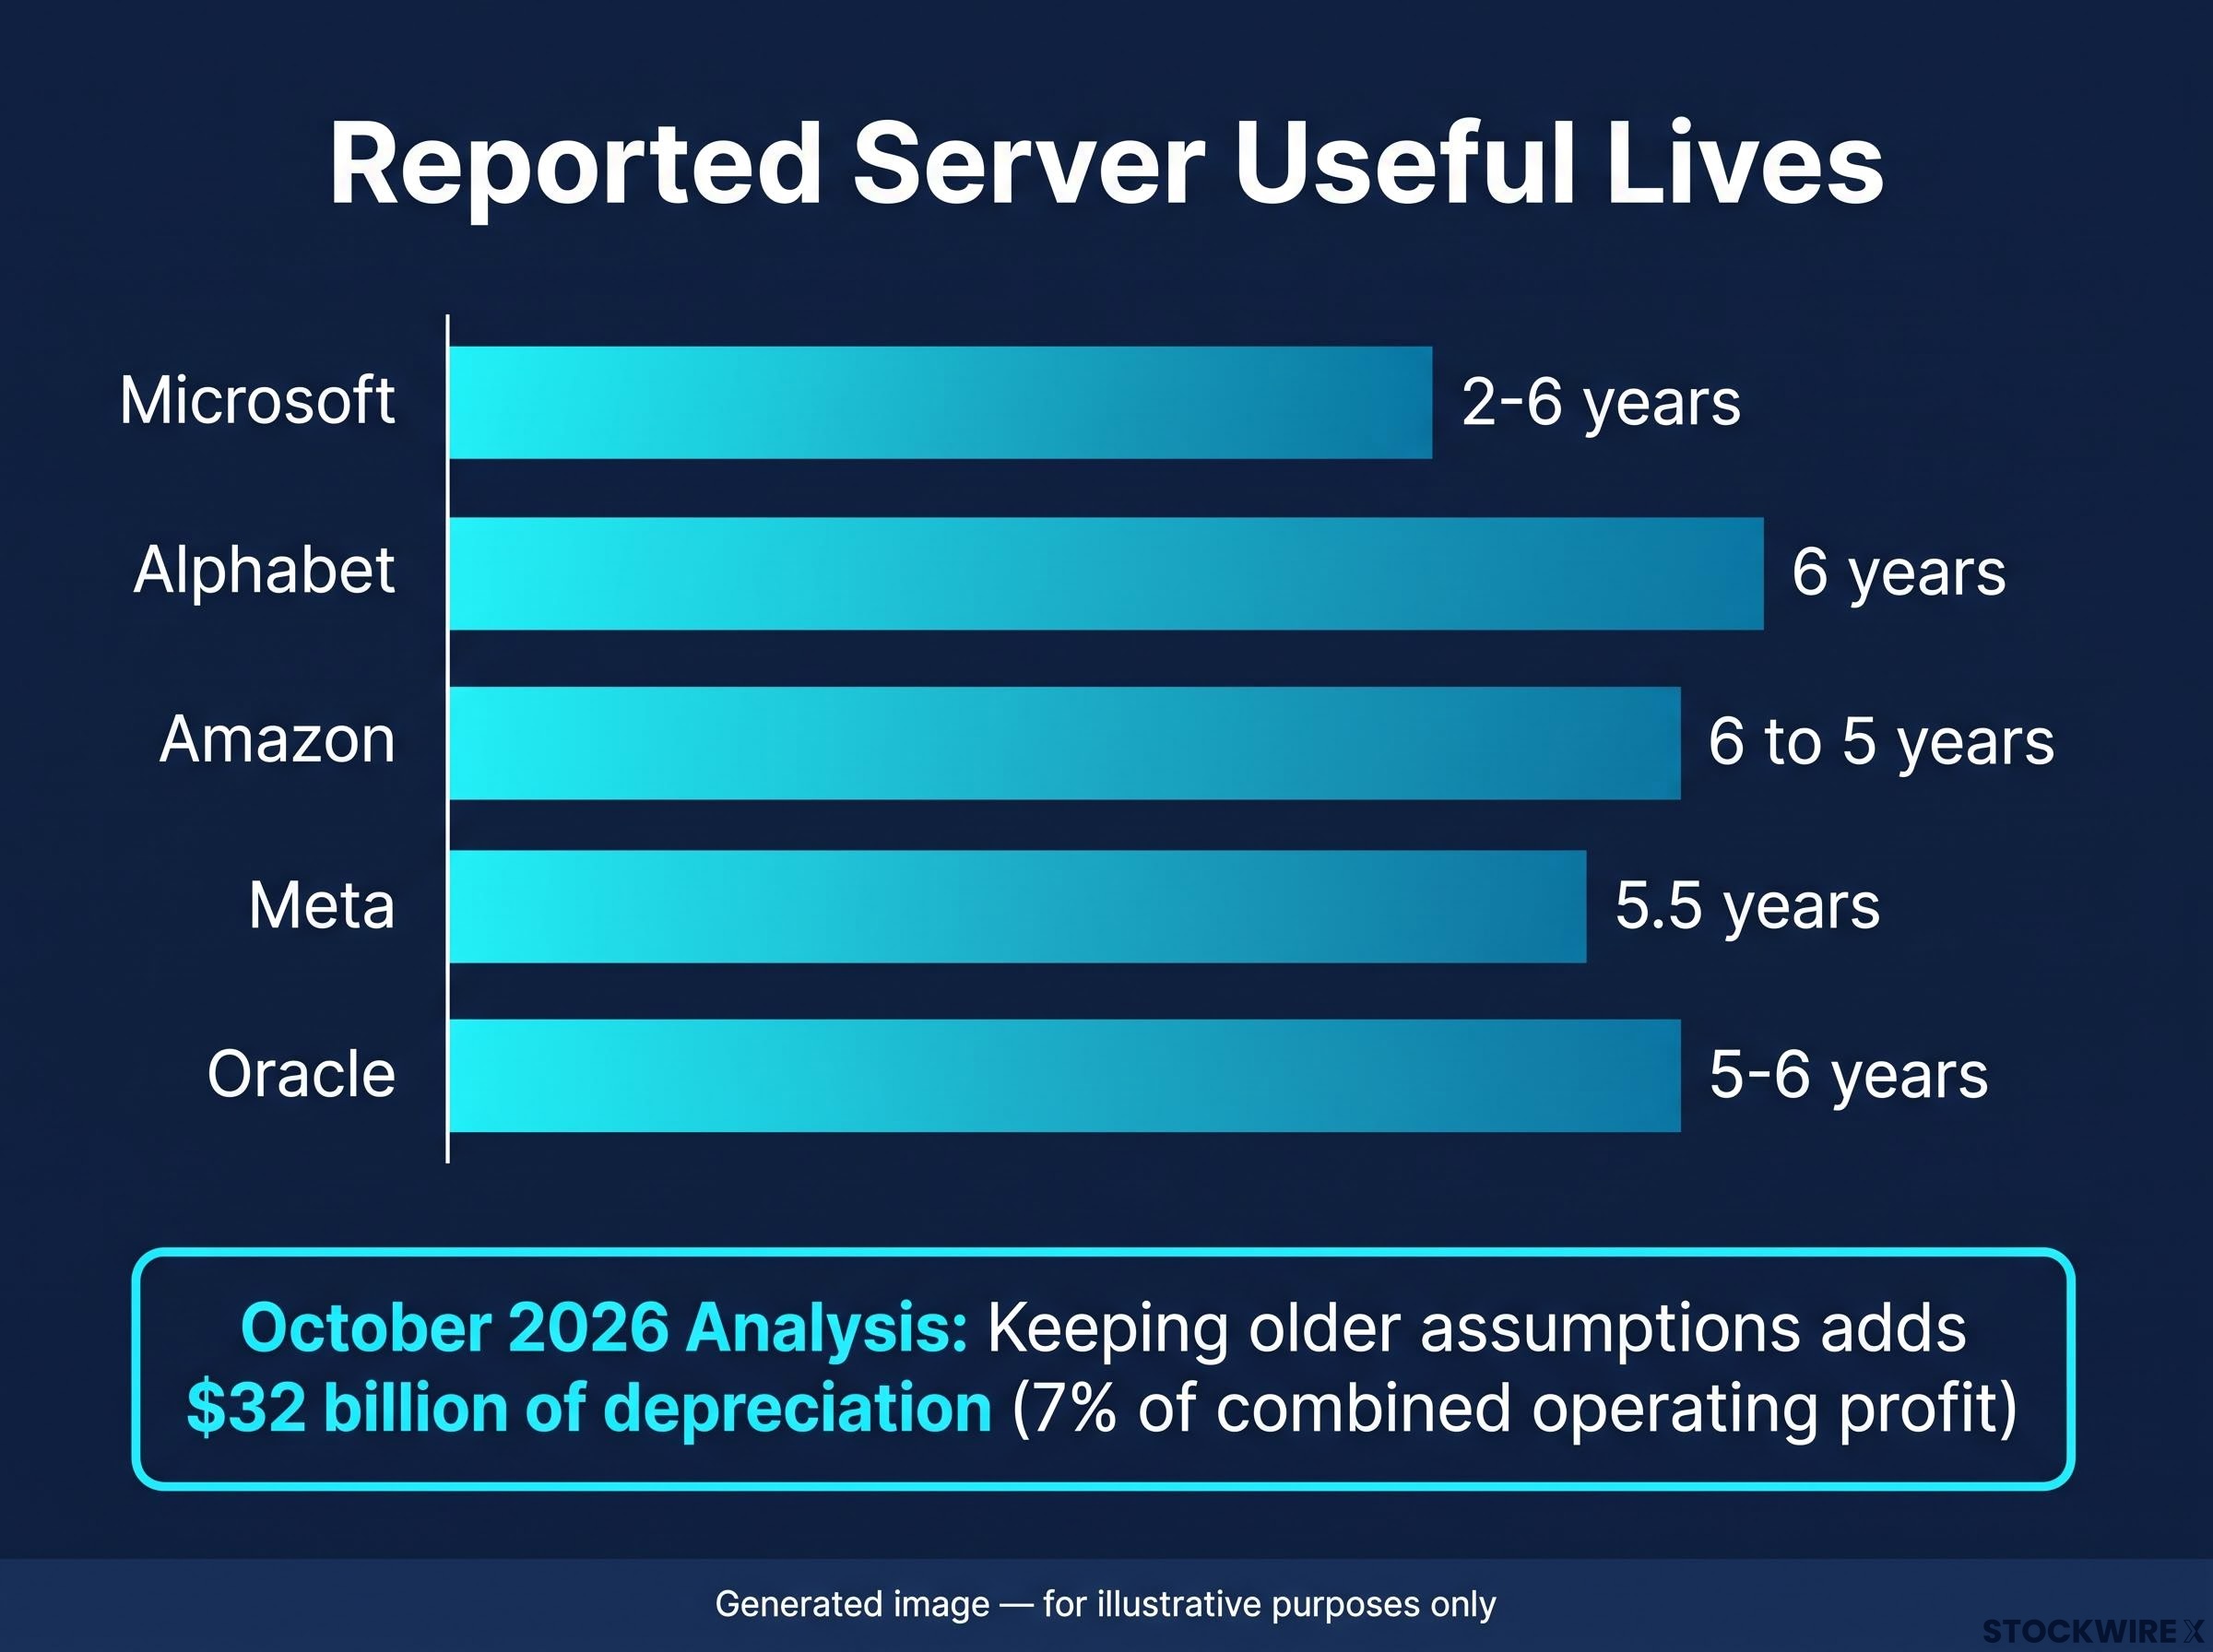
Muir approximates hyperscaler amortisation at around seven years. Company filings show a documented range of roughly two to six years:
| Company | Reported server life or change |
|---|---|
| Microsoft | Generally 2-6 years (fiscal 2026 filing) |
| Alphabet | About 6 years (2025 filing) |
| Amazon | Shortened a subset from 6 to 5 years, citing the pace of AI development |
| Meta | Extended to about 5.5 years |
| Oracle | Roughly 5-6 years |
A cross-company analysis published on 13 October 2026 reportedly found lives stretched from about 3-4 years in 2020 to 5-6 years by 2025. Keeping the older assumptions would have added roughly $32 billion of depreciation in the latest year, around 7% of combined operating profit. The counterpoint is fair: longer-lived equipment may stay productive, so the extended lives are not necessarily fiction.
Supplier revenue timing and circular financing
Muir illustrates a second asymmetry with a hypothetical $100 billion hyperscaler loan:
- The money splits roughly into thirds: chips, the building, and cooling and other equipment.
- Suppliers book their share as revenue and profit immediately.
- The hyperscaler recovers that cost over many years, if at all.
This is why Muir calls Nvidia’s roughly 10-12 times earnings multiple misleading. No reliable consolidated forward price-to-earnings (P/E) figure was available as of mid-October, so treat his number as his own characterisation.
Circular financing adds another layer. Nvidia invests in companies that buy its hardware; Microsoft funds OpenAI while capturing related Azure spending. This is not automatically improper, but it can make demand look stronger than independently funded customers would justify.
A low P/E in this sector may simply reflect when costs are recognised. Check cash flow and depreciation assumptions before you treat any AI stock as cheap.
What is a bubble in cash flow terms? Capex, free cash flow and subsidised demand
Accounting choices can flatter profit, but cash is harder to dress up. That makes it the cleaner test.
The cash squeeze
Free cash flow is the cash a business generates from operations after paying for capital expenditure (capex), its spending on physical assets such as data centres. When capex is heavy, it matters more than P/E because it shows whether a company can fund its ambitions from its own pocket.
| Company | 2026 capex guidance | Free cash flow signal (reported) |
|---|---|---|
| Microsoft | Latest quarter about $55.7B | Positive, $19.6B in the quarter |
| Alphabet | $195-205B | Negative quarter, about -$5.9B |
| Amazon | About $220B | Trailing 12 months about -$7.6B |
| Meta | $130-145B | Q2 down 91% year on year |
| Oracle | Fiscal 2027 about $90-95B | Fiscal 2026 about -$23.7B |
A Reuters analysis based on LSEG data reportedly projects capex for the five will exceed their free cash flow by 2027. Between 2025 and 2027, operating cash flow is expected to rise by about $340 billion while capex rises by about $534 billion.
Is demand subsidised?
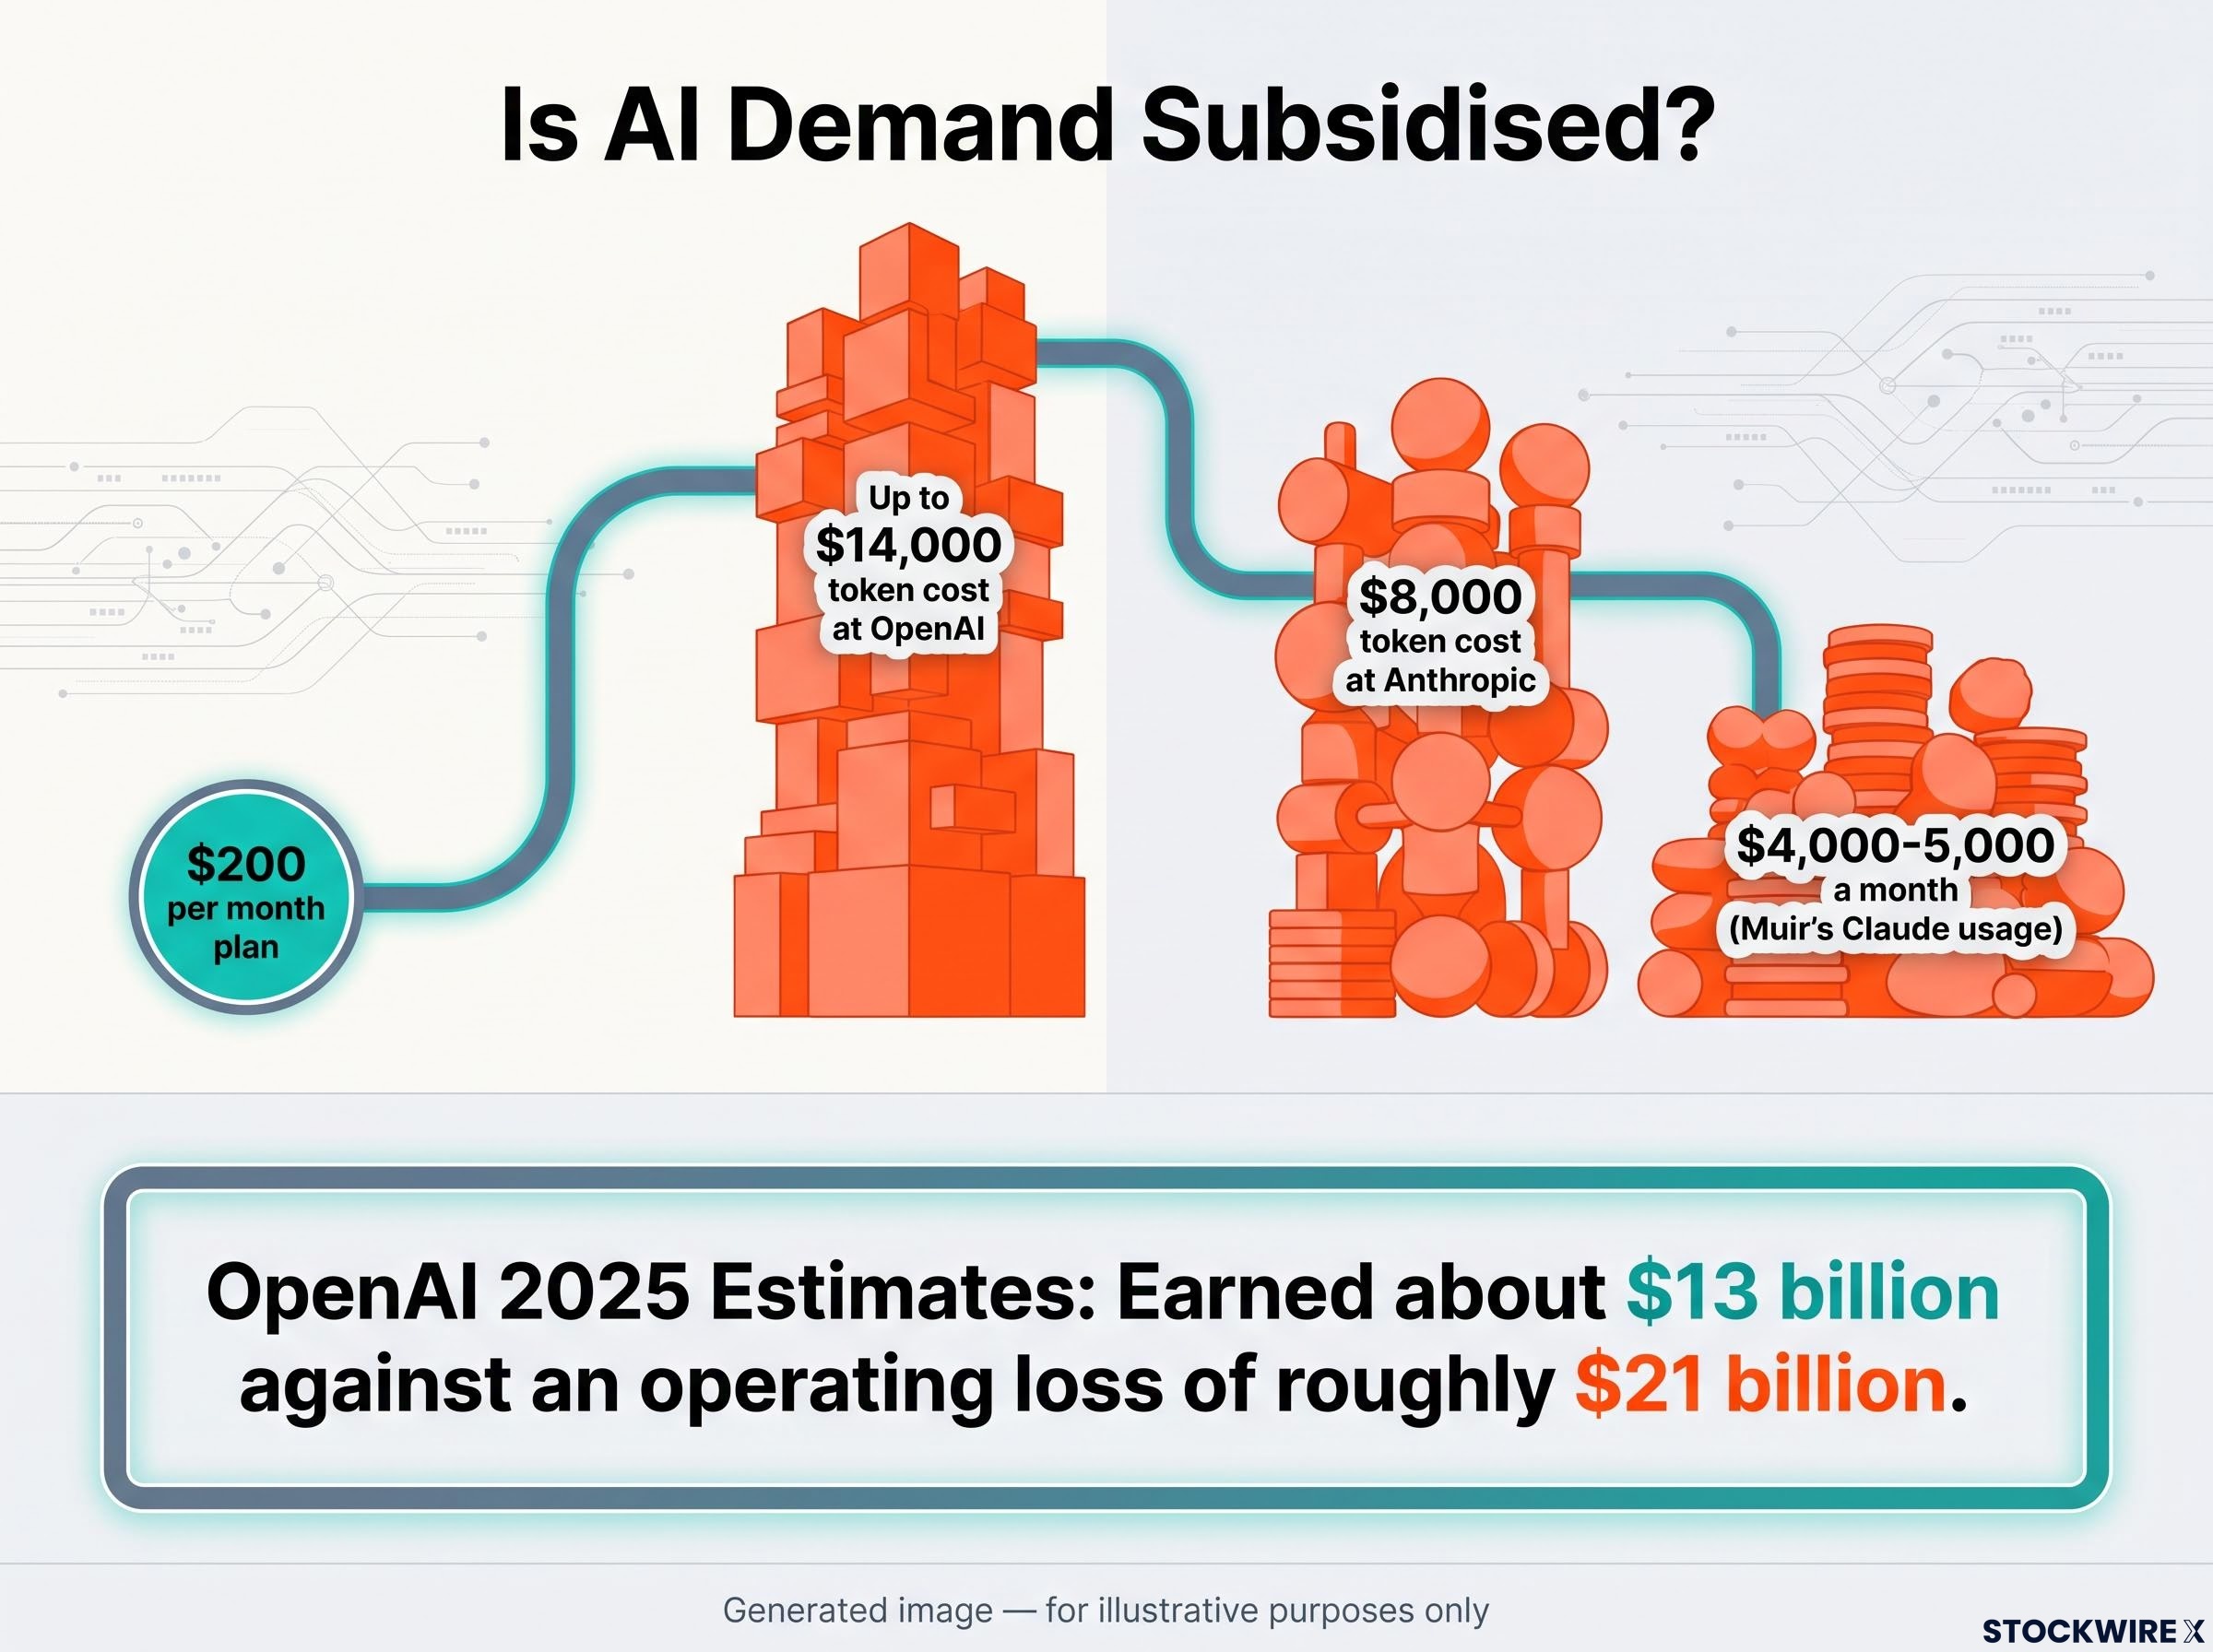
The revenue side raises its own doubts. OpenAI reportedly earned about $13 billion in 2025 against an operating loss of roughly $21 billion.
An estimate, not a company figure Reported estimates suggest a $200 per month plan could consume up to about $14,000 of token cost at OpenAI, or $8,000 at Anthropic. Muir estimates his own Claude usage at $4,000-5,000 a month.
Muir compares this to Uber’s early years, when cheap rides built habits that higher prices later tested. The counterweight is real: Goldman Sachs forecasts token costs falling 60-70% a year and consumption rising 24-fold by 2030.
Treat current AI revenue as an upper bound on mature demand until unit economics are proven. Usage at today’s prices may not survive tomorrow’s.
Investors exploring how falling token prices hit returns will find our deep-dive into open-weight model lab returns, which compares Morgan Stanley’s 20%-to-60% model-lab ROIC range with hyperscalers.
The quiet end of the buyback tailwind
Cash shortfalls have to be filled somewhere. That shift has quietly removed a support most investors never thought about.
For roughly two decades, Microsoft and Google bought back their own shares, shrinking the share count. Fewer shares meant each remaining one claimed more profit, a steady tailwind for prices. Now the same companies are borrowing and issuing.
Goldman Sachs reports hyperscaler buyback allocation has fallen from 27% of total cash spending to about 15%, which helps explain why the share-count tailwind has faded.
- Alphabet reportedly raised about $31.5 billion in a February 2026 bond, including a 100-year tranche.
- The five hyperscalers reportedly issued about $159 billion of bonds through early June 2026, about 47% above all of 2025.
- Goldman reportedly expects $250 billion in 2026 and $400 billion in 2027.
- Debt and equity fundraising across hyperscalers, data centre vehicles and neo-clouds reportedly rose from $172 billion in 2025 to $346 billion in 2026 through late September.
- The International Monetary Fund (IMF) reportedly identified about $300 billion of equity and $650 billion of debt across 14 AI deals since 2023, against $1.4 trillion of future revenue commitments.
Muir on share supply Muir notes Google had not issued shares since its 2004 IPO, yet is now raising equity, and he sees the supply of stock expanding for the first time in years, possibly decades.
No consolidated figure netting buybacks against issuance exists yet. The direction is still clear. If the companies stop being net buyers of their own stock, the support behind past returns may not be there, so those returns are a weaker guide to what comes next.
A framework for questioning AI valuations, and the case against the bears
None of this proves the AI bubble will burst. The bull case deserves a fair hearing first.
The strongest case against the bubble view
Hyperscalers have described capacity as supply-constrained, according to Liontrust. Falling costs could expand demand rather than erode it. Amazon reportedly generated about $161 billion of operating cash flow through June 2026 despite negative free cash flow, and downstream customers may capture real productivity gains.
Bulls point to more than $2.3 trillion of contracted backlog across the major cloud providers as evidence that demand is signed rather than speculative, though counterparties still have to be able to pay.
| Voice | Position |
|---|---|
| Kevin Muir | Bubble on dot-com scale; retail investors can stay out while professionals face career risk |
| Howard Marks (Oaktree) | Speculative traits visible, too early to call prices irrational |
| Michael Burry | Warns of excess capacity and write-offs |
| Bank of England | Valuations outpacing indices; markets pricing everyone as a winner |
| IMF | No bubble call, but flags correction risk |
| Goldman Sachs | Constructive on adoption and margins |
| Morningstar | Covered stocks about 8% below fair value |
Eight tests to apply to any AI holding
- Does the company earn above its cost of capital?
- What is free cash flow after capex, and what share of operating cash flow does capex consume?
- How do earnings look with three- or four-year hardware lives?
- What are revenue per GPU and utilisation?
- Is revenue committed or durable, and can counterparties pay?
- Is there a margin of safety against independent fair value?
- Are you diversified down the value chain?
- What happens if AI pricing falls 30-50%?
Some answers will be hard to find: Nvidia’s forward P/E and Anthropic’s financials remain data gaps. You do not need to call the top. You need to know which assumptions your holdings depend on, and what happens if they fail.
What the bubble debate changes, and what it leaves untouched
AI can be world-changing and still be a poor home for capital at current prices. Neither claim cancels the other, and the evidence here sits across three pillars: earnings that may run ahead of cash, demand that may be priced below cost, and share supply that is growing where it once shrank.
Rather than predicting a crash, watch the variables that will settle the argument: free cash flow after capex, depreciation assumptions, issuance volumes and any change in AI pricing. Figures cited are the latest available as of mid-October 2026, and several are reported rather than independently confirmed.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and forward-looking statements are speculative and subject to change.