Wafermine may reach U.S. military users before its Phase 3 trial finishes, and that changes what a small-cap biotech’s value depends on. Phillip Securities left its BUY rating on iX Biopharma unchanged after the news, which suggests the analyst had already counted this route in. The harder question for any iX Biopharma Wafermine investment is what the market has priced in and what it has not.
The sequence is short. On 15 July 2026 the Secretary of War made a military emergency determination, the Department of Health and Human Services (HHS) declaration took effect on 31 August 2026, and a US$40.95M (about US$41M) Department of War award is funding the work.
It is early October 2026, and every milestone that would turn this into revenue still lies ahead.
Here is a framework for judging which parts of the story are funded and validated, and which remain binary.
Why the HHS declaration changes the regulatory picture
The declaration came in steps, and each one raised the stakes a little.
- 15 July 2026: The Secretary of War made a military emergency determination under section 564(b)(1)(B) of the Federal Food, Drug, and Cosmetic (FD&C) Act, citing a heightened risk of a chemical, biological, radiological or nuclear (CBRN) attack on U.S. forces.
- 31 August 2026: The HHS declaration took effect, justifying emergency use of drugs for moderate-to-severe acute pain in military casualties.
- 3 September 2026: The notice was published.
- 7 September 2026: iX Biopharma issued its announcement to the Singapore Exchange (SGX).
Phillip Securities called it:
“A significant step towards FDA approval and commercialisation for iX Biopharma’s Wafermine product.”
Head of Research Paul Chew reads the declaration as implicit endorsement from two U.S. government departments. The pathway is rare: it has been used only once before, in 2018 for freeze-dried plasma.
Scope matters. The declaration covers pain from CBRN or combat agents, including firearms and explosive devices, tied to the emergency circumstances rather than all military injuries.
Now the sober part. The declaration satisfies the statutory precondition that lets the Food and Drug Administration (FDA) consider an Emergency Use Authorization (EUA). It is not an authorisation.
Not all regulatory designations carry the same weight: a declaration that satisfies a statutory precondition is a different signal from a Fast Track grant or an actual authorisation, and each reflects a different evaluating body.
For you as an investor, one gating uncertainty is gone, namely whether an EUA route exists at all. The harder one, whether the FDA will actually grant it, remains fully open.
When big ASX news breaks, our subscribers know first
How the Section 564 EUA pathway works, and why it can shorten the route to revenue
How can a drug be used before it is approved? Section 564 of the FD&C Act lets the HHS Secretary declare that circumstances justify emergency use of unapproved medical products. Those circumstances can include a CBRN threat or a military emergency.
Once a declaration exists, the FDA can grant an EUA if the product clears several tests. It weighs risk against benefit, checks whether adequate approved alternatives exist, and looks at manufacturing and quality controls.
Analysts see this as a shorter route to U.S. revenue because an EUA can rest on a smaller data package than a full New Drug Application (NDA), the standard filing for approval.
| Attribute | EUA | NDA | Why it matters to investors |
|---|---|---|---|
| Data required | Can rest on a smaller package | Full evidence of safety and efficacy | Earlier revenue is possible |
| Duration | Temporary | Ongoing once approved | Revenue may not last |
| Permanence | Can be revised or revoked | Standard approval | Affects how you value the cash flows |
What an EUA is not
It is not full approval, and it may be limited to specific populations or settings. FDA guidance stresses that EUAs are temporary and can be revoked once the emergency ends or the data change.
Precedent offers limited comfort. The 2018 plasma case is the only prior use of this military route, and the research does not detail its sponsor or revenue. Broader COVID-19 and anthrax EUAs show early procurement is possible, but always conditional.
Any EUA-driven revenue you model should therefore be treated as dependent on the declaration persisting, not as a permanent base.
What the roughly US$41m Department of War award actually funds
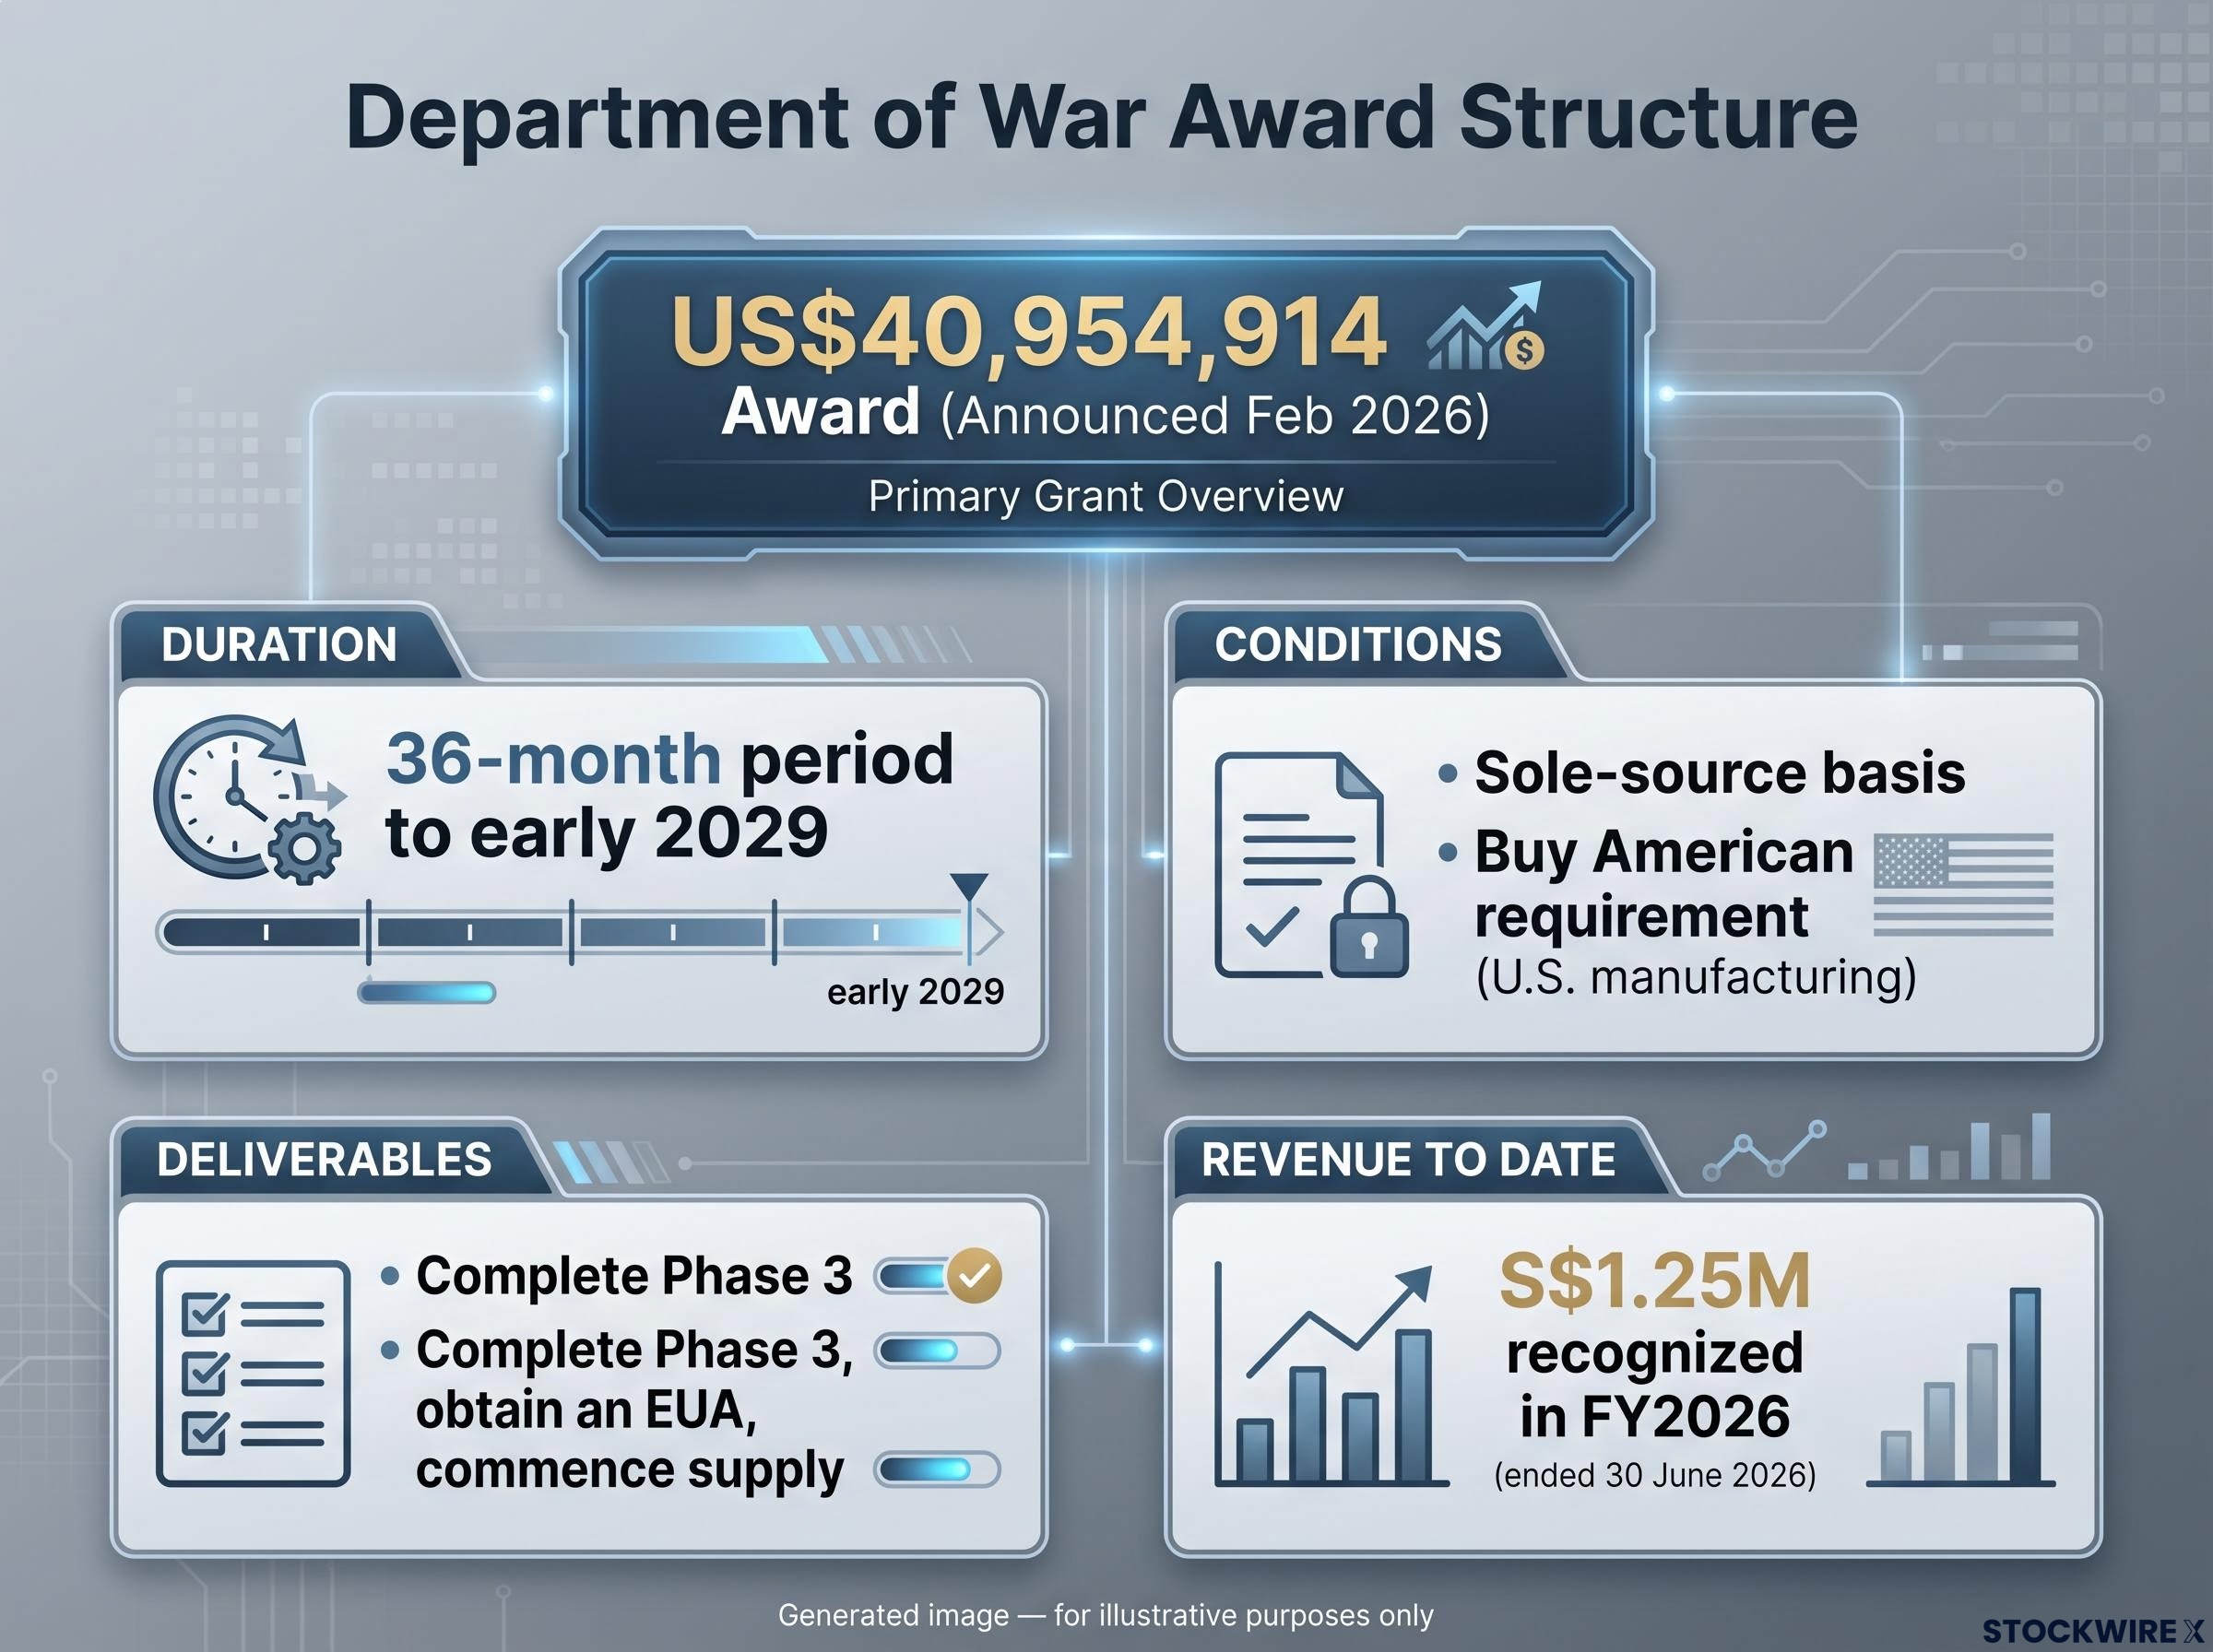
The headline number is US$40,954,914, announced in February 2026. The finer print is where the investment case gets its shape.
Key terms of the Other Transaction Agreement with the Defense Health Agency Contracting Activity:
- A 36-month period, running to roughly early 2029
- Sole-source basis, meaning the government judged the company uniquely capable of delivering on time
- Fixed monthly payments for directly incurred labour, with other costs reimbursed monthly
- Deliverables: complete Phase 3, obtain an EUA, then commence supply
- A Buy American requirement, so supply must be manufactured in the U.S.
Chew described the funding as:
“A major endorsement and major external validation” of the WaferiX sublingual technology.
The revenue so far is modest. About S$1.25M was recognised as development services in FY2026 (year ended 30 June 2026), according to a 31 August 2026 SGX filing.
The award tells you Phase 3 and EUA costs are largely covered, which cuts near-term dilution risk. But S$1.25M shows the contract is a funding bridge, not a profit engine.
With only S$1.25M of development services revenue recognised, conventional earnings metrics say little about iX Biopharma, and milestone-based analysis, tracking submissions, decisions and production starts, is the more useful lens for judging progress.
The 4Q26 to 2Q27 timeline: catalysts and where it can slip
The calendar is compact, and the company left it unchanged after the HHS news. The declaration did not accelerate anything.
| Milestone | Timing | Status | Key dependency |
|---|---|---|---|
| EUA submission | Q4 2026 | In progress | Data package |
| EUA approval | Q1 2027 | Pending | FDA discretion |
| First U.S. production line | Q1 2027 | Pending | Nevada equipment move |
| EUA production | Q2 2027 | Pending | EUA granted |
| Three additional lines | Q2 2027 | Pending | Buy American build-out |
| Phase 3 trial approval | Q2 2027 | Pending | Regulatory clearance |
Revenue is likely to cluster around and after the Q1 2027 decision and the Q2 2027 production start. You should treat Q1 2027 as the date that decides whether this is a validated early-revenue story or a slower, standard NDA story.
Where slippage is most likely
The main execution exposure is manufacturing. Freeze-drying equipment must move to Nevada and four U.S. production lines must be built to satisfy Buy American rules.
History urges caution. In October 2022, Phillip cut its target to S$0.25 on delays in capacity expansion and drug trials. FDA review timing and data sufficiency are the other pressure points.
Valuation and risk: what Phillip’s S$1.00 BUY rating does and does not tell you
Phillip re-initiated coverage at BUY with a S$1.00 target on 24 April 2026, and left both unchanged on 31 August and 25 September 2026. Unchanged after the HHS news means the analyst did not raise estimates on it.
How the valuation is built
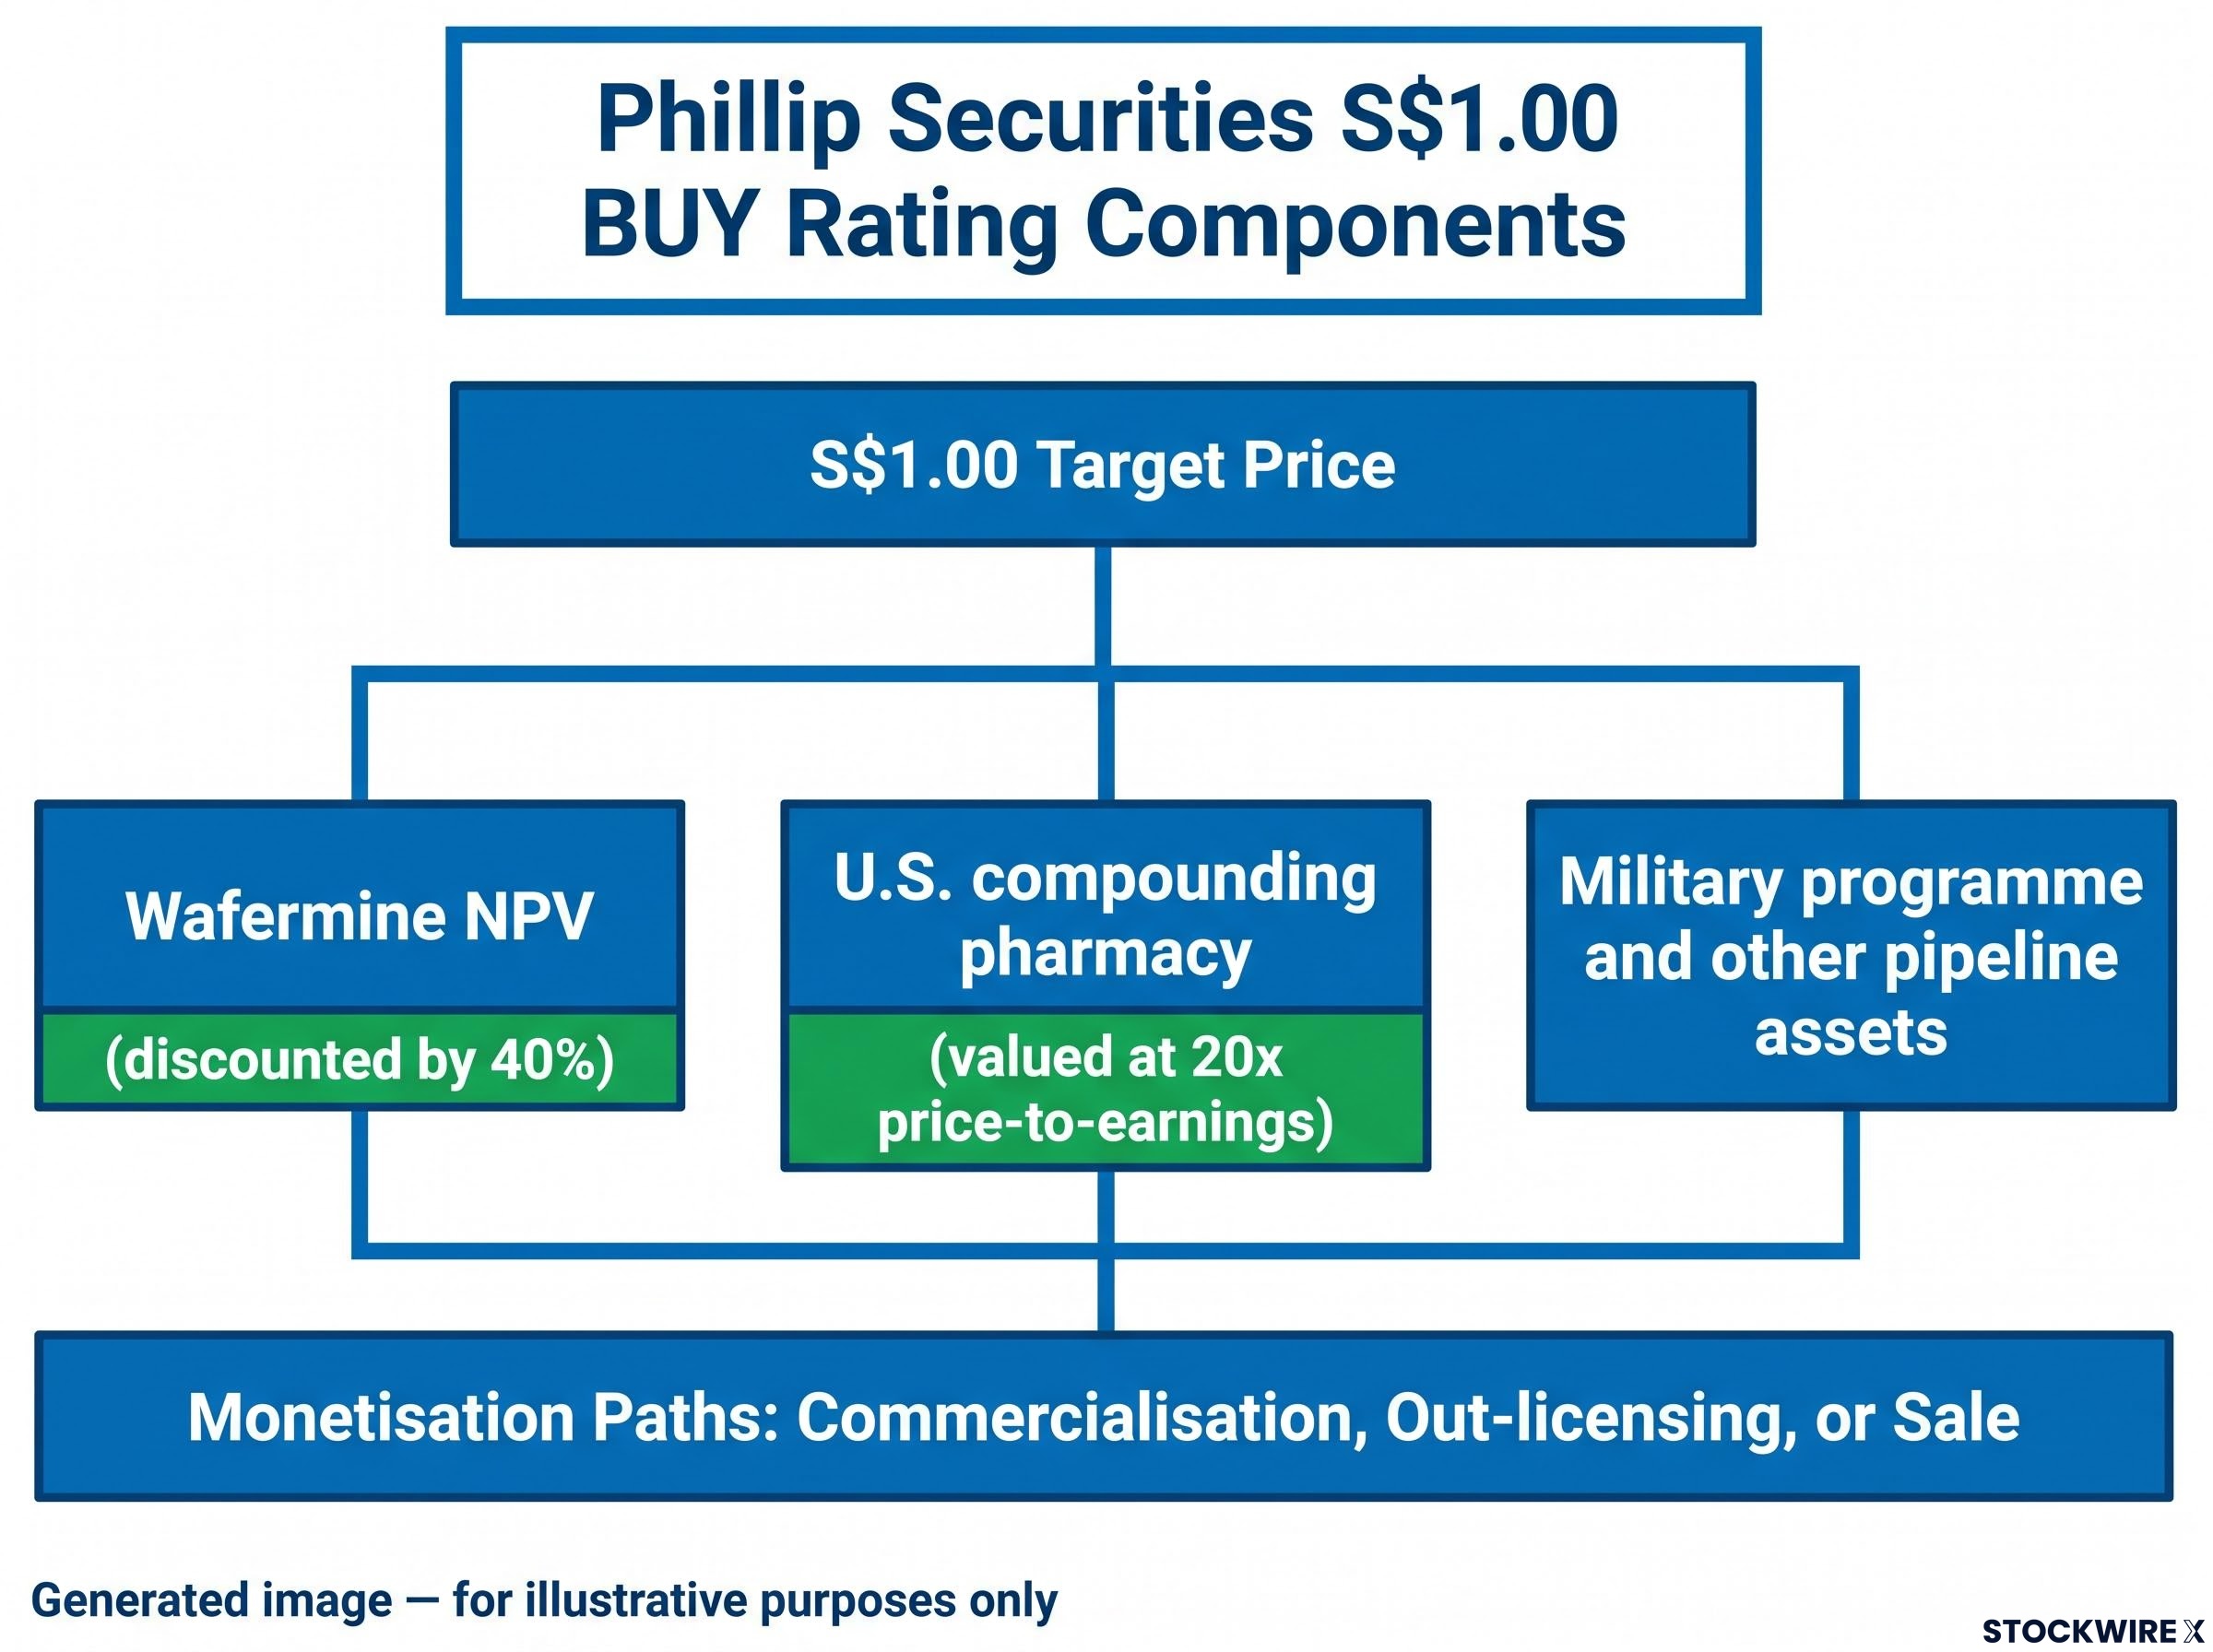
The target comes from a discounted cash flow sum-of-the-parts:
- Wafermine net present value, discounted by 40%
- The U.S. compounding pharmacy, valued at 20x price-to-earnings
- The military programme and other pipeline assets
Phillip points to three monetisation paths: commercialisation, out-licensing or a sale.
The risks that can break it
| Factor | Bull case | Bear case | What to watch |
|---|---|---|---|
| Customer | Funded government buyer | Single-customer concentration | Contract continuity |
| Regulation | EUA granted in Q1 2027 | Denied, limited or revoked | FDA decision |
| Funding | Phase 3 covered | NDA and build-out may need capital | Financing announcements |
| Product | Non-opioid, rapid onset | Ketamine scheduling and abuse potential | Labelling and access controls |
If the FDA finds the data insufficient, Wafermine reverts to a longer NDA timeline without the early military revenue. This is a single-broker view, and iX Biopharma is SGX-listed, not U.S.-listed. One target is an input, so weigh S$1.00 against these risks rather than treating it as an expected outcome.
The DEA ketamine factsheet classifies the drug as a Schedule III non-narcotic substance and flags its abuse potential, which is why labelling and access controls sit on the bear-case side of the risk ledger.
A checklist for judging the case before the 1Q27 EUA decision
Five tests can tell you whether the funded parts of the story are converting into revenue.
- EUA submission confirmed in Q4 2026.
- FDA decision arriving in Q1 2027.
- First Nevada production line starting on schedule.
- Further revenue recognition beyond the S$1.25M baseline.
- Financing announcements that signal dilution.
Each result matters more than the S$1.00 target, which is context only. The thesis is binary and suits only investors who can tolerate that. This is analysis, not personal financial advice.
What is validated, what is still binary, and what to watch next
Two U.S. government departments have backed the pathway, and the Phase 3 programme is funded. Those parts are validated.
EUA discretion, manufacturing execution and reliance on one customer are not. The Q4 2026 submission and the Q1 2027 decision are the next events to resolve them.
Your call depends on whether you can hold through a binary outcome.
Investors exploring how to size a position ahead of a binary regulatory decision will find our dedicated guide to biotech position sizing and catalyst risk sets out concrete exposure caps.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. These statements are speculative and subject to change based on market developments and company performance.