Australia holds a $45 million grant for a battery anode plant and still has a $55 million hole in the budget. Meanwhile, rivals in the UK and US are being handed equity and loans measured in the tens or hundreds of millions.
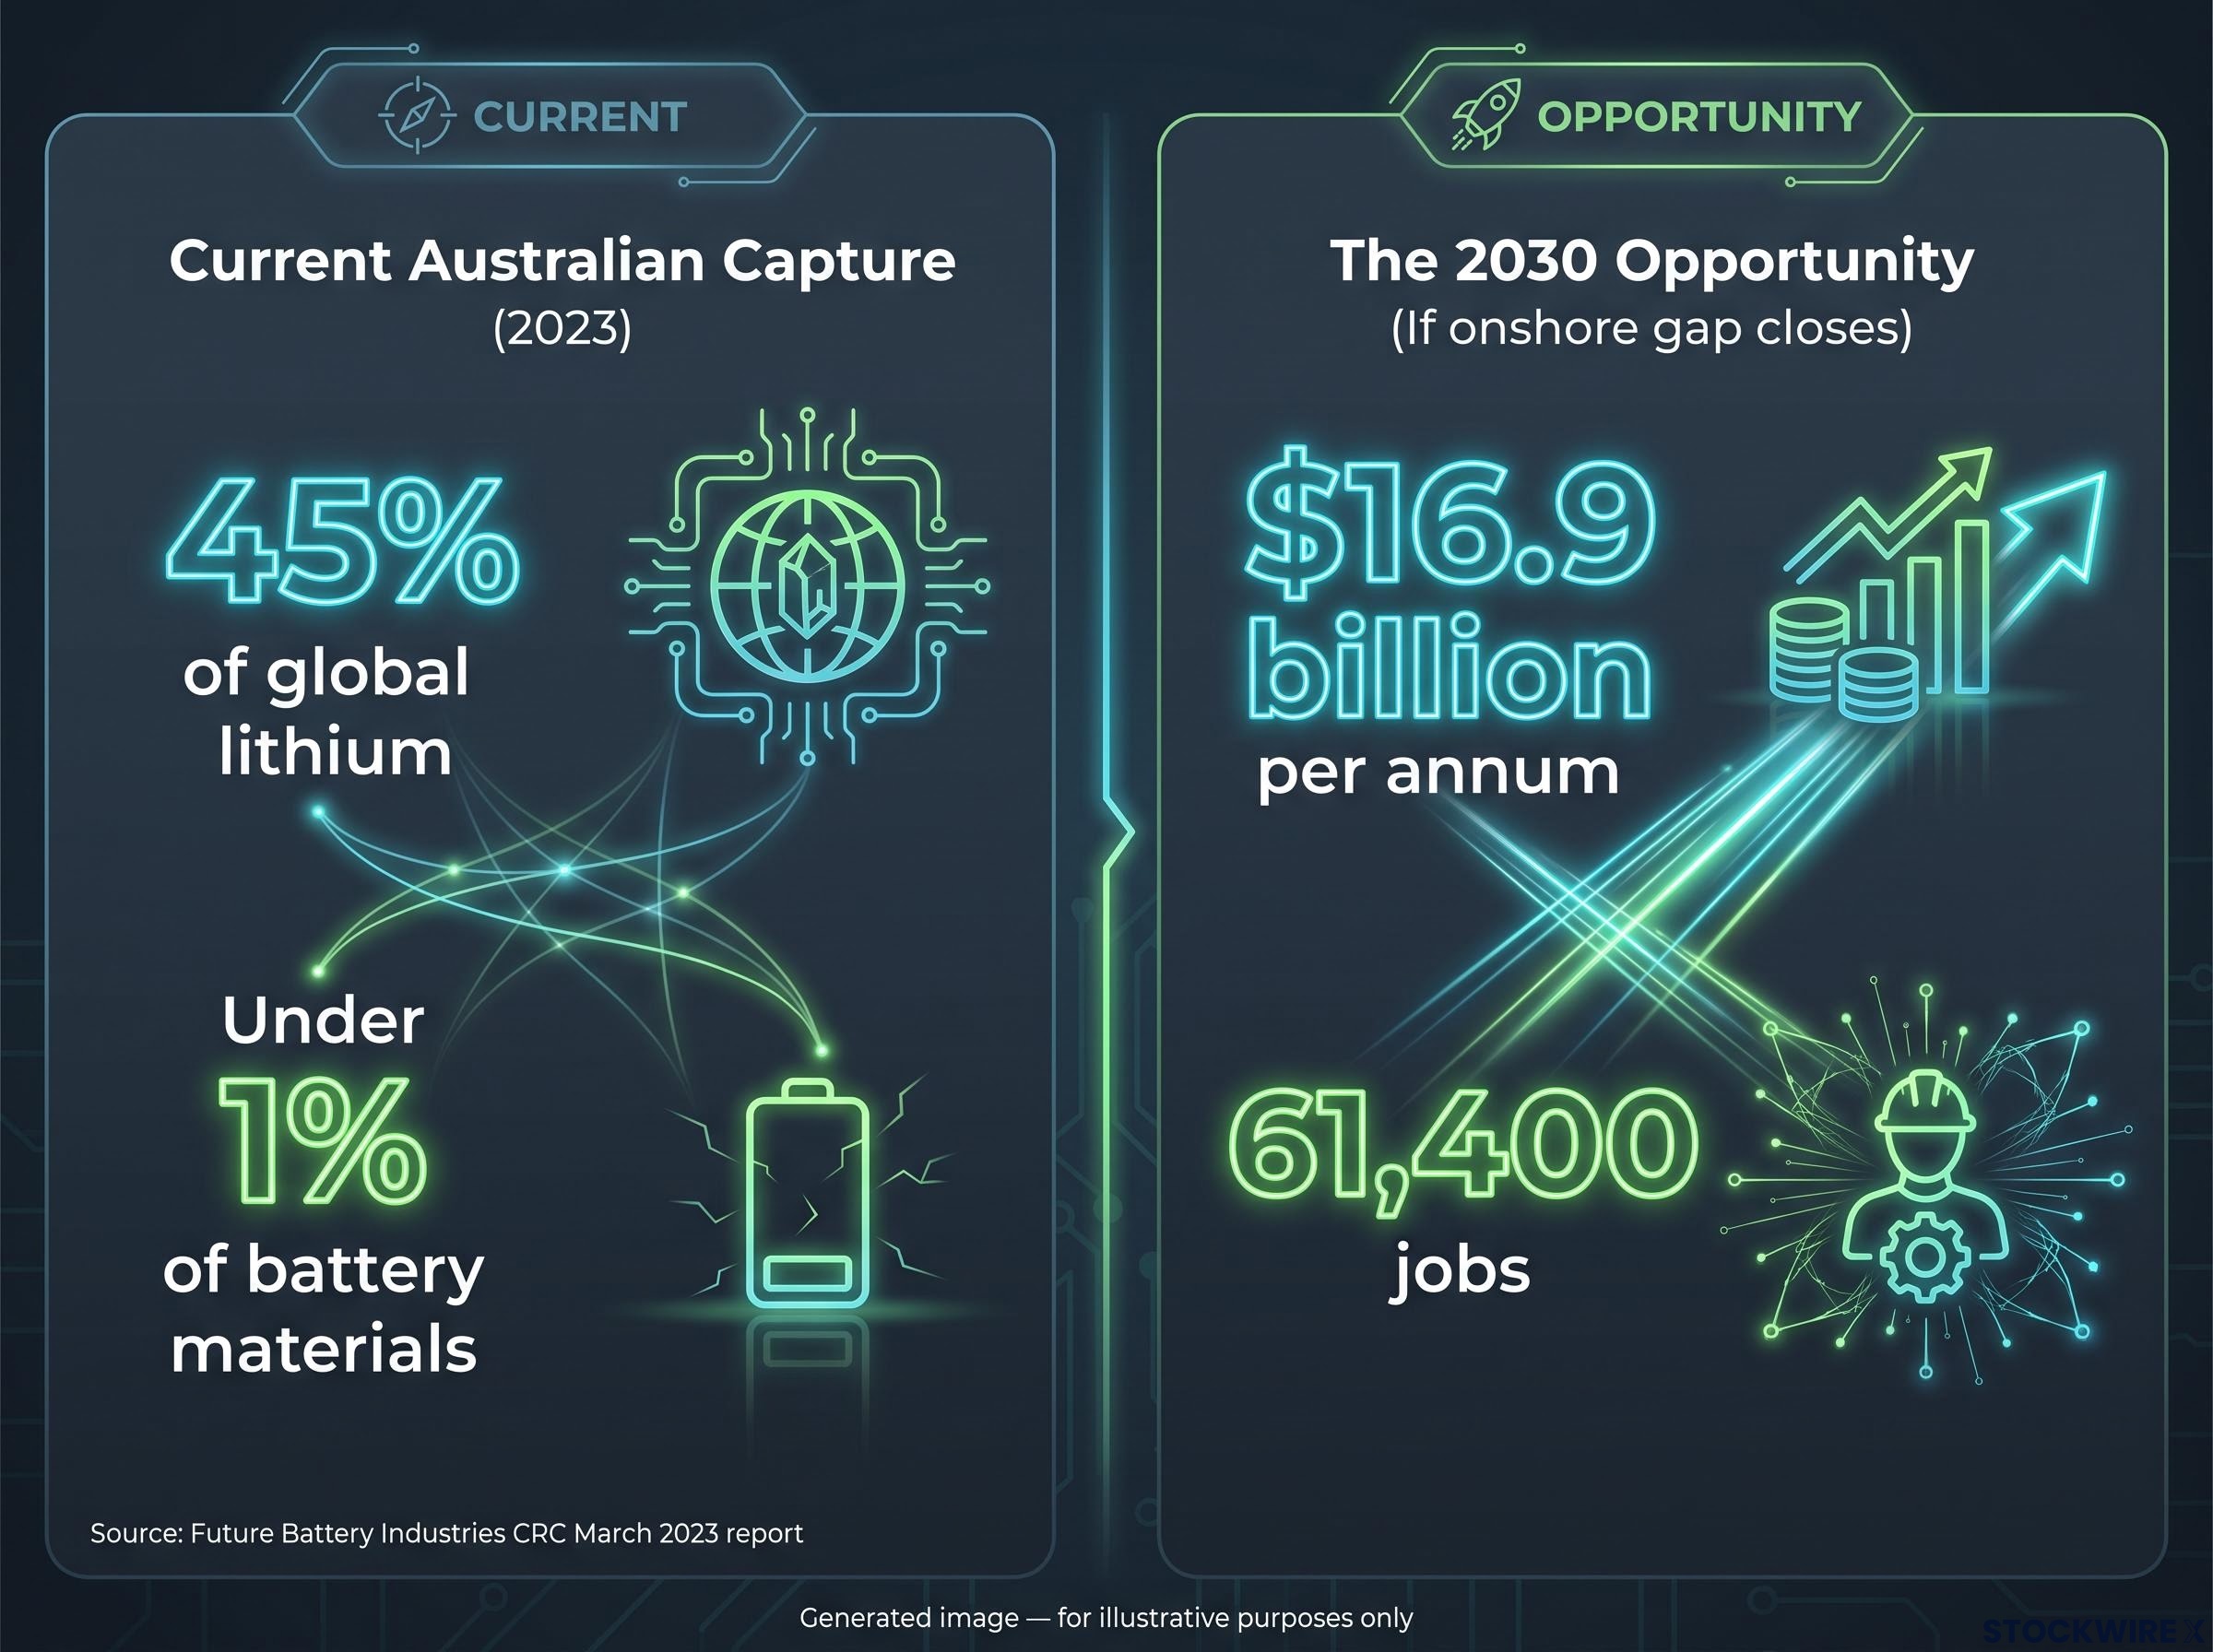
That asymmetry challenges the assumption that grant support alone gets factories built. Australia produced 45% of the world’s lithium in 2023 but under 1% of global battery materials or components, and the stated $16.9 billion per annum, 61,400-job opportunity depends on closing that gap onshore.
Here is where the funding gap actually sits, how overseas governments are filling it, and what to watch to judge whether the National Reconstruction Fund changes the picture. If the midstream is financed elsewhere, Australian investors stand to lose the value-add that the forecast promises.
Why does a funded battery startup still stall before the factory?
Sicona Battery Technologies has a $45 million grant from the Australian Renewable Energy Agency’s (ARENA) Battery Breakthrough Initiative (BBI) for a silicon-carbon anode plant at BlueScope’s Port Kembla precinct in New South Wales. Yet as of early October 2026, the company is still seeking $55 million in equity. PV Magazine Australia (2 October 2026) describes the project as moving from pilot to commercial scale, not under construction or commissioned.
| Item | Detail | Status |
|---|---|---|
| ARENA grant | **$45M** (BBI) | Secured |
| Total project cost | About **$100M** (official **$98.84M**) | Funding incomplete |
| Equity sought | **$55M** | Open as of early October 2026 |
| Nameplate capacity | Up to **230 tpa** (some sources cite **150-230 tpa**) | Planned |
| Jobs | Up to **72** (Sicona) or up to **36** (ARENA) | Sources conflict |
The technology is not the obvious weak point. Sicona’s SiCx® silicon-carbon anode is reported to deliver around 20% higher energy density and over 40% faster charging than conventional graphite, as a drop-in additive for existing lithium-ion lines. The project targets a roughly 300-fold output increase, with about 35 tpa (tonnes per annum) in initial operation, and pathways to 6,500 tpa and potentially 26,500 tpa. The project window runs from 1 June 2026 to 31 January 2030, with site exclusivity from BlueScope.
Sicona’s September 2026 acquisition of US-based Advano lifted its portfolio to 151 patents across 46 families and added a New Orleans pilot site. Port Kembla plans are unchanged.
“Battery manufacturing in Australia repeatedly stalls at the same point,” said Christiaan Jordaan, Chief Executive Officer and founder of Sicona.
Jordaan’s point is that grants and venture capital carry projects to pilot scale, then stop. John Wood, Director at NOAB Ventures, says construction finance becomes the main hurdle across his portfolio after seed and venture funding.
For you, the lesson is that “grant secured” is a milestone, not a guarantee. A strong patent portfolio and public money do not remove scale-up and funding risk.
When big ASX news breaks, our subscribers know first
What is the construction-finance “valley of death”?
The valley of death is the financing gap between a pilot or demonstration plant and full commercial manufacturing. It is a gap in money, not in technology: the product works, but nobody has yet funded the factory.
Funding arrives in stages, and each type of funder drops away at a different point:
- Research and grants: public programmes such as the BBI fund early development and demonstration.
- Pilot and venture capital: private investors back proving the product at small scale.
- Construction finance: large-scale project finance pays for the plant. This is where the gap occurs.
- Commercial operation: revenue from production supports the business.
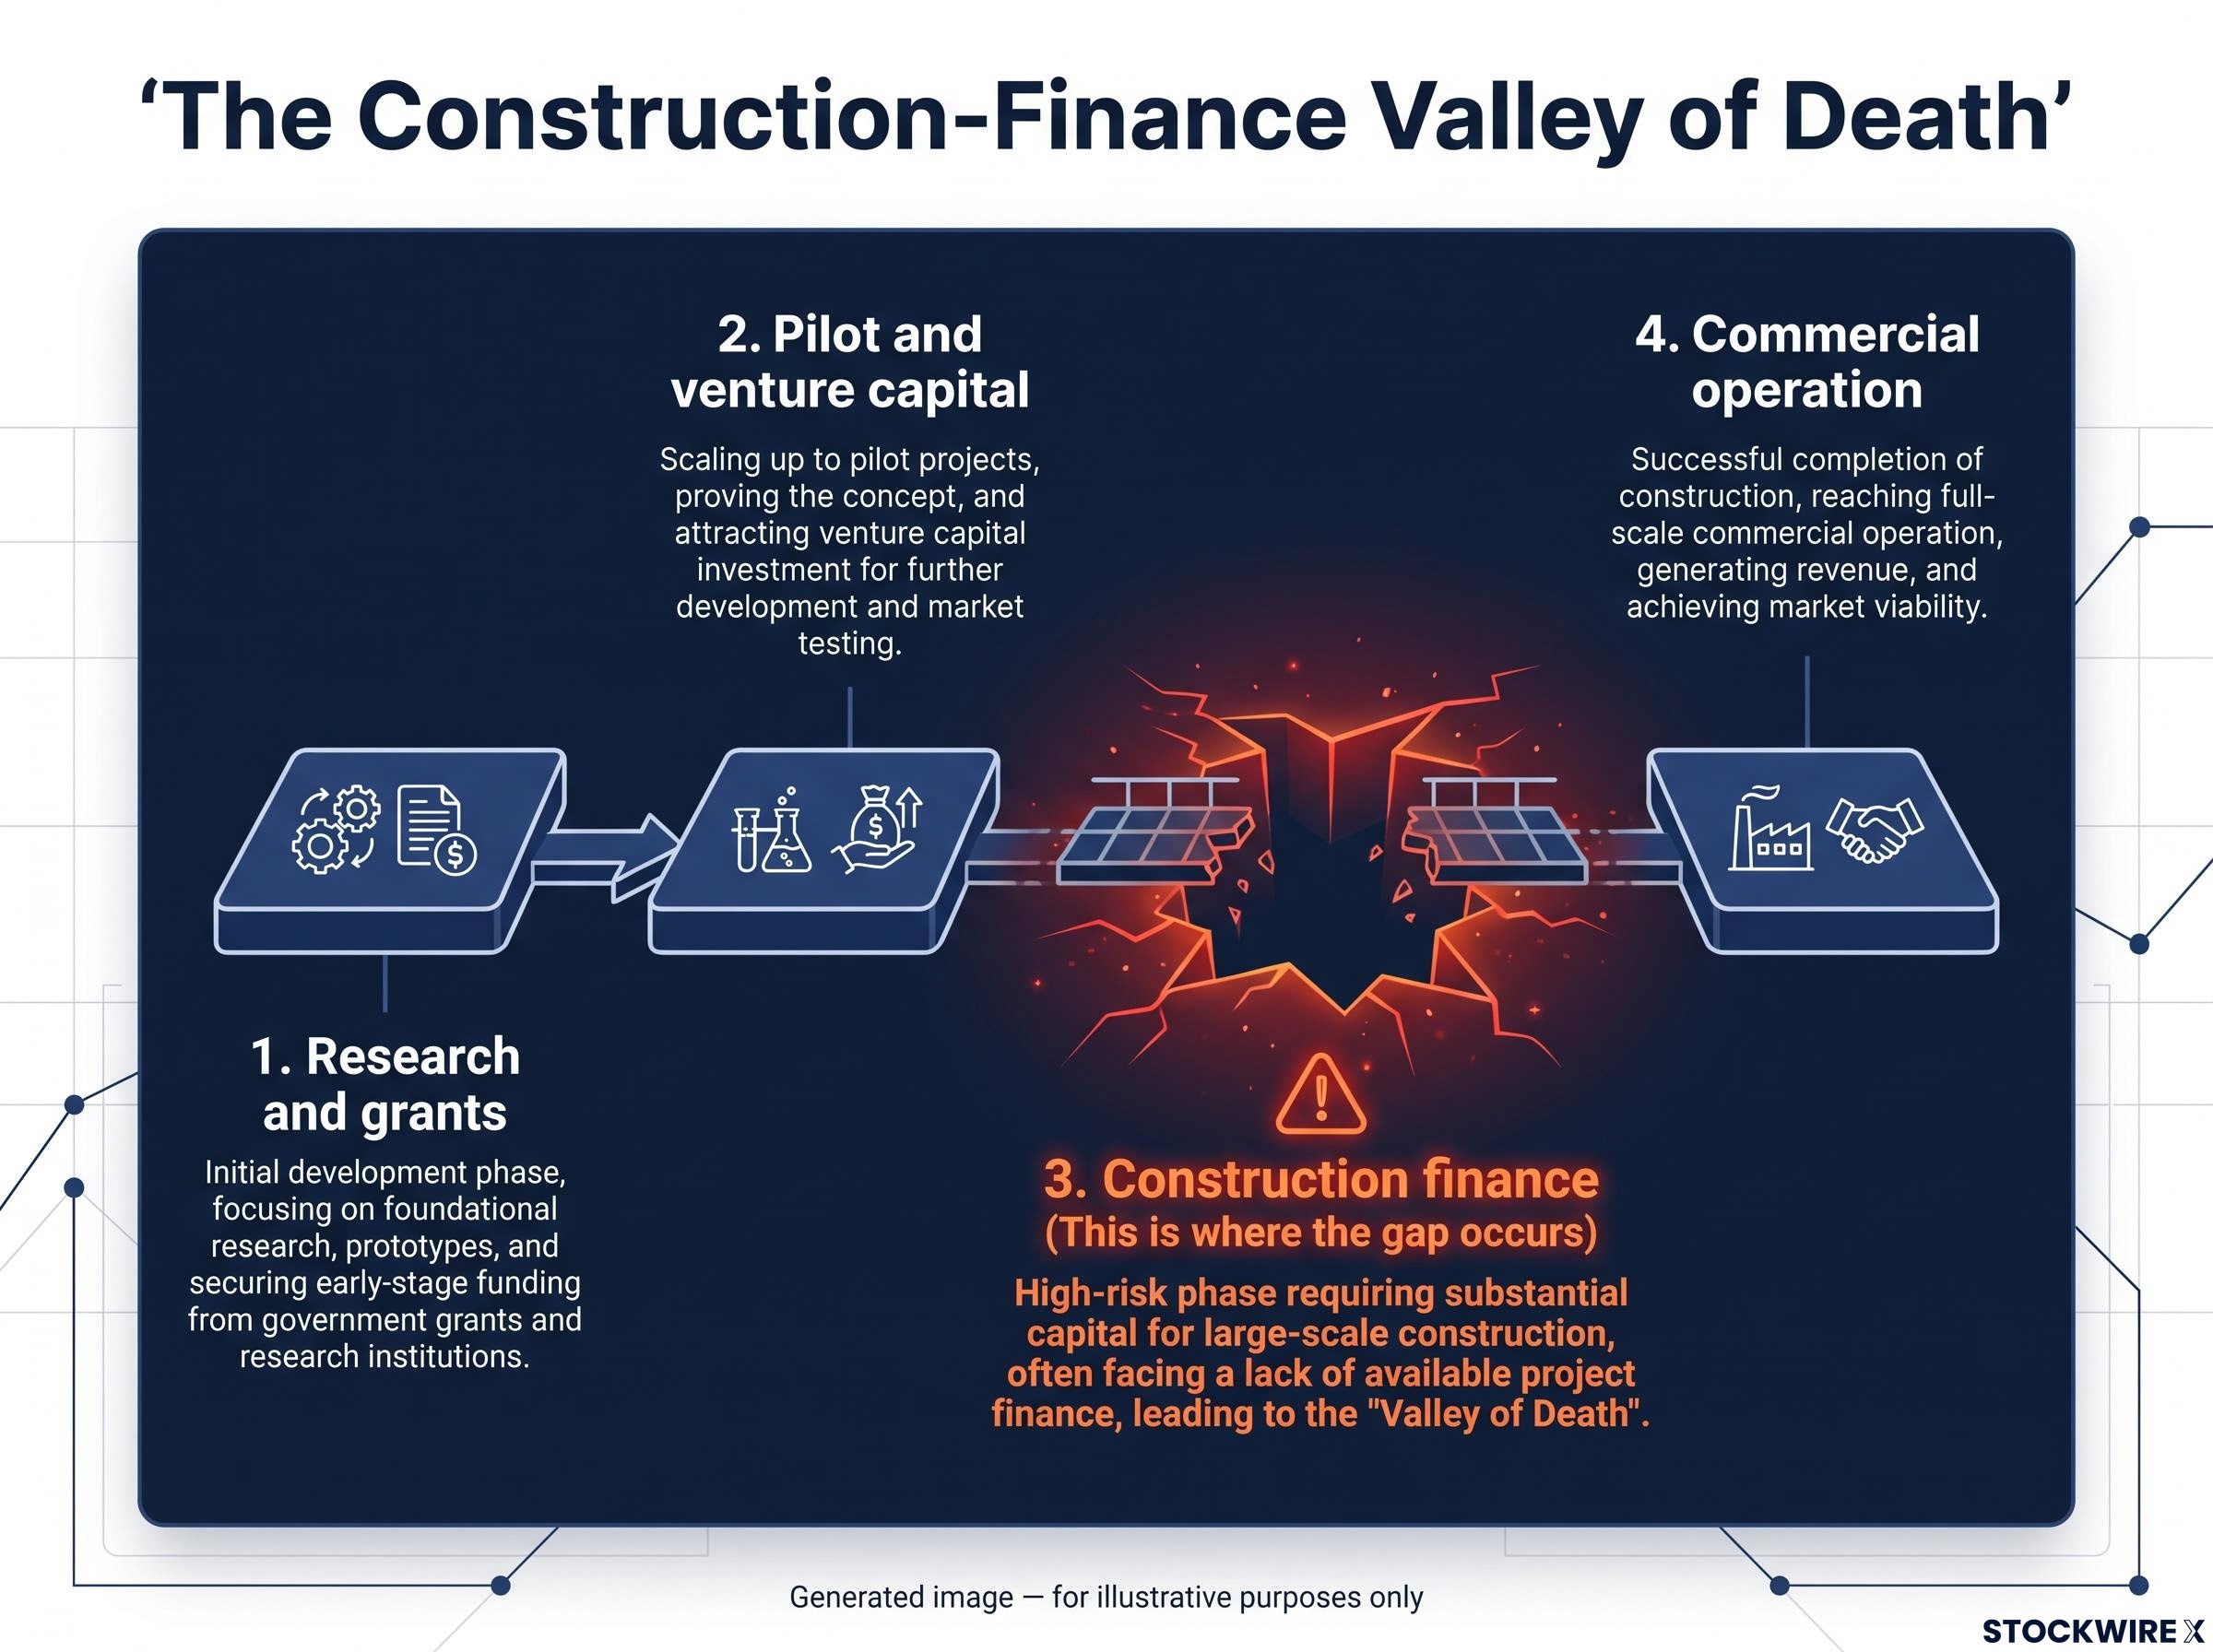
Late-stage lenders are cautious because a first-of-kind plant carries both technical and market risk. Grant and venture money has often run out by then.
Part of the problem is that climate technology now behaves like an infrastructure-style capital cycle, where factories need patient, large-ticket financing rather than the venture funding that carries pilot projects.
Sicona illustrates the point. The BBI is closed to new applications, so the grant pathway that carried the company is not open to the next cohort. Jordaan’s position is that every company in the category needs construction finance once grants and venture capital run out.
The scale of the missed opportunity shows in Australia’s capture rate: 45% of global lithium, under 1% of battery materials. Because the gap sits between funding types, more early-stage grants alone will not shift where factories are built.
Why a strong patent portfolio does not close the gap
Patents reduce commercialisation risk by protecting the technology, but they do not eliminate it. A plant still has to be built, commissioned and run at scale.
Sicona’s 151 patents make the technology harder to copy. They do not mean the Port Kembla plant is derisked, and you should not read them that way.
How are the UK and US financing their battery anode rivals?
Start with the UK. On 31 August 2026, the National Wealth Fund (NWF) put £52.6 million (about US$70 million) into Nexeon, completing a £100 million round. Korea Development Bank and Honda Xcelerator Ventures also took part, so public equity anchored the round and drew in private capital.
The money funds a UK pilot facility, continued research and development, and expansion of Nexeon’s manufacturing technology unit.
The US has taken a different route. On 7 August 2026, the Office of Strategic Capital signed an agreement with Sila Nanotechnologies covering a conditional loan of up to US$1.4 billion. It would expand silicon-carbon anode production at Moses Lake, Washington, and build a cell plant.
Novonix has secured a conditional US Department of Energy loan of up to US$754.8 million. It is the clearest example in the research of an Australian-linked firm seeking capital overseas; no other relocation cases since 2024 were found.
Novonix has also secured US$103 million in certified Section 48C tax credits for its Chattanooga plant, a transferable asset that reduces dilution risk and shows how US support stacks on top of the conditional loan.
| Company | Country | Mechanism | Amount | Status |
|---|---|---|---|---|
| Nexeon | UK | Public equity (NWF) | **£52.6M** | Announced 31 August 2026 |
| Sila | US | Conditional loan | Up to **US$1.4B** | Agreement 7 August 2026 |
| Novonix | US | Conditional loan | Up to **US$754.8M** | Conditional |
| Sicona | Australia | Grant plus equity raise | **$45M** grant; **$55M** sought | Raise open |
The UK equity model versus the US loan model
Equity makes the government a shareholder and signals confidence to co-investors. Conditional debt offers scale but depends on the borrower meeting terms. The US figures are conditional offers, not completed disbursements, and further terms were not located.
Australia’s contrast is factual. Grants are substantial, but no proven mechanism has yet put large-scale public equity or concessional debt into a construction-stage battery materials plant.
For you, the implication is direct: competing jurisdictions are using public balance sheets to carry construction risk. Australian projects therefore compete for factory siting against better-capitalised offers.
Can the National Reconstruction Fund close the gap, and what is at stake for investors?
The National Reconstruction Fund (NRF) is the hope. It holds $15 billion, including a $1 billion sub-fund for value-add in resources, and invests through debt, equity and guarantees. Renewables and Low-Emission Technologies is a priority area, and a Net Zero Fund sub-fund features in the 2026 Investment Mandate.
With the BBI closed, Sicona expects the NRF to supply the next stage of funding.
The NRF should “pick up where the BBI has left off,” said Jordaan.
That is an expectation, not a demonstrated outcome. No NRF investment has been publicly detailed for battery anode or materials manufacturing, and no assessment of its governance or performance in battery investments was found.
The stakes are large. The Future Battery Industries CRC’s March 2023 report, still cited in 2026, says the industry could deliver $16.9 billion per annum and 61,400 jobs by 2030, but only if the middle segment of processing and materials manufacturing is captured onshore. Manufacturing employment has fallen an estimated 14% over 20 years, and 8,700 sector jobs were lost in the year to February 2026.
Open questions remain. No Australian critique of government-backed lending (credit risk, crowding out) and no discussion of Chinese anode competition was found.
For you, the NRF is a policy option to monitor, not a reason to assume onshore factories are assured. Signals to watch:
- The first NRF battery-materials commitment
- The size and form of capital (equity, debt or guarantee)
- Sicona closing its $55 million raise
- Further overseas loans to Australian-linked firms
Where onshore battery manufacturing goes from here
Grants and venture capital are not the binding constraint. Late-stage construction capital is, and overseas peers have received it.
The funding gap is not unique to batteries: Australia’s clean energy investment slump of roughly 20% in 2025 followed a record 2024, driven by bottlenecks rather than weak economics.
The $16.9 billion and 61,400-job forecast remains conditional, and whether the NRF delivers is still unanswered. The sensible test of Australia battery materials funding is what gets deployed into construction-stage plants, not what gets announced.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Forecasts cited are speculative and subject to change based on market developments and policy decisions.